
 Wire Cage Pallet Collar Market | 2026-2036
Wire Cage Pallet Collar Market Size, Share, and Industry Trends Forecast 2026-2036
Wire Cage Pallet Collar Market Analytics
The EU Green Deal is expanding requirements for circular packaging systems across member states. Rotom leverages its European manufacturing footprint to supply standardized collapsible cage systems to automotive and food processing clients. Schoeller Allibert anchors its position through deep expertise in polymer-based returnable packaging, while ORBIS Corporation dominates North American distribution with injection-molded and metal hybrid cage platforms.
Wire cage pallet collars are hinged, foldable perimeter frames—typically constructed from zinc-plated or powder-coated steel wire mesh with hardwood or composite bases—that mount onto standard pallets to create temporary four-sided containment for bulk goods during transport and storage. Steel variants lead volume due to load-bearing capacity in automotive and heavy manufacturing logistics, while aluminum and composite segments capture premium positioning in food-grade and pharmaceutical warehousing where weight reduction and corrosion resistance command higher unit margins. Application demand clusters in logistics and manufacturing, with retail adoption accelerating as omnichannel fulfillment centers adopt flexible, returnable container pools to reduce cardboard waste and improve dock-to-stock velocity.
FDA food-contact regulations in the United States, REACH chemical compliance in Europe, and China's GB standards for packaging materials collectively shape material selection, surface treatment protocols, and market access conditions for cross-border suppliers. The analysis indicates stakeholders must monitor evolving extended producer responsibility frameworks and assess material certification pathways before committing to capacity expansion or geographic diversification strategies.
Market Dynamics
Automotive OEMs in Germany are mandating closed-loop packaging pools to meet EU Green Deal circularity targets, forcing suppliers to convert single-use expendable systems to returnable wire cage platforms with full material traceability.
Growth Catalysts
- REACH compliance tightening:ECHA's expanded substance restrictions are compelling manufacturers to document zinc-plating chemistry and hardwood sourcing for cross-border EU shipments.
- China's eastern manufacturing corridor:Export-oriented factories in Jiangsu and Zhejiang provinces are standardizing collapsible returnable container systems to reduce per-unit logistics costs for automotive components.
- Lightweight aluminum adoption:Food-grade warehousing operators are specifying corrosion-resistant alloy variants to eliminate rust contamination risks in temperature-controlled pharmaceutical storage.
Market Restraints
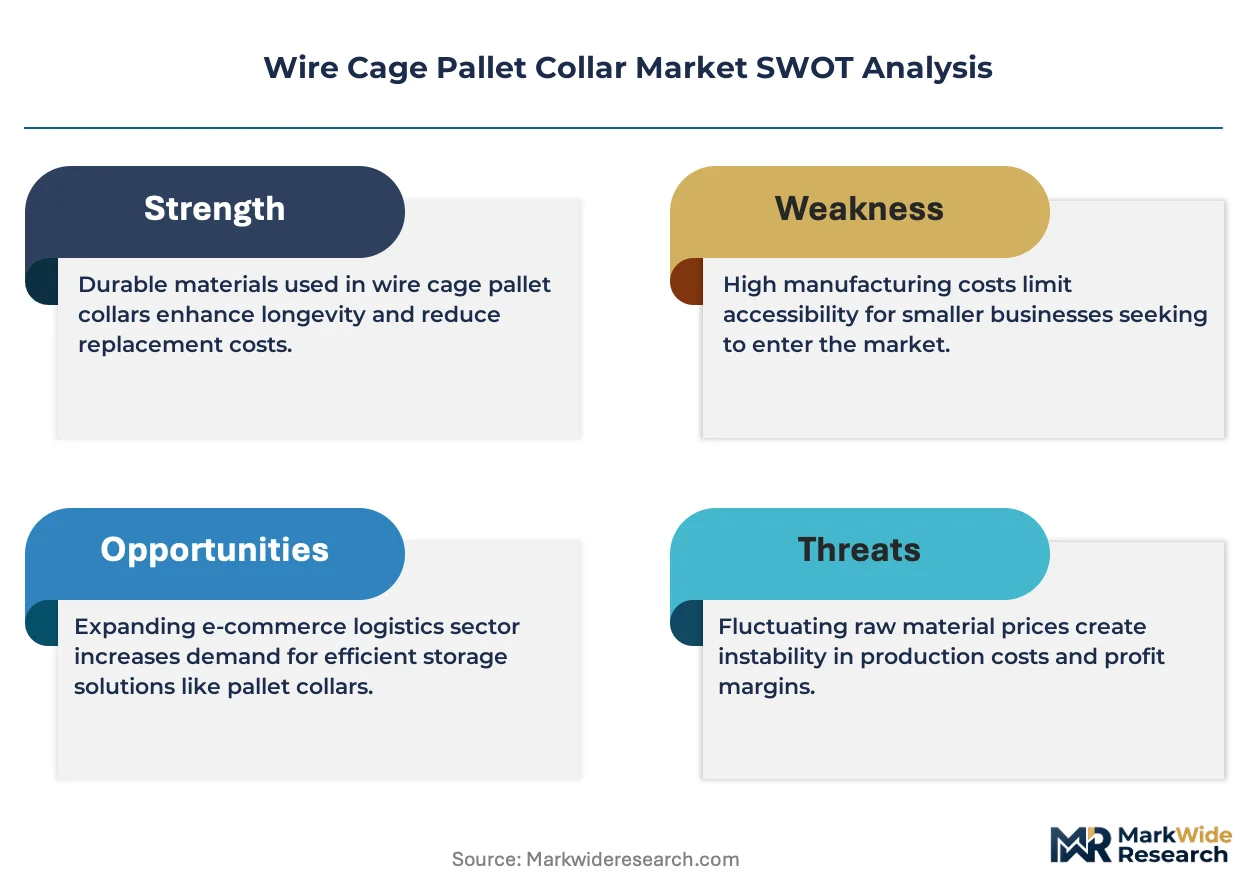
- Steel price volatility:Zinc-plated wire mesh input costs fluctuate with global hot-rolled coil indices, compressing margins for standardized product lines.
- Regional supplier concentration:European cage fabrication capacity clusters in Poland and Romania, creating lead time vulnerability for just-in-time automotive sequences.
- Plastic foldable bulk container substitution:Schoeller Allibert's polymer-based alternatives capture share in weight-sensitive pharmaceutical distribution where washdown protocols favor non-porous surfaces.
Strategic Opportunities
- India's automotive component belt:Tamil Nadu and Gujarat suppliers lack standardized returnable packaging infrastructure, creating first-mover advantage for collapsible cage system providers.
- RFID-embedded traceability convergence:Integration of passive tag technology with wire mesh structures enables real-time location tracking for high-value aerospace component pools.
- EU extended producer responsibility expansion:Member state packaging waste directives are mandating reuse quotas that favor durable metal containment over corrugated expendables.
Industry Challenges
- Welding automation skill scarcity:Precision MIG welding for food-grade stainless cage joints requires certified technicians that Eastern European fabricators struggle to recruit.
- Legacy WMS integration friction:Returnable container pool management software must interface with SAP and Oracle warehouse modules, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire Cage Pallet Collar Market |
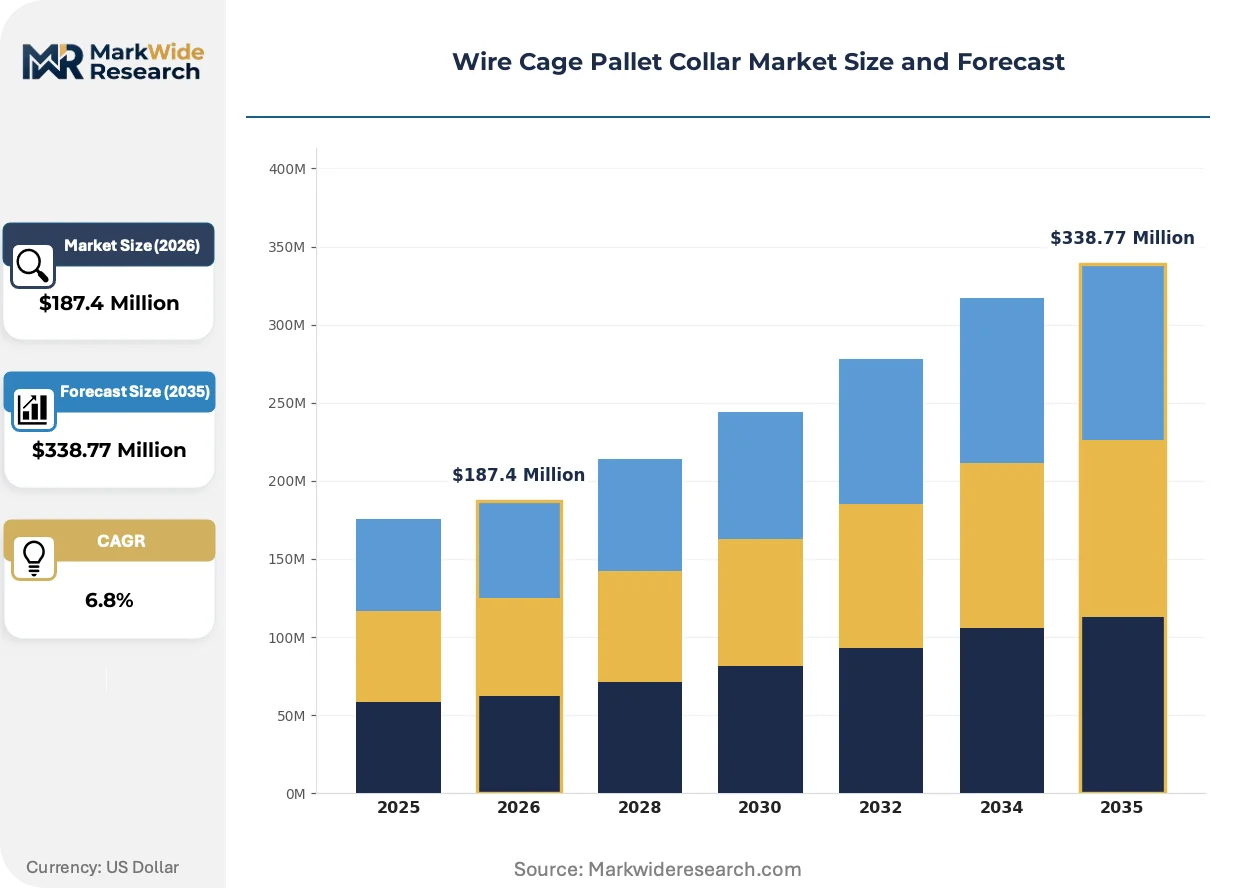
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
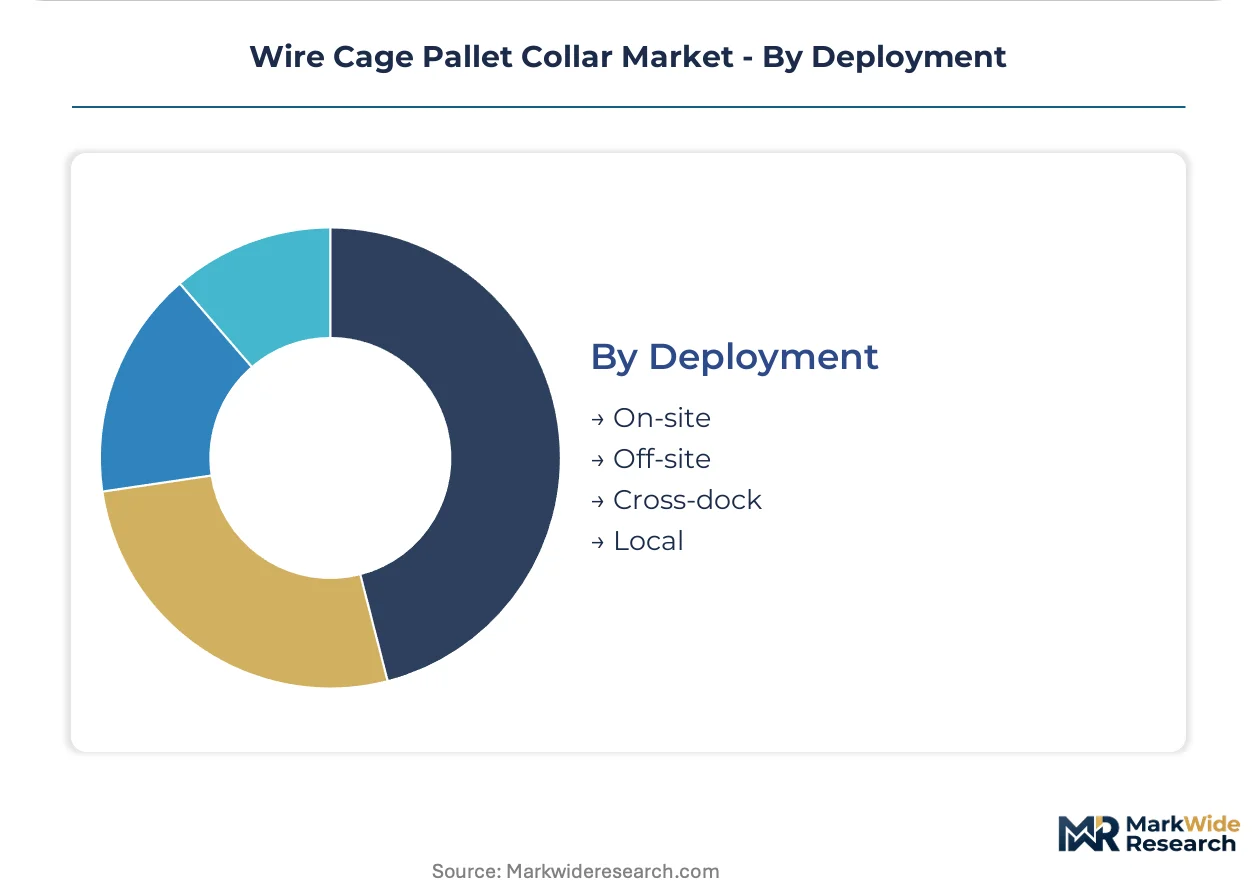
| Segmentation | Material: Steel, Aluminum, Plastic, Composite Application: Logistics, Manufacturing, Retail, Warehousing Size: Small, Medium, Large, Custom Deployment: On-site, Off-site, Cross-dock, Local |
| Companies Covered | Rotom, Loscam, Arcawa GmbH, Titan Load Restraints, Fletcher European Containers, Dajano, Trazmet, ORBIS Corporation, Schoeller Allibert, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire Cage Pallet Collar Market Evolving Landscape
Material science advances and digital traceability requirements are converging to redefine cage architecture, with hybrid construction methods and embedded sensor platforms displacing conventional welded wire formats.
Composite-reinforced wire mesh is modularizing pallet collar construction by replacing rigid welded frames with snap-fit polymer-steel hybrid joints. Automotive tier-one suppliers in Stuttgart and Wolfsburg are piloting these platforms for engine component sequencing. The technology is modularizing repair and reconfiguration workflows, allowing field replacement of damaged panels without full cage retirement.
REACH Article 33 disclosure obligations are forcing surface treatment suppliers to document chromium-VI-free passivation chemistries for zinc coatings. German automotive packaging engineers now specify certified plating shops for cage procurement. Heavy manufacturing logistics in the Ruhr Valley faces the steepest compliance burden, with OEMs auditing supplier coating documentation before contract renewal.
Asset pooling consortia are displacing direct equipment purchase for mid-size food processors. Third-party pool operators in the Netherlands and Belgium now finance cage fleets and charge per-use fees, transferring utilization risk from shippers to logistics providers. This model concentrates fastest in temperature-controlled dairy distribution where seasonal volume swings render captive fleet ownership uneconomical.
Wire Cage Pallet Collar Market Segmentation
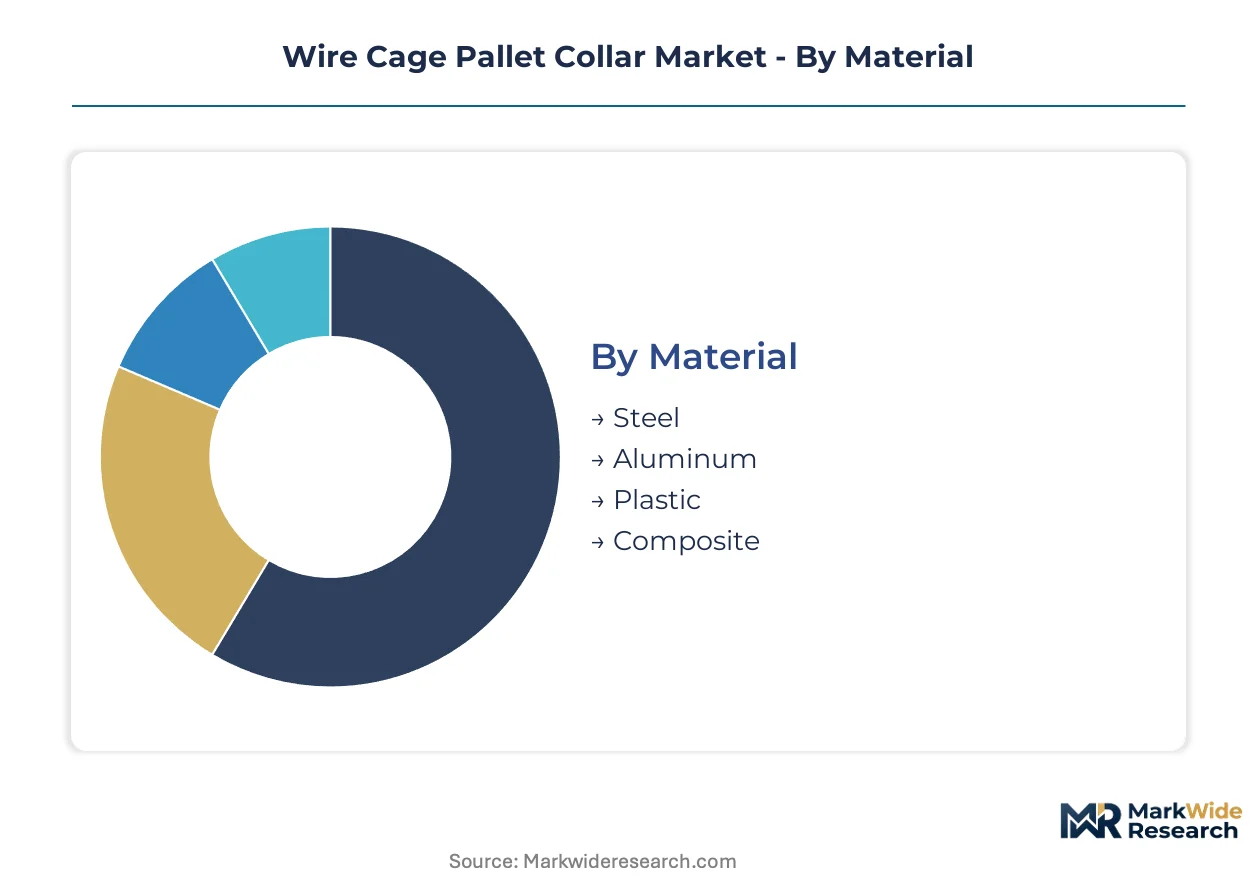
Wire cage pallet collar specifications diverge sharply across end-use requirements, with automotive sequencing demanding standardized steel platforms while pharmaceutical cold chains prioritize corrosion-resistant alloys. Material selection, dimensional flexibility, and deployment architecture collectively determine unit economics and regulatory compliance pathways for procurement teams.
Material:
Customization intensity spans from commodity-grade zinc-plated mesh to precision-engineered alloy variants certified for food-contact and aerospace applications.
- Steel:Zinc-plated or powder-coated wire mesh delivers maximum load-bearing capacity for automotive powertrain components and heavy machinery subassemblies. German OEMs in Stuttgart and Wolfsburg mandate steel platforms with full REACH Article 33 coating documentation for closed-loop packaging pools. REACH compliance auditing now extends to hardwood base sourcing and chromium-VI-free passivation chemistries.
- Aluminum:Corrosion-resistant alloys eliminate rust contamination risks in temperature-controlled pharmaceutical storage and dairy distribution networks. Food-grade warehousing operators in the Netherlands specify aluminum variants to meet EFSA hygiene protocols while reducing manual handling strain through weight reduction.
- Plastic:Injection-molded polymer frames capture share in washdown-intensive pharmaceutical distribution where non-porous surfaces simplify sterilization protocols.
- Composite:Snap-fit polymer-steel hybrid joints enable modular repair workflows and field panel replacement without full cage retirement.
Most installed capacity flows through steel. Expansion is steepest in aluminum.
Application:
Volume concentration correlates with supply chain maturity, from established automotive sequencing to emerging omnichannel retail fulfillment.
- Logistics:Third-party pool operators in Belgium and the Netherlands finance cage fleets and charge per-use fees, transferring utilization risk from shippers to logistics providers. Temperature-controlled dairy distribution exhibits fastest pooling adoption due to seasonal volume swings.
- Manufacturing:Automotive tier-one suppliers in Germany's Baden-Württemberg region pilot composite-reinforced platforms for engine component sequencing. EU Green Deal circularity targets mandate conversion from single-use expendables to returnable wire cage systems with full material traceability.
- Retail:Omnichannel fulfillment centers adopt flexible container pools to reduce cardboard waste and improve dock-to-stock velocity.
- Warehousing:Asset-light operators favor rental models over captive fleet ownership in high-turnover e-commerce distribution.
Manufacturing commands the largest installed base. Retail is climbing the fastest.
Size:
Standardization versus bespoke engineering determines procurement channel and margin structure across customer tiers.
- Small:Compact perimeter frames suit high-value aerospace components and precision electronics requiring dense storage configurations.
- Medium:Euro-pallet-compatible dimensions dominate cross-border automotive component flows within the European Union.
- Large:Extended base platforms accommodate bulky agricultural machinery parts and construction equipment subassemblies.
- Custom:Engineered-to-order collars with integrated RFID tags serve aerospace component pools requiring real-time location tracking.
Medium dimensions carry the heaviest throughput volume. Custom specifications are gaining share fastest.
Deployment:
Physical custody models range from shipper-controlled captive fleets to multi-user pooling infrastructure.
- On-site:Captive cage fleets remain anchored at single manufacturing campuses with dedicated return loops.
- Off-site:Remote warehousing arrangements require tracking integration with SAP and Oracle warehouse management modules.
- Cross-dock:High-velocity transfer points demand rapid collapse and redeployment capabilities to minimize dwell time.
- Local:Short-radius distribution networks in China's Jiangsu and Zhejiang provinces standardize collapsible systems to reduce per-unit logistics costs for export-oriented automotive suppliers.
On-site deployment retains the largest installed base. Cross-dock configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wire cage pallet collar fabrication originated in post-war European heavy manufacturing zones, where German automotive clusters pioneered standardized returnable container systems for component sequencing. Industrial packaging demand subsequently diffused through export manufacturing corridors in Asia and North American automotive belts.
Germany
Automotive OEMs in Stuttgart and Wolfsburg mandate closed-loop packaging pools to meet EU Green Deal circularity targets. REACH Article 33 disclosure obligations now require full documentation of zinc-plating chemistry and hardwood base sourcing for cross-border shipments. The Baden-Württemberg automotive belt concentrates tier-one supplier demand for certified steel cage systems.
China
Export-oriented factories in Jiangsu and Zhejiang provinces standardize collapsible returnable containers to reduce per-unit logistics costs for automotive component exports. GB standards for packaging materials govern surface treatment protocols and material traceability for cross-border suppliers. The Yangtze River Delta manufacturing corridor anchors domestic production capacity for regional automotive supply chains.
United States
FDA food-contact regulations shape material selection for pharmaceutical and dairy distribution networks requiring corrosion-resistant containment. Automotive assembly plants in Michigan and Ohio deploy steel cage systems for powertrain component sequencing. Third-party pool operators in the Midwest now finance cage fleets under per-use pricing models.
Netherlands
EFSA hygiene protocols drive food-grade warehousing operators toward aluminum variants that eliminate rust contamination risks in temperature-controlled storage. Asset pooling consortia in Belgium and the Netherlands finance cage fleets for dairy processors facing seasonal volume swings. The Rotterdam-Antwerp logistics corridor concentrates third-party pool management infrastructure.
India
Tamil Nadu and Gujarat automotive component suppliers lack standardized returnable packaging infrastructure, creating first-mover openings for collapsible cage system providers. BIS certification requirements for industrial packaging materials are tightening import compliance pathways. The Chennai automotive belt exhibits fastest adoption velocity among emerging manufacturing clusters.
Wire Cage Pallet Collar Market Competitive Landscape
Capital-heavy European fabricators compete with asset-light Asian assemblers across distinct capability tiers. The vendor base fragments across three strategic archetypes: integrated steel processors controlling wire drawing and zinc plating, modular system designers outsourcing fabrication to contract foundries, and third-party pool operators managing asset-light fleet logistics. Dominant competitive moves include backward integration into surface treatment shops and geographic expansion through distributor partnerships in underpenetrated automotive corridors.
Among European-anchored specialists, Rotom leverages its manufacturing footprint to supply standardized collapsible cage systems, while Schoeller Allibert occupies a position exemplifying polymer-based returnable packaging expertise. ORBIS Corporation represents the North American injection-molded and metal hybrid platform tier. These three anchors illustrate how regional manufacturing heritage shapes competitive positioning across material technology vectors.
| Leading Market Players |
|---|
| Rotom |
| Loscam |
| Arcawa GmbH |
| Titan Load Restraints |
| Fletcher European Containers |
| Dajano |
| Trazmet |
| ORBIS Corporation |
| Schoeller Allibert |
| Others |
Value Network & Pricing Analysis
Backward integration into zinc-plating and wire-drawing operations anchors both cost position and pricing power for European fabricators serving German automotive OEMs, while Asian assemblers rely on outsourced surface treatment shops that compress margins during hot-rolled coil price spikes. Captive coating capacity insulates integrated producers from REACH Article 33 compliance auditing costs that now factor into contract renewals.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between German OEMs and certified cage fabricators, with price differentiation driven by REACH documentation tier and volume scale. Premium-mid-economy pricing differentiation separates food-grade aluminum variants from commodity zinc-plated steel, while cost compression in standard steel tiers intensifies as Polish and Romanian suppliers compete for automotive sequencing contracts. Tier-one automotive procurement teams exhibit lowest price sensitivity due to traceability mandates, whereas mid-size food processors prioritize per-use rental economics over capital purchase.
Supply Chain Analysis
Hot-rolled coil supply rests on integrated steel mills in Germany, Poland, and China, with zinc ingot sourcing concentrated among European smelters and Chinese refiners. Hardwood base materials draw from certified forestry operations in Romania and Baltic states, while polymer-steel hybrid joints hinge on injection-molding capacity in China's Yangtze River Delta. Single-source vulnerability concentrates in REACH-compliant plating chemistry suppliers, with distribution running through Rotterdam-Antwerp logistics corridors for pooled fleet redeployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in wire cage pallet collars stems from aluminum adoption in pharmaceutical cold chains, where corrosion-resistant alloys command premium positioning against commodity steel alternatives.
For Market Incumbents: Anchor market position through captive zinc-plating capacity investments that satisfy REACH Article 33 disclosure obligations before contract renewal cycles. Defend against polymer-based substitution threats from Schoeller Allibert by certifying stainless steel variants for washdown-intensive pharmaceutical distribution. Prioritize RFID-embedded traceability R&D to capture aerospace component pool contracts requiring real-time location tracking. For New Entrants and Emerging Players: E-commerce platform direct sourcing routes offer lowest-friction entry for standardized steel cage sales to mid-size food processors lacking procurement sophistication. Target India's Tamil Nadu and Gujarat automotive corridors where standardized returnable packaging infrastructure remains underdeveloped. Pursue asset-light pooling partnerships with third-party logistics operators rather than captive fleet ownership models. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance auditing costs and welding automation skill scarcity strand sub-scale European fabricators. Frame long-term viability around aluminum segment growth and composite-hybrid technology transitions. Monitor ECHA substance restriction announcements as inflection indicators for coating chemistry replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surface Treatment | Captive zinc-plating capacity satisfies REACH Article 33 documentation demands from German OEM procurement teams. |
| RFID-Embedded Traceability Development | Passive tag integration with wire mesh structures enables real-time tracking for high-value aerospace component pools. |
| Aluminum Alloy Product Line Expansion | Corrosion-resistant variants capture pharmaceutical cold chain demand driven by EFSA hygiene protocol compliance. |
| Asset Pooling Consortium Partnerships | Per-use rental models transfer utilization risk from dairy processors to third-party logistics providers in Belgium and Netherlands. |
| India Manufacturing Footprint Establishment | First-mover positioning in Tamil Nadu and Gujarat automotive corridors addresses infrastructure gaps among component suppliers. |
Research Methodology
Direct dialogue with automotive packaging engineers, Tier 1 supplier procurement leads, third-party pool operators, and zinc-plating shop technical directors grounded qualitative insights. Secondary validation drew from ECHA substance restriction databases, EU packaging waste directive filings, customs trade data for wire mesh imports, and automotive OEM supplier sustainability reports. Bottom-up and top-down triangulation reconciled fabrication capacity estimates with end-use demand segmentation.
Bottom-up volume modeling tracked material-grade shipments by application and deployment architecture across the analysis window, while top-down validation tested aggregate figures against automotive production data and logistics sector capital expenditure patterns. Segmentation dimensions included material technology, end-use industry, deployment model, and geographic manufacturing cluster. CAGRs were derived from regression analysis of historical shipment trends and elasticity-adjusted demand projections, with aluminum adoption curves and REACH compliance cost pass-through serving as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for composite-reinforced polymer-steel hybrid joints would alter the outlook if automotive OEMs accelerate modular platform standardization. Forecasts reflect assumptions regarding sustained EU Green Deal circularity enforcement and stable hot-rolled coil pricing. Material deviation in ECHA substance restriction timelines or China's GB standards enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Pallet Collar Market
Pallets Packaging
Pallet Pooling Market
Pallets Packaging
Pallet Tines Market
Pallets Packaging
Spill Pallets Market
Pallets Packaging
Global Wood Pallet Market
Pallets Packaging
Stringer Pallets Market
Pallets Packaging
France Pallets Market
Pallets Packaging
Pallets Market
Pallets Packaging
Corrugated Pallet Containers Market
Pallets Packaging
Disposable Plastic Pallet Market
Pallets Packaging
Pallet Labelling System Market
Pallets Packaging
Composite Pallet Market
Pallets Packaging
Asia-Pacific Lumber Pallet Market
Pallets Packaging
Paper Pallet Market
Pallets Packaging
Presswood Pallets Market
Pallets Packaging
United States Pallet Market