
 Global Crates and Pallets Packaging Market | 2026-2036
Global Crates and Pallets Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Crates and Pallets Packaging Market Intelligence
The modularization of crate and pallet designs is repositioning buyer preference toward systems that optimize reverse logistics and storage density. These nestable and collapsible formats reduce transportation costs for empty units. Brambles Ltd (CHEP) leverages its extensive pooling network to capitalize on this efficiency. Schoeller Allibert specializes in innovative, returnable plastic packaging solutions that meet these modular design criteria, differentiating itself in the market.
Crates and pallets packaging refers to rigid, flat transport structures and containers used to unitize goods for efficient handling by forklifts or pallet jacks. Wooden pallets must often comply with ISPM 15 standards requiring heat treatment to prevent pest transmission. While the wooden crates segment remains mature and volume-driven, plastic pallets represent the fastest-growing product type, favored by logistics providers for durability and reusability. Agricultural producers also increasingly use plastic crates for hygiene and product protection.
Regulatory frameworks significantly influence material choice and design. The EU's Packaging and Packaging Waste Regulation promotes reusable systems, while in the United States, the FDA sets stringent requirements for food-contact surfaces on plastic pallets. Compliance with international standards, such as ISO 8611 for pallet testing, also dictates market access and product specifications. Navigating the trade-offs between initial cost, lifecycle durability, and evolving sustainability mandates is the central challenge for procurement managers.
Market Dynamics
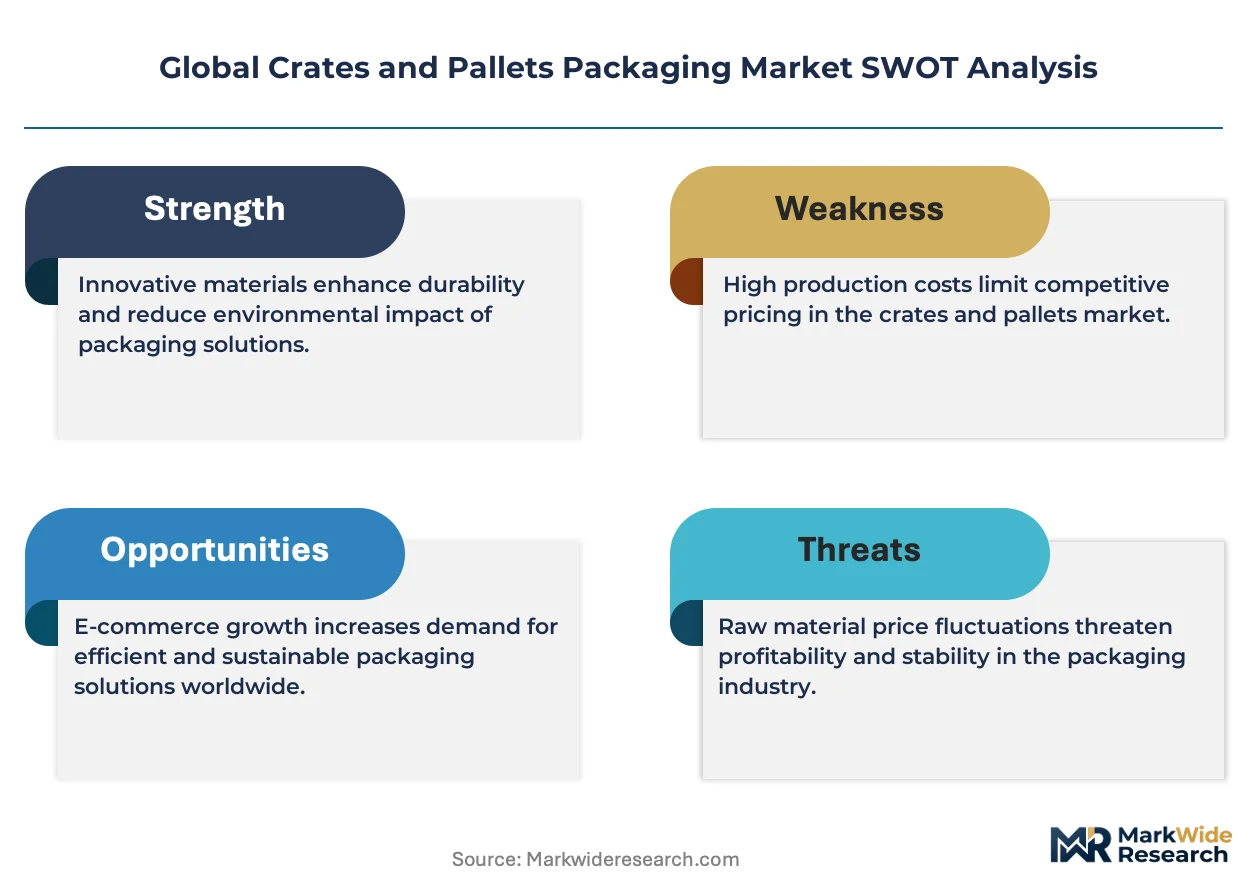
The market's central dynamic revolves around the shift from traditional wood pallets to reusable plastic systems, driven by supply chain efficiency demands and circular economy frameworks. Regulations like the EU Green Deal are accelerating this transition toward sustainable, long-life assets.
Growth Catalysts
- Agricultural Sector Demand:Hygiene requirements for fresh produce favor non-porous plastic crates over wood, reducing spoilage and contamination risks during transport from farm to retailer.
- EU Circular Economy Frameworks:Policies promoting waste reduction and reusability create a powerful incentive for adopting returnable plastic packaging systems, boosting demand for nestable and collapsible designs.
- Chinese Manufacturing Output:China's extensive manufacturing and export activities generate immense, consistent demand for pallets and crates to unitize goods for domestic and international logistics.
Market Restraints
- High Initial Capex:The upfront investment for durable plastic pallets is significantly higher than for wooden alternatives, creating a cost barrier for smaller enterprises or those with low-velocity supply chains.
- Polymer Price Volatility:Plastic pallet production costs are directly tied to fluctuating petrochemical feedstock prices, which can create margin pressure and pricing instability for manufacturers.
- Fragmented Reverse Logistics:Outside of established pooling systems, the lack of widespread, interoperable infrastructure for returns limits the economic viability of reusable plastic systems in many regions.
Strategic Opportunities
- IoT Integration:Embedding sensors like RFID or BLE tags into pallets enables real-time asset tracking, temperature monitoring, and supply chain data analytics for high-value goods.
- Indian E-commerce Expansion:Rapid growth in India's e-commerce and organized retail sectors presents an underpenetrated market for standardized, durable packaging to support modern logistics hubs.
- Recycled Content Innovation:Developing high-performance pallets from post-consumer recycled plastics helps meet sustainability mandates and can lower material costs, appealing to environmentally conscious buyers.
Industry Challenges
- Navigating Divergent Standards:Manufacturers must manage a complex web of regulations, including ISPM 15 for wood, FDA food-contact rules in the US, and EU packaging waste mandates, increasing compliance costs.
- Reverse Logistics Complexity:The operational difficulty and cost of collecting, cleaning, and repositioning empty reusable crates represents a significant hurdle to scaling closed-loop systems efficiently.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Crates and Pallets Packaging Market |
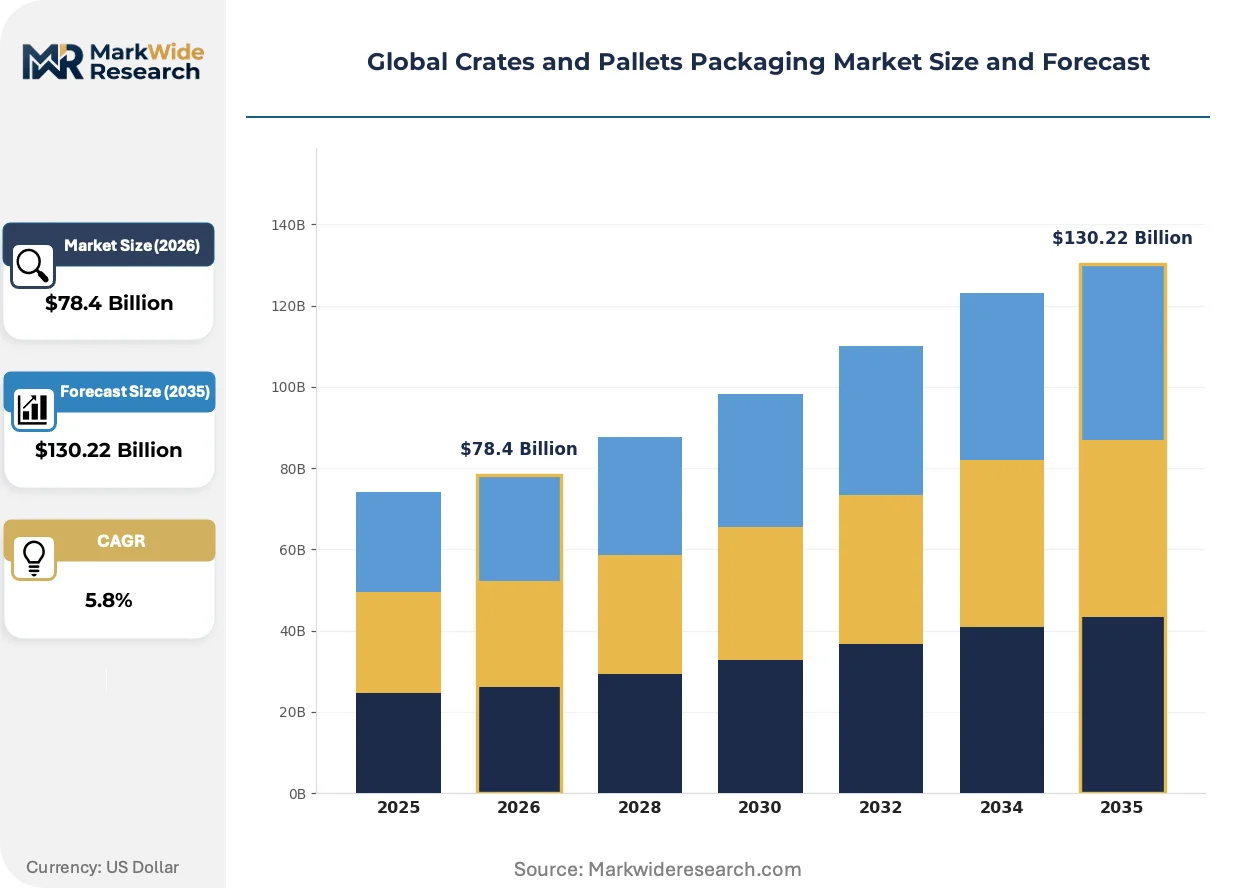
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $130.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wooden Crates, Plastic Pallets, Metal Pallets, Corrugated Crates, Composite Pallets Material: Recycled Plastic, Steel, Aluminum, Hardwood, Plywood Distribution Channel: Direct Sales, Distributors, Online Marketplaces, Retail Stores, Wholesale Suppliers End User: Manufacturers, Warehousing, Logistics Providers, Agricultural Producers, Construction Firms |
| Companies Covered | Rehrig Pacific Company, Myers Industries, IFCO Systems, Georg Utz Holding AG, DS Smith Plc, Brambles Ltd (CHEP), ORBIS Corporation, Craemer Group, Schoeller Allibert, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Crates and Pallets Packaging Market Strategic Shifts & Innovations
A fundamental shift from transactional purchasing to total cost of ownership analysis is redefining product value. This evolution prioritizes lifecycle performance, driving innovations in material science, modular design, and data integration to optimize long-term asset utilization and supply chain efficiency.
Collapsible and nestable designs reduce the storage footprint and return-trip transportation costs of empty units. Logistics providers and large retailers are adopting these formats to improve reverse logistics efficiency. This technology is modularizing the asset pool, allowing for flexible configurations that increase storage density and optimize vehicle capacity for empty returns.
The EU's Packaging and Packaging Waste Regulation sets aggressive targets for reusable packaging and recycled content within member states. This forces a systemic shift away from single-use wooden pallets toward investment in durable, returnable plastic packaging pools. The food and beverage sector, in particular, is re-evaluating its packaging strategy to comply with these new circularity mandates.
Asset pooling and rental models are displacing direct ownership for many end-users, especially in the fast-moving consumer goods sector. This shift allows companies to convert capital expenditures into operational expenses while outsourcing the management of pallet inventory, cleaning, and repair. This trend is most pronounced in Europe and North America, where established pooling networks offer extensive coverage.
Global Crates and Pallets Packaging Market Segmentation
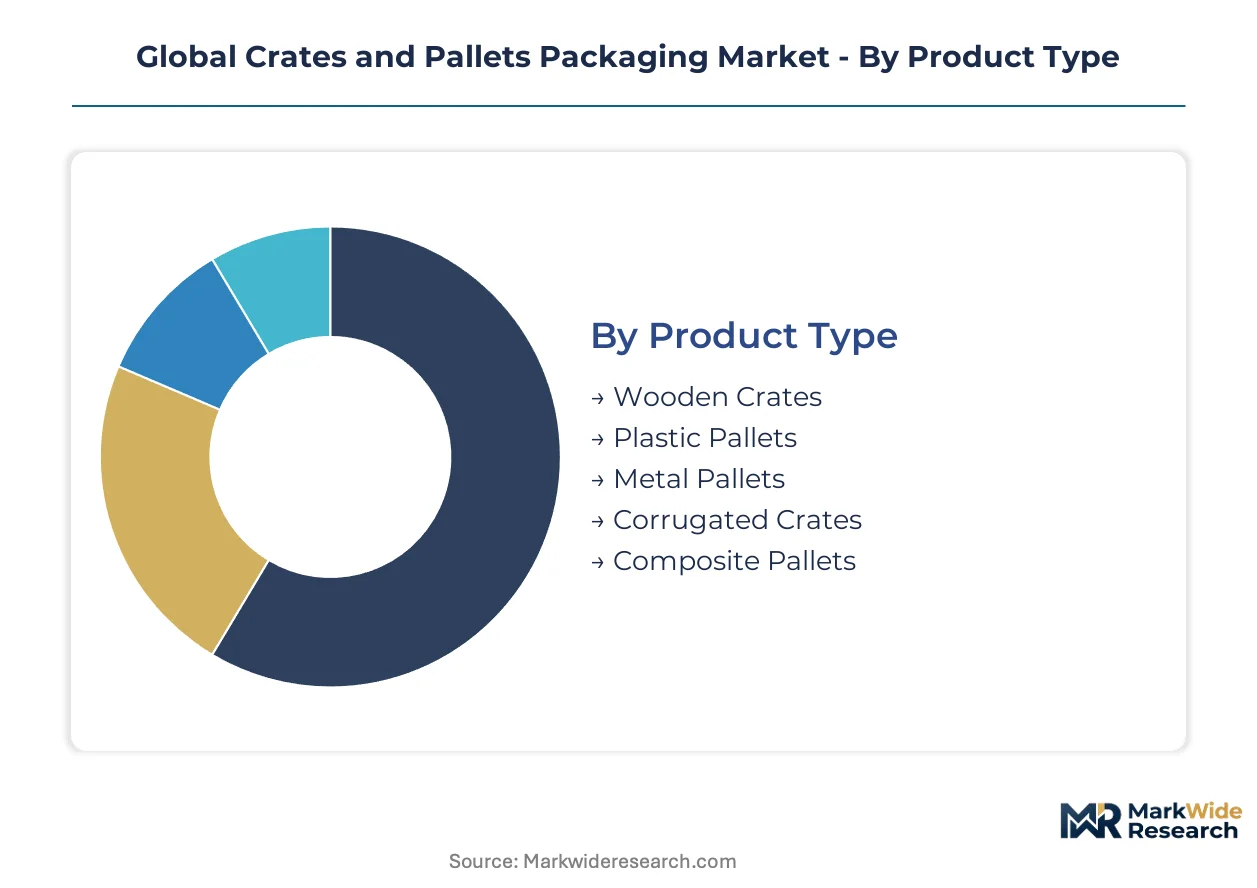
The crates and pallets packaging market categorizes products and applications to address distinct operational requirements and material preferences. Understanding these segments helps procurement managers align their purchasing strategies with specific supply chain demands and sustainability objectives. Each segment reflects unique performance attributes and cost considerations.
Product Type:
Supply concentration for crates and pallets packaging centers on specific product types that meet diverse industrial demands.
- Plastic Pallets:These durable, non-porous units are engineered from high-density polyethylene or polypropylene for extended lifecycle use. Logistics providers in Europe favor plastic pallets for their reusability and compliance with stringent hygiene regulations, reducing contamination risks in closed-loop systems.
- Wooden Crates:Constructed from various timber types, these rigid containers provide robust protection and are often custom-built for specific cargo dimensions. China's extensive manufacturing and export activities generate substantial demand for wooden crates, particularly for heavy industrial goods.
- Metal Pallets:Fabricated from steel or aluminum, these pallets offer extreme durability and high load-bearing capacity for specialized industrial applications.
- Corrugated Crates:Lightweight and cost-effective, these paperboard containers are used for shipping lighter goods and often for single-use applications.
- Composite Pallets:Blending wood fibers with plastics, these pallets offer a balance of durability and cost-effectiveness, suitable for various general-purpose uses.
Wooden Crates absorb the bulk of installed capacity; Plastic Pallets are expanding most quickly.
Material:
Application needs dictate material choices across the crates and pallets packaging market.
- Recycled Plastic:Composed of post-consumer or post-industrial plastic waste, these materials contribute to circular economy goals and reduce reliance on virgin polymers. European regulatory frameworks, including the EU Green Deal, specifically incentivize the use of recycled content in packaging solutions.
- Hardwood:Derived from dense timber species such as oak or maple, hardwood offers superior strength and longevity for heavy-duty pallet construction. Manufacturers globally rely on hardwood for its structural integrity and widespread availability in traditional supply chains.
- Steel:This robust metal provides exceptional strength and resistance to damage, primarily used for specialized industrial pallets and heavy-duty applications.
- Aluminum:Lightweight and corrosion-resistant, aluminum is preferred for specialized pallets where weight reduction and hygiene are critical, such as in aerospace or food processing.
- Plywood:Engineered wood panels offer a smooth surface and consistent strength, often utilized in custom crate fabrication and lighter-duty pallet designs.
Hardwood materials continue to dominate volume; Recycled Plastic is gaining share fastest.
Distribution Channel:
Customer preferences and transaction volumes shape distribution channel dynamics for packaging solutions.
- Direct Sales:Manufacturers and large-scale suppliers engage directly with major corporate clients and pooling service providers. This channel facilitates large volume orders, custom solutions, and long-term contractual agreements for returnable packaging assets.
- Distributors:These intermediaries stock a wide range of packaging products and serve smaller businesses or those with fluctuating demand. Distributors provide localized inventory and logistics support, crucial for regional supply chain needs.
- Online Marketplaces:Digital platforms connect buyers and sellers, offering convenience and broader product selection for standard packaging solutions.
- Retail Stores:Physical retail outlets cater to small businesses or individual consumers requiring immediate, smaller quantities of crates or pallets.
- Wholesale Suppliers:These providers offer bulk quantities of packaging materials to businesses, often at discounted rates for large-volume purchases.
Direct Sales channels manage the largest transactions; Online Marketplaces demonstrate the steepest expansion trajectory.
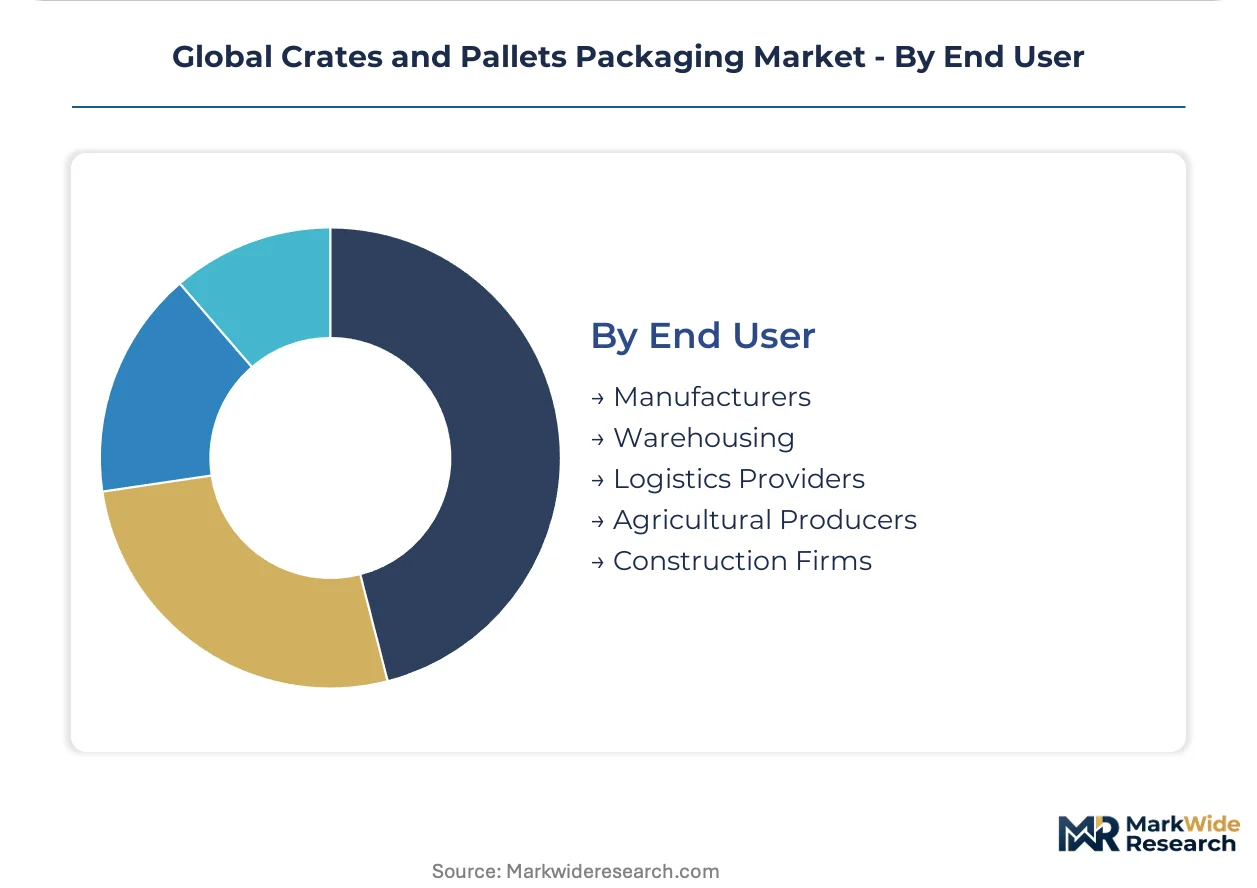
End User:
Demand volume and operational requirements define the end-user segments within crates and pallets packaging.
- Logistics Providers:These entities manage the movement and storage of goods across supply chains, requiring efficient and durable unitization solutions. Pooling networks address the high-volume, asset-intensive needs of logistics operations.
- Agricultural Producers:Farms and food processing companies utilize crates and pallets for harvesting, storage, and transport of fresh produce. Hygiene requirements drive agricultural producers in Europe to adopt non-porous plastic crates, minimizing spoilage and contamination.
- Manufacturers:Industrial and consumer goods manufacturers use packaging to protect products during internal handling and external shipment.
- Warehousing:Storage facilities rely on standardized pallets for efficient stacking, inventory management, and material handling within their operations.
- Construction Firms:Building and infrastructure projects use robust crates and pallets for transporting heavy materials and equipment to job sites.
Manufacturers represent the foundational demand base; Agricultural Producers show significant growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global crates and pallets packaging market exhibits a clear divide between manufacturing-heavy nations driving demand and regions prioritizing circular economy models. China's vast production output generates substantial volume requirements for unitization solutions. Meanwhile, European countries increasingly focus on reusable systems to meet ambitious sustainability targets.
China
China's extensive manufacturing and export activities create consistent demand for pallets and crates to unitize goods for domestic and international logistics. The country's GB standards influence packaging specifications, particularly for export-bound products requiring specific material and structural integrity. Industrial clusters in the Yangtze River Delta region, including Shanghai and Suzhou, continually require robust packaging for diverse manufactured goods.
United States
Demand for efficient transport solutions in the United States stems from its large consumer market and extensive logistics networks. The FDA sets stringent requirements for food-contact surfaces on plastic pallets, particularly for agricultural and food processing sectors. Major logistics hubs, such as those in Chicago and Atlanta, rely heavily on standardized pallet systems for efficient material flow.
Germany
Germany's advanced manufacturing sector and strong focus on sustainability drive demand for durable, reusable packaging. The EU Green Deal promotes circular economy models, incentivizing the adoption of returnable plastic systems across various industries. Automotive and machinery manufacturing centers in Bavaria and North Rhine-Westphalia actively integrate these packaging solutions into their supply chains.
India
India's rapidly expanding e-commerce and organized retail sectors generate new demand for standardized and durable packaging solutions. The government's PLI scheme supports domestic manufacturing, indirectly increasing the need for efficient logistics packaging. Major urban centers like Mumbai and Delhi are developing modern logistics hubs that require high-quality crates and pallets.
Global Crates and Pallets Packaging Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the crates and pallets packaging market. The market exhibits a tiered structure, with global pooling operators alongside regional manufacturers and custom solution providers. Key strategic archetypes include asset pooling specialists, material-specific innovators, and broad-line packaging suppliers. Companies frequently pursue strategic partnerships to expand geographic reach and invest in capacity expansion for high-demand product types.
At the scale-driven end, Brambles Ltd (CHEP) exemplifies the global pooling network model, optimizing asset utilization and reverse logistics for large enterprises across multiple continents. Schoeller Allibert, a Netherlands-based company, occupies a position as an innovator in returnable plastic packaging solutions, catering to hygiene-sensitive sectors with its modular and nestable designs. Rehrig Pacific Company, a US-based manufacturer, anchors a significant segment of durable plastic products, including pallets and crates, for various industrial and agricultural applications, emphasizing long-term performance.
| Leading Market Players |
|---|
| Rehrig Pacific Company |
| Myers Industries |
| IFCO Systems |
| Georg Utz Holding AG |
| DS Smith Plc |
| Brambles Ltd (CHEP) |
| ORBIS Corporation |
| Craemer Group |
| Schoeller Allibert |
| Others |
Cost & Logistics Intelligence
EU's Packaging and Packaging Waste Regulation mandates for reusable systems are reshaping procurement preferences, compelling suppliers to invest in durable, higher-cost solutions that influence market pricing. This demand-side pressure requires supply chains to adapt with greater emphasis on circularity and material innovation, affecting overall cost structures.
Pricing Analysis
Polymer price volatility creates significant cost compression for plastic pallet manufacturers, impacting their ability to offer stable pricing. The dominant pricing model remains per-unit transactional, though long-term contracts are common for large-volume customers. Price differentiation stems from quality grade, such as FDA-compliant plastic pallets, and volume scale. Smaller enterprises exhibit higher price sensitivity compared to large logistics providers who prioritize total cost of ownership.
Supply Chain Analysis
The operational complexity of collecting, cleaning, and repositioning empty reusable crates represents a significant hurdle for scaling closed-loop systems efficiently. Geographic supply concentrates in China for wooden crates and increasingly in Europe for advanced plastic pallet manufacturing. The supply chain draws from key raw materials like HDPE, polypropylene, and timber. A structural risk is commodity price volatility for polymers. Distribution runs through direct sales to large corporate clients and pooling service providers, with distributors serving smaller businesses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Crates and Pallets Packaging Market is increasingly defined by compliance costs, where the EU's Packaging and Packaging Waste Regulation creates a formidable barrier-to-entry for non-compliant solutions.
For Market Incumbents:
To counter the increasing polymer price volatility and the shift towards recycled content, established players must deepen R&D into advanced material science for plastic pallets. Expanding asset pooling networks, exemplified by Brambles Ltd (CHEP), will reinforce market position by offering scalable, circular solutions. Investing in ISO 8611 and FDA certifications secures access to regulated markets and high-value applications, protecting against emerging substitute technologies.
For New Entrants and Emerging Players:
The EU's Packaging and Packaging Waste Regulation in Europe opens a window for new entrants specializing in sustainable, returnable plastic packaging solutions. Target underpenetrated segments like Indian e-commerce and hygiene-sensitive agricultural producers with innovative, modular plastic crates. A go-to-market angle integrating IoT sensors for real-time asset tracking offers a differentiated value proposition, appealing to logistics providers seeking enhanced supply chain visibility.
For Investors and Strategic Acquirers:
The window for entry favors strategic investors with a long-term outlook on circular economy models and supply chain modernization. Acquisition targets should include innovators in modular plastic designs and established asset pooling specialists with robust reverse logistics infrastructure. A key signal to watch for inflection is the widespread adoption of IoT-enabled pallets, indicating a shift towards data-driven asset management and higher valuation potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Recycled Plastic R&D | Reduces reliance on virgin polymers, aligning with EU Green Deal mandates for sustainable material use. |
| Expand Asset Pooling Networks | Improves reverse logistics efficiency for large enterprises, converting capital expenditures into operational expenses. |
| Develop IoT-Integrated Pallets | Enables real-time asset tracking and data analytics, enhancing supply chain visibility for high-value goods. |
| Target Emerging E-commerce Logistics | Capitalizes on rapid growth in markets like India, providing standardized packaging for modern distribution hubs. |
| Obtain FDA/ISO Certifications | Ensures compliance for food-contact surfaces and international transport, facilitating market access and trust. |
Research Approach
Independent corroboration across industry reports, regulatory frameworks, and company financial filings underwrites the qualitative findings and quantitative projections within this study. Primary interviews with logistics managers, procurement specialists, packaging engineers, and agricultural producers provided critical market insights. Secondary data sources included ISO standards documents, EU regulatory reports, national trade statistics from China and the United States, and company annual reports, triangulating bottom-up and top-down perspectives.
Rate-of-change decomposition models market evolution by segmenting growth across product types, materials, distribution channels, and end-user applications. This analytical framework projects compound annual growth rates over the projection horizon, considering historical trends, demand drivers, and market restraints. Key forecast inputs include polymer prices, global trade volumes, and regional manufacturing output, alongside regulatory changes impacting material choice and reusability.
The model assumes a particular technology adoption path; alternative pathways for advanced recycled plastic composites would alter the outlook. Forecasts reflect assumptions regarding geopolitical trade policies and raw material supply stability. Practitioners should monitor regulatory shifts and material science breakthroughs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Italy Pallets Market
Pallets Packaging
Thermal Pallet Covers Market
Pallets Packaging
Single Use Pallet Market
Pallets Packaging
Presswood Pallets Market
Pallets Packaging
Pallet Collar Market
Pallets Packaging
Stretch Hood Pallet Wrapping Market
Pallets Packaging
Pallet Pooling Market
Pallets Packaging
United States Pallet Market
Pallets Packaging
Pallet Shippers Market
Pallets Packaging
Asia-Pacific Lumber Pallet Market
Pallets Packaging
Foldable Pallet Container Market
Pallets Packaging
Composite Pallet Market
Pallets Packaging
Europe Palletizer Market
Pallets Packaging
Palletizer Market
Pallets Packaging
Paper Pallet Market
Pallets Packaging
Pallet Labeler Market