
 Wooden Pallet Collars Market | 2026-2036
Wooden Pallet Collars Market Size, Share, and Industry Trends Forecast 2026-2036
Wooden Pallet Collars Market Analytics
Food & Beverage cold-chain logistics is hardening as the dominant demand vertical for wooden pallet collars, displacing traditional retail bulk display applications. Kronus leverages its Baltic timber sourcing and ISPM-15 heat-treatment infrastructure to anchor supply for Northern European pharmaceutical and dairy exporters. CABKA Group competes through its closed-loop pooling model, while Nefab differentiates via engineered corner-collar designs for high-value electronics freight.
Wooden pallet collars are hinged, foldable timber frames, typically 1200 mm by 800 mm, that mount atop standard pallets to create modular, stackable containment walls for irregular or fragile cargo. Pine dominates material selection due to favorable strength-to-weight ratios and established kiln-drying workflows, though birch grades command premium positioning in moisture-sensitive pharmaceutical lanes. Standard collars retain volume leadership across manufacturing end users, while nesting collars are gaining fastest in third-party logistics where trailer cube utilization directly governs fleet economics.
EU Green Deal timber traceability requirements and REACH chemical treatment disclosures are tightening market access for uncertified suppliers, while FDA sanitary wood packaging rules shape export eligibility for North American food-contact applications. Germany's national packaging ordinance, enforced by the Länder waste authorities, mandates recycling quotas that favor durable, multi-trip collar systems over single-use alternatives. Stakeholders must monitor evolving phytosanitary border protocols and decide whether to captive-source heat-treatment capacity or rely on third-party ISPM-15 certification networks.
Market Dynamics
EU Green Deal timber traceability mandates are restructuring supplier qualification hierarchies, forcing pooling operators to consolidate heat-treatment capacity around certified Baltic sawmills while pharmaceutical cold-chain shippers demand ISPM-15 documentation at load tender.
Growth Catalysts
- EU Green Deal packaging mandates:REACH chemical disclosure rules and timber provenance requirements redirect procurement toward certified sustainable sources, locking in multi-year supply contracts for compliant Baltic producers.
- Food & Beverage cold-chain hardening:Dairy and pharmaceutical exporters in Germany's Rhine-Ruhr corridor are expanding collar pooling networks to maintain temperature integrity through modular stacking systems.
- Nesting collar adoption:Third-party logistics operators are converting trailer fleets to collapsible nesting designs, compressing empty return haulage costs and improving cube utilization rates.
Market Restraints
- Pine input cost volatility:Baltic softwood prices fluctuate with Nordic pulp mill demand and Russian timber export restrictions, squeezing margin predictability for heat-treatment operators.
- Supply concentration in Baltic states:Sawmill capacity clusters in Latvia and Estonia create geographic vulnerability to port congestion and phytosanitary border delays.
- Plastic pallet substitution:Injection-molded HDPE collars are penetrating pharmaceutical lanes where moisture resistance outweighs timber's cost advantage.
Strategic Opportunities
- Underpenetrated Polish manufacturing:Automotive component suppliers in Silesia lack dense pooling infrastructure, presenting white space for closed-loop operators to establish depot networks.
- Engineered corner-collar convergence:Composite-reinforced hinge designs combining timber frames with aluminum corner posts are penetrating high-value electronics freight.
- Digital load-tracking integration:RFID-enabled collars are enabling real-time asset visibility, allowing pooling companies to monetize location data alongside rental fees.
Industry Challenges
- ISPM-15 certification backlog:Heat-treatment kiln capacity constraints are extending compliance timelines for uncertified suppliers attempting market entry.
- Legacy ERP integration friction:Pooling operators struggle to synchronize collar tracking systems with shipper warehouse management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wooden Pallet Collars Market |
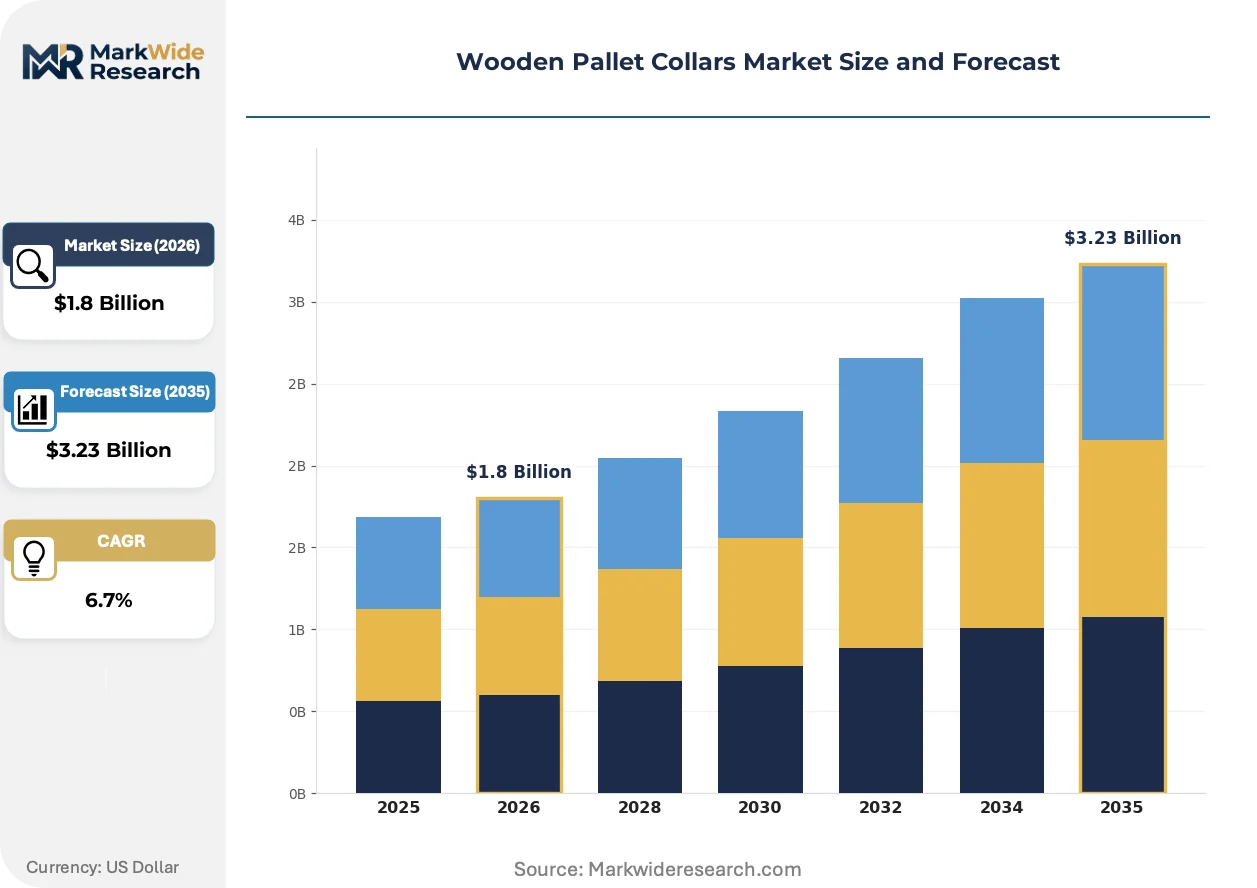
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Collar, Nesting Collar, Corner Collar, Adjustable Collar End User: Retail, Manufacturing, Logistics, Food & Beverage Material: Pine, Oak, Birch, Composite Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Kronus, DUROtherm, Loscam, H G Timber, Hangzhou Guoli Packing, CABKA Group, Eredi Caimi, Nefab, GEBHARDT Logistic Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wooden Pallet Collars Market Evolving Landscape
Automation of kiln operations and digital asset tracking are compressing treatment cycle times while regulatory documentation requirements harden across EU border checkpoints. These forces are reshaping competitive positioning toward vertically integrated operators with captive certification capacity.
Laser-guided moisture detection systems are automating quality grading at Baltic sawmill intake stations. German automotive shippers are adopting these platforms fastest, rejecting inbound collars with residual moisture above 20 percent. This technology is automating supplier pre-qualification, compressing the field of approved vendors to heat-treatment operators with inline sensing infrastructure.
EU Green Deal timber traceability requirements are mandating blockchain-anchored chain-of-custody documentation from forest stand to pallet pool. Baltic producers are retrofitting sawmills with GPS-tagged log tracking to satisfy Länder waste authority audits. Pharmaceutical exporters face the steepest compliance burden, as EMA good distribution practice guidelines now reference packaging material provenance.
Third-party logistics buyers are consolidating vendor relationships around full-service pooling contracts that bundle collar supply, reverse logistics, and treatment compliance. This displaces spot-market purchasing for standard 1200 mm by 800 mm formats. The shift is most visible in Netherlands-based food distribution, where Albert Heijn and Jumbo Supermarkten operators have moved to single-source pooling agreements.
Wooden Pallet Collars Market Segmentation
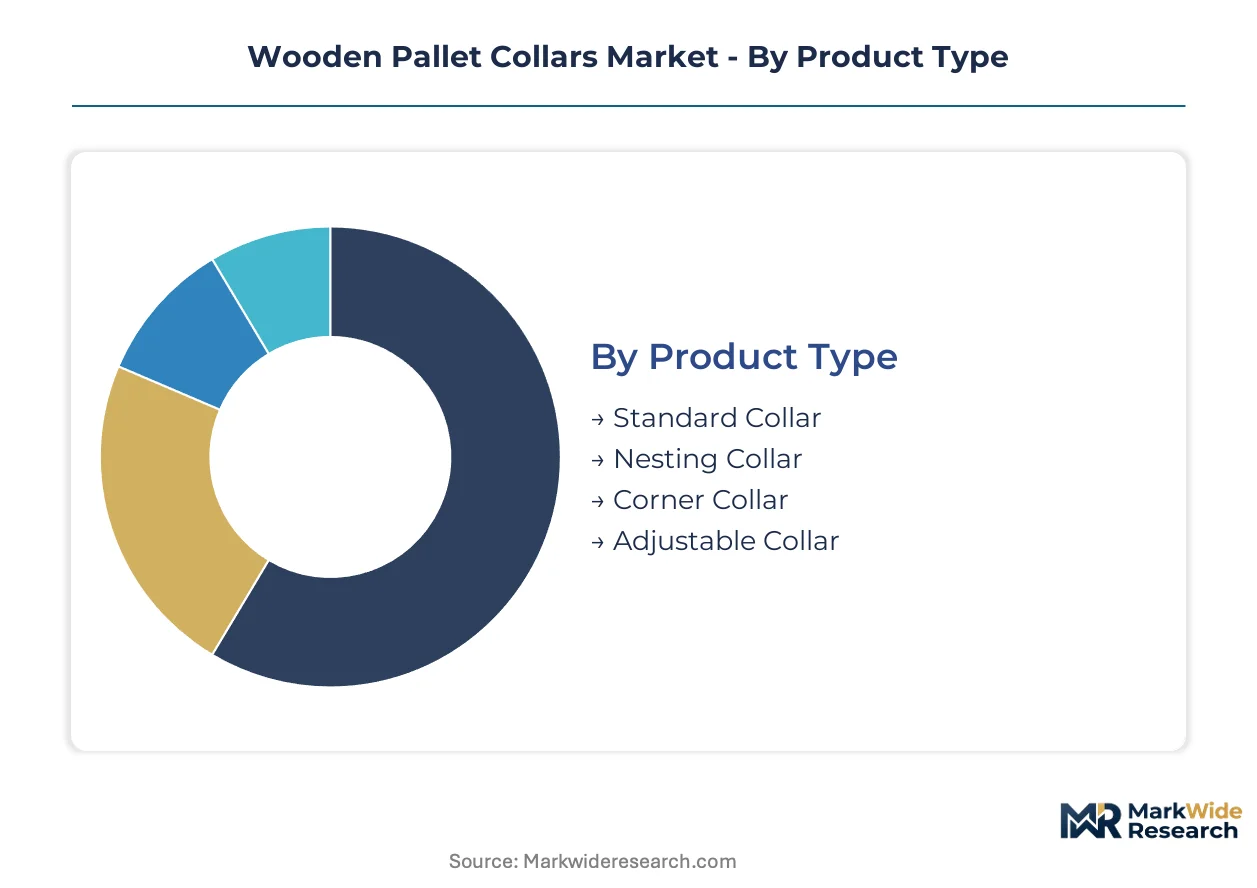
Wooden pallet collar procurement hinges on load containment requirements, return-trip economics, and regulatory compliance documentation. Buyers segment choices across product geometry, material grade, and channel reliability to optimize pooling network performance.
Product Type:
Cost tier determines adoption velocity across shipper categories, with premium formats commanding multi-year pooling contracts while economy variants serve spot-market spot buyers.
- Standard Collar:Fixed 1200 mm by 800 mm timber frames with hinged construction dominate automotive and chemical manufacturing in Germany's Rhine-Ruhr corridor. These units anchor the installed base for closed-loop pooling networks where durability amortization across 50+ rotation cycles justifies higher upfront capital deployment.
- Nesting Collar:Collapsible designs with interlocking hinge geometry compress to one-fifth of erected height, enabling trailer cube utilization gains of 30-40 percent on empty return legs. Third-party logistics operators in Netherlands food distribution are converting fleets fastest, driven by Albert Heijn and Jumbo Supermarkten single-source pooling mandates.
- Corner Collar:Engineered aluminum-reinforced posts at frame corners protect high-value electronics freight from compression damage during stacked transport.
- Adjustable Collar:Modular height configurations accommodate irregular pharmaceutical and dairy loads requiring variable containment walls.
Standard collars lead on scale; nesting collars lead on momentum.
End User:
Application severity separates segments, with temperature-sensitive lanes demanding ISPM-15 documentation and moisture-graded timber while general freight tolerates broader supplier qualification.
- Food & Beverage:Cold-chain hardening in dairy and pharmaceutical export corridors is redirecting procurement toward certified Baltic producers with captive heat-treatment capacity. EMA good distribution practice guidelines now reference packaging material provenance, elevating compliance documentation to load-tender requirements.
- Logistics:Third-party operators prioritize nesting collar compatibility and RFID-enabled asset tracking to monetize location data alongside rental fees, compressing vendor relationships toward full-service pooling contracts.
- Manufacturing:Automotive component suppliers in Poland's Silesia region lack dense pooling infrastructure, presenting white space for depot network establishment.
- Retail:Traditional bulk display applications are losing share to cold-chain logistics as dominant demand vertical, though supermarket chains still specify standard collars for back-of-store inventory management.
Food & Beverage leads on compliance premium capture; Logistics leads on technology integration pace.
Material:
Volume scale and margin structure diverge sharply, with commodity softwoods serving mass-market pooling while specialty hardwoods and engineered composites defend niche positioning.
- Pine:Baltic softwood dominates material selection due to favorable strength-to-weight ratios and established kiln-drying workflows, though price volatility tied to Nordic pulp mill demand and Russian timber export restrictions squeezes margin predictability for heat-treatment operators.
- Birch:Dense, moisture-resistant grades command premium positioning in pharmaceutical lanes where residual content below 20 percent is mandatory, with laser-guided detection systems automating supplier pre-qualification at German automotive intake stations.
- Oak:Hardwood durability serves heavy manufacturing applications requiring extended rotation cycles beyond typical softwood fatigue limits.
- Composite:Fiber-reinforced polymer blends penetrate moisture-critical lanes where timber's hygroscopic limitations disqualify conventional options.
Pine leads on volume throughput; birch leads on value-per-unit expansion.
Distribution Channel:
Customer type and purchase frequency shape channel economics, with large fleet operators consolidating around direct relationships while fragmented buyers rely on intermediary stocking.
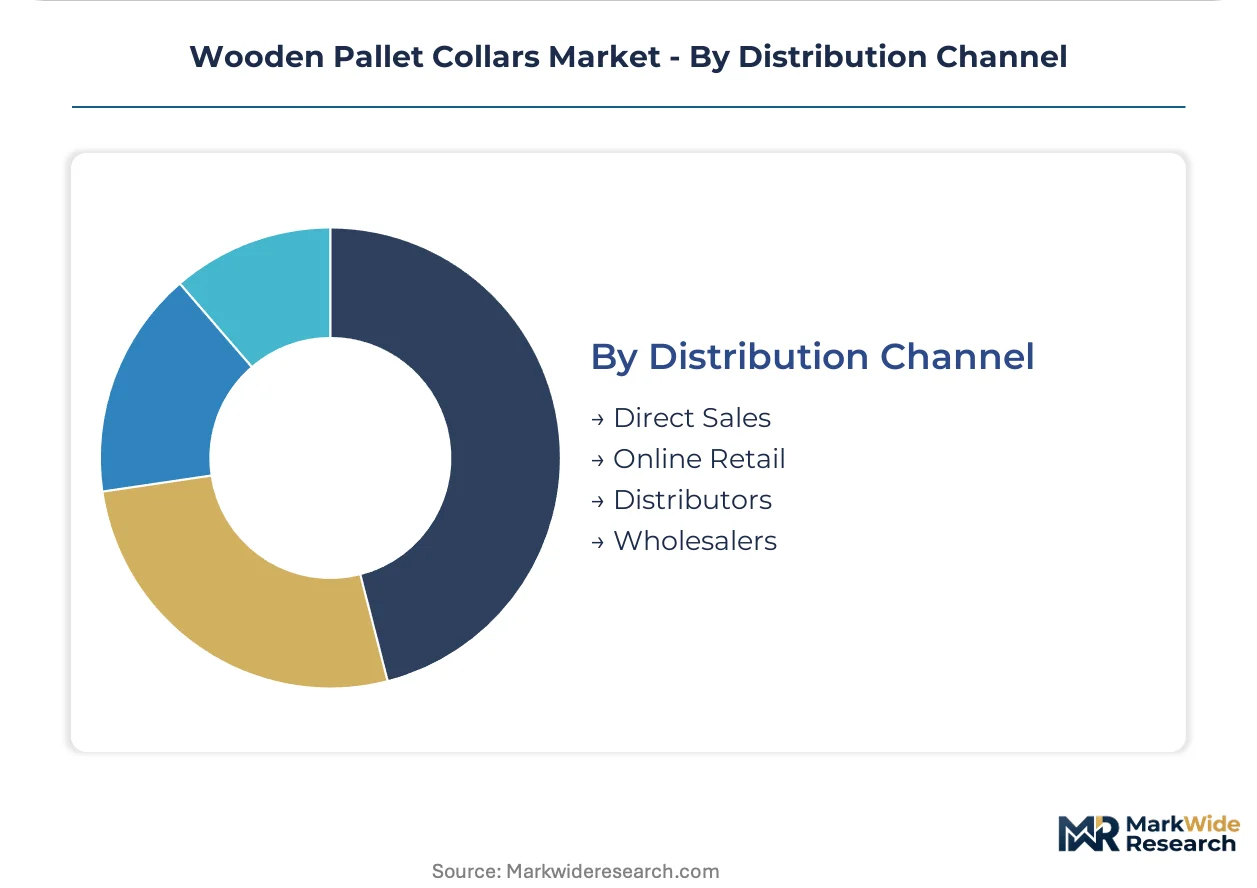
- Direct Sales:Closed-loop pooling operators in Germany and Netherlands negotiate multi-year supply contracts directly with Baltic sawmills, bundling collar provision with reverse logistics and ISPM-15 compliance documentation to displace spot-market purchasing.
- Distributors:Regional stocking intermediaries serve mid-tier manufacturers lacking volume scale for direct mill relationships, particularly in underpenetrated Polish automotive corridors.
- Wholesalers:Bulk aggregators supply standard 1200 mm by 800 mm formats to small retail and light manufacturing accounts with irregular replenishment patterns.
- Online Retail:Digital channels capture spot buyers requiring rapid fulfillment of replacement collars without pooling network membership.
Direct sales leads on contract value concentration; distributors lead on geographic coverage extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting pallet collar production toward Baltic states where EU Green Deal compliance costs remain lower than Western European manufacturing centers, while demand concentrates in Germany's industrial corridors and Netherlands distribution hubs.
Germany
Automotive and chemical shippers in the Rhine-Ruhr corridor maintain dense pooling networks that absorb standard collar volumes. The national packaging ordinance enforced by Länder waste authorities mandates recycling quotas favoring multi-trip systems. Stuttgart-based OEMs are rejecting inbound collars with residual moisture above 20 percent, automating supplier pre-qualification.
Netherlands
Food distribution operators Albert Heijn and Jumbo Supermarkten have migrated to single-source pooling agreements for nesting collar fleets. REACH chemical disclosure rules redirect procurement toward certified Baltic producers. Rotterdam port congestion is compressing lead times for uncertified suppliers attempting market entry.
Poland
Automotive component suppliers in Silesia lack dense pooling infrastructure, presenting white space for depot network establishment. EMA good distribution practice guidelines elevate packaging material provenance to load-tender requirements. Warsaw-based third-party logistics operators are converting trailer fleets to collapsible nesting designs.
Latvia
Sawmill capacity clusters create geographic concentration of ISPM-15 heat-treatment infrastructure. Timber traceability mandates under EU Green Deal are mandating blockchain-anchored chain-of-custody documentation. Riga port operations face phytosanitary border delays that extend compliance timelines for export-bound collars.
France
Pharmaceutical exporters face steep compliance burdens as EMA guidelines reference packaging material provenance. ANSM audits enforce sanitary wood packaging rules for food-contact applications. Lyon-based dairy exporters are expanding collar pooling networks to maintain temperature integrity through modular stacking systems.
Wooden Pallet Collars Market Competitive Landscape
Capacity consolidation dominates the current landscape as pooling operators captive-source heat-treatment infrastructure to secure ISPM-15 certification capacity. The vendor base stratifies across three tiers: Baltic sawmill-integrated producers with inline sensing infrastructure, Western European logistics operators bundling reverse logistics with collar provision, and Asian fabricators serving spot-market replacement demand. M&A activity targets heat-treatment kiln networks, while strategic partnerships embed collar tracking into shipper warehouse management platforms.
Among Baltic-integrated producers, Kronus anchors supply for Northern European pharmaceutical and dairy exporters through its timber sourcing and treatment infrastructure. CABKA Group occupies a position within the closed-loop pooling tier, while Nefab exemplifies the engineered design specialists serving high-value electronics freight. These three represent distinct competitive archetypes: captive supply chain control, full-service logistics bundling, and premium product engineering.
| Leading Market Players |
|---|
| Kronus |
| DUROtherm |
| Loscam |
| H G Timber |
| Hangzhou Guoli Packing |
| CABKA Group |
| Eredi Caimi |
| Nefab |
| GEBHARDT Logistic Solutions |
| Others |
Value Network & Pricing Analysis
EU Green Deal timber traceability mandates gate both qualified supply and premium-tier pricing access, forcing buyers to pay compliance premiums for Baltic-certified collars while locking out uncertified competitors from pharmaceutical and dairy export lanes. This regulatory filtering concentrates pricing power among heat-treatment operators with captive ISPM-15 infrastructure.
Pricing Analysis
Distributor margins compress 15-25 percent for spot-market standard collars, while direct-to-OEM pooling contracts command 8-12 percent discounts in exchange for volume commitments. Pricing stratifies across ISPM-15 certified premium, moisture-graded standard, and uncertified economy tiers, with birch pharmaceutical grades capturing the widest spreads. Cost compression in pine softwood inputs is intensifying because Nordic pulp mill demand competes for Baltic supply. Third-party logistics operators show highest price sensitivity, while pharmaceutical exporters prioritize documentation reliability over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Germany's Rhine-Ruhr automotive and chemical corridors, while distributor networks serve fragmented Polish manufacturing. Supply concentrates in Latvia, Estonia, and Lithuania, where sawmill capacity clusters around Riga and Tallinn ports. Raw material flows draw from Nordic pine forests, Russian timber alternatives, and Baltic birch stands. Single-source vulnerability runs through Riga port congestion and phytosanitary border delays that extend ISPM-15 certification timelines. Distribution feeds from Baltic sawmills through Rotterdam and Hamburg hub-and-spoke networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wooden pallet collars function as a stable compounder anchored by EU packaging sustainability mandates that harden demand for certified reusable systems across food and pharmaceutical cold chains.
For Market Incumbents: To counter plastic pallet substitution in moisture-critical pharmaceutical lanes, deepen backward integration into Baltic kiln capacity and deploy laser-guided moisture detection at intake stations. Certification investment in blockchain-anchored chain-of-custody documentation defends premium positioning against emerging Baltic sawmill competitors. For New Entrants and Emerging Players: Enter via Poland's underpenetrated Silesia automotive corridor, where depot network gaps and EMA good distribution practice compliance burdens deter established pooling operators. Target nesting collar conversion opportunities among Warsaw-based third-party logistics fleets seeking trailer cube utilization gains. For Investors and Strategic Acquirers: Roll-up economics work for Baltic sawmill-integrated heat-treatment specialists because ISPM-15 certification backlogs create scarcity value for compliant capacity. Watch nesting collar adoption rates among Netherlands food distributors as the inflection signal for fleet conversion momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kiln Capacity | Captive ISPM-15 infrastructure secures pharmaceutical tender eligibility under EMA guidelines. |
| RFID-Enabled Asset Tracking Deployment | Real-time collar visibility allows pooling operators to monetize location data alongside rental fees. |
| Nesting Collar Fleet Conversion | Compresses empty return haulage costs for Albert Heijn and Jumbo Supermarkten distribution networks. |
| Blockchain Chain-of-Custody Implementation | Satisfies Länder waste authority audits and EU Green Deal timber provenance requirements. |
| Depot Network Establishment in Poland | Addresses infrastructure gaps among Silesia automotive component suppliers lacking pooling coverage. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Baltic sawmill operations managers, German automotive procurement leads, Netherlands food distribution logistics directors, and pharmaceutical supply chain compliance officers with secondary validation. Sources included EU customs trade data, EMA good distribution practice guidance documents, Länder waste authority enforcement records, and SEC filings from listed pooling operators. Bottom-up collar volume estimates and top-down packaging market sizing were cross-referenced for triangulation.
Historical reference periods anchored the projection horizon through verified installed base counts and rotation cycle economics across German pooling networks. The analytical framework modeled segmentation across product geometry, material grade, end-use vertical, and distribution channel, with CAGRs derived from elasticity-adjusted demand curves. Forecast inputs incorporated Baltic softwood price volatility indices and phytosanitary border delay frequencies.
Inputs from EMA regulatory filings and Baltic customs records were available through the study window; gaps in real-time pooling fleet utilization data introduce uncertainty bands around nesting collar adoption velocity. Forecasts reflect assumptions about EU Green Deal enforcement consistency and pine input cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
United States Pallet Market
Pallets Packaging
Pallet Displays Market
Pallets Packaging
Pallet Tines Market
Pallets Packaging
Pallet Labeler Market
Pallets Packaging
Global Crates and Pallets Packaging Market
Pallets Packaging
Indonesia Pallets Market
Pallets Packaging
Global Pallet Racking System Market
Pallets Packaging
Japan Pallets Market
Pallets Packaging
Disposable Plastic Pallet Market
Pallets Packaging
Mexico Pallets Market
Pallets Packaging
Asia-Pacific Lumber Pallet Market
Pallets Packaging
Europe Lumber Pallet Market
Pallets Packaging
Middle East Pallets Market
Pallets Packaging
Spill Pallets Market
Pallets Packaging
Foldable Plastic Pallet Boxes Market
Pallets Packaging
Palletizer Market