
 Single Use Pallet Market | 2026-2036
Single Use Pallet Market Size, Share, and Industry Trends Forecast 2026-2036
Single Use Pallet Market Analytics
Automation in pallet manufacturing is rewriting cost structures across the single-use pallet supply chain. CABKA Group leverages recycled polymer injection molding to anchor its position in closed-loop supply contracts for retail chains. Schoeller Allibert competes through modular nestable designs that reduce empty return freight by sixty percent in European distribution networks. Brambles Ltd operates the largest pooled pallet network globally, though its single-use offerings target specialized pharmaceutical and fresh-produce lanes where hygiene mandates dominate procurement criteria.
A single-use pallet is a platform designed for one-way shipment, typically manufactured through high-pressure injection molding of recycled HDPE or thermoformed corrugated plastic, engineered to specified load ratings for racking and floor stacking without repair or return logistics. Wood retains the largest volume share in single-use applications due to lowest unit cost, yet plastic is displacing share fastest in pharmaceutical and food-grade segments where contamination control and ISPM-15 exemption eliminate heat-treatment delays. Euro-size configurations dominate intra-European freight, while custom dimensions capture premium margin pools in automated warehouse environments where exact rack tolerances reduce product damage.
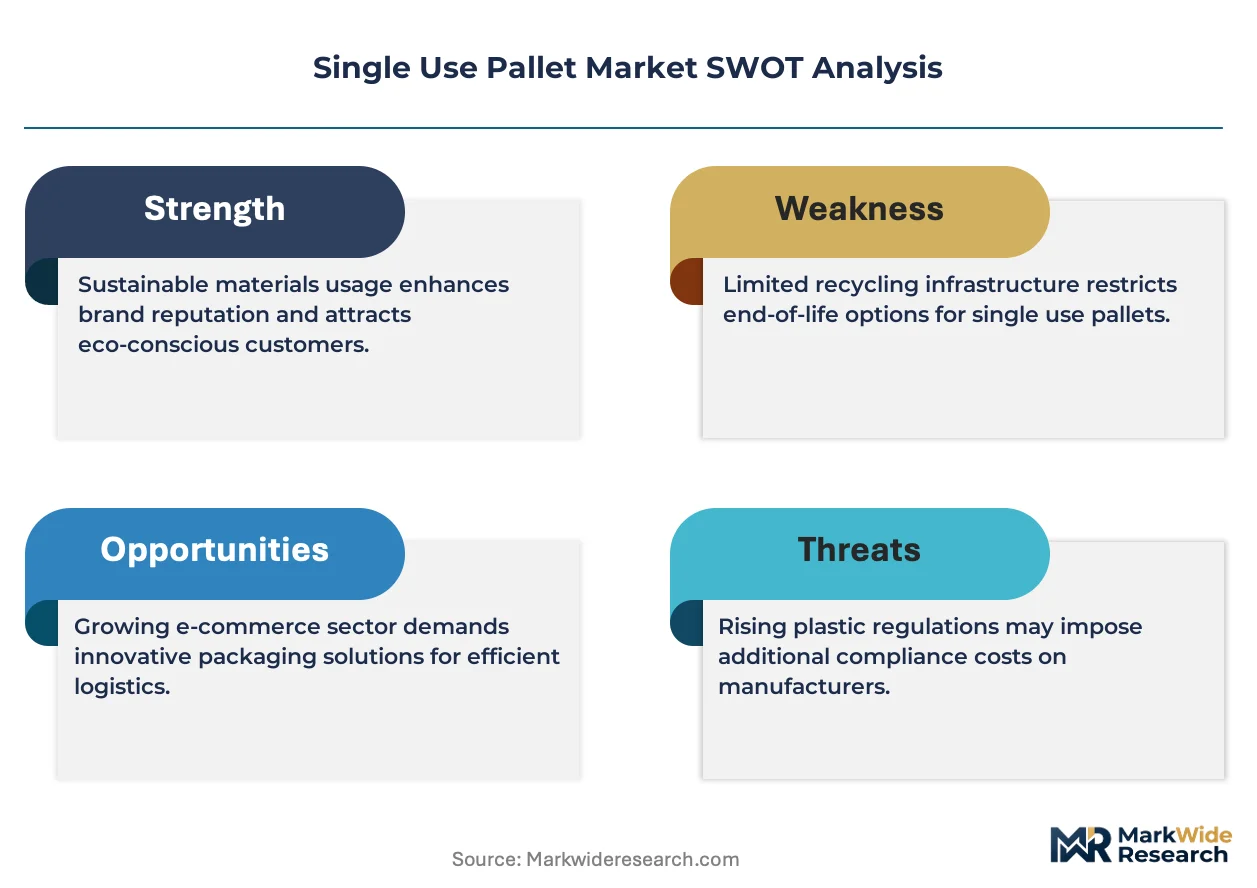
The EU Packaging and Packaging Waste Regulation and REACH compliance frameworks mandate recyclability thresholds and restrict certain chemical additives in plastic pallets sold across member states, forcing manufacturers to reformulate resins or risk market exclusion. FDA food-contact regulations in the United States and CFIA standards in Canada impose parallel migration limits that shape material selection for North American food and pharmaceutical pallet applications. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to invest in chemical recycling partnerships or pivot toward fiber-based alternatives as carbon accounting tightens across buyer procurement scorecards.
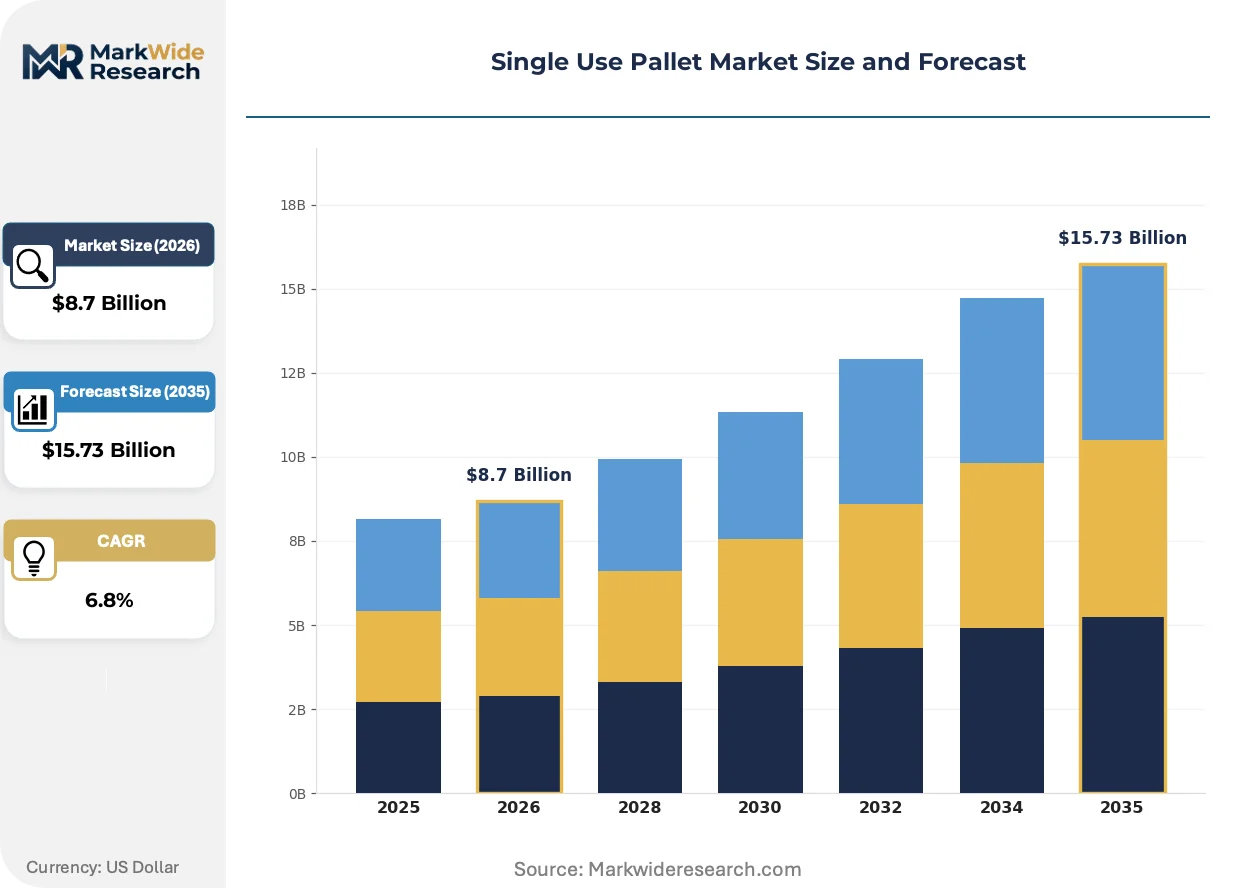
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles for single-use pallet converters. REACH compliance mandates and ISPM-15 exemption advantages for plastic platforms are accelerating material substitution decisions across European freight networks.
Growth Catalysts
- Pharmaceutical cold-chain expansion:Temperature-sensitive biologics distribution demands hygienic, trackable platforms that eliminate cross-contamination risks. Single-use plastic pallets satisfy FDA and EMA cold-chain validation protocols.
- REACH chemical restrictions:ECHA reformulation deadlines are forcing resin suppliers to develop additive-free HDPE compounds. Compliant pallets capture premium positioning in food-contact and healthcare segments.
- German automotive export density:Just-in-time component flows between Stuttgart, Wolfsburg, and Eastern European assembly plants favor lightweight, nestable platforms that reduce fuel surcharges on intra-European lanes.
Market Restraints
- Recycled polymer price volatility:Post-consumer HDPE flake costs fluctuate with crude oil benchmarks and packaging collection rates. Margins compress when virgin resin becomes price-competitive with recycled feedstock.
- Tooling capex concentration:High-pressure injection molds for 1200x800mm Euro pallets require seven-figure capital commitments. Equipment suppliers cluster in Southern Germany and Northern Italy, creating bottleneck risk.
- Wood pallet residual cost advantage:Softwood platforms retain lowest unit economics for non-hygienic bulk freight. Heat-treated timber satisfies ISPM-15 at marginal incremental cost for transoceanic shipments.
Strategic Opportunities
- Polish manufacturing expansion:Lower labor and energy costs versus Western Europe attract molders serving German retail chains. Silesian industrial zones offer proximity to major distribution corridors.
- RFID-embedded trackability:Convergence of low-cost sensors and cloud logistics platforms enables pallet-level visibility. Pharmaceutical shippers in Basel and Copenhagen pilot subscription-based tracking services.
- Chemical recycling partnerships:Pyrolysis and depolymerization facilities in Rotterdam and Antwerp promise food-grade resin recovery. Early offtake agreements secure circular feedstock claims for ESG procurement scorecards.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FDA, EFSA, and CFIA food-contact approvals require 18-24 month validation cycles. Migration testing protocols differ across regulators, forcing redundant laboratory expenditure.
- Automation integration complexity:Exact dimensional tolerances for automated warehouse racking vary by OEM. Pallet suppliers must maintain multiple mold configurations for Swisslog, Dematic, and Vanderlande system specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Use Pallet Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Wood, Metal, Composite End User: Food & Beverage, Retail, Pharmaceuticals, E-Commerce Size Category: Standard, Euro, Half-Size, Custom Distribution Channel: Direct Sales, Distributor, Online Retail, Others |
| Companies Covered | Brambles Ltd, CABKA Group, Schoeller Allibert, Menasha Corporation, Craemer Group, DNA Packaging Systems Inc., NEFAB GROUP, PECO Pallet, Inc., PalletOne, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Use Pallet Market Evolving Landscape
Material science advances and regulatory compression are converging to redefine platform performance standards. Three developments dominate strategic planning for pallet converters and their end-use customers.
Cellular foam-core thermoforming is collapsing the weight-strength tradeoff that historically favored injection-molded designs. Refrigerated pharmaceutical distributors in Denmark and the Netherlands are adopting these platforms for air freight lanes where every kilogram drives fuel surcharge calculations. The technology is collapsing minimum order quantities for custom dimension production, enabling mid-size shippers to specify exact rack tolerances without committing to dedicated mold investment.
EU Green Deal carbon border adjustment mechanisms are tightening embodied emissions accounting for imported plastic products. Pallet converters sourcing virgin resin from Middle Eastern petrochemical complexes face mounting documentation burdens to prove lifecycle carbon intensity below sector benchmarks. German automotive manufacturers are responding by inserting recycled content mandates into supplier qualification questionnaires, effectively filtering platform vendors by circular feedstock access.
Subscription-based pallet pooling is displacing capital purchase models among mid-market food retailers. Carrefour and Ahold Delhaize procurement teams in France and Belgium are piloting per-trip pricing that bundles platform supply with reverse logistics and sanitization. This shift concentrates volume with network operators possessing dense depot infrastructure, marginalizing standalone manufacturers lacking last-mile collection capability.
Single Use Pallet Market Segmentation
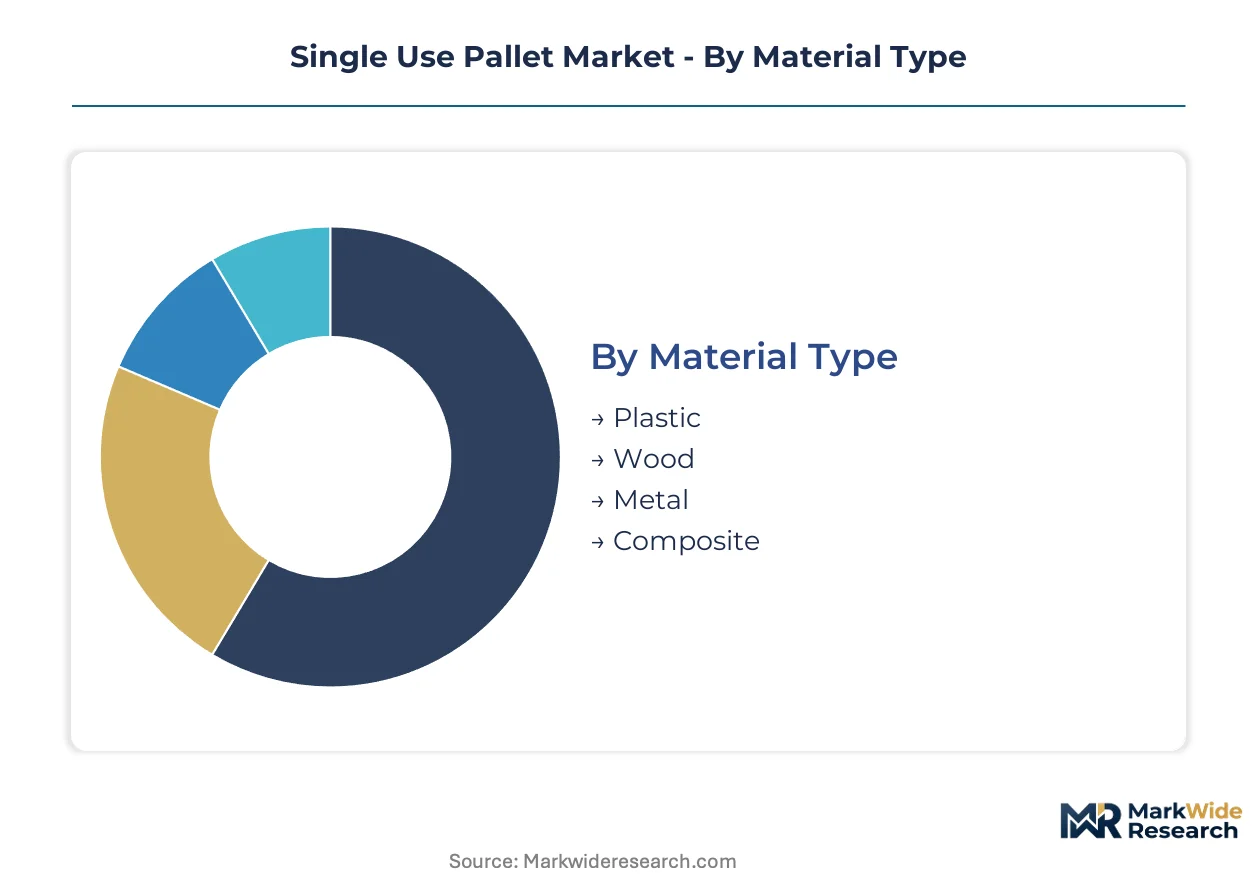
Material composition determines regulatory compliance pathways and lifecycle cost structures for single-use pallet procurement. End-use application shapes hygiene mandates, load specifications, and tracking requirements across pharmaceutical, food-grade, and general freight segments.
Material Type:
Cost tier positioning separates commodity bulk freight solutions from premium hygienic platforms requiring chemical compliance and contamination control.
- Plastic:Injection-molded recycled HDPE or thermoformed corrugated designs deliver ISPM-15 exemption and FDA/EMA food-contact compliance. Pharmaceutical cold-chain distributors in Denmark and the Netherlands specify these for temperature-sensitive biologics where heat-treatment delays are unacceptable.
- Wood:Softwood platforms retain lowest unit economics for non-hygienic bulk shipments. Heat-treated timber satisfies ISPM-15 for transoceanic freight at marginal incremental cost, though REACH chemical restrictions and EU Packaging Waste Regulation recyclability thresholds are compressing share in European lanes.
- Metal:Steel and aluminum configurations serve heavy-load industrial applications requiring extreme durability for single-use export of machinery and automotive components.
- Composite:Engineered wood-plastic or fiber-reinforced hybrids balance weight reduction with structural integrity for specialized aerospace and precision equipment logistics.
Wood commands the established base. The steepest expansion runs through plastic.
End User:
Application-specific hygiene mandates and automation integration requirements fragment procurement criteria across consumer-facing and industrial supply chains.
- Food & Beverage:FDA and EFSA migration limits dictate material selection for direct-contact applications. Major retail chains in France and Belgium are piloting subscription pooling models that bundle platform supply with sanitization and reverse logistics.
- Pharmaceuticals:EMA cold-chain validation protocols and trackability mandates drive specification of RFID-embedded plastic platforms. Basel and Copenhagen shippers prioritize hygienic, nestable designs that eliminate cross-contamination risks in temperature-sensitive distribution.
- Retail:High-volume grocery and hypermarket distribution networks favor lightweight nestable configurations to minimize fuel surcharges on dense depot-to-store lanes.
- E-Commerce:Parcel carrier sortation centers demand exact dimensional tolerances for automated warehouse integration with Swisslog, Dematic, and Vanderlande system specifications.
Food & Beverage anchors volume demand. Pharmaceuticals is climbing the fastest.
Size Category:
Volume throughput and rack system compatibility determine standardization versus customization tradeoffs in procurement decisions.
- Standard:North American 48x40 inch configurations dominate transatlantic freight and US domestic distribution networks.
- Euro:1200x800mm specifications govern intra-European automotive and chemical supply chains, with German exporters prioritizing lightweight designs for just-in-time component flows to Eastern European assembly plants.
- Half-Size:Reduced footprints serve retail display pallets and promotional shipments requiring store-floor placement without secondary handling.
- Custom:Automated warehouse environments with exact rack tolerances drive specification of bespoke dimensions, with cellular foam-core thermoforming collapsing minimum order quantities for mid-size shippers.
Euro dimensions capture the densest intra-regional flow. Custom specifications are gaining share fastest.
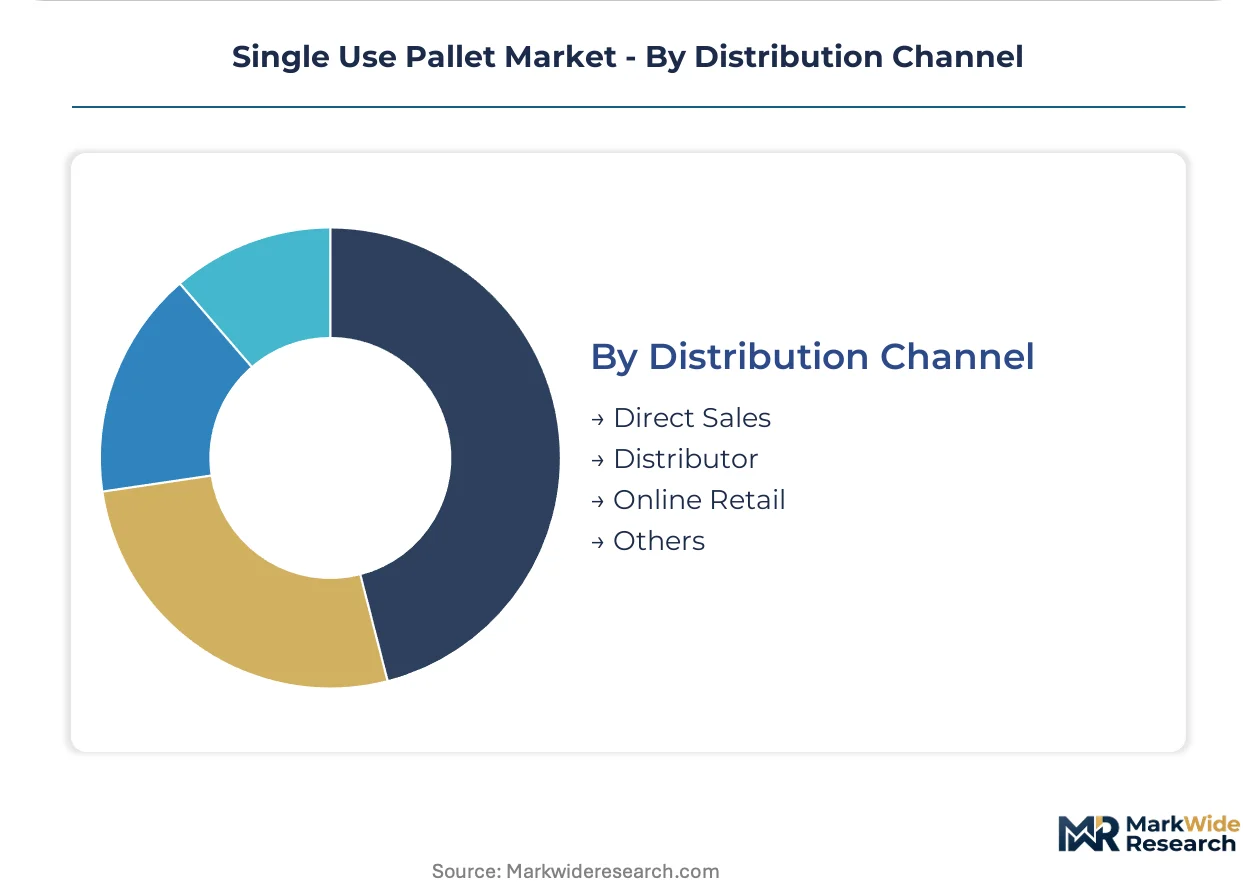
Distribution Channel:
Customer scale and geographic concentration shape whether procurement runs through direct manufacturer relationships or intermediated network structures.
- Direct Sales:Large automotive and pharmaceutical manufacturers negotiate closed-loop supply contracts with molders for predictable volume commitments and mold-sharing arrangements.
- Distributor:Regional logistics providers aggregate demand from mid-market food retailers and industrial shippers, offering inventory buffering and localized technical support.
- Online Retail:Digital procurement platforms serve spot-market buyers and smaller e-commerce operators requiring rapid fulfillment without long-term contract structures.
- Others:Pallet pooling subscription services and equipment leasing arrangements are emerging as alternative access models, particularly among French and Belgian retail chains testing per-trip pricing.
Distributor networks handle the broadest customer base. Direct sales is expanding most quickly among large-volume accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive exporters ship just-in-time components to Eastern European assembly plants via lightweight plastic platforms that evade ISPM-15 heat-treatment delays. This corridor anchors European single-use pallet demand.
Germany
Stuttgart and Wolfsburg automotive clusters specify nestable plastic pallets for intra-European freight to Poland and Czech Republic. REACH compliance mandates from ECHA force resin reformulation for food-contact applications. Bavarian molders in the Nuremberg industrial zone supply closed-loop contracts to discount retail chains.
United States
Pharmaceutical distributors in New Jersey and North Carolina cold-chain hubs demand FDA-validated hygienic platforms for biologics shipment. EPA industrial emissions frameworks shape manufacturing site selection for domestic producers. Chicago-area logistics corridors concentrate pallet pooling depot networks serving Midwest food retail.
China
E-commerce fulfillment centers in Shanghai and Shenzhen specify exact dimensional tolerances for automated sortation systems. NMPA pharmaceutical logistics standards drive adoption of trackable plastic platforms for domestic vaccine distribution. Yangtze River Delta manufacturers export thermoformed designs to Southeast Asian consumer markets.
Netherlands
Rotterdam chemical recyclers pilot pyrolysis facilities promising food-grade resin recovery for circular pallet production. EU Packaging and Packaging Waste Regulation recyclability thresholds compress design cycles for converters serving Belgian and French retail chains. Eindhoven-region automation OEMs demand custom rack-tolerance specifications from platform suppliers.
India
Pharmaceutical exporters in Maharashtra and Gujarat adopt ISPM-15 exempt plastic pallets for EU-bound temperature-sensitive shipments. CDSCO cold-chain validation protocols mirror FDA standards for domestic vaccine distribution. Delhi-NCR logistics hubs aggregate demand from mid-market food retailers transitioning from wood to hygienic platforms.
Single Use Pallet Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Pooled network operators leverage depot density to bundle platform supply with reverse logistics, while standalone molders compete on custom specifications and mold-sharing flexibility. Two archetypes dominate: automation-integrated specialists serving pharmaceutical and e-commerce verticals, and scale-driven recyclers anchoring retail closed-loop contracts. Competitive moves concentrate on chemical recycling partnerships for circular feedstock claims and RFID-embedded trackability pilots for pharmaceutical subscription services.
Within the pooled-network tier, Brambles Ltd exemplifies channel control through global depot infrastructure. Among European molders, CABKA Group and Schoeller Allibert occupy positions at opposite ends of the design spectrum: the former anchors closed-loop recycling contracts with retail chains, while the latter represents modular nestable configurations that minimize empty return freight. Menasha Corporation and Craemer Group sit within the North American fabrication tier, supplying standard and custom dimensions to automotive and food-grade segments. NEFAB GROUP and PECO Pallet, Inc. represent hybrid models blending manufacturing with logistics network operation.
| Leading Market Players |
|---|
| Brambles Ltd |
| CABKA Group |
| Schoeller Allibert |
| Menasha Corporation |
| Craemer Group |
| DNA Packaging Systems Inc. |
| NEFAB GROUP |
| PECO Pallet, Inc. |
| PalletOne, Inc. |
| Others |
Value Network & Pricing Analysis
Overcapacity in Southern German injection molding clusters is compressing supplier margins and forcing tiered pricing concessions to automotive buyers. ECHA reformulation deadlines for REACH-compliant resins are simultaneously elevating input costs, creating divergent cost trajectories across compliant and non-compliant pallet tiers.
Pricing Analysis
The pricing gap between cellular foam-core thermoformed platforms and legacy injection-molded designs is narrowing as production scale accumulates. A three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical grades from automotive just-in-time specifications and commodity bulk freight wood alternatives. Cost compression in the standard tier is intensifying because recycled HDPE flake costs track crude oil volatility. Food retailers in France and Belgium exhibit the highest price sensitivity, while pharmaceutical cold-chain distributors in Denmark accept premium positioning for contamination control.
Supply Chain Analysis
EU dual-use export controls on advanced automation components are constraining mold fabrication equipment flows to non-member states. Manufacturing gravity centers on Germany, Poland, and Italy, with Silesian industrial zones drawing molders serving German retail chains. Feedstock draws from post-consumer packaging collection networks across the Benelux and Northern France, with pyrolysis facilities in Rotterdam and Antwerp anchoring circular resin recovery. Single-source vulnerability concentrates in Southern German equipment suppliers for high-pressure injection molds. Distribution runs through pooled network operators with dense depot infrastructure rather than standalone manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of chemical recycling partnerships with food-grade resin offtake agreements is concentrating margin capture among early movers. Mold-sharing flexibility and EMA cold-chain validation expertise represent the critical capability gaps separating viable competitors from marginal players.
For Market Incumbents: Insulate core automotive contracts in Stuttgart and Wolfsburg through backward integration into recycled resin compounding. Secure exclusive mold-sharing arrangements with discount retail chains to block emerging Polish competitors. Chemical recycling partnership scarcity threatens long-term feedstock access for ESG procurement scorecards. For New Entrants and Emerging Players: Pursue mid-market pharmaceutical distributors in Basel and Copenhagen lacking dedicated cold-chain validation resources. White-space concentrates in RFID-embedded trackability services bundled with per-trip pricing models. A subscription-based pooling pilot with regional hospital networks offers the most penetrable entry vector. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across thermoformed pallet sub-segments as cellular foam-core tooling costs decline. Long-term viability favors acquisition targets possessing dense depot infrastructure in the Netherlands and Belgium combined with EMA validation expertise. Watch for CDSCO alignment with FDA cold-chain standards in India as the inflection signal for emerging market expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Partnership | Secures circular feedstock claims for ESG procurement scorecards at German automotive manufacturers. |
| RFID Trackability Integration | Enables subscription-based visibility services for pharmaceutical shippers in Basel and Copenhagen. |
| Polish Manufacturing Expansion | Captures labor and energy cost advantages versus Western European molder competitors. |
| EMA Cold-Chain Validation | Unlocks premium positioning in temperature-sensitive biologics distribution networks. |
| Cellular Foam-Core Adoption | Collapses minimum order quantities for custom dimensions in automated warehouse specifications. |
Research Methodology
A standing panel of pallet pooling network operators, automotive procurement directors, pharmaceutical logistics managers, and chemical recycling facility engineers provided ongoing calibration across the study period. Primary interviews with resin compounders and mold fabrication equipment suppliers combined with secondary validation from ECHA regulatory filings, EU Packaging and Packaging Waste Regulation impact assessments, and customs trade data for HDPE flake movements. Bottom-up volume estimates triangulated against top-down sector expenditure analysis.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeled by material type, end-use application, size category, and distribution channel. CAGRs derived from weighted average of historical trajectory and technology diffusion curves. Forecast inputs incorporated REACH compliance timeline acceleration and automation penetration rates in European warehouse installations.
Sensitivities concentrate around recycled resin price volatility and EMA validation protocol revisions. Forecasts reflect documented assumptions on chemical recycling facility commissioning schedules and automotive just-in-time lane density. Material shifts in EU carbon border adjustment mechanism scope or CDSCO-FDA harmonization timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Corrugated Pallet Containers Market
Pallets Packaging
Corrugated Pallet Wrap Market
Pallets Packaging
Pallet Corner Boards Market
Pallets Packaging
Spill Pallets Market
Pallets Packaging
Pallet Bands Market
Pallets Packaging
Thermal Pallet Covers Market
Pallets Packaging
PUR Shippers Market
Pallets Packaging
Block Pallets Market
Pallets Packaging
Global Crates and Pallets Packaging Market
Pallets Packaging
Pallet Jacks Market
Pallets Packaging
Stringer Pallets Market
Pallets Packaging
Composite Pallet Market
Pallets Packaging
Pallet Pooling Market
Pallets Packaging
Presswood Pallets Market
Pallets Packaging
Stretch Hood Pallet Wrapping Market
Pallets Packaging
China Pallets Market