
 Disposable Plastic Pallet Market | 2026-2036
Disposable Plastic Pallet Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Plastic Pallet Market Outlook
Pallet pooling subscription models is rebalancing how logistics platforms monetize fleet access rather than asset ownership. CABKA Group leverages captive recycling infrastructure to control resin feedstock quality across production cycles. Schoeller Allibert anchors European pharmaceutical distribution through ISO-standard hygienic pallet designs. ORBIS Corporation competes on lightweight nesting geometry that reduces truck cube utilization in retail replenishment networks.
Disposable plastic pallets are rotationally molded or injection-molded platforms from HDPE, PP, or recycled polymer blends, engineered for one-way or limited-use logistics cycles with specified load ratings from 500 kg to 5,000 kg. Their primary purpose is eliminating reverse logistics costs and cross-contamination risks in sensitive supply chains. Nestable designs dominate volume economics by collapsing empty pallet stacks to one-quarter of erected height, while rackable variants command margin pools in automated warehouse environments where beam-supported storage is mandatory. Heavy-duty capacity grades are displacing wood alternatives in beverage export applications where ISPM-15 heat treatment compliance adds cost and delay.
FDA regulations on sanitary transport for food contact surfaces and EPA recycled content mandates are shaping material specifications and limiting virgin resin reliance in domestic production. EU REACH restrictions on additive chemistries and the F-Gas Regulation's indirect pressure on cold-chain energy efficiency are filtering into pallet procurement criteria for temperature-controlled logistics. Stakeholders must monitor how Extended Producer Responsibility frameworks in multiple jurisdictions redefine cost allocation between pallet manufacturers and their brand-owner customers.
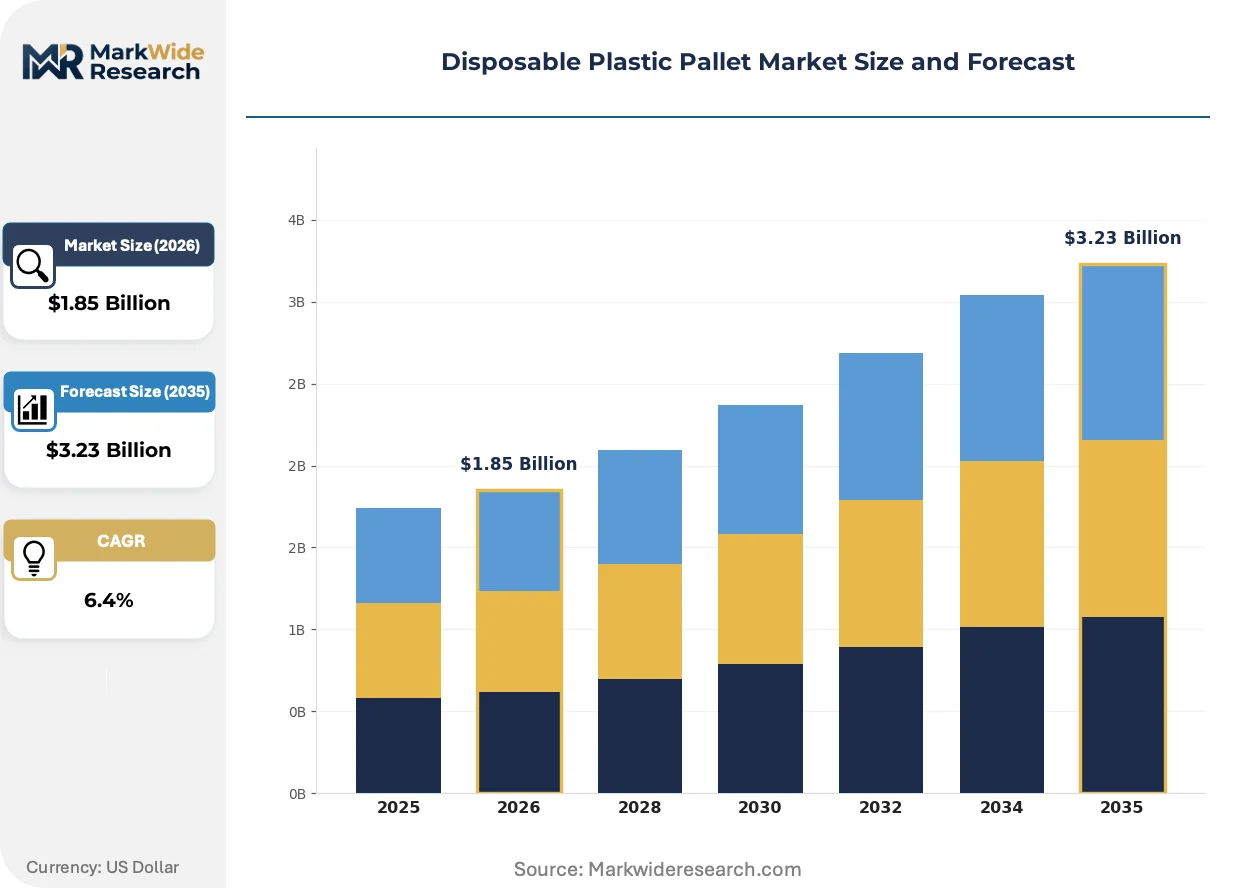
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing material recovery timelines for plastic shipping platforms, forcing manufacturers to reengineer resin selection and end-of-life collection infrastructure ahead of enforcement deadlines.
Growth Catalysts
- Pharmaceutical cold-chain expansion:Temperature-sensitive biologics distribution requires hygienic single-use pallets that eliminate cross-contamination risks between batches. FDA sanitary transport rules reinforce this specification in US pharmaceutical corridors.
- ISPM-15 compliance burden on wood:Heat treatment certification delays and documentation costs for wooden export pallets push beverage and agricultural exporters toward disposable plastic alternatives with immediate customs clearance.
- Lightweight nesting geometry:Truck cube utilization improvements from collapsible pallet designs reduce empty return freight costs in retail replenishment networks, particularly in Germany's automotive component export lanes.
Market Restraints
- Virgin resin price volatility:HDPE and polypropylene feedstock costs fluctuate with crude oil indices, compressing margin predictability for rotationally molded pallet producers without captive recycling streams.
- EU REACH additive restrictions:Flame retardants and UV stabilizers face progressive authorization limits, forcing reformulation cycles that extend product development timelines and certification costs.
- Wood pallet residual competitiveness:Domestic hardwood availability in Eastern European sawmill regions sustains low-cost wooden platform supply for non-hygienic applications with limited regulatory pressure.
Strategic Opportunities
- Extended Producer Responsibility frameworks:France and Germany's advance implementation of full-cost waste recovery obligations creates first-mover advantage for manufacturers with established closed-loop collection infrastructure.
- Post-consumer recycled content mandates:EPA recycled content requirements for federal procurement channels open premium positioning for pallet producers achieving specified rHDPE blend ratios in domestic production.
- Automated warehouse rackable designs:Beam-supported storage requirements in high-bay distribution centers command margin pools through reinforced deck structures that wooden alternatives cannot replicate at equivalent weight.
Industry Challenges
- Multi-jurisdiction certification complexity:ISO 8611 load testing, FDA food contact notification, and EU CE marking requirements demand parallel documentation streams that strain quality assurance staffing in mid-cap producers.
- Legacy ERP integration friction:Pallet pooling subscription platforms require real-time asset tracking APIs that conflict with incumbent logistics software architectures in established freight networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Plastic Pallet Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nestable, Rackable, Stackable, Customized End User: Food & Beverage, Pharmaceuticals, Retail, Electronics Application: Warehouse, Transportation, Packaging, Export Capacity: Lightweight, Medium Duty, Heavy Duty, Extra Heavy Duty |
| Companies Covered | CHEP, Craemer Holding GmbH, ORBIS Corporation, Polymer Logistics, Falkenhahn AG, Rehrig Pacific Company, CABKA Group, SSI Schaefer, Schoeller Allibert, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Plastic Pallet Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are converging to redefine acceptable resin formulations, while digital asset tracking penetrates fleet management models.
Recycled ocean-bound plastic feedstock is electrifying sustainable pallet manufacturing by converting coastal waste collection into certified polymer inputs. Beverage exporters with published net-zero commitments are specifying these pallets for brand-aligned supply chain documentation. The technology is electrifying competitive differentiation by transforming environmental compliance into procurement selection criteria.
EU F-Gas Regulation amendments are indirectly tightening cold-chain energy efficiency standards that propagate into pallet insulation specifications for temperature-controlled pharmaceutical lanes. Logistics operators must now document thermal bridge minimization in platform selection for qualified medicinal product distribution. German and Dutch pharmaceutical hubs are responding by mandating pallet thermal performance data in vendor qualification questionnaires.
Subscription-based fleet access contracts are displacing outright pallet purchases in retail grocery replenishment networks. Third-party pooling operators assume asset ownership and maintenance liability, converting capital expenditure into operational line items. This model is most visible in France's hypermarket distribution corridors where centralized procurement favors service relationships over inventory ownership.
Disposable Plastic Pallet Market Segmentation
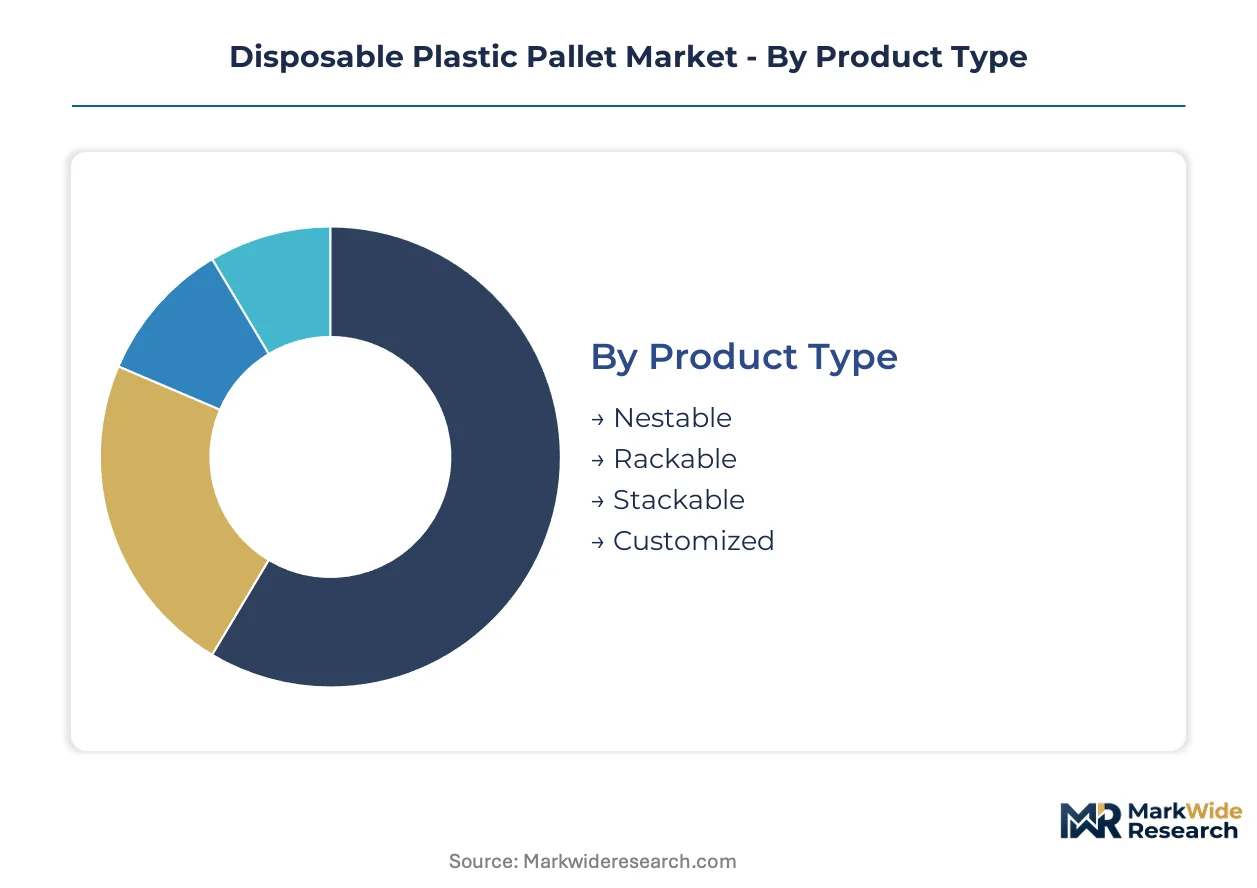
Segmentation in the disposable plastic pallet market reflects divergent logistics economics. Load-bearing requirements, warehouse automation compatibility, and hygiene protocols each drive distinct procurement patterns across end-use verticals.
Product Type:
Buyers differentiate primarily by empty-return freight economics versus storage infrastructure requirements.
- Nestable:Collapsible designs reduce empty stack height to one-quarter of erected dimensions, cutting return shipment costs in retail replenishment networks. Germany's automotive component export corridors favor these for high-frequency turnaround cycles where truck cube utilization directly impacts landed cost calculations.
- Rackable:Reinforced deck structures withstand beam-supported storage in automated high-bay warehouses, commanding premium positioning where wooden alternatives fail at equivalent weight ratings. Pharmaceutical distribution centers specify these for FDA-compliant sanitary transport of temperature-sensitive biologics.
- Stackable:Fixed-height platforms optimize floor loading in non-automated storage environments with lower capital infrastructure requirements.
- Customized:Application-specific dimensions and load ratings serve specialized export packaging for oversized industrial components.
Nestable designs lead volumes today; rackable variants are gaining share fastest in automated warehouse deployments.
End User:
Regulatory intensity and contamination risk tolerance separate procurement specifications across buyer categories.
- Food & Beverage:ISPM-15 heat treatment compliance burdens on wooden pallets push beverage exporters toward immediate customs clearance advantages of plastic alternatives. FDA sanitary transport rules reinforce single-use specifications for food contact surfaces.
- Pharmaceuticals:Temperature-sensitive biologics distribution demands hygienic platforms that eliminate cross-contamination between batches. EU F-Gas Regulation amendments propagate into thermal bridge minimization requirements for qualified medicinal product lanes.
- Retail:Subscription-based pooling models convert capital expenditure to operational line items in grocery replenishment networks.
- Electronics:Static-dissipative resin formulations protect sensitive components through controlled conductivity specifications.
Food and beverage anchors current demand; pharmaceutical applications are expanding most quickly.
Application:
Asset ownership models and reverse logistics burden shape platform selection across use cases.
- Warehouse:Beam-supported storage mandates rackable designs with reinforced perimeter profiles for automated retrieval systems.
- Transportation:Lightweight nesting geometry reduces fuel consumption in long-haul freight corridors where empty return trips dominate cost structures.
- Packaging:Unit-load containment specifications drive customized dimensions for export shipment stability.
- Export:Immediate customs clearance without ISPM-15 documentation delays displaces heat-treated wood in agricultural and beverage export lanes.
Transportation applications dominate volume; export usage is climbing the fastest as trade documentation burdens intensify.
Capacity:
Load rating thresholds determine material thickness, resin grade, and structural reinforcement requirements.
- Lightweight:Sub-500 kg ratings serve single-use consumer goods distribution with minimal handling cycles.
- Medium Duty:500-1,500 kg capacity brackets balance material cost against durability for retail replenishment networks.
- Heavy Duty:1,500-3,000 kg ratings with reinforced deck structures displace wood in beverage export applications where ISPM-15 compliance adds cost and delay.
- Extra Heavy Duty:3,000-5,000 kg specifications serve industrial machinery and automotive component logistics with concentrated load distribution engineering.
Medium duty capacity leads current procurement; heavy duty grades are expanding most quickly in regulated export corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive export corridors generate heavier pallet throughput than France's retail consolidation hubs, though both face identical EU Packaging and Packaging Waste Regulation compliance deadlines. Regulatory pressure is compressing material recovery timelines across multiple jurisdictions simultaneously.
United States
FDA sanitary transport rules and EPA recycled content mandates drive pharmaceutical and federal procurement specifications. Domestic hardwood availability in Eastern sawmill regions sustains residual wood pallet competition for non-regulated freight. Chicago's distribution corridor anchors cold-chain logistics expansion for temperature-sensitive biologics.
Germany
Automotive component export volumes through North Rhine-Westphalia and Bavaria favor nestable designs for high-frequency turnaround cycles. Extended Producer Responsibility frameworks in Germany impose full-cost waste recovery obligations ahead of EU-wide harmonization. Stuttgart's manufacturing belt concentrates heavy-duty pallet demand for machinery export packaging.
China
Dual carbon goals and GB standards on packaging waste accelerate domestic recycled content requirements. E-commerce fulfillment expansion in the Yangtze River Delta generates lightweight pallet consumption for single-use consumer goods distribution. Shanghai's port logistics cluster standardizes plastic pallet specifications for export container optimization.
France
Hypermarket distribution networks in Île-de-France advance subscription-based pooling models that convert capital expenditure to operational line items. ANSM pharmaceutical regulations reinforce hygienic single-use specifications for qualified medicinal product lanes. Lyon-Rhône logistics corridor implements thermal performance data requirements for cold-chain pallet procurement.
Netherlands
Rotterdam-Europoort container throughput drives export-oriented pallet standardization for immediate customs clearance without ISPM-15 delays. REACH additive restrictions on flame retardants and UV stabilizers force reformulation cycles among domestic compounders. Eindhoven's high-tech manufacturing cluster specifies static-dissipative resin formulations for electronics component logistics.
Disposable Plastic Pallet Market Competitive Environment
Top-tier vendors anchor premium rackable and hygienic designs, while mid-cap specialists compete on nestable volume economics and captive recycling infrastructure. The vendor base stratifies across three functional tiers: integrated resin-to-platform producers controlling feedstock quality, pooling operators monetizing fleet access through subscription contracts, and regional fabricators serving customized export packaging specifications. Two dominant competitive moves are reshaping positioning: backward integration into post-consumer recycling streams and technology licensing agreements for lightweight nesting geometries.
Among German-based integrated producers, Craemer Holding GmbH and CABKA Group exemplify the resin-capture archetype through captive recycling infrastructure. Schoeller Allibert occupies a position within the hygienic design tier serving pharmaceutical distribution requirements. ORBIS Corporation anchors the lightweight nesting specialization for retail replenishment networks. These three represent distinct strategic vectors rather than overlapping competitive territory.
| Leading Market Players |
|---|
| CHEP |
| Craemer Holding GmbH |
| ORBIS Corporation |
| Polymer Logistics |
| Falkenhahn AG |
| Rehrig Pacific Company |
| CABKA Group |
| SSI Schaefer |
| Schoeller Allibert |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical cold-chain distributors and automotive component exporters concentrate procurement power across Germany and the United States, anchoring subscription-based fleet access contracts that convert capital expenditure into operational line items while compressing spot-market pricing for standardized nestable designs.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for lightweight consumer-grade pallets. Three-tier pricing structure across hygienic-certified, standard industrial, and economy single-use levels separates pharmaceutical buyers from beverage exporters from retail replenishment networks. Cost compression in economy tiers is intensifying because domestic hardwood availability in Eastern European sawmill regions sustains residual wood pallet competition. Pharmaceutical buyers show least price sensitivity due to FDA sanitary transport compliance requirements.
Supply Chain Analysis
EPA recycled content mandates and EU REACH additive restrictions are reshaping sourcing patterns for resin feedstock across domestic production. Supply concentrates in Germany, China, and the United States for injection-molded and rotationally molded platforms. Raw material dependencies draw from HDPE and polypropylene resin streams, recycled polymer blends, and captive post-consumer recycling infrastructure. Single-source vulnerability runs through crude oil-indexed virgin resin pricing. Distribution runs through third-party pooling operators and direct OEM supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Temperature-sensitive biologics distribution demands are shifting procurement specifications toward hygienic-certified rackable designs with documented thermal performance data.
For Market Incumbents: To counter virgin resin price volatility eroding margin predictability, deepen backward integration into captive recycling infrastructure controlling feedstock quality across production cycles. Invest in ISO 8611 load testing certification for automated warehouse rackable designs to defend premium positioning against lightweight nesting specialists. For New Entrants and Emerging Players: EU Packaging and Packaging Waste Regulation in Germany and France opens a window for closed-loop collection infrastructure providers ahead of harmonized enforcement deadlines. Target France's hypermarket distribution corridors where subscription-based pooling models convert capital expenditure to operational line items. Lead with real-time asset tracking API integration to resolve legacy ERP friction in established freight networks. For Investors and Strategic Acquirers: Pallet pooling operators and logistics technology platforms are the most active acquirers in this space. Five-to-ten year viability hinges on Extended Producer Responsibility framework implementation creating first-mover advantage for manufacturers with established waste recovery infrastructure. Monitor ANSM and FDA pharmaceutical procurement qualification questionnaires for thermal performance data requirements as inflection indicator for hygienic design tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Recycling Infrastructure Buildout | CABKA Group and Craemer Holding GmbH control resin feedstock quality across production cycles in Germany. |
| Subscription-Based Fleet Access Contracts | Third-party pooling operators convert capital expenditure to operational line items in France's hypermarket networks. |
| Hygienic Design Certification Investment | Schoeller Allibert anchors European pharmaceutical distribution through ISO-standard thermal performance data. |
| Lightweight Nesting Geometry Licensing | ORBIS Corporation reduces truck cube utilization in Germany's automotive component export corridors. |
| Real-Time Asset Tracking API Development | Resolves legacy ERP integration friction in established retail replenishment freight networks. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with logistics procurement directors, pharmaceutical supply chain managers, automotive component export coordinators, and pallet pooling platform operators with secondary validation from FDA filings, EPA procurement databases, EU Packaging and Packaging Waste Regulation implementation trackers, and customs trade data. Bottom-up shipment volume triangulation against top-down resin consumption estimates anchors forecast integrity.
Rate-of-change decomposition separates volume growth from price trajectory across the projection horizon. Segmentation dimensions modeled include product type, end-use vertical, application context, and capacity rating. CAGRs derive from logistic curve fitting to historical adoption patterns with pharmaceutical cold-chain expansion and ISPM-15 compliance burden on wood as primary demand drivers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under crude oil price volatility and EU REACH additive authorization limits. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and pooling subscription penetration rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Stretch Hood Pallet Wrapping Market
Pallets Packaging
Global Crates and Pallets Packaging Market
Pallets Packaging
Pallet Jacks Market
Pallets Packaging
Pallet Tines Market
Pallets Packaging
United States Pallet Market
Pallets Packaging
PUR Shippers Market
Pallets Packaging
Germany Pallets Market
Pallets Packaging
Pallet Banding Machine Market
Pallets Packaging
Stringer Pallets Market
Pallets Packaging
Corrugated Pallet Containers Market
Pallets Packaging
North America Lumber Pallet Market
Pallets Packaging
Spill Pallets Market
Pallets Packaging
Corrugated Pallets Market
Pallets Packaging
Pallet Collar Market
Pallets Packaging
Wooden Pallets Market
Pallets Packaging
Foldable and Collapsible Pallets Market