
 PUR Shippers Market | 2026-2036
PUR Shippers Market Size, Share, and Industry Trends Forecast 2026-2036
PUR Shippers Market Analytics
North American production capacity for temperature-controlled packaging is fragmenting as regional manufacturers scale polyurethane foam molding operations. Sonoco Products leverages its integrated fiber and foam operations to sustain cost advantages across pharmaceutical and food segments. Pelican BioThermal anchors the high-performance segment with reusable thermal container systems. Cold Chain Technologies competes through specialized validation services that support regulatory compliance for biologics distribution.
PUR shippers are insulated shipping containers manufactured with rigid polyurethane foam cores that provide thermal resistance values between R-6 and R-8 per inch, engineered to maintain payload temperatures between frozen and controlled room-temperature ranges for 48 to 120 hours during transit. Their primary purpose is protecting temperature-sensitive biologics, vaccines, and perishable foods from thermal excursion during multi-modal distribution. Rigid shippers dominate current volume due to established pharmaceutical validation protocols, while flexible shippers represent the fastest-expanding category as e-commerce grocery and meal-kit channels scale last-mile cold delivery. Custom shippers command premium positioning where patient-specific cell therapies require validated lane-specific configurations.
The US FDA's Drug Supply Chain Security Act and the EU's Good Distribution Practice guidelines shape validation requirements, forcing manufacturers to document thermal performance across seasonal ambient profiles. Germany's national pharmaceutical regulator enforces supplementary temperature-mapping standards for cross-border EU shipments. Stakeholders must decide whether to prioritize reusable asset models against single-use convenience as carbon accounting pressures intensify across European and North American logistics networks.
Market Dynamics
Pharmaceutical serialization mandates and carbon accounting pressures are bifurcating the PUR shipper landscape between validated reusable systems and compliant single-use alternatives. This structural tension compresses margins for mid-tier converters while rewarding integrated manufacturers with captive foam production.
Growth Catalysts
- EU Good Distribution Practice:Temperature-mapping requirements for cross-border biologics shipments expand demand for validated lane-specific configurations across German and Benelux distribution corridors.
- Cell therapy logistics:Patient-specific autologous treatments require ultra-low temperature shippers with validated thermal profiles from manufacturing site to infusion center.
- Polyurethane foam chemistry advances:Next-generation blowing agents with lower global warming potential enable compliance with EU F-Gas Regulation while maintaining R-7 thermal performance.
Market Restraints
- MDI price volatility:Methylene diphenyl diisocyanate feedstock costs fluctuate with crude oil and natural gas benchmarks, compressing converter margins during energy price spikes.
- Concentrated foam board supply:Rigid polyurethane core production clusters in the US Gulf Coast and northwestern Europe, creating geographic vulnerability to weather disruptions.
- Reusable asset tracking complexity:Return logistics for high-performance thermal containers require RFID infrastructure investment that smaller 3PLs cannot absorb.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO-aligned cold chain infrastructure investment creates demand for cost-optimized shippers validated to EU and US standards.
- Carbon border adjustment mechanisms:EU CBAM implementation favors regional foam molding operations over imported alternatives, rewarding localized production footprints.
- Meal-kit channel expansion:Direct-to-consumer frozen food subscription services require flexible, right-sized thermal packaging for variable last-mile delivery windows.
Industry Challenges
- Thermal validation engineering scarcity:Qualified engineers capable of executing ISTA 7E seasonal profile testing are concentrated among a handful of specialized service providers.
- Serialization integration timelines:FDA Drug Supply Chain Security Act compliance requires shipper-level traceability systems that extend development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PUR Shippers Market |
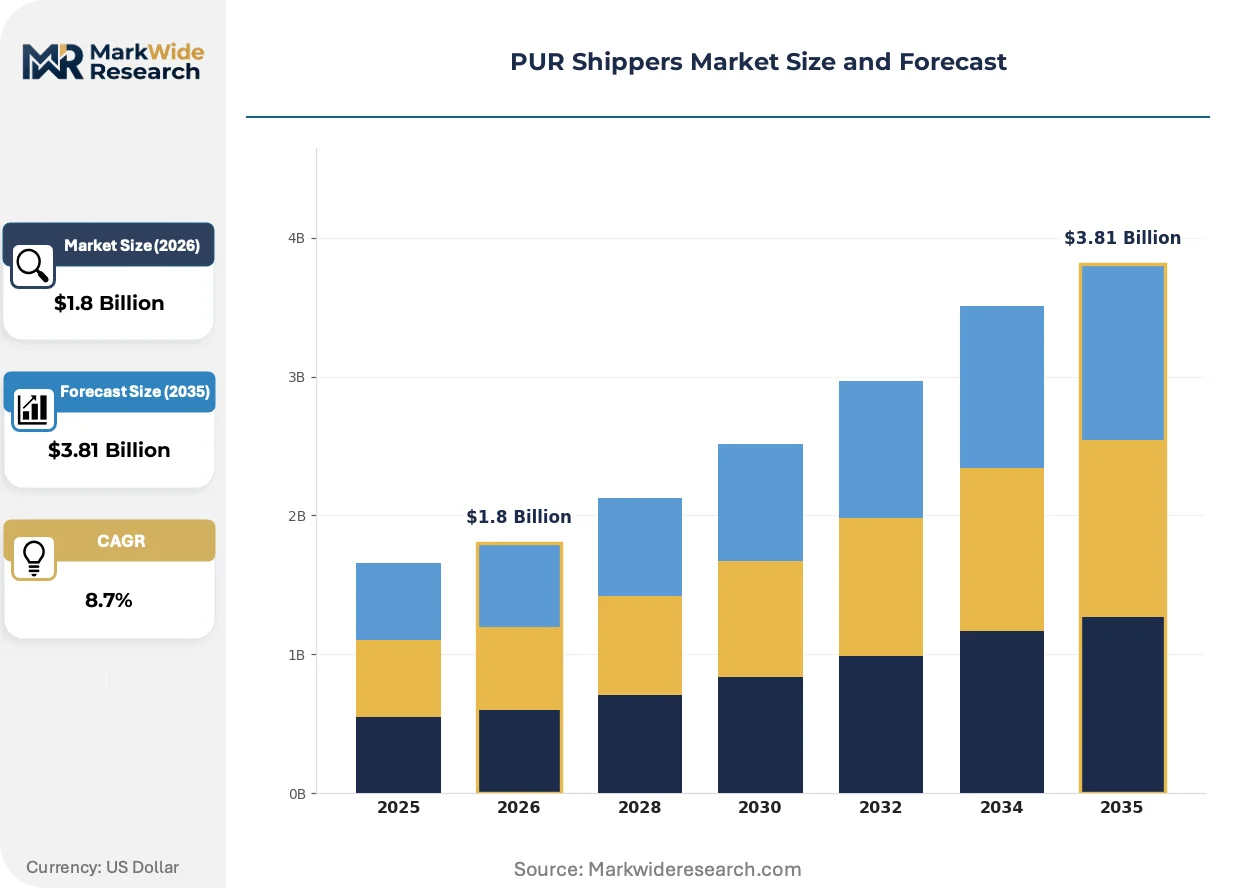
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Shippers, Rigid Shippers, Insulated Shippers, Custom Shippers Material: Polyurethane, EPS Foam, Polyethylene, Plastic Application: Food & Beverage, Pharmaceuticals, Electronics, Industrial Goods End User: Retailers, Manufacturers, Distributors, Logistics Providers |
| Companies Covered | Sonoco Products, Pelican BioThermal, Cold Chain Technologies, Chill-Pak, Polar Tech Industries, DS Smith Plastics, Sonoco ThermoSafe, Tempack Packaging Solutions, Lifoam Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PUR Shippers Market Evolving Landscape
Vacuum insulation panel integration and phase-change material optimization are redefining thermal performance benchmarks while regulatory pressure on refrigerant chemistry accelerates material substitution cycles across converter operations.
Vacuum insulation panels with thermal resistance values exceeding R-30 per inch are penetrating high-value biologics segments where payload temperatures must hold below -60°C for 96-hour transit windows. Gene therapy manufacturers in Massachusetts and North Carolina are specifying VIP-composite shippers for commercial distribution of CAR-T cell therapies. This technology is rendering obsolete traditional expanded polystyrene dominant in frozen food logistics.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon blowing agents forces polyurethane foam producers to reformulate with hydro-olefin or water-blown alternatives. German converters face accelerated compliance timelines under national implementation rules stricter than baseline EU requirements. Pharmaceutical shippers using legacy foam cores encounter revalidation costs that favor integrated manufacturers with in-house polymer chemistry capabilities.
Biopharma procurement teams are consolidating supplier relationships around full-service thermal packaging partners capable of lane-specific qualification studies. This behavior compresses the vendor base for mid-size converters lacking validation service capacity. The shift is most visible among US-based CDMOs managing multi-site clinical trial material distribution networks.
PUR Shippers Market Segmentation
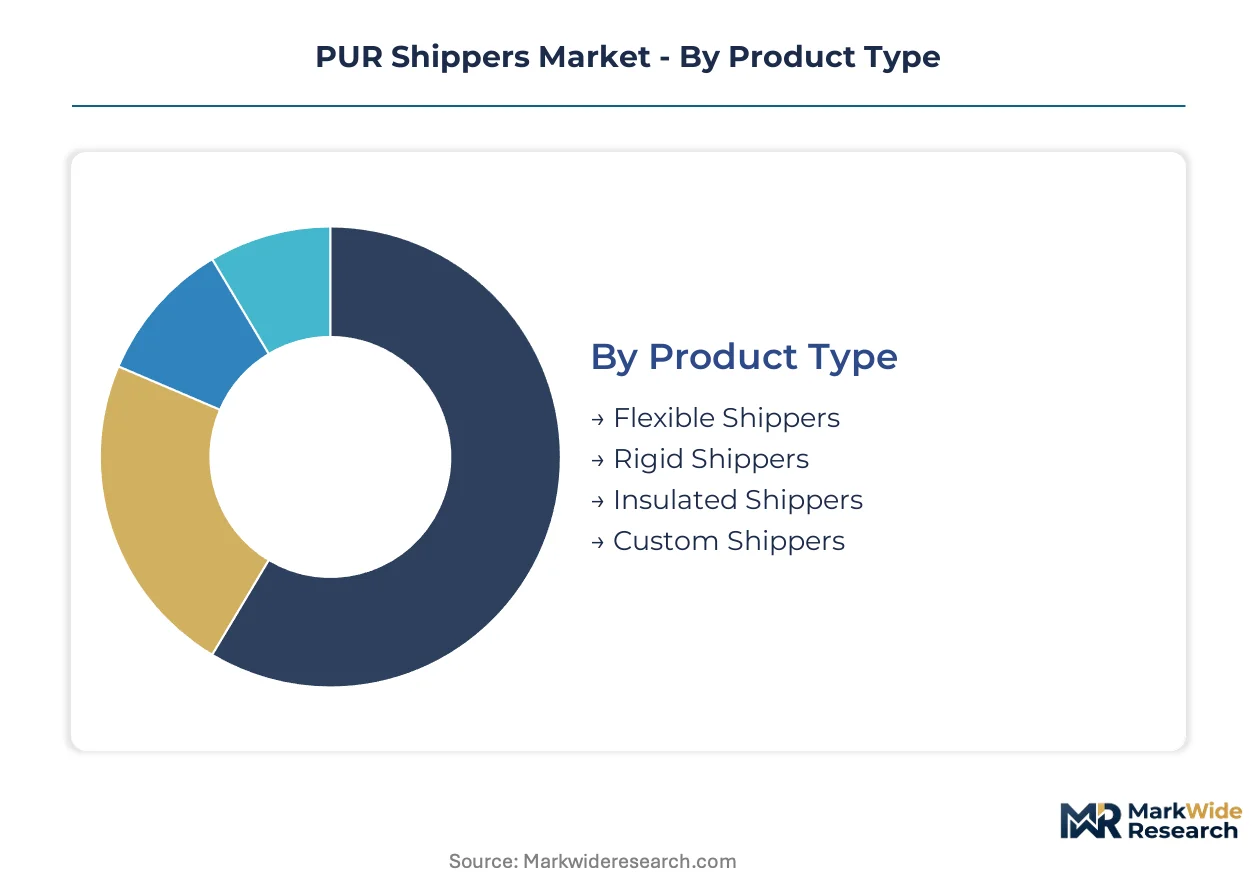
PUR shippers serve divergent thermal protection requirements across pharmaceutical cold chains, perishable food distribution, and industrial logistics. Segmentation reveals how material selection and structural design align with payload value, transit duration, and regulatory validation burdens.
Product Type:
Use-case spectrum spans single-use convenience for meal-kit delivery through validated reusable systems for cell therapy distribution.
- Rigid Shippers:Molded polyurethane foam cores with structural outer shells deliver R-6 to R-8 thermal resistance per inch. Pharmaceutical manufacturers in Germany's Frankfurt corridor specify these for validated lane configurations under EU Good Distribution Practice.
- Flexible Shippers:Lightweight, collapsible designs using quilted foam laminates adapt to variable payload dimensions. E-commerce grocery channels in the United States deploy these for last-mile frozen delivery where return logistics prove uneconomical.
- Insulated Shippers:Hybrid constructions combining foam cores with reflective barriers address intermediate duration requirements. Regional food distributors favor these for 48-72 hour transit windows.
- Custom Shippers:Patient-specific configurations engineered for autologous cell therapies requiring ultra-low temperature maintenance from manufacturing site to infusion center.
Established volume favors rigid shippers; emerging adoption favors flexible shippers.
Material:
Cost tier and carbon accounting pressure differentiate material selection across converter operations.
- Polyurethane:Rigid foam systems blown with next-generation hydro-olefin agents achieve R-7 performance while complying with EU F-Gas Regulation phasedown timelines. German converters face accelerated national implementation stricter than baseline EU requirements.
- EPS Foam:Expanded polystyrene dominates frozen food logistics on price but encounters displacement by vacuum insulation panels in high-value biologics segments.
- Polyethylene:Rotationally molded shells provide moisture barriers and impact resistance for reusable asset models.
- Plastic:Structural components and outer shells from recycled content address emerging procurement sustainability criteria.
Polyurethane commands premium positioning; EPS retains economy tier dominance.
Application:
Regulatory intensity and payload value create divergent performance specifications across verticals.
- Pharmaceuticals:Temperature-sensitive biologics, vaccines, and gene therapies demand ISTA 7E seasonal profile validation. US FDA serialization mandates and EU Good Distribution Practice guidelines force documentation across ambient temperature extremes.
- Food & Beverage:Perishable proteins, dairy, and prepared meals require 48-120 hour thermal protection without pharmaceutical-grade validation overhead.
- Electronics:Temperature-sensitive semiconductors and precision instruments need controlled room-temperature ranges during multi-modal transit.
- Industrial Goods:Chemicals and adhesives with temperature-dependent viscosity specifications represent lower-margin, specification-driven demand.
Pharmaceutical applications concentrate margin; food and beverage applications concentrate volume.
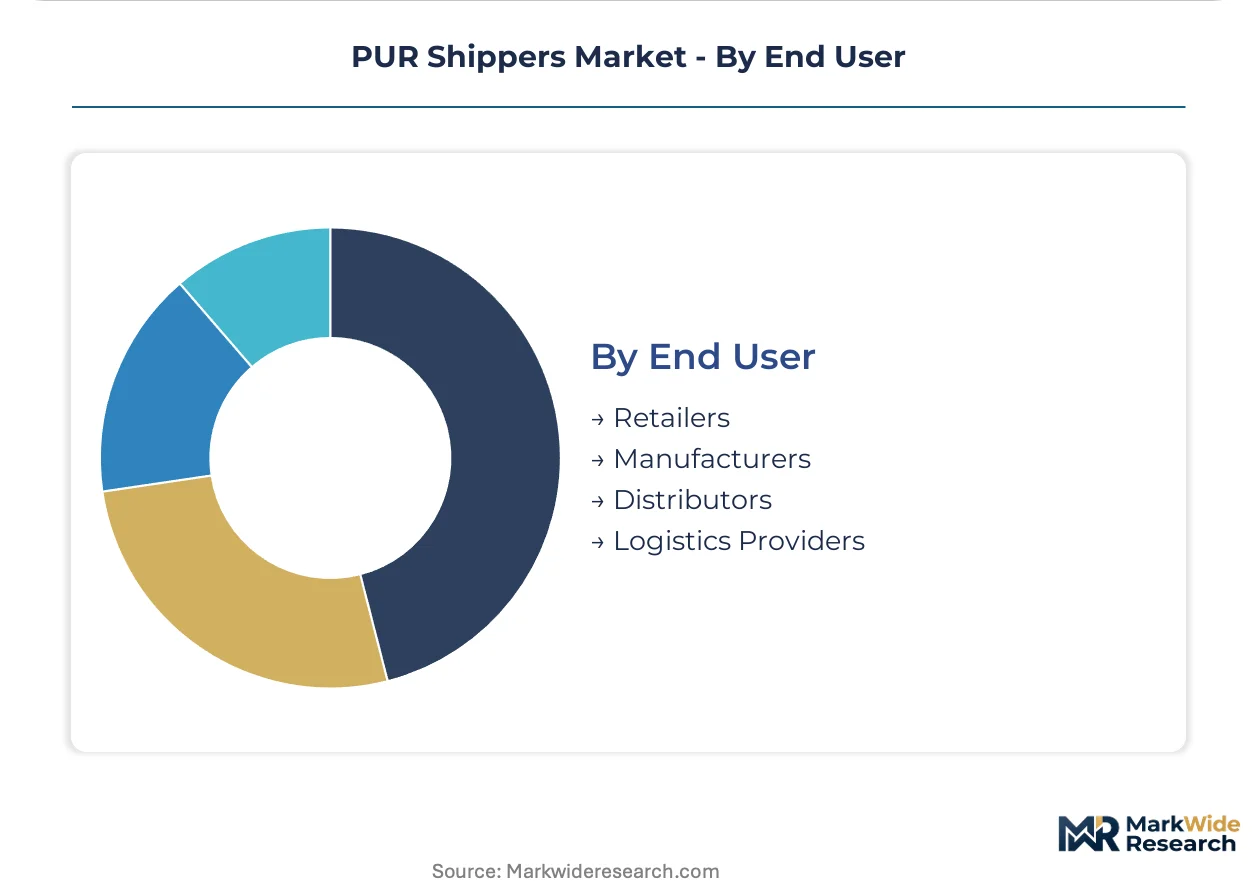
End User:
Procurement sophistication and validation capability separate customer tiers.
- Manufacturers:Biopharma and food producers with captive quality teams execute lane-specific qualification studies. These stakeholders consolidate supplier relationships around full-service thermal packaging partners.
- Logistics Providers:Third-party logistics operators balance asset tracking infrastructure investment against single-use convenience. Smaller 3PLs lack capital for RFID-enabled reusable container networks.
- Distributors:Wholesale and cross-border operators prioritize cost-optimized shippers validated to multiple regulatory standards for Indian pharmaceutical export corridors.
- Retailers:Direct-to-consumer grocery and meal-kit channels drive demand for right-sized, flexible thermal packaging with variable delivery window tolerance.
Manufacturers lead specification authority; logistics providers drive operational scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA serialization mandates and carbon accounting pressures are concentrating PUR shipper demand in pharmaceutical manufacturing corridors across Germany, the United States, India, China, and Japan. Each geography presents distinct regulatory timelines and industrial clustering patterns that shape converter operations and validation requirements.
Germany
Cell therapy manufacturers in Frankfurt and Munich drive demand for ultra-low temperature shippers with validated lane-specific configurations. The national pharmaceutical regulator enforces supplementary temperature-mapping standards stricter than baseline EU Good Distribution Practice requirements. Bavaria's pharmaceutical manufacturing corridor hosts integrated converters with captive foam molding operations serving cross-border EU distribution networks.
United States
Gene therapy manufacturers in Massachusetts and North Carolina specify vacuum insulation panel composite shippers for CAR-T cell therapy commercial distribution. FDA Drug Supply Chain Security Act compliance extends shipper development cycles through serialization integration requirements. The Greater Boston biotech cluster anchors demand for high-performance reusable thermal container systems with RFID-enabled asset tracking infrastructure.
India
Pharmaceutical export corridors to EU and US markets create demand for cost-optimized shippers validated to multiple regulatory standards. CDSCO-aligned cold chain infrastructure investment accelerates as domestic biologics manufacturing scales. Maharashtra's pharmaceutical manufacturing belt around Mumbai and Pune concentrates converter operations serving international distribution networks.
China
Domestic biologics manufacturing expansion and vaccine export programs drive temperature-controlled packaging demand across Yangtze River Delta pharmaceutical clusters. NMPA serialization requirements and EU-equivalent validation standards shape procurement specifications for international-compliant shippers. Shanghai's pharmaceutical logistics hub anchors regional converter capacity for cross-border cold chain distribution.
Japan
Precision medicine logistics and cell therapy commercialization create specialized demand for patient-specific shipper configurations. PMDA guidelines on temperature-controlled distribution align with ISTA 7E seasonal profile validation requirements. The Kanto region's pharmaceutical manufacturing concentration around Tokyo sustains premium-tier demand for validated reusable thermal packaging systems.
PUR Shippers Market Competitive Landscape
Integrated manufacturers with captive foam production and specialized validation service providers split the market between margin-capture and compliance-driven procurement. The competitive structure concentrates around three strategic archetypes: diversified packaging conglomerates with polymer chemistry capabilities, dedicated thermal packaging specialists with regulatory validation expertise, and regional foam converters serving cost-optimized segments. Dominant competitive moves include backward integration into polyurethane foam molding operations and strategic partnerships with third-party logistics operators for reusable asset network deployment.
Among North American-based providers, Sonoco Products exemplifies the diversified conglomerate archetype through integrated fiber and foam operations sustaining cost advantages across pharmaceutical and food segments. Pelican BioThermal occupies a position within the high-performance specialist tier, anchoring demand for reusable thermal container systems in cell therapy and gene therapy distribution. Cold Chain Technologies represents the validation-centric service model, competing through specialized compliance support for biologics manufacturers navigating FDA and EU regulatory requirements.
| Leading Market Players |
|---|
| Sonoco Products |
| Pelican BioThermal |
| Cold Chain Technologies |
| Chill-Pak |
| Polar Tech Industries |
| DS Smith Plastics |
| Sonoco ThermoSafe |
| Tempack Packaging Solutions |
| Lifoam Life Sciences |
| Others |
Value Network & Pricing Analysis
The Rotterdam-Frankfurt pharmaceutical freight corridor anchors cost dynamics across the PUR shipper landscape, with lane-specific validation requirements feeding price differentiation while MDI feedstock volatility compresses margins for non-integrated converters serving price-sensitive food distribution channels.
Pricing Analysis
Geographic price spreads between German pharmaceutical corridors and US Gulf Coast manufacturing widen during energy price spikes, with three-tier pricing structure across premium, standard, and economy levels separating validated reusable systems from single-use alternatives. Price differentiation hinges on ISTA 7E certification tier and captive foam production capability, with integrated manufacturers commanding premium positioning. Cost compression in the economy tier intensifies because EPS displacement by VIP composites forces converter repositioning. Food and beverage distributors exhibit highest price sensitivity; cell therapy manufacturers demonstrate lowest sensitivity due to payload value concentration.
Supply Chain Analysis
Tariff exposure between Germany and China for vacuum insulation panel substrates dominates supply chain risk assessment, with rigid polyurethane core production drawing from the US Gulf Coast, northwestern Europe, and Maharashtra's emerging converter belt. MDI and polyol feedstocks rest on crude oil and natural gas benchmarks, while VIP composites hinge on fumed silica and fiberglass substrate availability. Single-source vulnerability concentrates in German blowing agent formulation capacity. Distribution runs through pharmaceutical 3PL networks with RFID-enabled asset tracking infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among biopharma procurement teams consolidating supplier relationships around full-service thermal packaging partners, fragmenting the vendor base for mid-size converters lacking validation service capacity.
For Market Incumbents: Build regulatory validation moats through in-house ISTA 7E seasonal profile testing capability and backward integration into polyurethane foam molding operations. Threats from emerging Indian converters with CDSCO-aligned cost structures demand capacity addition in Bavaria's pharmaceutical corridor. Certification investment for EU F-Gas Regulation compliance serves as the primary defensive lever against reformulation cost shocks. For New Entrants and Emerging Players: Build out flexible shipper manufacturing capacity targeting US e-commerce grocery channels where return logistics economics favor single-use convenience. The most penetrable segment spans meal-kit subscription services requiring right-sized thermal packaging for variable last-mile delivery windows. Go-to-market execution centers on pilot programs with regional food distributors seeking 48-72 hour transit protection without pharmaceutical-grade validation overhead. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates seeking to divest non-core thermal packaging divisions lacking regulatory validation service integration. Long-term viability favors assets with captive polymer chemistry capabilities and established lane-specific qualification study capacity. Watch for inflection signals in EU CBAM implementation timelines favoring localized foam molding footprints over imported alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Molding | Captive MDI supply secures margin stability against feedstock volatility for German converters. |
| Regulatory Validation Service Expansion | ISTA 7E testing capability attracts biopharma procurement consolidation toward full-service partners. |
| VIP Composite Technology Licensing | R-30 thermal performance access enables CAR-T therapy distribution for Massachusetts gene therapy manufacturers. |
| Reusable Asset Network Partnership | RFID infrastructure deployment with 3PL operators reduces per-shipment cost for high-value biologics. |
| Next-Generation Blowing Agent Transition | Hydro-olefin formulation compliance with EU F-Gas Regulation avoids accelerated German national implementation penalties. |
Research Methodology
The analysis maps rigid shippers, flexible shippers, and custom cell therapy configurations, each validated through quality directors at biopharma manufacturers, thermal packaging procurement leads at CDMOs, and logistics engineering heads at pharmaceutical 3PLs. Primary interview data triangulates against FDA Drug Supply Chain Security Act guidance documents, EU Good Distribution Practice regulatory texts, customs trade flows for polyurethane foam board, and SEC filings from diversified packaging conglomerates. Bottom-up demand modeling across application segments converges with top-down supply capacity assessments from converter operations.
Assumptions held fixed include current EU F-Gas Regulation phasedown timelines and existing FDA serialization mandate compliance deadlines, while variables include crude oil price trajectories affecting MDI costs and carbon border adjustment mechanism implementation scope. Segmentation dimensions span product type, material chemistry, application vertical, and end-user procurement sophistication. CAGRs derive from regression analysis against pharmaceutical cold chain infrastructure investment patterns and biologics manufacturing capacity expansion across the analysis window. Forecast inputs incorporate gene therapy commercialization rates and meal-kit channel penetration metrics.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Indian converters with CDSCO-aligned validation capabilities would shift outcomes toward price compression in cost-optimized segments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Wooden Pallet Collars Market
Pallets Packaging
Pallet Pooling Market
Pallets Packaging
Empty Fruit Bunch Pallets Market
Pallets Packaging
Europe Lumber Pallet Market
Pallets Packaging
North America Lumber Pallet Market
Pallets Packaging
Spill Pallets Market
Pallets Packaging
Global Crates and Pallets Packaging Market
Pallets Packaging
Thermal Pallet Covers Market
Pallets Packaging
Corrugated Pallets Market
Pallets Packaging
Pallets Market
Pallets Packaging
Pallet Shippers Market
Pallets Packaging
Mexico Pallets Market
Pallets Packaging
Palletizer Market
Pallets Packaging
Global Pallet Racking System Market
Pallets Packaging
Foldable Pallet Container Market
Pallets Packaging
Pallet Displays Market