
 Foldable Plastic Pallet Boxes Market | 2026-2036
Foldable Plastic Pallet Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Foldable Plastic Pallet Boxes Market Foresight
Multi-source procurement among large-format retailers is recalibrating vendor selection criteria for foldable plastic pallet boxes. Schoeller Allibert leverages its European manufacturing footprint to sustain long-term pooling contracts with grocery chains. Rehrig Pacific Company anchors North American supply through proprietary resin formulations and regional mold operations. CABKA Group GmbH competes on recycled-content integration, differentiating its product line for sustainability-focused buyers.
Foldable plastic pallet boxes are injection-molded or twin-sheet thermoformed containers, typically rated for dynamic loads exceeding 500 kg and designed to collapse to one-third of assembled height for empty return transport. Their primary purpose is to protect unitized goods through multi-leg supply chains while minimizing backhaul volume and storage footprint. Collapsible boxes dominate warehousing deployments due to established aftermarket service networks and repair ecosystems. Nestable containers represent the fastest-growing material category among e-commerce fulfillment operators seeking floor-space efficiency in last-mile sortation hubs. HDPE formulations retain margin concentration because resin recyclability aligns with retailer circularity mandates and reduces total cost of ownership across rotation cycles.
FDA food-contact regulations and EU REACH compliance frameworks govern resin additives and migration limits for pharmaceutical and food-grade pallet box applications. ISO 8611 testing standards for pallet load performance create baseline entry barriers that filter out low-durability injection molders. Stakeholders must monitor how California SB 54 extended producer responsibility rules and emerging state-level packaging taxes reshape total cost models for single-use versus returnable packaging investments.
Market Dynamics
Third-party logistics providers are consolidating empty-haul reduction into core procurement criteria, compressing vendor selection around pooling-system compatibility and reverse-logistics integration rather than unit purchase price.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Reuse mandates across member states favor durable returnable containers over single-use corrugated alternatives in automotive and grocery supply chains.
- Automotive just-in-sequence delivery:German OEMs and tiered supplier networks operate dense pooling systems that standardize foldable pallet box specifications across multi-tier supply bases.
- HDPE resin recyclability:Retailer circularity mandates and total cost-of-ownership calculations across rotation cycles reinforce specification of recyclable formulations.
Market Restraints
- Petrochemical feedstock volatility:HDPE and polypropylene resin prices fluctuate with crude oil and natural gas derivatives, compressing margin predictability for molders.
- Injection molding asset concentration:High-volume production capacity clusters in Germany, Belgium, and the Netherlands, creating geographic supply risk for distant buyers.
- Corrugated cardboard substitution:Single-use fiber-based containers retain cost advantage for low-rotation, one-way shipments in price-sensitive segments.
Strategic Opportunities
- California SB 54 implementation:Extended producer responsibility rules for packaging reshape total cost models toward returnable investments in the US western states.
- E-commerce sortation hub deployment:Nestable container configurations address floor-space constraints in last-mile fulfillment centers experiencing volume surges.
- Pharmaceutical cold-chain integration:Insulated foldable pallet box variants capture unitized vaccine and biologics distribution requiring temperature integrity.
Industry Challenges
- ISO 8611 testing compliance:Pallet load performance certification timelines extend product development cycles and filter out undercapitalized molders.
- Legacy warehouse management system integration:RFID-tracked returnable container pools require middleware adaptation with existing inventory platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foldable Plastic Pallet Boxes Market |
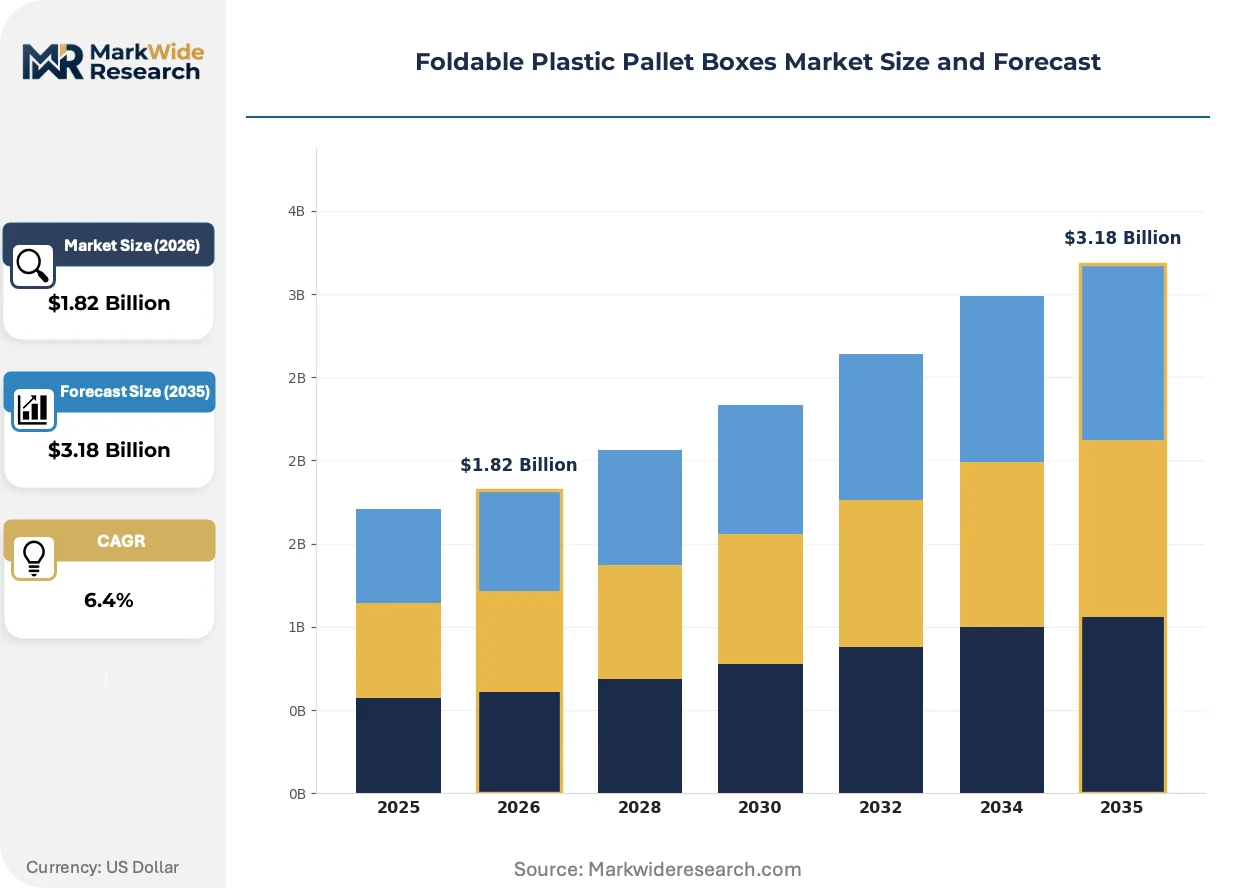
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collapsible Boxes, Nestable Containers, Stackable Crates, Rigid Pallet Boxes, Modular Units Material: HDPE, Polypropylene, PVC, Composite Polymers, Bioplastics Application: Warehousing, Distribution Centers, Cold Chain Logistics, E-commerce Fulfillment, Automotive Parts Handling End User: Retail Chains, Third-Party Logistics Providers, Food & Beverage Companies, Pharmaceutical Distributors, Electronics Manufacturers |
| Companies Covered | IFCO Systems, Rehrig Pacific Company, Schoeller Allibert, CABKA Group GmbH, Brambles Limited, ORBIS Corporation, Craemer Group, DS Smith, CHEP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foldable Plastic Pallet Boxes Market Shifts & Advancements
Material science advances and regulatory pressure on packaging waste are converging to reshape container specifications, pooling economics, and buyer-vendor contracting structures across supply chain tiers.
Twin-sheet thermoforming is absorbing structural load requirements previously met by injection-molded alternatives, enabling lighter wall thicknesses without sacrificing dynamic load ratings above 500 kg. European grocery chains are adopting these configurations for fresh produce distribution, reducing per-unit resin consumption and transport fuel burn across rotation cycles.
REACH compliance frameworks are tightening migration limits on resin additives for food-contact and pharmaceutical applications, forcing compound reformulation and additive substitution. EFSA evaluations of specific plasticizers are accelerating specification shifts among suppliers serving dairy and meat processing sectors, with German retailers leading compliance verification demands.
Buyer concentration among large-format retailers is compressing vendor negotiation leverage and standardizing technical specifications across national boundaries. Pooling operators are displacing direct purchase models in automotive and grocery verticals, with contract structures emphasizing per-trip pricing and maintenance-included service bundles rather than capital expenditure.
Foldable Plastic Pallet Boxes Market Segmentation
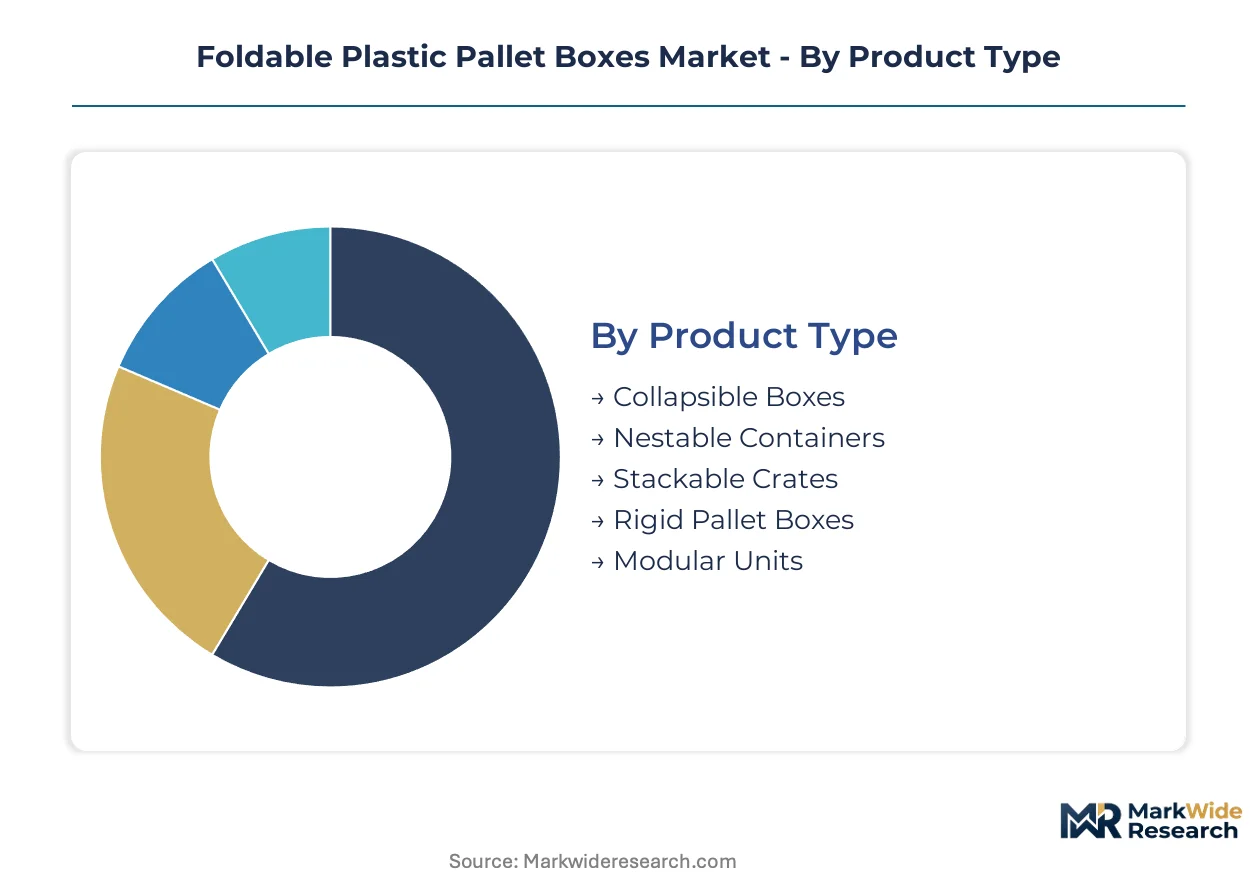
Container geometry, resin formulation, and operational use case dictate procurement specifications across supply chain tiers. Buyers segment selections by load rating, collapse ratio, and rotation cycle economics rather than unit purchase price alone.
Product Type:
Volume deployment favors established collapsible configurations, while premium positioning attaches to specialized geometries serving high-velocity fulfillment.
- Collapsible Boxes:Injection-molded or twin-sheet thermoformed designs collapse to one-third of assembled height for empty return transport. German automotive OEMs specify these for just-in-sequence parts delivery through dense pooling networks.
- Nestable Containers:Tapered-wall designs stack inside one another when empty, reducing backhaul cube by up to 75 percent. E-commerce fulfillment operators in the Netherlands and Belgium deploy these for last-mile sortation hub efficiency.
- Stackable Crates:Fixed-height containers with interlocking feet for vertical stability. Food & beverage distributors favor these for stable palletization of fresh produce loads.
- Rigid Pallet Boxes:Non-collapsible structural designs rated for dynamic loads exceeding 800 kg. Heavy manufacturing and chemical processing applications specify these for durability under harsh handling.
- Modular Units:Interchangeable panel systems allowing footprint reconfiguration. Contract packaging services use these for flexible SKU accommodation across seasonal demand swings.
Mature deployment sits with collapsible boxes. Newer deployment is concentrated in nestable containers.
Material:
Resin selection tracks circularity mandates, temperature requirements, and total cost-of-ownership calculations across multi-year rotation cycles.
- HDPE:High-density polyethylene formulations dominate procurement due to established recycling infrastructure and FDA food-contact compliance. Retailer circularity mandates in France and Italy reinforce HDPE specification for closed-loop pooling.
- Polypropylene:Lighter weight alternative with superior impact resistance at low temperatures. Cold chain logistics operators in Spain and Poland specify these for pharmaceutical distribution.
- PVC:Rigid formulations with chemical resistance for industrial applications. Limited food-contact penetration due to migration limit concerns under REACH frameworks.
- Composite Polymers:Engineered blends combining stiffness with reduced wall thickness. Premium positioning for export shipment applications requiring weight minimization.
- Bioplastics:Bio-based or biodegradable alternatives responding to corporate sustainability commitments. Pilot deployments in Nordic grocery chains testing end-of-life composting pathways.
Cost-sensitive procurement anchors on HDPE. Premium positioning clusters with composite polymers.
Application:
Operational environment determines structural specifications, with temperature control and throughput velocity driving divergent technical requirements.
- Warehousing:Static storage applications prioritize collapse ratio and stack stability for empty container management. Third-party logistics providers in Germany consolidate these specifications across multi-client operations.
- Distribution Centers:High-velocity cross-dock environments demand rapid assembly and RFID-trackable pooling integration. Benelux grocery distribution networks lead standardization here.
- Cold Chain Logistics:Temperature-controlled transport requires resin formulations maintaining impact resistance at sub-zero conditions. Pharmaceutical distributors in Switzerland and Austria specify insulated variants for biologics.
- E-commerce Fulfillment:Last-mile sortation hubs prioritize nestability for floor-space efficiency during volume surges. Polish and Czech fulfillment centers are expanding fastest.
- Automotive Parts Handling:Just-in-sequence delivery mandates precise dimensional tolerances and pooling system interoperability. Tiered supplier networks in Baden-Württemberg and Bavaria drive specification.
Established volume concentrates in warehousing. Steepest expansion trajectory appears in e-commerce fulfillment.
End User:
Buyer concentration among large-format retailers compresses vendor negotiation leverage and standardizes technical specifications across national markets.
- Retail Chains:Grocery and general merchandise operators mandate returnable packaging for fresh and ambient goods. French and German supermarket groups lead pooling system consolidation.
- Third-Party Logistics Providers:Asset-light operators procure through service contracts emphasizing per-trip pricing and maintenance inclusion. DHL Supply Chain and Kuehne+Nagel operations in the Netherlands set procurement benchmarks.
- Food & Beverage Companies:Processors and distributors require FDA and EFSA compliance for direct food contact. Dairy and meat sectors in Denmark and Ireland drive additive reformulation demands.
- Pharmaceutical Distributors:Cold-chain integrity and batch traceability requirements specify insulated and RFID-enabled variants. Swiss and German wholesale distributors maintain tightest specifications.
- Electronics Manufacturers:Electrostatic discharge protection and cleanroom compatibility for component transport. Semiconductor fabrication suppliers in Saxony and Flanders specify these requirements.
Procurement scale concentrates with retail chains. Specification complexity peaks with pharmaceutical distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock clusters in the Netherlands and Belgium anchor European resin supply for injection molders serving automotive and grocery pooling networks. This feedstock proximity shapes regional manufacturing gravity and cross-border logistics integration.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria operate dense pooling systems for just-in-sequence parts delivery. The KBA enforces transport packaging standards that favor durable returnable containers over single-use alternatives. Stuttgart's tiered supplier networks standardize foldable pallet box specifications across multi-tier supply bases.
United States
Third-party logistics providers in the Great Lakes region consolidate procurement around reverse-logistics compatibility and empty-haul reduction. California SB 54 extended producer responsibility rules reshape total cost models toward returnable packaging investments in western states. Chicago distribution hubs integrate RFID-tracked container pools with legacy warehouse management systems.
Netherlands
Benelux grocery distribution networks lead standardization of rapid-assembly containers for high-velocity cross-dock environments. ECHA REACH compliance frameworks govern resin additive migration limits for food-contact applications. Rotterdam's port-centric logistics operators optimize backhaul volume through collapsed container return cycles.
China
E-commerce fulfillment operators in the Yangtze River Delta deploy nestable containers for floor-space efficiency during volume surges. MIIT circular economy directives promote recyclable HDPE formulations for closed-loop packaging systems. Shanghai's last-mile sortation hubs represent the fastest-expanding material category deployment in Asia-Pacific.
France
Retailer circularity mandates in Île-de-France reinforce HDPE specification for closed-loop pooling of fresh and ambient goods. EFSA evaluations of plasticizer additives accelerate specification shifts among dairy and meat processing suppliers. Paris supermarket groups consolidate vendor negotiation leverage through standardized technical specifications.
Foldable Plastic Pallet Boxes Market Competitive Landscape
Global majors compete with regional champions across pooling-system integration and resin formulation expertise. The vendor base clusters around three strategic archetypes: European molders with long-term automotive contracts, North American operators with proprietary material science, and sustainability-focused competitors leveraging recycled-content integration. Consolidation pressure concentrates among injection molding asset holders in Germany, Belgium, and the Netherlands. Dominant competitive moves include backward integration into resin compounding and geographic expansion through service-based pooling contracts rather than equipment sales.
Within the European molder tier, Schoeller Allibert and CABKA Group GmbH represent contrasting archetypes of pooling-system incumbency versus recycled-content differentiation. Rehrig Pacific Company anchors North American supply through regional manufacturing presence. These three exemplify how vendor selection criteria now prioritize reverse-logistics integration and circularity mandates over unit purchase price alone.
| Leading Market Players |
|---|
| IFCO Systems |
| Rehrig Pacific Company |
| Schoeller Allibert |
| CABKA Group GmbH |
| Brambles Limited |
| ORBIS Corporation |
| Craemer Group |
| DS Smith |
| CHEP |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up injection molders in Germany and the Netherlands enforce pricing discipline through captive resin compounding and long-term automotive pooling contracts, compressing margin visibility for independent operators lacking backward integration into petrochemical feedstocks.
Pricing Analysis
Warranty and refurbishment bundling separates premium-tier vendors from unbundled transactional sellers in the foldable plastic pallet boxes market. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 8611 certification status and per-trip maintenance inclusion. Cost compression in economy-grade HDPE formulations is intensifying because corrugated cardboard retains substitution threat for low-rotation applications. Third-party logistics providers demonstrate highest price sensitivity due to asset-light procurement models, while pharmaceutical distributors accept premium positioning for cold-chain-validated variants.
Supply Chain Analysis
Reverse-logistics flows for collapsed container returns concentrate refurbishment and redeployment economics in Benelux pooling hubs. Manufacturing capacity clusters in Germany, Belgium, and the Netherlands, drawing from Rotterdam-Antwerp petrochemical corridors. Raw material dependencies center on HDPE resin, polypropylene formulations, and recycled-content feedstocks. Single-source vulnerability runs through concentrated injection molding asset ownership. Distribution runs through automotive OEM captive pools and grocery chain consolidation networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is accelerating as EU Packaging and Packaging Waste Regulation reuse mandates force sub-scale molders out of compliance reach.
For Market Incumbents: Hedge against corrugated substitution by deepening backward integration into resin compounding and securing long-term pooling contracts with German automotive OEMs. Prioritize ISO 8611 certification investment to filter out undercapitalized competitors. Capture margin protection through proprietary twin-sheet thermoforming technology serving European grocery chains. For New Entrants and Emerging Players: Capture white-space opportunity in pharmaceutical cold-chain insulated variants for Swiss and Austrian biologics distributors. Target e-commerce nestable container deployment in Polish and Czech fulfillment centers where floor-space constraints drive specification. Pursue sustainability-focused buyers through recycled-content integration exceeding CABKA Group benchmarks. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap molders with established automotive contracts in Baden-Württemberg and Bavaria, where KBA transport packaging standards create regulatory moats. Long-term viability hinges on pooling-system interoperability and RFID-tracked asset management capabilities. Monitor California SB 54 implementation pace as inflection indicator for US western state returnable packaging investment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive HDPE supply secures margin stability against Rotterdam-Antwerp petrochemical volatility. |
| RFID-Enabled Pooling System Deployment | DHL Supply Chain and Kuehne+Nagel middleware integration demands drive vendor selection criteria. |
| Twin-Sheet Thermoforming Capacity Expansion | Lighter wall thicknesses reduce fuel burn across European grocery distribution rotation cycles. |
| Pharmaceutical Cold-Chain Variant Development | Insulated configurations capture Swissmedic-regulated vaccine and biologics distribution requirements. |
| Recycled-Content Integration Above 50% | Retailer circularity mandates in France and Italy favor closed-loop HDPE pooling economics. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this foldable plastic pallet boxes market assessment. Primary interviews with logistics procurement directors, automotive tier supplier packaging engineers, grocery chain sustainability officers, and injection molding plant managers combined with ECHA REACH documentation, EU Packaging and Packaging Waste Regulation impact assessments, and KBA transport standards. Bottom-up unit deployment estimates triangulated against top-down resin consumption patterns.
Data-stream reconciliation across shipment volumes, pooling fleet sizes, and rotation cycle economics informed the analytical framework. Segmentation dimensions modeled include container geometry, resin formulation, application environment, and end-user procurement structure. CAGRs derived from weighted average of historical deployment trajectories and regulatory-driven substitution elasticities. Forecast inputs incorporated automotive production schedules and e-commerce fulfillment center expansion pipelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical feedstock volatility and corrugated cardboard price competitiveness. Practitioners should monitor EU member state reuse mandate enforcement intensity and California SB 54 producer responsibility rulemaking for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Europe Lumber Pallet Market
Pallets Packaging
Middle East Pallets Market
Pallets Packaging
Composite Pallet Market
Pallets Packaging
Stringer Pallets Market
Pallets Packaging
Conventional Palletizers Market
Pallets Packaging
Wire Cage Pallet Collar Market
Pallets Packaging
Latin America Pallet Market
Pallets Packaging
Middle East and Africa Lumber Pallet Market
Pallets Packaging
Block Pallets Market
Pallets Packaging
Europe Palletizer Market
Pallets Packaging
Pallet Pooling Market
Pallets Packaging
Pallet Tines Market
Pallets Packaging
Asia-Pacific Lumber Pallet Market
Pallets Packaging
Global Pallet Racking System Market
Pallets Packaging
Corrugated Pallet Containers Market
Pallets Packaging
Mexico Pallets Market