
 Japan Pallets Market | 2026-2036
Japan Pallets Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Pallets Market Insights
Japan's domestic manufacturing base is reconfiguring pallet supply chains to reduce import dependency on raw timber. Wintex Co., Ltd. leverages automated repair systems to extend pallet lifecycle in high-turnover logistics environments. Yamamuro Wood Industry Co., Ltd. anchors traditional wooden pallet production through controlled forestry partnerships in Hokkaido. KYORAKU Co., Ltd. specializes in plastic pallet molding for pharmaceutical cold-chain compliance.
A pallet is a portable, rigid platform with a top deck and bottom deck, typically constructed with stringers or blocks to enable forklift entry from multiple sides, designed to consolidate goods into unit loads for efficient handling, storage, and transport. Wooden pallets dominate Japan's installed base due to lower upfront cost and established repair infrastructure, though plastic variants gain traction in hygiene-sensitive applications. Nestable designs reduce empty-return shipping volume for distribution centers operating tight freight budgets. Metal pallets occupy premium niches in automotive OEMs requiring extreme load ratings and fire resistance.
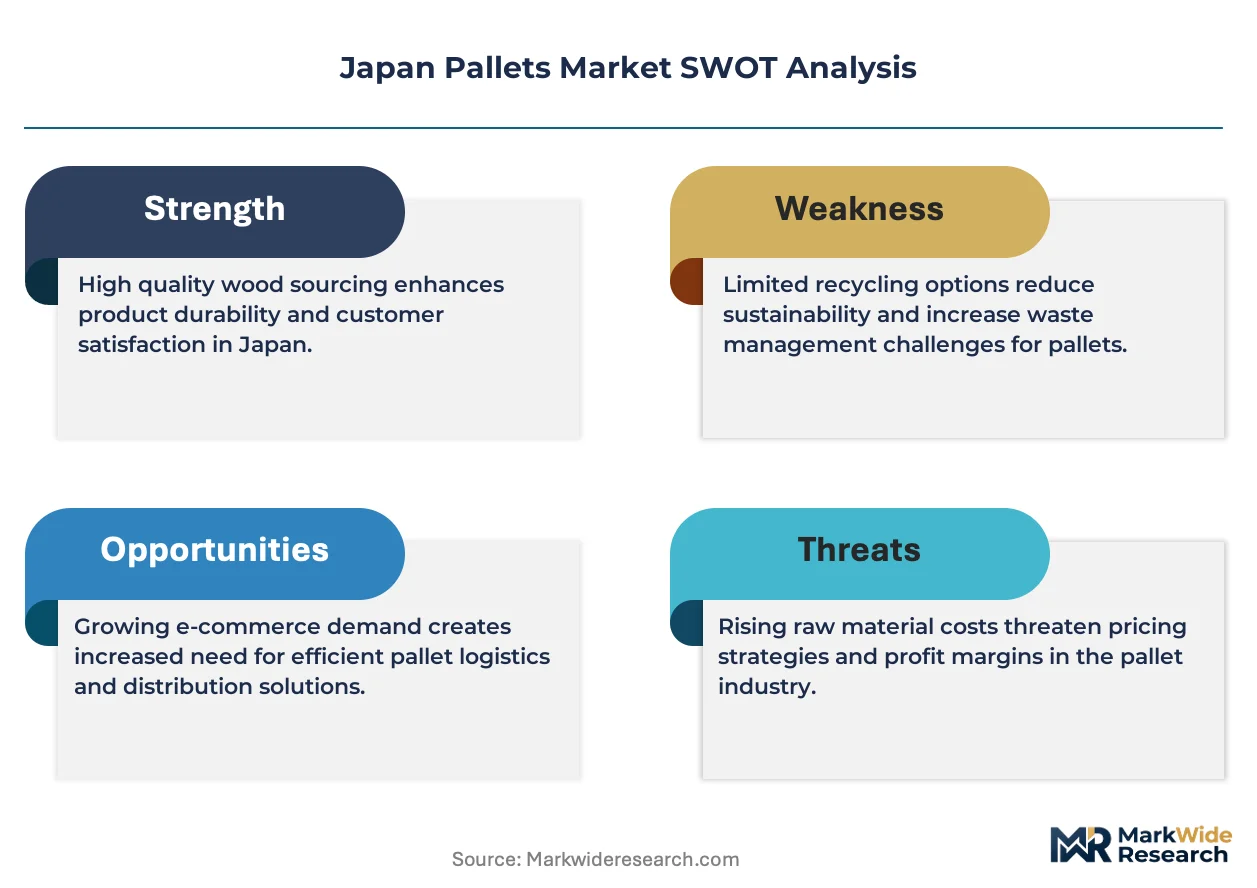
METI enforces JIS standards for pallet dimensions and load ratings, while the EPA's waste management frameworks push recyclability mandates that favor plastic and composite materials with traceable recovery pathways. The Ministry of Health, Labour and Welfare imposes sanitation protocols on pallets contacting food and pharmaceutical products, effectively filtering non-compliant suppliers from regulated supply chains. Stakeholders must weigh material conversion costs against tightening reuse quotas and regional logistics consolidation trends.
Market Dynamics
METI's circular economy guidelines for packaging reuse are compressing pallet replacement cycles and forcing material recovery obligations across Japan's logistics networks. Pharmaceutical distribution standardization and Kanto corridor consolidation amplify structural pressure on supply chain configurations.
Growth Catalysts
- Pharmaceutical cold-chain expansion:Temperature-sensitive drug distribution networks across Japan are mandating hygienic pallet specifications that favor plastic and composite materials with traceable sanitation protocols.
- METI circular economy mandates:The ministry's tightening material recovery obligations are accelerating closed-loop rental systems and automated repair infrastructure investments.
- Kanto industrial corridor concentration:Logistics consolidation across Tokyo, Kanagawa, and Saitama prefectures is driving standardized pallet pooling programs to reduce empty-return freight costs.
Market Restraints
- Timber import dependency:Japan's domestic forestry cannot satisfy raw material requirements for traditional wooden pallet production, exposing manufacturers to yen-denominated lumber price volatility.
- Plastic resin cost sensitivity:Oil-indexed polymer feedstock prices compress margins for injection-molded pallet specialists serving pharmaceutical and food-contact applications.
- JIS standardization friction:Dimensional and load-rating compliance requirements create certification bottlenecks that filter smaller repair operators from formal supply chains.
Strategic Opportunities
- Pharmaceutical serialization integration:Track-and-trace mandates for drug distribution create demand for RFID-embedded pallets that bridge physical logistics with digital supply chain visibility.
- Hokkaido controlled forestry partnerships:Vertical integration into sustainable timber sourcing offers domestic wooden pallet producers insulation from import price shocks and circular economy credentialing.
- Nestable design penetration:Empty-return volume reduction technology remains underdeployed in Japan's mid-tier distribution centers, presenting white space for specialized engineering services.
Industry Challenges
- Repair technician scarcity:Automated sorting and refurbishment systems require skilled operators that Japan's logistics sector struggles to recruit and retain against manufacturing competition.
- Legacy wooden pallet infrastructure:Decades of sunk investment in stringer-based designs and repair tooling creates switching friction for operators evaluating plastic or composite alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Pallets Market |
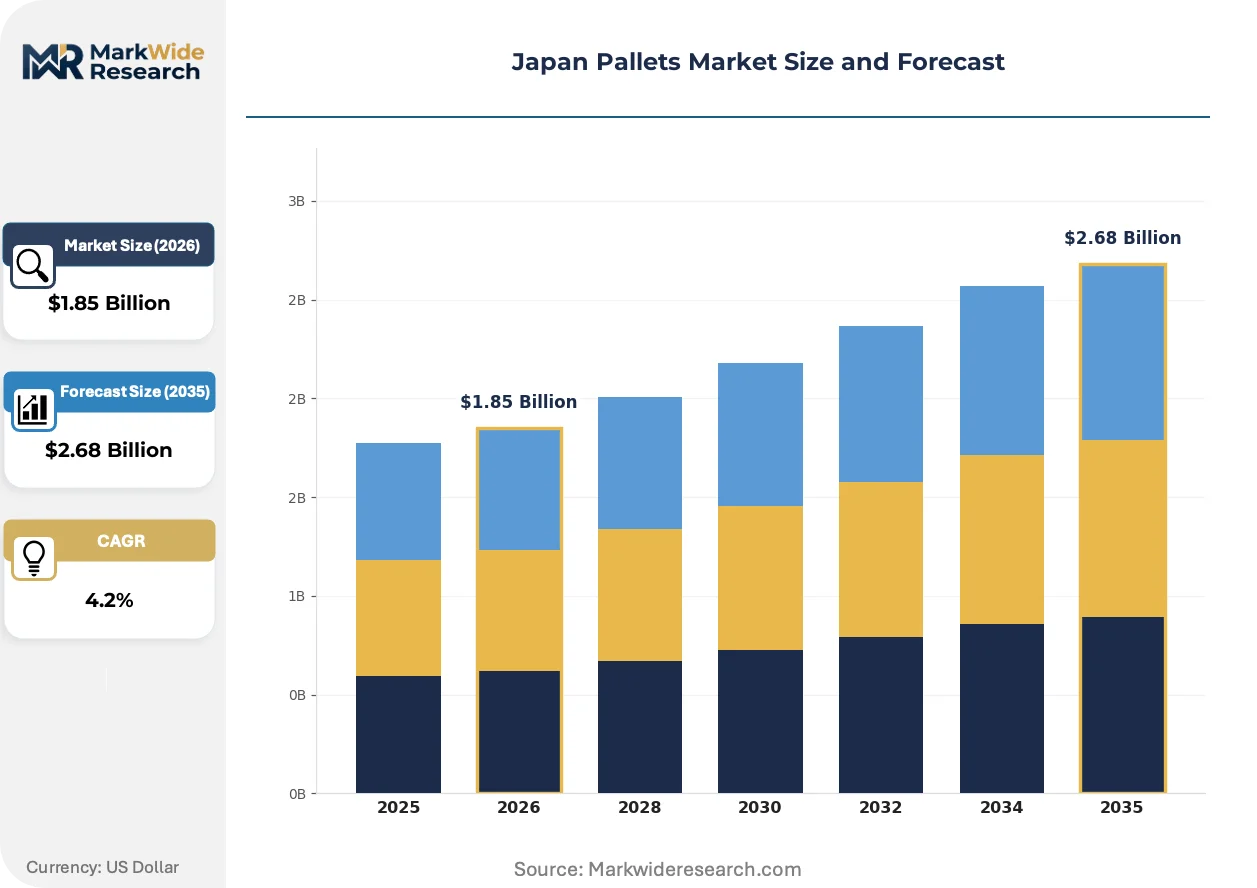
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.68 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wooden, Plastic, Metal, Paperboard, Composite Design Style: Block, Stringer, Double-Face, Reversible, Nestable Application Sector: Manufacturing, Logistics, Agriculture, Construction, Pharmaceuticals End User Category: Warehousing, Distribution Centers, Retail Chains, Food Processing, Automotive OEMs |
| Companies Covered | Wintex Co., Ltd., Yamamuro Wood Industry Co., Ltd., Kiefel Co., Ltd., Fukui Environmental Plastics Co., Ltd., Partners Corporation Co., Ltd., KYORAKU Co., Ltd., Higashiosaka Steel Co., Ltd., iRop Co., Ltd., Sanko Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Pallets Market Trends and Innovations
Material science advances and regulatory digitization are compressing traditional pallet lifecycles while enabling new service models that merge physical handling equipment with data infrastructure.
Automated optical inspection systems for pallet damage assessment are rendering obsolete manual sorting operations that dominated Japanese repair depots for decades. Pharmaceutical distributors and chilled-food logistics operators are adopting these systems fastest to satisfy Ministry of Health, Labour and Welfare sanitation documentation requirements. The technology is compressing repair turnaround times from days to hours while reducing labor dependency in an aging workforce environment.
METI's waste management frameworks now mandate traceable recovery pathways for packaging materials, forcing pallet operators to document cradle-to-grave material flows. This regulatory pressure is accelerating blockchain-integrated rental platforms that authenticate reuse cycles for compliance auditing. Food and pharmaceutical supply chains bear the heaviest documentation burden, filtering informal repair networks from regulated tender processes.
Consolidated procurement by third-party logistics operators is displacing fragmented buyer-seller relationships that historically characterized Japan's pallet market. Major distribution centers now negotiate multi-year pooling contracts with standardized service-level agreements rather than spot purchasing. The Kanto industrial corridor exhibits this behavioral shift most prominently, where Tokyo-based 3PLs are absorbing pallet management functions previously handled by individual manufacturers.
Japan Pallets Market Segmentation
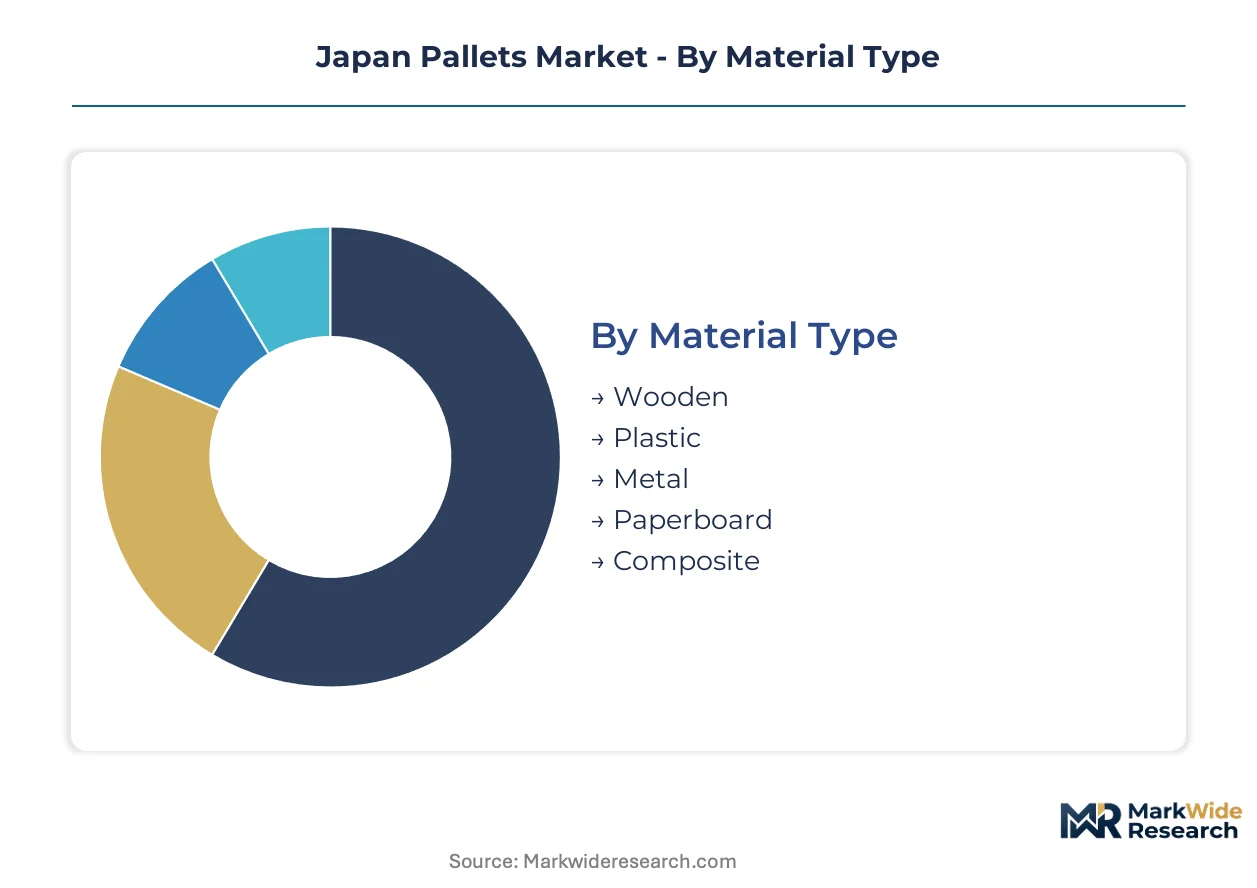
Japan's pallet market segments reveal divergent material preferences across regulatory environments and operational intensities. Pharmaceutical cold-chain mandates and METI circular economy requirements are compressing traditional material hierarchies while elevating hygiene and traceability specifications.
Material Type:
Mature wooden pallet infrastructure dominates installed base volumes while emerging materials capture premium application niches.
- Wooden:Constructed from softwood or hardwood lumber with stringer or block configurations, wooden pallets retain lowest upfront cost per unit. Manufacturing corridors across Aichi and Osaka prefectures concentrate demand where repair infrastructure density offsets higher lifecycle replacement rates.
- Plastic:Injection-molded or thermoformed from HDPE or PP resins, plastic pallets deliver consistent dimensional stability and moisture resistance. Pharmaceutical distribution networks in Tokyo and Kanagawa mandate these specifications for Ministry of Health, Labour and Welfare sanitation compliance.
- Metal:Fabricated from steel or aluminum with welded frame construction, metal pallets withstand extreme load ratings and fire exposure. Automotive OEMs in Toyota City and Yokohama anchor this segment's concentrated demand.
- Paperboard:Engineered from corrugated fiberboard or honeycomb structures for single-use export applications. Lightweight characteristics reduce air freight surcharges for electronics exporters shipping from Narita corridor.
- Composite:Hybrid constructions blending wood fibers with polymer binders or recycled plastics. Emerging adoption in closed-loop rental systems seeking METI-recognized circular economy credentials.
Wooden pallets retain volume leadership; plastic pallets hold the steepest expansion curve.
Design Style:
Cost tier stratification separates entry-level stringer designs from premium reversible configurations engineered for automated handling systems.
- Block:Four-way entry via cubic blocks at corners and center, enabling forklift access from all sides. High-throughput distribution centers in Saitama Prefecture specify block designs for cross-docking efficiency.
- Stringer:Two-way or partial four-way entry via parallel longitudinal boards, representing Japan's most entrenched design legacy. Lower replacement costs sustain dominance among small and mid-tier manufacturers.
- Double-Face:Deck boards on both top and bottom surfaces distribute loads evenly for rack storage applications. Cold storage facilities in Chiba Prefecture favor this reinforcement for stacked inventory stability.
- Reversible:Identical deck construction on both faces permits inversion without functional degradation. Premium pharmaceutical and food-grade applications absorb higher unit costs for operational flexibility.
- Nestable:Tapered leg or frame geometry allows empty pallets to stack within each other, reducing return freight volume by up to 60 percent. Underdeployed among mid-tier 3PLs despite Kanto corridor consolidation pressures.
Stringer designs retain volume leadership; nestable configurations hold the steepest expansion curve.
Application Sector:
Volume concentration in manufacturing and logistics contrasts with margin premium capture in pharmaceutical and agricultural cold chains.
- Manufacturing:Assembly line feed and finished goods staging across automotive, electronics, and machinery producers. Just-in-time delivery requirements in Toyota and Hamamatsu production clusters standardize pallet specifications.
- Logistics:Third-party operator pooling and freight consolidation across multimodal networks. Tokyo Bay port-centric 3PLs are absorbing pallet management functions from individual shippers.
- Agriculture:Fresh produce harvesting and chilled transport from Hokkaido and Kyushu growing regions. Seasonal demand volatility complicates rental pool utilization planning.
- Construction:Heavy material handling for cement, tile, and prefabricated component distribution. Load rating requirements exceed standard specifications, filtering toward metal and reinforced plastic alternatives.
- Pharmaceuticals:Temperature-controlled drug distribution with serialization track-and-trace integration. PMDA distribution regulations and Ministry of Health, Labour and Welfare sanitation protocols mandate hygienic materials with documented cleaning cycles.
Manufacturing retains volume leadership; pharmaceuticals holds the steepest expansion curve.
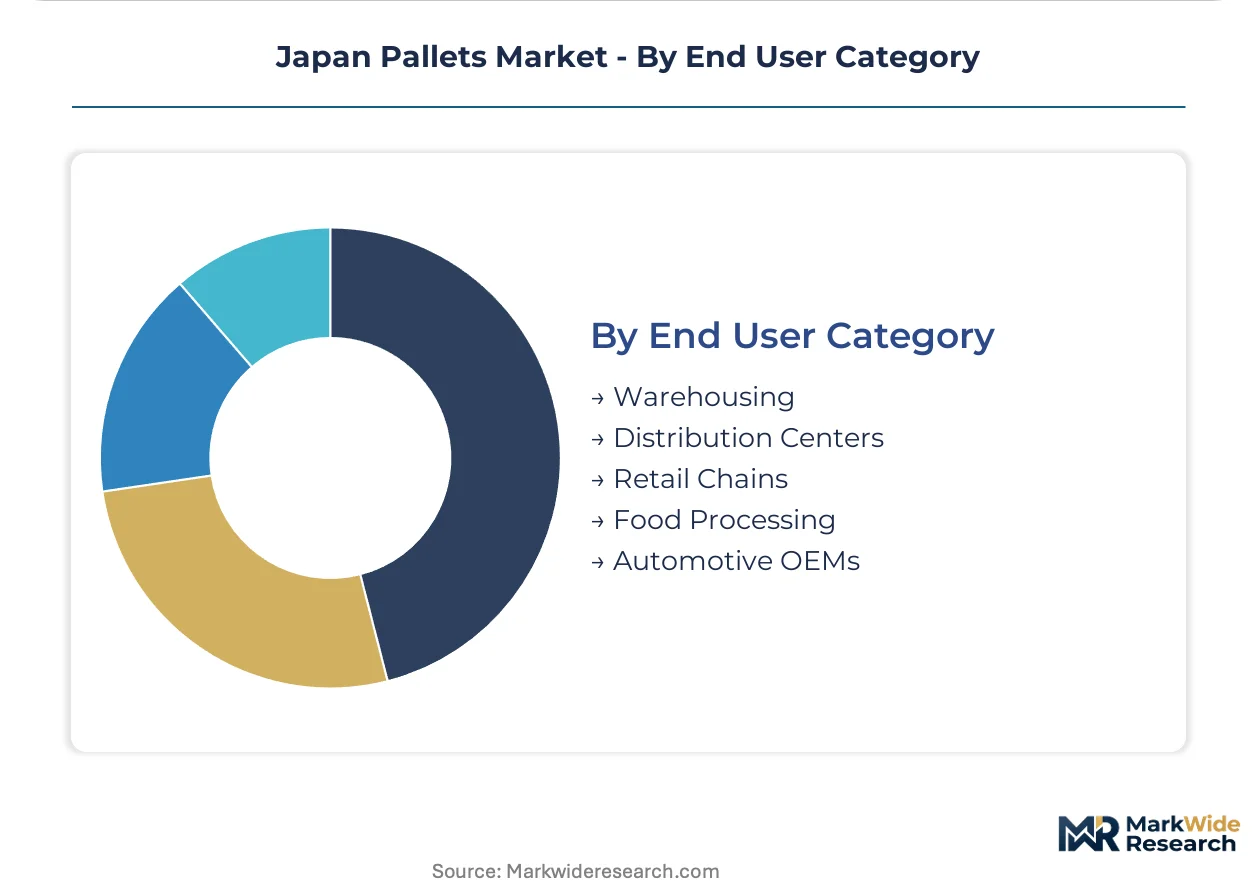
End User Category:
Customer type differentiation separates asset-owning manufacturers from service-oriented rental subscribers.
- Warehousing:Long-term storage operations with static inventory positioning. Racking compatibility and fire safety ratings drive specification priorities in Osaka and Nagoya distribution hubs.
- Distribution Centers:High-velocity cross-docking and sortation facilities with rapid turnover. Kanto corridor consolidation is standardizing pooling contracts with multi-year service-level agreements.
- Retail Chains:Store delivery and backroom inventory management across convenience and supermarket networks. Uniformity requirements favor rental subscriptions over fragmented ownership.
- Food Processing:Raw material intake and finished goods dispatch with HACCP sanitation protocols. Washdown-compatible plastic designs displace wooden alternatives under tightening METI guidance.
- Automotive OEMs:Inbound parts sequencing and outbound vehicle component logistics. Extreme load ratings and dimensional precision requirements sustain metal pallet penetration.
Distribution centers retain volume leadership; food processing holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pallet manufacturing clusters concentrate in Japan's industrial heartland, with supply-side density highest along the Pacific coastal belt from Tokyo to Nagoya. Regional specialization reflects divergent end-use demands, material access, and logistics infrastructure maturity.
Kanto
Pharmaceutical distribution networks and third-party logistics operators drive premium pallet specifications across Tokyo, Kanagawa, and Saitama prefectures. METI circular economy guidelines compress replacement cycles and mandate traceable recovery pathways for packaging materials. The Tokyo Bay port cluster anchors standardized pooling contracts that absorb pallet management from individual manufacturers.
Kansai
Automotive OEMs and electronics manufacturers sustain heavy-duty pallet demand across Osaka, Kyoto, and Hyogo prefectures. JIS dimensional standards enforce compliance bottlenecks that filter smaller repair operators from formal supply chains. The Osaka-Kobe logistics corridor exhibits consolidated procurement patterns as major 3PLs negotiate multi-year service agreements.
Chubu
Toyota City's automotive production cluster generates extreme load-rating requirements that sustain metal pallet penetration in Aichi, Gifu, and Mie prefectures. Ministry of Health, Labour and Welfare sanitation protocols filter non-compliant suppliers from food-contact and pharmaceutical adjacent operations. The Nagoya port hinterland concentrates just-in-time delivery infrastructure standardizing pallet specifications.
Hokkaido
Controlled forestry partnerships anchor domestic timber sourcing for wooden pallet producers seeking insulation from import price volatility. The prefecture's sustainable timber credentials align with METI-recognized circular economy credentialing requirements. Sapporo-based distribution networks feed agricultural cold chains with seasonal demand volatility complicating rental pool planning.
Kyushu
Electronics exporters and agricultural producers generate divergent pallet specifications across Fukuoka, Kumamoto, and Kagoshima prefectures. Narita corridor air freight connections favor lightweight paperboard designs for electronics shipments. Regional repair infrastructure density lags behind Honshu, creating service gaps for mid-tier distribution operators.
Japan Pallets Market Competitive Landscape
Traditional wood specialists and polymer molders split the market along material lines, with rental system operators occupying an emerging service tier. The vendor base clusters around three strategic archetypes: integrated forestry-to-fabrication operators, injection-molding specialists serving hygiene-sensitive applications, and automated repair service providers extending asset lifecycles. Competitive intensity centers on backward integration into raw material sourcing and technology licensing for optical inspection systems.
Within the wood-processing tier, Yamamuro Wood Industry Co., Ltd. exemplifies traditional fabrication anchored in controlled forestry partnerships. KYORAKU Co., Ltd. occupies a position among polymer specialists targeting pharmaceutical cold-chain compliance. Wintex Co., Ltd. represents the automated repair archetype with service infrastructure designed for high-turnover logistics environments. These three companies illustrate divergent strategic responses to METI's tightening material recovery obligations and JIS standardization pressures.
| Leading Market Players |
|---|
| Wintex Co., Ltd. |
| Yamamuro Wood Industry Co., Ltd. |
| Kiefel Co., Ltd. |
| Fukui Environmental Plastics Co., Ltd. |
| Partners Corporation Co., Ltd. |
| KYORAKU Co., Ltd. |
| Higashiosaka Steel Co., Ltd. |
| iRop Co., Ltd. |
| Sanko Corporation |
| Others |
Pricing and Supply Chain Analysis
Yen-denominated lumber price volatility determines both tier spreads between wooden and plastic pallet specifications and supply chain shape across Japan's logistics networks. METI circular economy mandates compress replacement cycles while forcing material recovery investments that widen cost differentials between compliant and non-compliant suppliers.
Pricing Analysis
METI's material recovery obligations dictate the pricing tier structure across Japan's pallet market. Three-tier pricing separates pharmaceutical-grade plastic specifications from standard wooden block designs and economy stringer configurations used in general manufacturing. Price differentiation rests on JIS certification level and volume scale in multi-year pooling contracts. Cost compression in the wooden tier is intensifying because import timber exposure feeds yen volatility into raw material costs. Small and mid-tier manufacturers exhibit highest price sensitivity, while pharmaceutical distributors absorb premium specifications for compliance.
Supply Chain Analysis
Extended payment terms from automotive OEMs and pharmaceutical distributors shape supplier financing dynamics across Japan's pallet networks. Domestic manufacturing draws from Hokkaido forestry partnerships, Southeast Asian timber imports, and domestic polymer feedstock. Raw material dependencies span softwood lumber, HDPE resin, and steel alloy components. Single-source vulnerability concentrates in import timber channels exposed to currency fluctuation. Distribution runs through Tokyo Bay port-centric 3PLs consolidating pallet management from individual shippers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's pallet market demands substitution defense against plastic and composite materials displacing wooden infrastructure under tightening sanitation mandates. Incumbents must navigate material conversion costs while preserving repair network advantages.
For Market Incumbents: Build repair technician certification moats through automated optical inspection training partnerships with pharmaceutical distributors. Backward integration into Hokkaido controlled forestry partnerships insulates against yen-denominated timber volatility. Channel control through multi-year pooling contracts with Kanto corridor 3PLs locks out spot-market competitors. R&D investment in nestable design engineering captures empty-return cost savings for distribution centers.
For New Entrants and Emerging Players: Establish a beachhead in RFID-embedded pallet serialization for pharmaceutical track-and-trace mandates. The mid-tier 3PL segment in Saitama and Chiba prefectures shows lowest nestable design penetration and highest consolidation pressure. A go-to-market angle pairing automated damage assessment with blockchain-integrated rental platforms satisfies METI documentation requirements while filtering informal repair networks from regulated tenders.
For Investors and Strategic Acquirers: METI's tightening waste management frameworks reshape the acquisition landscape toward operators with traceable recovery pathways. Long-term viability centers on rental system operators with circular economy credentialing and pharmaceutical cold-chain compliance. Acquisition targets should demonstrate captive timber sourcing or polymer molding capacity with JIS certification infrastructure. Watch for PMDA distribution regulation amendments expanding serialization requirements as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled Forestry | Hokkaido timber partnerships insulate domestic wooden pallet producers from import price shocks. |
| Automated Repair Infrastructure Deployment | Optical inspection systems compress turnaround times from days to hours for pharmaceutical distributors. |
| RFID Serialization Integration | Track-and-trace mandates bridge physical logistics with digital supply chain visibility in drug distribution. |
| Nestable Design Engineering Services | Empty-return volume reduction technology remains underdeployed among mid-tier 3PLs in Kanto corridor. |
| Blockchain-Integrated Rental Platforms | METI documentation requirements filter informal repair networks from regulated tender processes. |
Research Methodology
A standing panel of logistics operations directors, pallet repair depot managers, pharmaceutical distribution procurement leads, and 3PL contract administrators provided ongoing calibration throughout this study. Primary interviews with industry stakeholders combined with secondary validation from METI circular economy guideline publications, JIS standard documentation, Ministry of Health Labour and Welfare sanitation protocol filings, and customs timber import data. Bottom-up volume modeling triangulated against top-down macroeconomic indicators anchored forecast integrity.
Scenario-bracketing across conservative, baseline, and expansion cases bounded uncertainty without year-specific anchoring. The analytical framework modeled material type, design style, application sector, and end user category dimensions across the projection horizon. CAGRs were derived from segment-level growth trajectories informed by pharmaceutical cold-chain expansion rates, Kanto corridor consolidation patterns, and METI regulatory implementation timelines. Industry-specific inputs included timber import volume fluctuations, polymer resin price indices, and 3PL pooling contract penetration rates.
Stress conditions across yen-dollar exchange rates, oil-indexed polymer feedstock costs, and JIS certification backlog durations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation pace and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Europe Pallet Market
Pallets Packaging
Germany Pallets Market
Pallets Packaging
Single Use Pallet Market
Pallets Packaging
Global Crates and Pallets Packaging Market
Pallets Packaging
Paper Pallet Market
Pallets Packaging
Foldable Pallet Container Market
Pallets Packaging
Stretch Hood Pallet Wrapping Market
Pallets Packaging
Pallet Corner Boards Market
Pallets Packaging
Pallet Slip Sheets Market
Pallets Packaging
Wooden Pallets Market
Pallets Packaging
Pallet Pooling Market
Pallets Packaging
India Pallets Market
Pallets Packaging
Empty Fruit Bunch Pallets Market
Pallets Packaging
Spill Pallets Market
Pallets Packaging
Indonesia Pallets Market
Pallets Packaging
Foldable and Collapsible Pallets Market