
 Presswood Pallets Market | 2026-2036
Presswood Pallets Market Size, Share, and Industry Trends Forecast 2026-2036
Presswood Pallets Market Analytics
ISPM-15 heat-treatment compliance tier is unwinding legacy softwood pallet demand across international freight corridors. Schoeller Allibert Services leverages its European molding network to supply compliant presswood alternatives for cross-border pharmaceutical flows. Presswood International anchors North American production capacity through integrated fiber sourcing and compression molding operations. Litco International specializes in custom dimensional specifications for automated warehouse systems in the Midwest industrial belt.
Presswood pallets are engineered fiber-molded shipping platforms manufactured from recycled wood residues under high temperature and pressure, typically achieving densities of 750-950 kg/m³ with defined racking load capacities. These pallets serve as ISPM-15 exempt alternatives for export logistics, eliminating heat-treatment documentation burdens while offering nesting ratios that reduce empty transport volume. Standard pallets dominate volume flows in food and beverage distribution where uniform sizing aligns with automated handling systems. Custom pallets capture premium positioning in electronics and pharmaceutical applications requiring dimensional precision for fragile cargo. Reusable pallets are gaining structural traction among logistics providers implementing closed-loop pool systems under extended producer responsibility frameworks.
FDA traceability rules for pharmaceutical distribution, EPA recycled content guidelines for federal procurement, and EU REACH compliance for chemical treatment residues all shape product formulation and market access conditions for presswood pallet suppliers. ISO 8611 testing protocols for pallet load performance create baseline qualification requirements that filter marginal producers from institutional buyer vendor lists. Stakeholders must monitor evolving packaging waste regulations across their primary shipping corridors to anticipate material specification shifts before contract renewal cycles.
Market Dynamics
ISPM-15 heat-treatment documentation burdens are redirecting export logistics spend toward exempt fiber-molded platforms, compressing legacy softwood pallet demand across trans-Pacific and trans-Atlantic freight corridors.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Material traceability mandates for wood-based shipping platforms are elevating presswood pallet preference among pharmaceutical exporters seeking simplified compliance documentation.
- Automated warehouse systems:Food and beverage distributors in Germany and the United States are standardizing on uniform pallet dimensions to maximize robotic handling throughput.
- Closed-loop pool systems:Extended producer responsibility frameworks in the Netherlands and Belgium are incentivizing logistics providers to deploy reusable presswood pallets with embedded RFID tracking.
Market Restraints
- Recycled fiber input volatility:Sawmill residue and wood waste availability fluctuates with construction cycle downturns in the United States and Canada, pressuring production cost stability.
- Compression molding equipment concentration:High-tonnage press manufacturing concentrates among German and Italian machinery suppliers, creating capex bottlenecks for new market entrants.
- Plastic pallet substitution:Injection-molded HDPE alternatives from pool operators are capturing pharmaceutical cold-chain segments requiring washdown compatibility.
Strategic Opportunities
- India export manufacturing zones:Pharmaceutical and electronics clusters in Gujarat and Maharashtra lack compliant pallet supply, creating first-mover positioning for ISPM-15 exempt fiber-molded platforms.
- FDA pharmaceutical traceability rules:Serialized pallet-level tracking requirements are opening specification windows for embedded sensor integration in temperature-sensitive distribution.
- Hybrid pallet rental models:Pay-per-use structures combining asset ownership with logistics service provision are penetrating mid-sized German food exporters seeking working capital relief.
Industry Challenges
- ISO 8611 testing protocol compliance:Third-party certification timelines for racking load and edge-rack deflection testing extend 8-14 weeks, delaying vendor qualification for institutional buyers.
- Legacy WMS integration:Automated warehouse management systems in Midwest United States distribution centers require custom dimensional programming to accommodate non-standard presswood specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Presswood Pallets Market |
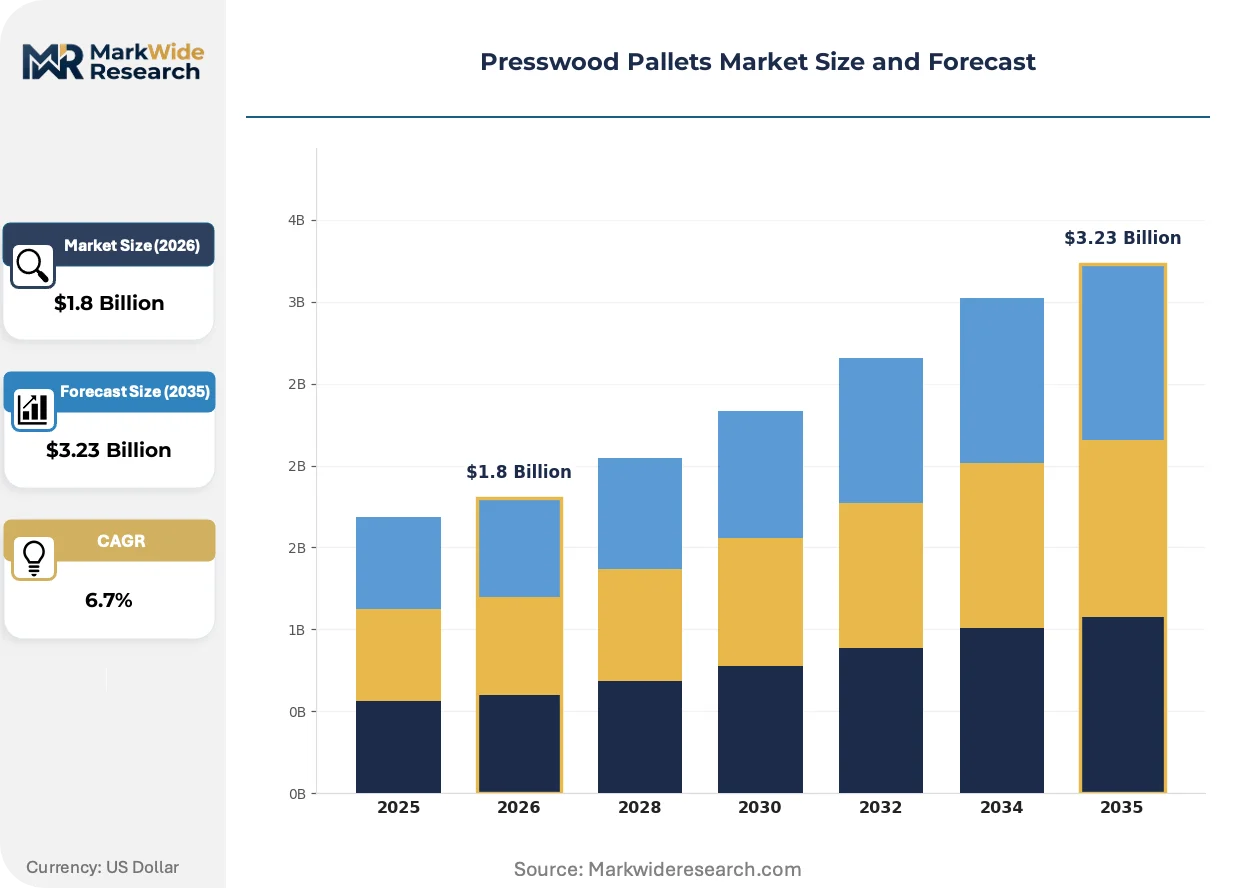
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pallets, Custom Pallets, Reusable Pallets, Export Pallets Application: Food & Beverage, Consumer Goods, Electronics, Pharmaceuticals End User: Manufacturers, Wholesalers, Retailers, Logistics Providers Distribution Channel: Direct Sales, Distributors, Online Retail, B2B Platforms |
| Companies Covered | Schoeller Allibert Services, Presswood International, Litco International, Nefab Group, INKA Paletten, Millwood, Brambles, The Nelson Company, Snyder Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Presswood Pallets Market Evolving Landscape
Compression molding process refinements and embedded sensor integration are redefining performance benchmarks for fiber-based shipping platforms across temperature-controlled logistics networks.
High-density fiber molding above 850 kg/m³ is decomposing the traditional trade-off between nesting efficiency and point-load capacity. Pharmaceutical 3PLs in Germany are specifying these grades for automated high-bay storage systems. The technology is decomposing incumbent softwood block pallet positions in export corridors where documentation simplicity carries premium value.
REACH compliance for chemical treatment residues in wood-based packaging is tightening formulation requirements across EU member states. Manufacturers are eliminating phenol-formaldehyde binders in favor of bio-based alternatives to maintain market access. Electronics exporters to Germany and France are prioritizing suppliers with ECHA-registered substance portfolios to preempt customs detention risks.
Buyer consolidation among multinational food retailers is compressing pallet specification cycles from annual to quarterly reviews. Category managers at German and United States grocery chains are unbundling pallet procurement from freight contracts to secure direct quality accountability. This pattern concentrates most visibly in fresh produce distribution networks where shelf-life sensitivity elevates platform reliability scrutiny.
Presswood Pallets Market Segmentation
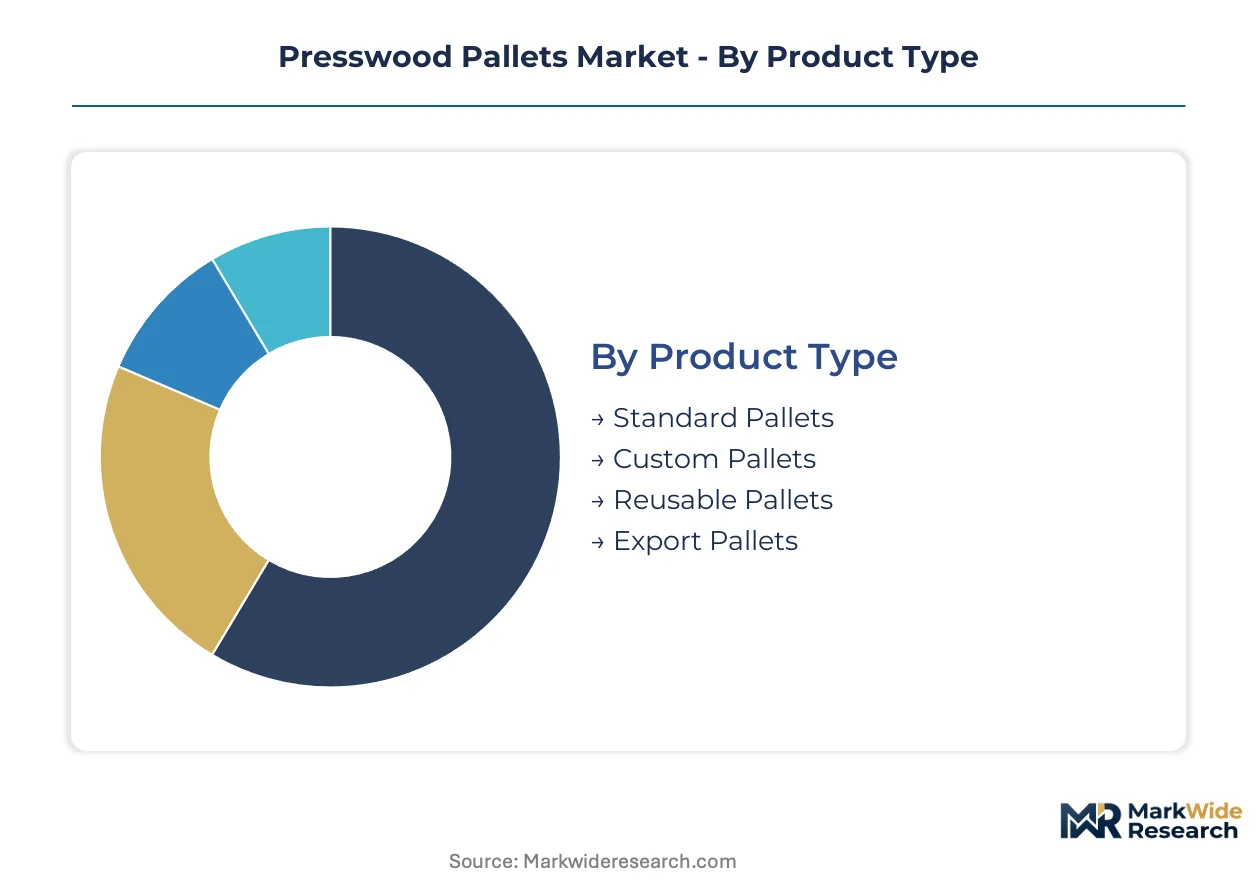
Presswood pallet procurement patterns diverge sharply across product configurations and downstream channels. Pharmaceutical exporters prioritize ISPM-15 exempt documentation paths, while food distributors optimize for automated handling compatibility.
Product Type:
Standard and custom configurations flow through divergent channel structures—direct sales dominate specification-intensive segments while distributors handle volume standard products.
- Standard Pallets:Uniform 1200x800mm and 1200x1000mm dimensions manufactured to ISO 8611 racking load specifications with densities of 750-850 kg/m³. German food retailers and United States beverage distributors concentrate procurement here for automated warehouse compatibility, though margin compression intensifies under annual contract renegotiation cycles.
- Custom Pallets:Engineered to dimensional tolerances within ±2mm for fragile cargo stabilization, typically achieving 850-950 kg/m³ density grades. Electronics manufacturers in China and pharmaceutical exporters in Germany specify these for high-bay automated storage systems where point-load distribution determines throughput efficiency.
- Reusable Pallets:Closed-loop pool systems with embedded RFID tracking deployed by Netherlands and Belgium logistics providers under extended producer responsibility frameworks.
- Export Pallets:ISPM-15 exempt fiber-molded platforms eliminating heat-treatment documentation burdens for trans-Pacific and trans-Atlantic freight corridors.
Standard pallets dominate installed base. Custom pallets are where expansion concentrates.
Application:
End-use concentration determines margin tiering—pharmaceutical and electronics applications command specification premiums while food and beverage segments compete on unit economics.
- Food & Beverage:Temperature-sensitive distribution networks requiring moisture-resistant fiber formulations compliant with FDA and EFSA contact material standards. German fresh produce chains and United States dairy distributors standardize on uniform pallet dimensions to maximize robotic handling throughput in refrigerated facilities.
- Pharmaceuticals:Serialized tracking requirements under FDA Drug Supply Chain Security Act and EU Falsified Medicines Directive mandate pallet-level traceability infrastructure. Temperature-controlled 3PLs in Germany specify high-density grades above 850 kg/m³ for automated high-bay storage reliability.
- Consumer Goods:Mass retail distribution through pooled pallet networks with quarterly specification reviews driven by multinational grocery chain consolidation.
- Electronics:ESD-sensitive cargo requiring dimensional precision for automated assembly line integration, with REACH-compliant binder formulations prioritized for EU market access.
Food and beverage anchors volume throughput. Pharmaceuticals represent the steepest expansion trajectory.
End User:
Procurement authority is shifting from logistics departments to sustainability officers as extended producer responsibility frameworks mature across European markets.
- Manufacturers:OEMs in automotive and electronics verticals specifying presswood alternatives for export compliance, with vendor qualification cycles extending 8-14 weeks for ISO 8611 certification.
- Logistics Providers:3PLs deploying closed-loop pool systems with pay-per-use rental models penetrating mid-sized German food exporters seeking working capital relief.
- Wholesalers:Consolidated buying groups negotiating direct pallet procurement unbundled from freight contracts to secure quality accountability.
- Retailers:Category managers at German and United States grocery chains compressing specification cycles from annual to quarterly reviews in fresh produce networks.
Logistics providers control pool system deployment. Manufacturers drive specification innovation.
Distribution Channel:
Channel selection correlates with pallet complexity—direct engagement prevails where dimensional customization or embedded sensor integration is required.
- Direct Sales:Specification engineering relationships with pharmaceutical and electronics OEMs requiring custom mold development and REACH-compliant formulation documentation.
- Distributors:Inventory-holding intermediaries serving food and beverage volume segments with standard pallet configurations and rapid replenishment capabilities.
- B2B Platforms:Digital procurement channels penetrating mid-market manufacturers in India export zones lacking compliant pallet supply infrastructure.
- Online Retail:Niche presence for small-batch custom specifications and replacement orders in fragmented electronics assembly operations.
Distributors handle volume velocity. Direct sales capture margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive food distributors in the United States and Germany drive volume procurement, while pharmaceutical exporters in Switzerland and electronics manufacturers in Japan absorb specification premiums with minimal elasticity.
United States
FDA pharmaceutical traceability mandates and EPA recycled content guidelines for federal procurement elevate presswood pallet specification intensity. Midwest distribution centers in Illinois and Ohio automate warehouse systems requiring uniform 1200x1000mm pallet dimensions. Dairy and fresh produce chains concentrate procurement authority in Minneapolis and Chicago regional hubs.
Germany
EU Packaging and Packaging Waste Regulation tightens material traceability requirements for temperature-sensitive pharmaceutical shipments. REACH compliance for chemical treatment residues eliminates phenol-formaldehyde binders from export-bound production. Bavarian automotive clusters and Baden-Württemberg electronics exporters specify high-density grades above 850 kg/m³ for automated handling.
China
Export manufacturing zones in Guangdong and Jiangsu provinces generate concentrated demand for ISPM-15 exempt fiber-molded platforms. Dual carbon goals under MIIT guidance incentivize recycled wood residue utilization in compression molding operations. Electronics assembly corridors in Shenzhen and Dongguan prioritize dimensional precision for fragile cargo stabilization.
India
Pharmaceutical and electronics clusters in Gujarat and Maharashtra lack compliant pallet supply infrastructure, creating positioning windows for exempt alternatives. BIS standards for wood-based packaging materials remain under development, delaying formal certification pathways. DGFT export promotion schemes accelerate manufacturing zone investment in Ahmedabad and Pune industrial belts.
Netherlands
Extended producer responsibility frameworks incentivize closed-loop pool systems with embedded RFID tracking. Rotterdam port logistics providers deploy reusable presswood pallets for EU-wide distribution networks. Belgian and Dutch food retailers compress specification cycles from annual to quarterly reviews under consolidated buying group pressure.
Presswood Pallets Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the presswood pallets market. European molders with integrated fiber sourcing dominate specification-intensive pharmaceutical segments, while North American volume producers compete on unit economics for food distribution contracts. Three archetypes define competitive positioning: vertically integrated fiber-mold specialists, regional compression molding operators, and pooled logistics platform providers. Capacity expansion and strategic partnerships represent the dominant competitive moves, with machinery access bottlenecks from German and Italian equipment suppliers constraining new entrant timelines.
Among European-based service providers, Schoeller Allibert Services and INKA Paletten exemplify the integrated molding network archetype serving cross-border pharmaceutical flows. Presswood International anchors North American production capacity through captive fiber sourcing and compression molding operations. These three companies occupy positions spanning specification engineering relationships and volume standard product distribution, reflecting the market's bifurcated demand structure between premium custom grades and cost-optimized food logistics platforms.
| Leading Market Players |
|---|
| Schoeller Allibert Services |
| Presswood International |
| Litco International |
| Nefab Group |
| INKA Paletten |
| Millwood |
| Brambles |
| The Nelson Company |
| Snyder Industries |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German pharmaceutical 3PLs and fiber-molding specialists lock in recycled fiber supply visibility while insulating buyers from sawmill residue volatility across North American construction cycles. These structures concentrate pricing power among integrated European molders with captive raw material streams.
Pricing Analysis
EU REACH compliance dictates the pricing tier structure across pharmaceutical export corridors, separating ECHA-registered formulation grades from legacy phenol-formaldehyde alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 8611 certification status, customization precision, and volume scale. Cost compression in standard pallet tiers intensifies as annual contract renegotiation cycles compress margins for food distribution buyers. Pharmaceutical exporters exhibit minimal price sensitivity, while United States fresh produce chains prioritize unit economics above performance specifications.
Supply Chain Analysis
Strategic stockpile preferences dominate fiber input procurement, with German and Italian compression molding equipment suppliers commanding 8-14 week lead times that force buffer inventory positions. Raw material sourcing draws from sawmill residues in the United States and Canada, recycled wood waste streams in Germany, and post-industrial fiber in China. Single-source vulnerability concentrates in high-tonnage press manufacturing, where machinery access bottlenecks constrain new entrant timelines. Distribution runs through direct sales channels for specification-intensive pharmaceutical segments and inventory-holding distributors for food and beverage volume flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Presswood pallet procurement is shifting toward platform-economics logic as embedded RFID tracking and closed-loop pool systems create interoperability standards that lock in logistics provider relationships.
For Market Incumbents: Fortify backward integration into recycled fiber sourcing to defend against input cost volatility from North American construction downturns. Prioritize ISO 8611 certification investment to maintain vendor qualification status amid quarterly specification reviews by consolidated German grocery chains. Capacity addition in Gujarat and Maharashtra industrial belts counters emerging competition from regional compression molding operators. For New Entrants and Emerging Players: ISO 8611 fast-track certification pathways open positioning in India export manufacturing zones where BIS standards remain under development. Pharmaceutical clusters in Ahmedabad and Pune present the most penetrable white-space, lacking compliant pallet supply infrastructure for temperature-sensitive shipments. Go-to-market execution should leverage B2B digital procurement channels to bypass established distributor networks. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated fiber-mold specialists with ECHA-registered formulation portfolios and established pharmaceutical 3PL relationships. Long-term viability hinges on extended producer responsibility framework maturation across EU member states, with pool system operators capturing recurring revenue streams. Watch for FDA serialized tracking mandate enforcement as the inflection signal for embedded sensor integration demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Sourcing | Captive supply of sawmill residue insulates German molders from North American construction cycle volatility. |
| ISO 8611 Certification Investment | Third-party load testing qualification filters marginal producers from institutional pharmaceutical buyer vendor lists. |
| Embedded RFID Tracking Deployment | Serialized pallet-level infrastructure satisfies EU Falsified Medicines Directive traceability mandates. |
| REACH-Compliant Formulation Transition | Elimination of phenol-formaldehyde binders preserves market access for electronics exporters to France and Germany. |
| Capacity Expansion in India Export Zones | First-mover positioning in Gujarat pharmaceutical clusters addresses acute compliant pallet supply gaps. |
Research Methodology
Initial hypotheses were tested against primary input from logistics procurement directors, pharmaceutical supply chain managers, compression molding plant engineers, and sustainability compliance officers, then refined through secondary validation against customs trade data, EPA recycled content guidelines, ECHA substance registration databases, and ISO 8611 testing protocol documentation. Bottom-up fiber input cost modeling and top-down pharmaceutical export volume estimates were triangulated to anchor demand projections.
Variance decomposition across product configuration, end-use application, and geographic regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented demand elasticity modeling and input cost trajectory assumptions. Industry-specific forecast inputs included ISPM-15 exemption adoption rates in trans-Pacific corridors and REACH compliance transition timelines for chemical treatment residues.
Underlying assumptions cover stable recycled fiber availability, machinery lead time continuity, and regulatory enforcement intensity, with deviation risk concentrated in construction cycle downturns and BIS standard finalization delays in India. Revision becomes warranted when FDA traceability mandate enforcement crosses implementation thresholds or EU Packaging and Packaging Waste Regulation material traceability requirements tighten beyond current specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Pallet Jacks Market
Pallets Packaging
Corrugated Pallets Market
Pallets Packaging
Pallets Market
Pallets Packaging
Block Pallets Market
Pallets Packaging
Europe Palletizer Market
Pallets Packaging
Pallet Wrappers Market
Pallets Packaging
Europe Pallet Market
Pallets Packaging
China Pallets Market
Pallets Packaging
UK Pallets Market
Pallets Packaging
France Pallets Market
Pallets Packaging
Single Use Pallet Market
Pallets Packaging
Conventional Palletizers Market
Pallets Packaging
Italy Pallets Market
Pallets Packaging
Global Pallet Racking System Market
Pallets Packaging
Europe Lumber Pallet Market
Pallets Packaging
Canada Pallets Market