
 Germany Pallets Market | 2026-2036
Germany Pallets Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Pallets Market Insights
Market Context
Multi-source pallet procurement is restructuring supply chain economics across German manufacturing hubs. CABKA Group GmbH leverages its closed-loop plastic pallet recycling network to secure long-term automotive contracts. Craemer Holding GmbH anchors its position through captive steel and plastic molding capacity that insulates against resin price swings. DS Smith Plc competes in corrugated pallets by extending its paper-based packaging expertise into lightweight, one-way shipping applications for e-commerce fulfillment.
Technical Definition and Segment Structure
A pallet is a flat transport structure built to ISO 6780 dimensions, typically measuring 1200 mm by 800 mm for European standard loads, designed to support goods in a stable fashion during lifting by forklifts, pallet jacks, or conveyor systems. Wooden pallets dominate German material handling due to low unit cost and repairability, though plastic pallets are displacing timber in pharmaceutical cleanrooms and food-grade cold chains where hygiene protocols prohibit fiber shedding. Food grade and hygienic material grades command premium positioning as German food processors face stricter HACCP documentation requirements, while rental services and pooling models capture recurring revenue streams that direct sales cannot match.
Regulatory Framework and Outlook
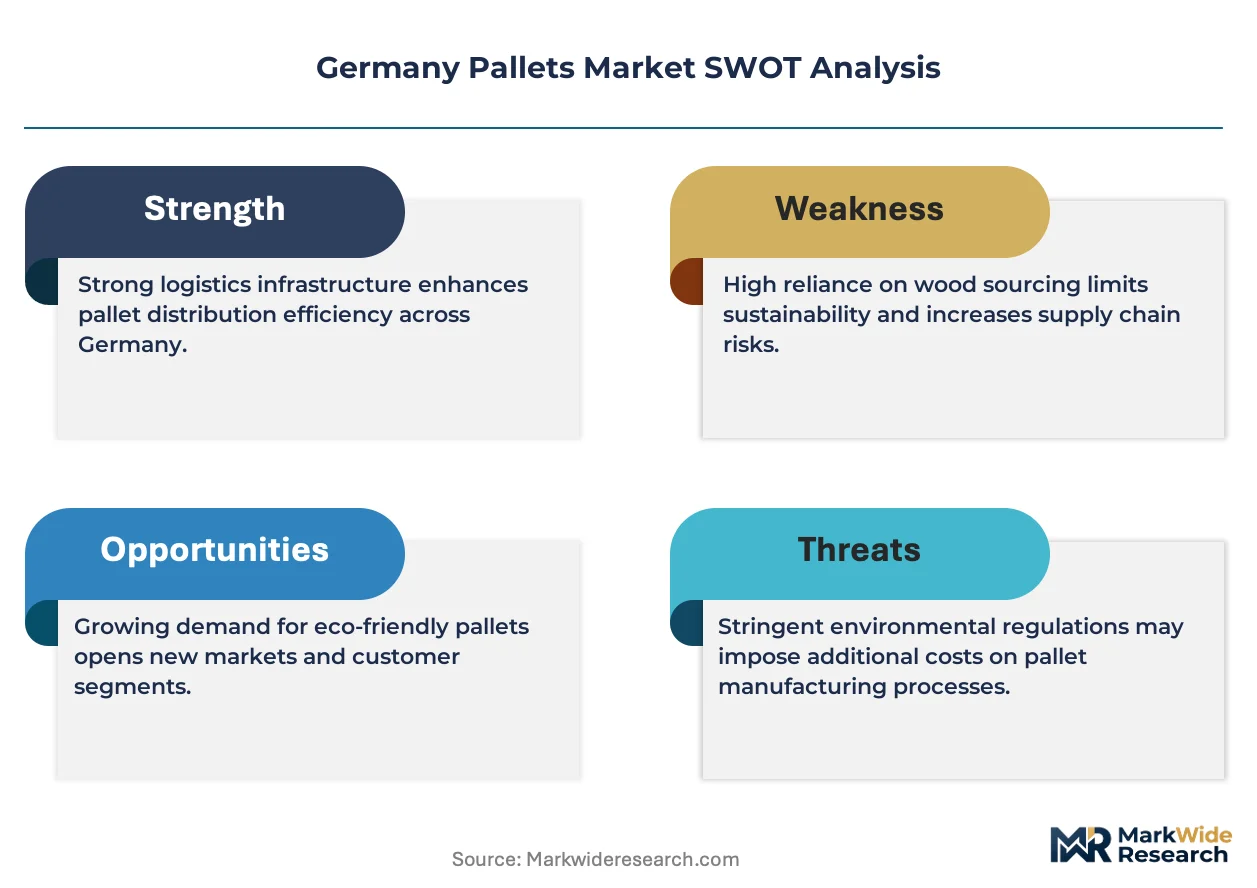
Germany's national implementation of EU Packaging and Packaging Waste Regulation, enforced by the Federal Environment Agency alongside KBA transport safety standards, mandates traceability and recyclability for all shipping platforms entering commercial circulation. REACH compliance and ECHA substance restrictions further limit chemical treatments in wooden pallet production, pushing converters toward heat-treated certified stock. Stakeholders must monitor how the EU Green Deal's packaging reuse targets will redefine pallet lifecycle accountability and pooling operator liability.
Market Dynamics
EU Circular Economy Action Plan mandates are forcing German manufacturers to abandon single-use shipping platforms in favor of closed-loop pooling systems that embed traceability and lifecycle accountability into logistics contracts.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Germany's Federal Environment Agency enforces strict recyclability quotas that accelerate reusable pallet adoption across automotive and food processing supply chains.
- North Rhine-Westphalia industrial corridor:Dense concentration of chemical and automotive OEMs creates concentrated demand for standardized pooling networks that reduce empty-mile transport.
- Heat-treated timber certification:ISPM 15-compliant wooden pallets gain preference in export-oriented manufacturing as REACH restrictions eliminate chemical treatment alternatives.
Market Restraints
- Resin price volatility:Polypropylene and HDPE input costs swing with crude oil indices, compressing margins for plastic pallet converters serving pharmaceutical cleanrooms.
- Baltic timber supply concentration:German wooden pallet manufacturers depend on Latvian and Estonian softwood imports vulnerable to export licensing disruptions and transport bottlenecks.
- Pooling operator liability caps:German transport law limits damage recovery from pallet rental providers, discouraging high-value electronics manufacturers from switching from owned assets.
Strategic Opportunities
- Baden-Württemberg precision engineering cluster:Medical device and optics manufacturers remain underpenetrated by hygienic plastic pooling services due to legacy stainless-steel container preferences.
- Rail-integrated pooling hubs:Deutsche Bahn freight terminals offer untapped last-mile consolidation points for pallet flows between Bavarian automotive plants and northern ports.
- Digital product passport mandates:Upcoming EU requirements for embedded RFID and blockchain traceability create first-mover advantages for pooling operators investing in IoT-enabled fleet management.
Industry Challenges
- Heat treatment technician certification:ISPM 15 audit requirements face bottlenecks as German forestry schools lack specialized training programs for kiln operation and phytosanitary documentation.
- Legacy WMS integration:Mid-sized 3PLs struggle to connect RFID-enabled pallet tracking with existing warehouse management systems without costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Pallets Market |
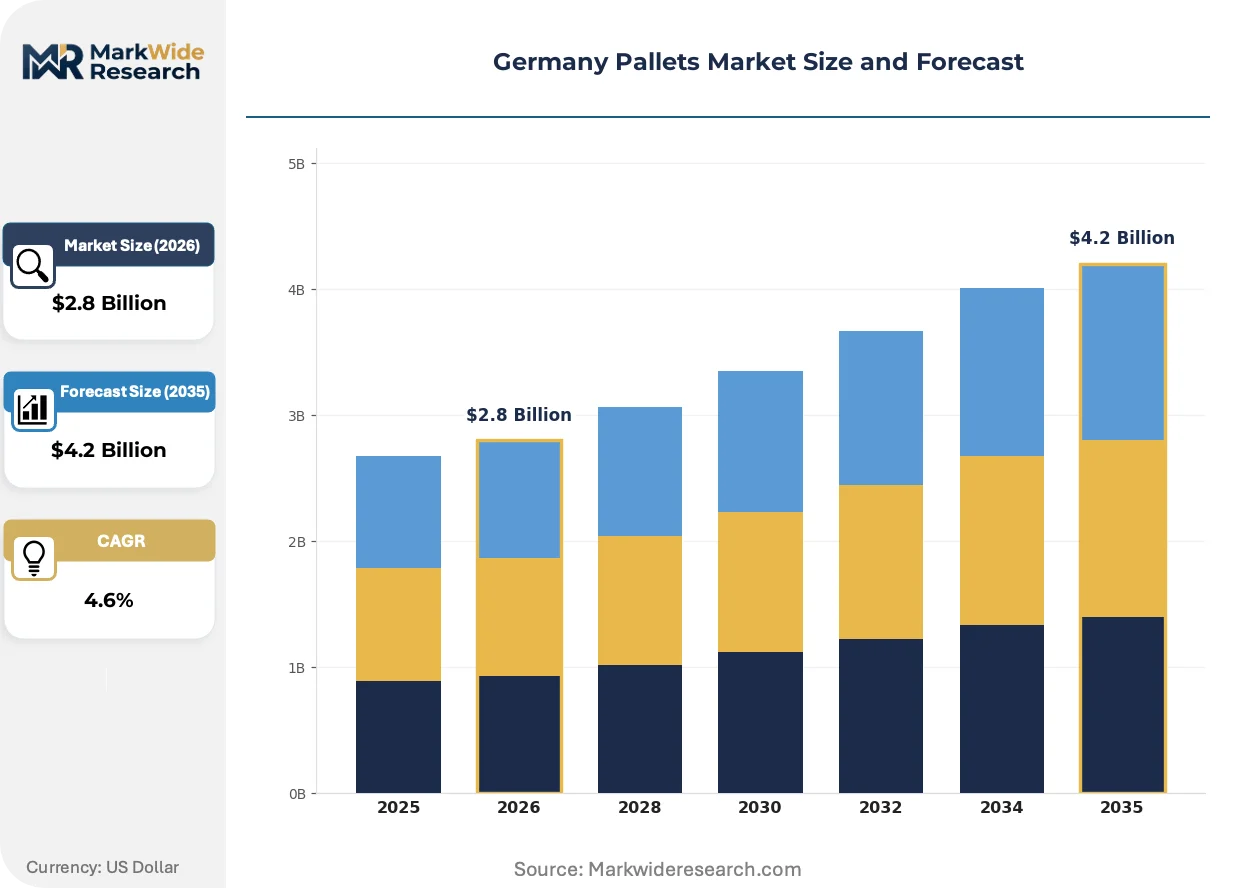
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wooden Pallets, Plastic Pallets, Metal Pallets, Composite Pallets, Corrugated Pallets Material Grade: Standard Grade, Food Grade, Chemical Resistant, Heat Treated, Hygienic End Use Industry: Food & Beverage, Pharmaceuticals, Automotive OEMs, Electronics Assembly, Chemicals Manufacturing Sales Channel: Direct Sales, Distributors, Ecommerce Platforms, Rental Services, Third-Party Vendors |
| Companies Covered | Craemer Holding GmbH, CABKA Group GmbH, Falkenhahn AG, AUER GmbH, INKA Paletten GmbH, CHEP, ORBIS Europe, Craemer GmbH, DS Smith Plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Pallets Market Trends and Innovations
Automation and sensor integration are transforming pallet fleets from passive shipping platforms into active data collection nodes that optimize supply chain visibility and asset utilization rates.
RFID-embedded plastic pallets is automating real-time location tracking for high-value pharmaceutical shipments moving through Bavarian cold chain distribution centers. Bayer and Merck KGaA are retrofitting existing fleets with UHF tags that transmit temperature and shock data to centralized logistics control towers. This sensor integration is automating compliance documentation for EU Good Distribution Practice audits while reducing manual inventory cycle counts by warehouse operators.
REACH chemical restrictions enforced by ECHA are eliminating chromated copper arsenate and methyl bromide fumigation from wooden pallet production across German manufacturing regions. Heat treatment kilns using controlled atmosphere technology now dominate export-certified timber processing in North Rhine-Westphalia. Food-grade pallet converters in Lower Saxony face the strictest adaptation timelines as EFSA documentation requirements for direct food contact expand beyond packaging to include shipping platforms.
Third-party pooling contracts are displacing direct pallet ownership among mid-sized automotive suppliers concentrated in Stuttgart and Wolfsburg industrial zones. Tier-2 component manufacturers now prioritize per-trip pricing over capital expenditure to preserve working capital for electrification investments. This subscription-based asset model spreads fastest among battery cell suppliers establishing new production lines in Thuringia and Saxony where infrastructure flexibility outweighs long-term ownership economics.
Germany Pallets Market Segmentation
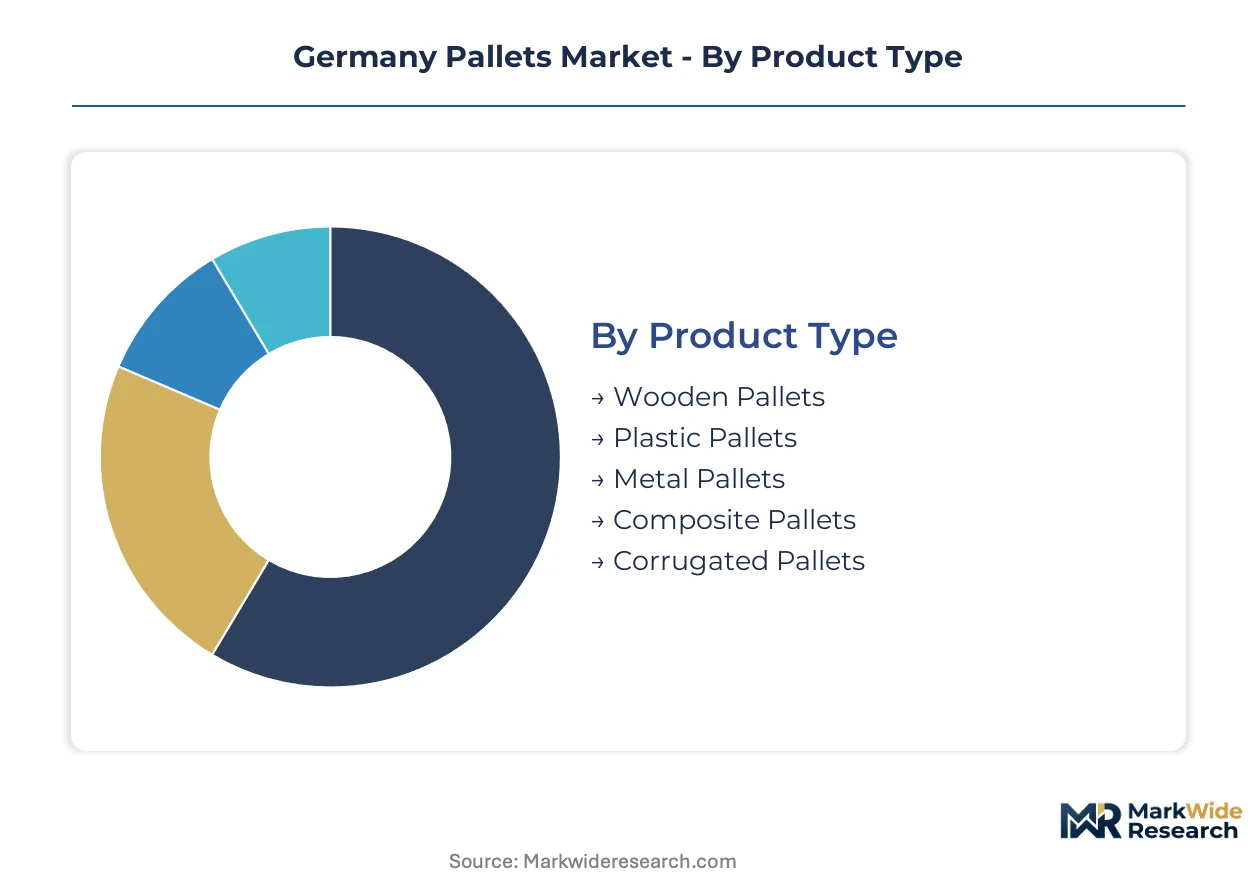
Pallet specification varies sharply across German industrial corridors, with material selection and hygiene certification determining contract eligibility in regulated supply chains. Procurement patterns diverge between capital-intensive automotive OEMs favoring rental pooling and mid-sized food processors prioritizing direct ownership of ISPM 15-certified timber assets.
Product Type:
Integration depth distinguishes standalone timber platforms from embedded sensor-enabled plastic systems tracking pharmaceutical shipments through Bavarian cold chains.
- Wooden Pallets:Softwood construction dominates North Rhine-Westphalia chemical corridors due to repairability and low unit economics. Heat-treated certification under ISPM 15 protocols remains mandatory for export-oriented manufacturers in Baden-Württemberg automotive clusters facing ECHA chemical restrictions.
- Plastic Pallets:HDPE and polypropylene injection molding serves pharmaceutical cleanrooms in Hesse where fiber shedding prohibitions eliminate timber alternatives. Embedded RFID tags enable real-time tracking for Merck KGaA and Bayer distribution networks through EU Good Distribution Practice compliance.
- Metal Pallets:Steel and aluminum platforms anchor heavy machinery logistics in Saxony precision engineering zones requiring load capacities exceeding timber limits.
- Composite Pallets:Wood-plastic hybrid construction targets mid-tier automotive suppliers seeking durability without full plastic premium pricing.
- Corrugated Pallets:Lightweight paper-based platforms support one-way e-commerce fulfillment from Lower Saxony distribution centers to northern European consumer markets.
Volume placements concentrate in Wooden Pallets; the faster expansion belongs to Plastic Pallets.
Material Grade:
Cost tier stratification separates commodity timber from certified grades commanding rental premiums in regulated food and pharmaceutical channels.
- Standard Grade:Untreated softwood serves domestic German manufacturing with minimal regulatory overhead, dominating intra-EU freight movements.
- Food Grade:FDA and EFSA-compliant surfaces with documented non-toxic coatings protect direct food contact shipments through Lower Saxony dairy processing corridors.
- Chemical Resistant:Specialized polymer formulations withstand corrosive substance transport for BASF and Covestro supply networks in Ludwigshafen chemical parks.
- Heat Treated:Kiln-dried timber certified to ISPM 15 phytosanitary standards enables export to North American and Asian markets from Hamburg port operations.
- Hygienic:Seamless plastic construction with microbiological resistance protocols serves medical device sterilization requirements in Tuttlingen surgical instrument manufacturing.
Standard Grade captures the highest shipment volumes; Hygienic grades are climbing the fastest on pharmaceutical demand.
End Use Industry:
Application specificity drives divergent material requirements, with hygiene protocols in food and pharma contrasting against load-bearing priorities in automotive and chemicals.
- Food & Beverage:HACCP documentation mandates dominate procurement for Nestlé and Unilever distribution networks across Bavarian dairy and confectionery processing facilities.
- Pharmaceuticals:Temperature-validated plastic pooling services support cold chain integrity for vaccine distribution through Frankfurt Rhine-Main logistics hubs.
- Automotive OEMs:Volkswagen and BMW assembly plants in Wolfsburg and Munich specify returnable packaging systems with embedded tracking for just-in-sequence component delivery.
- Electronics Assembly:ESD-safe platforms protect semiconductor shipments through Dresden silicon wafer fabrication corridors.
- Chemicals Manufacturing:Corrosion-resistant specifications prevail for agrochemical and specialty chemical movements through Leverkusen and Marl industrial zones.
Automotive OEMs generate the densest pallet circulation volumes; Pharmaceuticals show the steepest expansion trajectory on cold chain infrastructure investment.
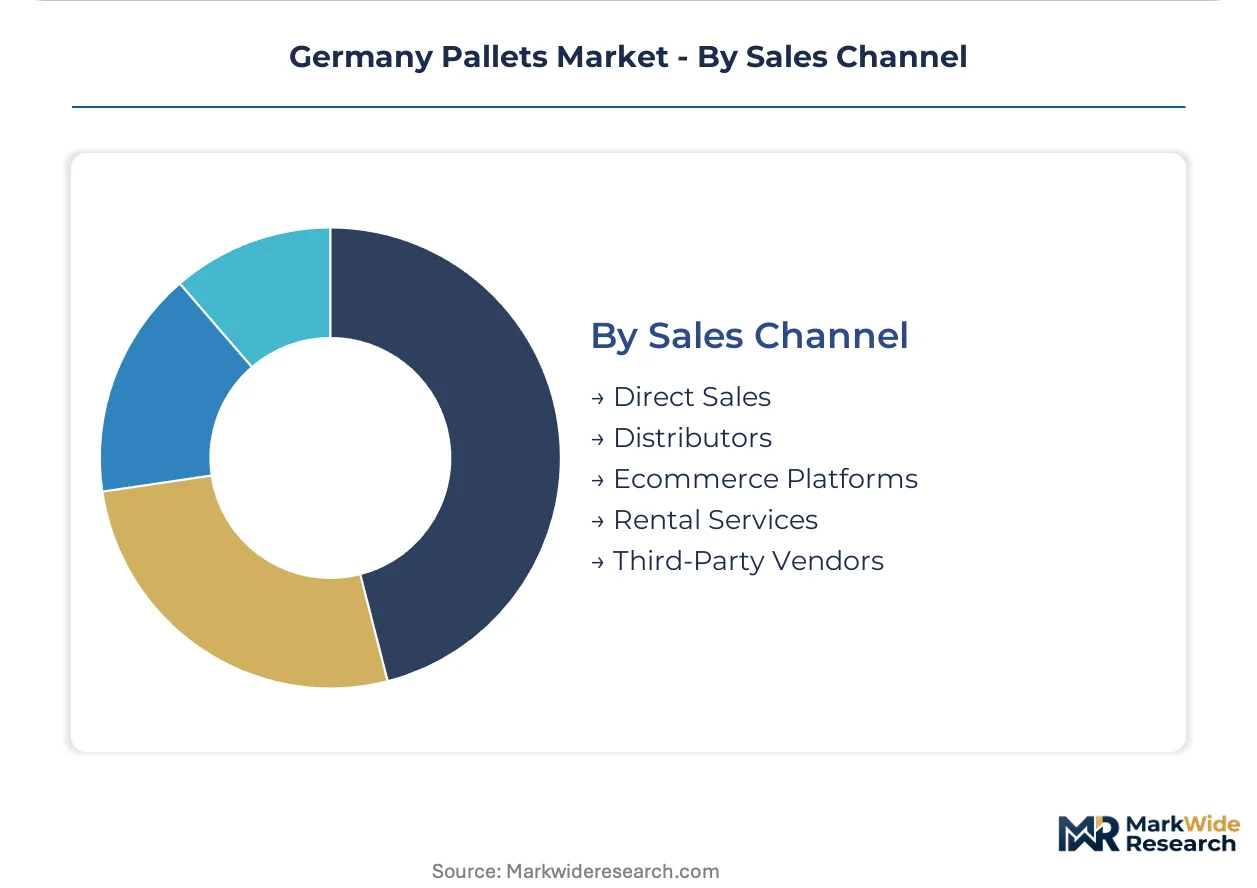
Sales Channel:
Customer type segmentation separates asset-heavy direct purchasers from working-capital-conscious subscribers to third-party pooling networks.
- Direct Sales:Capital expenditure ownership persists among large chemical manufacturers preferring balance sheet control over operational leasing complexity.
- Distributors:Regional pallet brokers aggregate fragmented demand from mid-sized metalworking shops in Solingen and Remscheid tooling clusters.
- Ecommerce Platforms:Digital procurement portals serve small logistics operators in Berlin-Brandenburg startup ecosystems with standardized EUR-pallet specifications.
- Rental Services:Per-trip pricing models accelerate among Thuringia battery cell suppliers prioritizing infrastructure flexibility over long-term ownership economics.
- Third-Party Vendors:Independent pooling operators compete with CHEP and PAKi networks in Stuttgart industrial zones through differentiated damage liability terms.
Rental Services concentrate transaction volume growth; Direct Sales retain margin leadership in specialized chemical-resistant specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baltic softwood imports from Latvia and Estonia anchor German pallet manufacturing, with domestic demand concentrated in industrial corridors stretching from the Rhine-Ruhr region to southern automotive clusters.
North Rhine-Westphalia
Chemical manufacturers in Leverkusen and Marl drive corrosion-resistant pallet specifications for agrochemical shipments. KBA transport safety standards govern load securing protocols for BASF supply networks. The Rhine-Ruhr logistics hub concentrates pooling depots serving intra-EU freight movements through Duisburg inland terminals.
Bavaria
Automotive OEMs in Munich and Ingolstadt specify returnable packaging systems for just-in-sequence component delivery. EU Packaging and Packaging Waste Regulation mandates accelerate reusable platform adoption across Volkswagen and BMW assembly plants. Cold chain distribution centers around Nuremberg handle temperature-validated pharmaceutical shipments for regional vaccine distribution.
Baden-Württemberg
Precision engineering manufacturers in Stuttgart and Tuttlingen require hygienic plastic pallets for medical device sterilization protocols. ECHA REACH restrictions eliminate chemical treatments from wooden platforms serving surgical instrument exporters. The region's optics cluster remains underpenetrated by pooling services due to legacy stainless-steel container preferences.
Lower Saxony
Food processors in Oldenburg and Verden demand EFSA-compliant surfaces for direct dairy contact shipments. HACCP documentation requirements expand beyond packaging to include shipping platforms under evolving food safety protocols. E-commerce fulfillment centers near Hanover deploy lightweight corrugated pallets for one-way northern European consumer deliveries.
Hesse
Pharmaceutical cleanrooms in Frankfurt Rhine-Main logistics hubs prohibit fiber shedding through strict hygiene protocols. EU Good Distribution Practice audits drive RFID-embedded plastic pallet adoption for Merck KGaA and Bayer distribution networks. Temperature-validated pooling services support vaccine integrity across centralized cold chain infrastructure.
Germany Pallets Market Competitive Landscape
Global pooling networks compete with regional manufacturing specialists across material technologies and service models. The vendor base organizes around three strategic tiers: integrated material converters with captive resin and steel capacity, asset-light pooling operators leveraging third-party fleet networks, and paper-based packaging extenders entering lightweight shipping applications. Dominant competitive moves include backward integration into raw material processing and digital tracking infrastructure deployment.
Among German-based fabricators, Craemer Holding GmbH and CABKA Group GmbH exemplify the integrated converter archetype through captive molding and recycling operations. DS Smith Plc represents packaging-to-pallet extension strategies. Falkenhahn AG, AUER GmbH, and INKA Paletten GmbH occupy positions within the mid-tier timber specialization segment serving regional chemical and food processing corridors.
| Leading Market Players |
|---|
| Craemer Holding GmbH |
| CABKA Group GmbH |
| Falkenhahn AG |
| AUER GmbH |
| INKA Paletten GmbH |
| CHEP |
| ORBIS Europe |
| Craemer GmbH |
| DS Smith Plc |
| Others |
Pricing and Supply Chain Analysis
ISPM 15-certified kiln operators concentrated in North Rhine-Westphalia command wage premiums that widen spreads between heat-treated export-grade pallets and untreated domestic timber platforms. Labor-cost differentials between certified technicians and general woodworking labor feed directly into three-tier pricing stratification across German manufacturing corridors.
Pricing Analysis
Warranty and damage-liability bundling separates CHEP-style full-service pooling contracts from bare-metal rental arrangements offered by regional operators. Three-tier pricing structure across premium hygienic-grade, standard ISPM 15-certified, and economy untreated timber levels reflects certification investment and RFID traceability inclusion. Price differentiation hinges on EFSA compliance documentation and embedded sensor capability. Pooling operators face margin compression as resin price volatility passes through to pharmaceutical customers least able to absorb increases, while food processors show highest price sensitivity to per-trip rental rates.
Supply Chain Analysis
Dual-sourcing mandates from Volkswagen and BMW procurement teams require pallet suppliers to qualify secondary molding capacity outside primary Baltic timber zones. Geographic supply concentration draws from Latvian and Estonian softwood forests, Polish sawmill processing, and domestic German kiln certification facilities. Raw material dependencies encompass untreated softwood feedstock, polypropylene resin for pharmaceutical grades, and steel for heavy machinery platforms. Single-source vulnerability concentrates in Baltic timber licensing disruptions. Distribution runs through Rhine-Ruhr inland terminals, Bavarian automotive plant cross-docks, and Frankfurt Rhine-Main pharmaceutical hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German pallet supply operates under kiln-capacity constraints that prop pricing for ISPM 15-certified export grades. Certification bottlenecks at forestry schools limit technician pipeline expansion.
For Market Incumbents: Lock in long-term softwood offtake agreements with Latvian exporters before EU Packaging and Packaging Waste Regulation enforcement tightens import documentation. Expand captive heat-treatment capacity in North Rhine-Westphalia to offset Baltic supply disruption risk. Defend margin position through backward integration into resin recycling rather than competing on rental pricing with asset-light pooling entrants. For New Entrants and Emerging Players: RFID-enabled track-and-trace platforms offer wedge positioning against legacy pooling operators serving pharmaceutical cold chains. Target underpenetrated medical device sterilization services in Tuttlingen surgical instrument corridors where stainless-steel container preferences are softening. Lead with temperature-validation documentation and EU Good Distribution Practice audit support as primary go-to-market differentiation. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid material converters given EU Green Deal packaging reuse targets accelerating composite pallet adoption. Five-to-ten-year viability favors operators controlling both timber certification infrastructure and plastic molding capacity. Monitor Deutsche Bahn freight terminal partnerships as inflection signal for rail-integrated pooling hub economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Recycling | CABKA-style closed-loop networks secure automotive contracts against crude oil price swings. |
| RFID Fleet Modernization | Embedded UHF tags enable Merck KGaA compliance with EU Good Distribution Practice audits. |
| Kiln Capacity Expansion | Additional ISPM 15 certification infrastructure reduces Baltic timber import dependency. |
| Rail-Integrated Pooling Hubs | Deutsche Bahn terminal partnerships consolidate Bavarian-to-port pallet flows. |
| Hygienic Grade Certification Investment | EFSA-compliant surfaces unlock Nestlé dairy processing corridor contracts. |
Research Methodology
Document review covered trade association filings, Federal Environment Agency regulatory notices, and KBA transport safety standards, complemented by interviews with plant managers at North Rhine-Westphalia chemical facilities, procurement leads at Bavarian automotive OEMs, pooling depot operators, and forestry school curriculum directors. Secondary validation drew from customs import records, EU Packaging and Packaging Waste Regulation implementation timelines, and ECHA REACH restriction updates. Bottom-up demand modeling triangulated against top-down industrial production indices.
Segmented outputs by material type, hygiene certification tier, end-use industry, and sales channel structure were generated across the projection horizon. CAGRs derived from regression analysis against automotive production forecasts, pharmaceutical cold chain infrastructure investment, and EU circular economy mandate implementation curves. Industry-specific inputs included Baltic softwood import volumes, ISPM 15 certification throughput rates, and RFID adoption curves in pharmaceutical distribution.
Several conditions sit outside the modeled scope, including potential EU timber import licensing suspensions, breakthroughs in biodegradable pallet materials, and Deutsche Bahn freight tariff restructuring. Forecasts reflect assumptions about regulatory enforcement timelines and pooling operator liability framework stability. Deviation in Baltic export policy or EFSA food-contact documentation expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Composite Pallet Market
Pallets Packaging
Pallet Jacks Market
Pallets Packaging
India Pallets Market
Pallets Packaging
Japan Pallets Market
Pallets Packaging
Wooden Pallets Market
Pallets Packaging
Italy Pallets Market
Pallets Packaging
Wooden Pallet Collars Market
Pallets Packaging
Pallet Slip Sheets Market
Pallets Packaging
Spill Pallets Market
Pallets Packaging
Pallet Collar Market
Pallets Packaging
Pallet Shippers Market
Pallets Packaging
Molded Wood Pallets Market
Pallets Packaging
Middle East and Africa Lumber Pallet Market
Pallets Packaging
Corrugated Pallet Containers Market
Pallets Packaging
North America Pallet Market
Pallets Packaging
Pallet Packaging Market