
 Corrugated Pallet Wrap Market | 2026-2036
Corrugated Pallet Wrap Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Pallet Wrap Market Outlook
EU Packaging and Packaging Waste Regulation is hardening recycled-content thresholds for transport packaging across European supply chains. Smurfit Kappa Group leverages integrated containerboard mills to secure virgin and recycled fiber supply for corrugated wrap production. Mondi Group anchors its position through kraft-paper specialization and barrier-coating R&D. DS Smith Plc competes via circular-design services that help exporters eliminate plastic pallet containment entirely.
Corrugated pallet wrap consists of multi-layer kraft paper sheets, typically 150–300 gsm, scored and folded to encase palletized loads; the material substitutes polyethylene stretch film with a recyclable, fiber-based containment system engineered for load stability during transit and warehousing. Heavy-Duty Wrap dominates logistics applications where puncture resistance and tensile strength must match plastic alternatives for dense industrial freight. Eco-Friendly Wrap captures the fastest expansion as retailers and exporters face Scope 3 emissions reporting obligations that penalize petroleum-based packaging.
EMA and EFSA frameworks govern fiber-contact safety and chemical migration limits for food-sector pallet wrap across Europe, while REACH restricts adhesive and coating chemistries used in barrier treatments. The EU Green Deal's packaging-waste reduction targets are forcing converters to certify circularity credentials through accredited recycling streams. Stakeholders must monitor how forthcoming national extended-producer-responsibility schemes alter cost structures for plastic-versus-paper containment choices.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing converters to redesign transport packaging around recycled-content mandates, compressing the competitive window for fiber-based alternatives against incumbent plastic stretch film systems.
Growth Catalysts
- EU Green Deal packaging-waste targets:Member states are accelerating EPR scheme rollouts that penalize petroleum-based containment, pulling automotive and food exporters toward certified recyclable wrap systems.
- Scope 3 emissions accounting:Retailers facing disclosure obligations under CSRD are mandating fiber-based pallet containment from upstream suppliers to hit net-zero commitments.
- German automotive cluster conversion:Parts distributors in Stuttgart and Wolfsburg are replacing plastic stretch film with corrugated wrap to meet OEM sustainability scorecards.
Market Restraints
- OCC price volatility:Old corrugated container feedstock costs swing with Chinese import quotas, squeezing converter margins on recycled-content wrap grades.
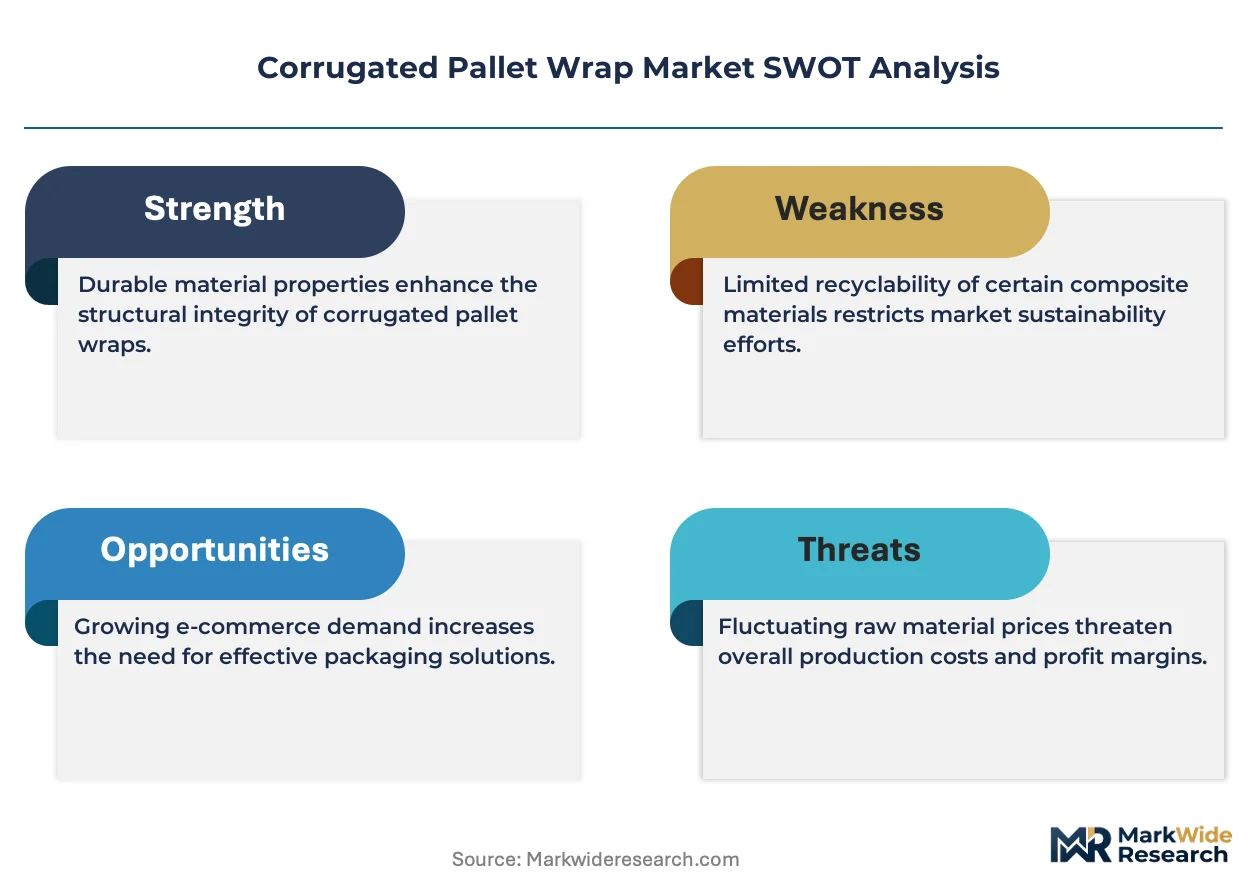
- Moisture barrier limitations:Kraft paper's inherent hydrophilicity requires wax or polymer coatings that complicate recyclability and add processing steps.
- Plastic film incumbency:Linear low-density polyethylene stretch systems retain cost advantages below 500-unit pallet volumes, blocking penetration in small-lot logistics.
Strategic Opportunities
- Nordic cold-chain expansion:Norwegian and Swedish seafood exporters need vapor-barrier corrugated wrap for frozen pallet loads, a specification gap unaddressed by standard kraft grades.
- Barrier-coating chemistry convergence:Bio-based polylactic acid and chitosan treatments are nearing commercial scale for fiber-contact applications under EFSA migration limits.
- Reverse logistics channel development:Pooled pallet programs operated by CHEP and LPR create closed-loop collection infrastructure for used wrap, enabling deposit-return circularity models.
Industry Challenges
- Multilayer adhesive compliance:REACH restrictions on isocyanate-based bonding agents force reformulation of high-strength corrugated laminates, extending R&D timelines.
- Load-stability certification backlog:Eumos 40509 transit-vibration testing for paper-based containment lacks accredited lab capacity in Eastern Europe, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Pallet Wrap Market |
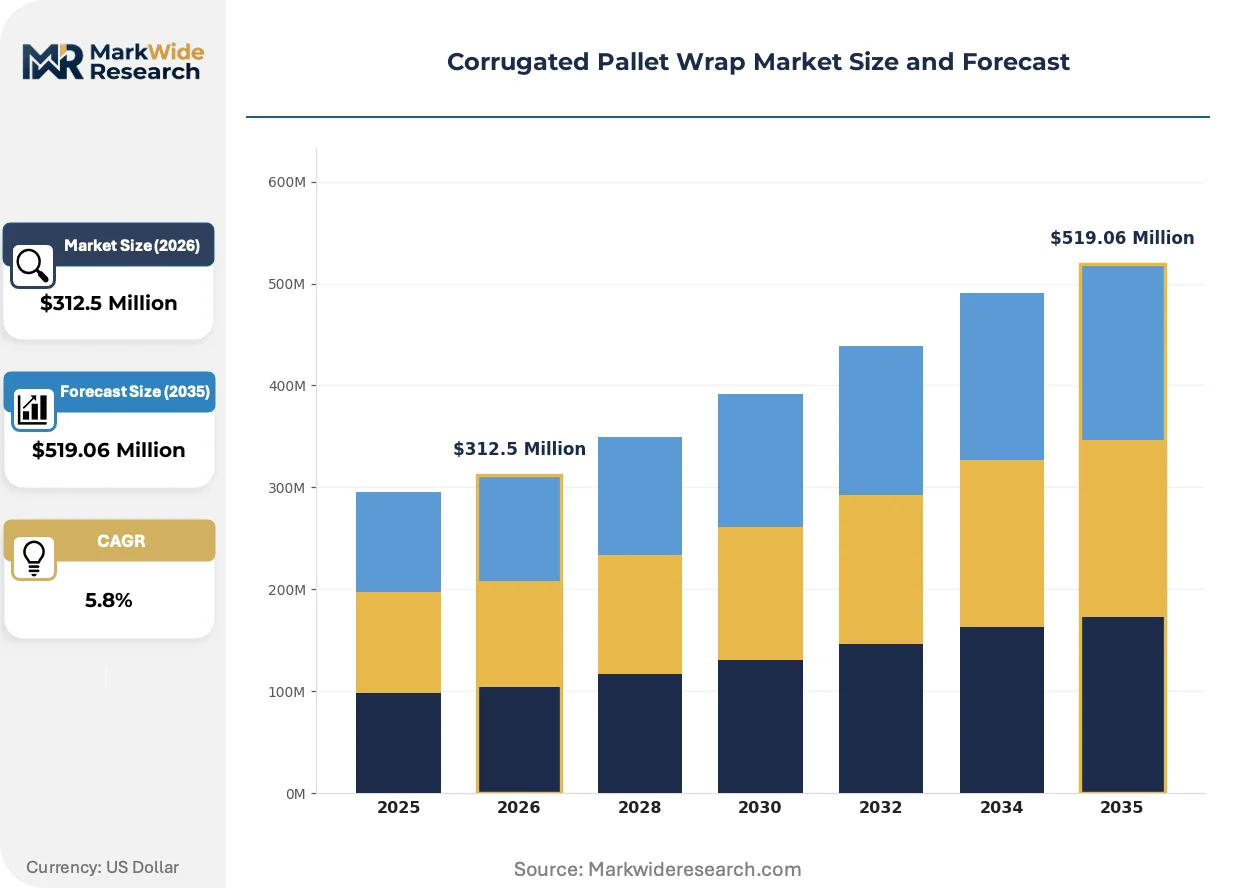
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty Wrap, Eco-Friendly Wrap, Stretch Wrap, Custom Wrap Application: Logistics, Warehousing, Retail Display, Export Shipping End User: Manufacturers, Distributors, Retailers, Exporters Material: Polyethylene, Paper, Biodegradable Material, Composite Material |
| Companies Covered | International Paper Company, Smurfit Kappa Group, WestRock Company, Mondi Group, DS Smith Plc, Sealed Air Corporation, Pregis LLC, Storopack, Ranpak Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Pallet Wrap Market Strategic Shifts
Active R&D in barrier coatings and scoring automation is compressing the performance gap between fiber-based containment and plastic alternatives while regulatory pressure accelerates specification changes.
Water-based acrylic barrier coatings are converging with nano-cellulose reinforcement layers to create humidity-resistant corrugated wrap that maintains EFSA-compliant fiber-contact safety. Food exporters in the Netherlands and Belgium are piloting these hybrid structures for chilled dairy pallet loads. The technology is converging with automated scoring equipment to produce variable-depth creases that adapt to irregular load geometries without stretch film backup.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated grease barriers from food-contact pallet wrap formulations. Converters must substitute with bio-based alternatives or lose access to EU food logistics contracts. German and French packaging engineers are accelerating validation of plant-derived wax emulsions under ECHA guidance timelines.
Buyer consolidation among European grocery retailers is compressing supplier qualification cycles for transport packaging. Lidl and Aldi South are unbundling pallet-wrap specification from third-party logistics contracts, forcing direct vendor relationships with corrugated converters. This pattern is most visible in the Benelux region where centralized procurement hubs now mandate ISO 14001-certified fiber containment for all ambient-goods inbound freight.
Corrugated Pallet Wrap Market Segmentation
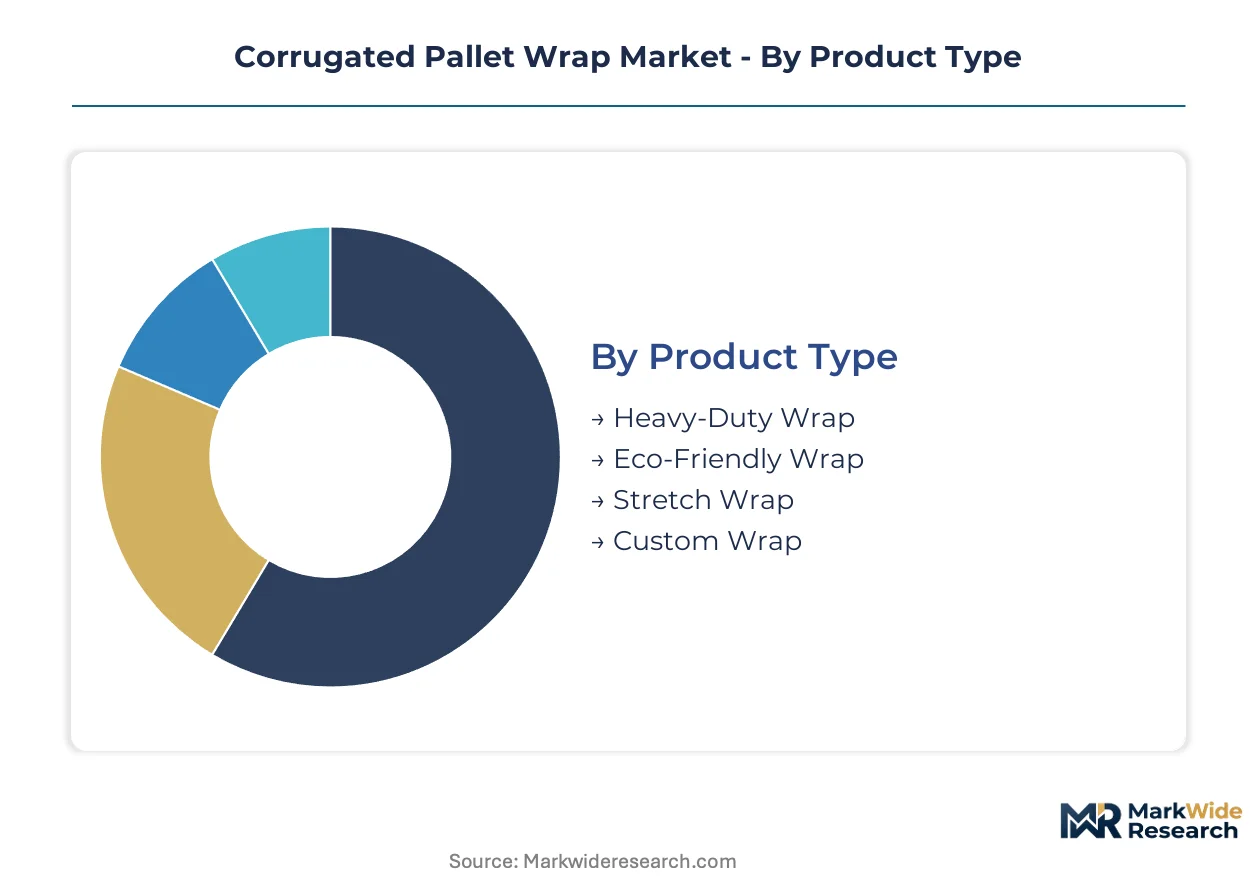
Segmentation in corrugated pallet wrap reflects divergent technical requirements across load densities, moisture exposure, and circularity mandates. Specification choices determine fiber grade, coating chemistry, and scoring patterns that converters must align with end-use certification standards.
Product Type:
Technology and specification axes dominate product differentiation, with load-bearing capacity and recyclability credentials driving specification splits.
- Heavy-Duty Wrap:Multi-layer kraft construction at 250–300 gsm with reinforced corrugation profiles withstands puncture from metal edges and dense industrial freight. German automotive parts distributors in Stuttgart and Wolfsburg specify this grade for powertrain component shipments under OEM sustainability scorecards.
- Eco-Friendly Wrap:Certified recycled-content grades incorporating post-consumer OCC fiber and bio-based barrier coatings meet CSRD-driven Scope 3 reporting requirements. Retailers facing disclosure obligations mandate this specification from upstream suppliers to hit net-zero commitments.
- Stretch Wrap:Scored and folded paper structures with elastic recovery properties compete directly with linear low-density polyethylene film in unit-load containment.
- Custom Wrap:Bespoke dimensions and printed branding surfaces serve promotional pallet displays and irregular load geometries.
Mature deployment sits with Heavy-Duty Wrap in automotive and machinery logistics. Newer deployment is concentrated in Eco-Friendly Wrap as EPR schemes penalize petroleum-based alternatives.
Application:
Cost tier and volume throughput shape application segmentation, with transit distance and handling frequency determining wrap specification economics.
- Logistics:High-velocity distribution centers specify tear-resistant grades for automated stretch-hooding equipment. Lidl and Aldi South procurement hubs mandate ISO 14001-certified fiber containment for ambient-goods inbound freight.
- Warehousing:Long-duration static storage drives moisture-vapor transmission rate specifications for inventory protection.
- Retail Display:Printed surface grades with high-quality flexographic reproduction serve promotional pallet presentations.
- Export Shipping:Maritime humidity and multi-modal handling stress barrier-coating performance for intercontinental freight.
Mature deployment sits with Logistics in high-throughput distribution networks. Newer deployment is concentrated in Export Shipping as bio-based barrier coatings near commercial scale under EFSA migration limits.
End User:
Customer type and procurement sophistication segment end-user demand, with sustainability reporting maturity determining specification stringency.
- Manufacturers:Vertically integrated production facilities specify wrap systems that integrate with automated palletizing lines. Benelux food producers pilot nano-cellulose hybrid structures for chilled dairy loads.
- Distributors:Third-party logistics providers balance unit economics against retailer certification requirements.
- Retailers:Centralized procurement functions unbundle pallet-wrap specification from 3PL contracts, forcing direct vendor relationships with corrugated converters.
- Exporters:Seafood and frozen food shippers in Norway and Sweden need vapor-barrier specifications unaddressed by standard kraft grades.
Mature deployment sits with Manufacturers with captive packaging engineering. Newer deployment is concentrated in Retailers as buyer consolidation compresses supplier qualification cycles.
Material:
Supply concentration and circularity certification segment material sourcing, with fiber provenance and coating chemistry determining regulatory compliance pathways.
- Polyethylene:Linear low-density stretch film retains cost advantages below 500-unit pallet volumes, blocking fiber penetration in small-lot logistics.
- Paper:Virgin and recycled kraft fiber supply chains anchor converter margins, with OCC price volatility swinging with Chinese import quotas.
- Biodegradable Material:Polylactic acid and chitosan treatments are accelerating validation under ECHA guidance timelines for food-contact applications.
- Composite Material:Multilayer structures combining fiber substrates with barrier films face REACH restrictions on adhesive bonding agents.
Mature deployment sits with Paper across European containerboard mill networks. Newer deployment is concentrated in Biodegradable Material as fluorinated grease barriers face elimination under REACH Annex XVII.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European corrugated pallet wrap demand as automotive parts distributors abandon plastic stretch film under OEM sustainability scorecards. The EU Packaging and Packaging Waste Regulation hardens recycled-content thresholds across member states, compressing specification windows for fiber-based alternatives. Rotterdam and Antwerp ports handle rising volumes of paper-wrapped export pallets as Dutch and Belgian food exporters pilot nano-cellulose hybrid structures.
Germany
Automotive clusters in Stuttgart and Wolfsburg specify Heavy-Duty Wrap grades for powertrain component shipments. The EU Green Deal's packaging-waste reduction targets force converters to certify circularity credentials through accredited recycling streams. Bavarian machinery manufacturers integrate corrugated containment systems into automated palletizing lines.
Netherlands
Benelux food producers pilot nano-cellulose reinforced structures for chilled dairy pallet loads under EFSA migration limits. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances eliminate fluorinated grease barriers from food-contact formulations. Rotterdam port terminals handle increasing paper-wrapped pallet volumes for intercontinental seafood exports.
France
Paris-based retail procurement hubs unbundle pallet-wrap specification from third-party logistics contracts under CSRD disclosure obligations. ECHA guidance timelines accelerate validation of plant-derived wax emulsions for barrier coatings. Lyon packaging engineers develop automated scoring equipment for variable-depth creases adapting to irregular load geometries.
Sweden
Seafood exporters in Gothenburg need vapor-barrier specifications unaddressed by standard kraft grades for frozen pallet loads. The EU Packaging and Packaging Waste Regulation tightens recycled-content thresholds for transport packaging across Nordic supply chains. Stockholm converters partner with CHEP on pooled pallet programs creating closed-loop collection infrastructure for used wrap.
United States
Chicago distribution centers specify tear-resistant grades for automated stretch-hooding equipment in high-velocity logistics networks. EPA circular economy initiatives align with retailer sustainability mandates pulling exporters toward certified recyclable wrap systems. California food processors face Scope 3 emissions accounting requirements under state climate disclosure laws.
Corrugated Pallet Wrap Market Competitive Environment
The competitive structure tilts toward integrated containerboard producers with captive fiber supply and barrier-coating R&D capabilities. Market participants cluster around three strategic archetypes: multinational paper and packaging conglomerates with mill networks, specialized protective packaging engineers with automation integration expertise, and emerging fiber-based containment specialists targeting plastic displacement. Dominant competitive moves include backward integration into OCC fiber sourcing and strategic partnerships with pooled pallet operators to secure closed-loop collection infrastructure.
Among integrated paper and packaging conglomerates, Smurfit Kappa Group and Mondi Group exemplify the scale-driven archetype with European mill networks and kraft-paper specialization. DS Smith Plc occupies a position within the circular-design services tier, helping exporters eliminate plastic pallet containment through fiber-based system engineering. International Paper Company anchors the North American competitive set with containerboard production capacity serving logistics and food-sector demand.
| Leading Market Players |
|---|
| International Paper Company |
| Smurfit Kappa Group |
| WestRock Company |
| Mondi Group |
| DS Smith Plc |
| Sealed Air Corporation |
| Pregis LLC |
| Storopack |
| Ranpak Holdings |
| Others |
Value Chain & Pricing Dynamics
Captive integration into containerboard mill networks anchors converter supply positions and pricing power, as Smurfit Kappa and Mondi leverage in-house fiber supply to buffer OCC volatility while commanding premium tiers for certified circularity grades under EU Green Deal mandates.
Pricing Analysis
Throughput-linked pricing anchors contract structures, with automotive OEMs and retail procurement hubs paying per-pallet-unit rates that scale with containment performance guarantees. Price differentiation separates EFSA-certified food-contact grades from industrial logistics specifications, while volume rebates compress margins for sub-500-unit orders. Cost compression in standard kraft grades intensifies as Chinese OCC import quotas swing feedstock availability. Small-lot distributors exhibit highest price sensitivity; integrated manufacturers with captive palletizing lines show lowest.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and Sweden concentrate finished-goods inventory, feeding hub-and-spoke patterns into automotive clusters and Benelux retail hubs. Raw material flows draw from Swedish and Finnish pulp mills, German OCC recovery streams, and French starch adhesive suppliers. Single-source vulnerability concentrates in barrier-coating chemistries facing REACH reformulation timelines. Distribution runs through CHEP and LPR pooled pallet networks enabling closed-loop wrap collection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is reshaping competitive positioning, with upstream control over recycled fiber supply and downstream captive demand from automotive OEMs emerging as the decisive margin levers.
For Market Incumbents: Lock in fiber supply security through long-term OCC offtake agreements with German and French waste management consortia. Certify Eumos 40509 load-stability testing capacity in Eastern Europe to clear product launch backlogs before REACH adhesive restrictions tighten. Bio-based barrier coating R&D investment defends premium positioning against fluorinated grease barrier phase-out. For New Entrants and Emerging Players: Small-lot seafood exporters in Norway and Sweden represent an underserved buyer archetype demanding vapor-barrier specifications unmet by incumbent kraft grades. Pilot plant-derived wax emulsion coatings under ECHA guidance timelines to capture Nordic cold-chain conversion. Direct technical sales engagement with Gothenburg port logistics operators bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated containerboard producers with captive mill networks and barrier-coating patent portfolios. Five-to-ten year viability favors converters securing accredited recycling stream certification before national EPR schemes alter plastic-versus-paper cost structures. Watch for Eumos 40509 lab capacity expansion announcements as inflection signal for product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OCC Fiber Sourcing | Long-term supply agreements with German waste consortia stabilize feedstock costs against Chinese import quota volatility. |
| Bio-Based Barrier Coating Scale-Up | Plant-derived wax emulsion validation under ECHA timelines secures food-contact positioning as fluorinated barriers face elimination. |
| Automated Scoring Equipment Deployment | Lyon-engineered variable-depth crease technology adapts to irregular automotive load geometries without stretch film backup. |
| Pooled Pallet Program Partnership | CHEP and LPR closed-loop infrastructure enables deposit-return circularity models for used wrap collection. |
| Eumos 40509 Certification Investment | Accredited Eastern European lab capacity clears transit-vibration testing backlogs delaying product launches. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated with primary interviews across containerboard mill operations managers, automotive procurement leads at Stuttgart OEMs, corrugated converter technical directors, retail sustainability officers at Benelux grocery hubs, and barrier-coating R&D chemists. Bottom-up pallet-volume modeling converged with top-down packaging spend analysis across the projection horizon.
Granularity-level modeling disaggregated volume and value outputs by product type tier, application throughput intensity, end-user procurement sophistication, and material circularity certification grade. CAGRs derived from segment-level growth rate convergence across German automotive cluster conversion trajectories, Dutch food exporter pilot adoption curves, and Nordic cold-chain specification gaps. Forecast inputs incorporated REACH adhesive restriction timelines and EPR scheme rollout schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to OCC price volatility, barrier-coating chemistry validation delays, and Eumos 40509 lab capacity expansion timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
India Pallets Market
Pallets Packaging
North America Pallet Market
Pallets Packaging
Pallet Bands Market
Pallets Packaging
Wire Cage Pallet Collar Market
Pallets Packaging
China Pallets Market
Pallets Packaging
Latin America Pallet Market
Pallets Packaging
Pallet Corner Boards Market
Pallets Packaging
Asia-Pacific Lumber Pallet Market
Pallets Packaging
Pallet Banding Machine Market
Pallets Packaging
Pallet Labelling System Market
Pallets Packaging
Palletizer Market
Pallets Packaging
Stretch Hood Pallet Wrapping Market
Pallets Packaging
North America Lumber Pallet Market
Pallets Packaging
Global Pallet Racking System Market
Pallets Packaging
Germany Pallets Market
Pallets Packaging
Foldable Plastic Pallet Boxes Market