
 North America Lumber Pallet Market | 2026-2036
North America Lumber Pallet Market Size, Share, and Industry Trends Forecast 2026-2036
North America Lumber Pallet Market Analytics
E-commerce fulfillment is decoupling from traditional retail replenishment as the dominant demand driver for new pallet flows. UFP Industries anchors its position through backward integration into sawmill operations across the US Southeast. PalletOne competes via dense manufacturing footprints in Florida and Texas that compress delivery lead times.
North America lumber pallets are load-bearing platforms fabricated from hardwood or softwood lumber, typically assembled with nails or staples to ISO 6780 dimensional tolerances, and engineered to support unitized goods through mechanized handling systems. Solid wood pallets sustain the largest volume share due to repairability and lower first cost, while block pallets command premium positioning in automated warehouse environments where four-way entry reduces handling cycle time. The 48x40 specification dominates cross-border freight between the US, Mexico, and Canada because it aligns with grocery and mass retail racking standards.
The US Lacey Act and Canadian CFIA wood packaging requirements constrain untreated lumber movement across borders, compelling heat treatment or fumigation certification for export-bound stock. OSHA ergonomic guidelines and state-level weight limits influence deckboard thickness specifications and worker safety investments. Stakeholders must weigh repair network density against new-build automation as labor availability tightens in Midwest manufacturing zones.
Market Dynamics
E-commerce fulfillment centers are compressing pallet replacement cycles and demanding four-way entry block pallets that accelerate automated warehouse throughput. This demand surge is colliding with hardwood supply constraints in the US Southeast, forcing manufacturers to reconfigure material sourcing and repair network density.
Growth Catalysts
- US Lacey Act amendments:Illegal logging verification requirements are driving certified sustainable lumber adoption, creating compliance-linked demand for heat-treated pallets with documented chain-of-custody.
- Automated warehouse expansion:Distribution centers in Michigan, Ohio, and Illinois are specifying block pallets with RFID integration to reduce handling cycle time in high-velocity fulfillment environments.
- Cross-border manufacturing integration:US-Mexico-Canada Agreement trade flows are standardizing 48x40 pallet specifications across automotive and appliance supply chains, consolidating replacement demand.
Market Restraints
- Hardwood lumber price volatility:Oak and maple input costs fluctuate with housing construction cycles, compressing margin predictability for new-build pallet manufacturers.
- Canadian CFIA wood packaging requirements:Heat treatment or fumigation mandates for export-bound stock add certification cost and transit delay friction at US-Canada border crossings.
- Plastic pallet substitution:Closed-loop beverage and pharmaceutical logistics are migrating to injection-molded alternatives that eliminate repair requirements and moisture absorption.
Strategic Opportunities
- Texas and Florida manufacturing expansion:Dense population growth and port proximity create underpenetrated demand for rapid-turn pallet pooling services in southeastern logistics corridors.
- OSHA ergonomic guideline alignment:Deckboard thickness and weight limit specifications are opening premium positioning for lightweight engineered wood composites that reduce worker injury claims.
- Pallet repair network digitization:IoT-enabled asset tracking and predictive maintenance scheduling are converging with pooled pallet programs to capture aftermarket service revenue.
Industry Challenges
- Certified heat-treatment capacity:ISPM-15 compliance backlog at Midwest treatment facilities is extending order fulfillment timelines for export-bound manufacturers.
- Sawmill labor availability:Equipment operator and maintenance technician shortages in Michigan and Ohio are constraining backward integration into captive lumber supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Lumber Pallet Market |
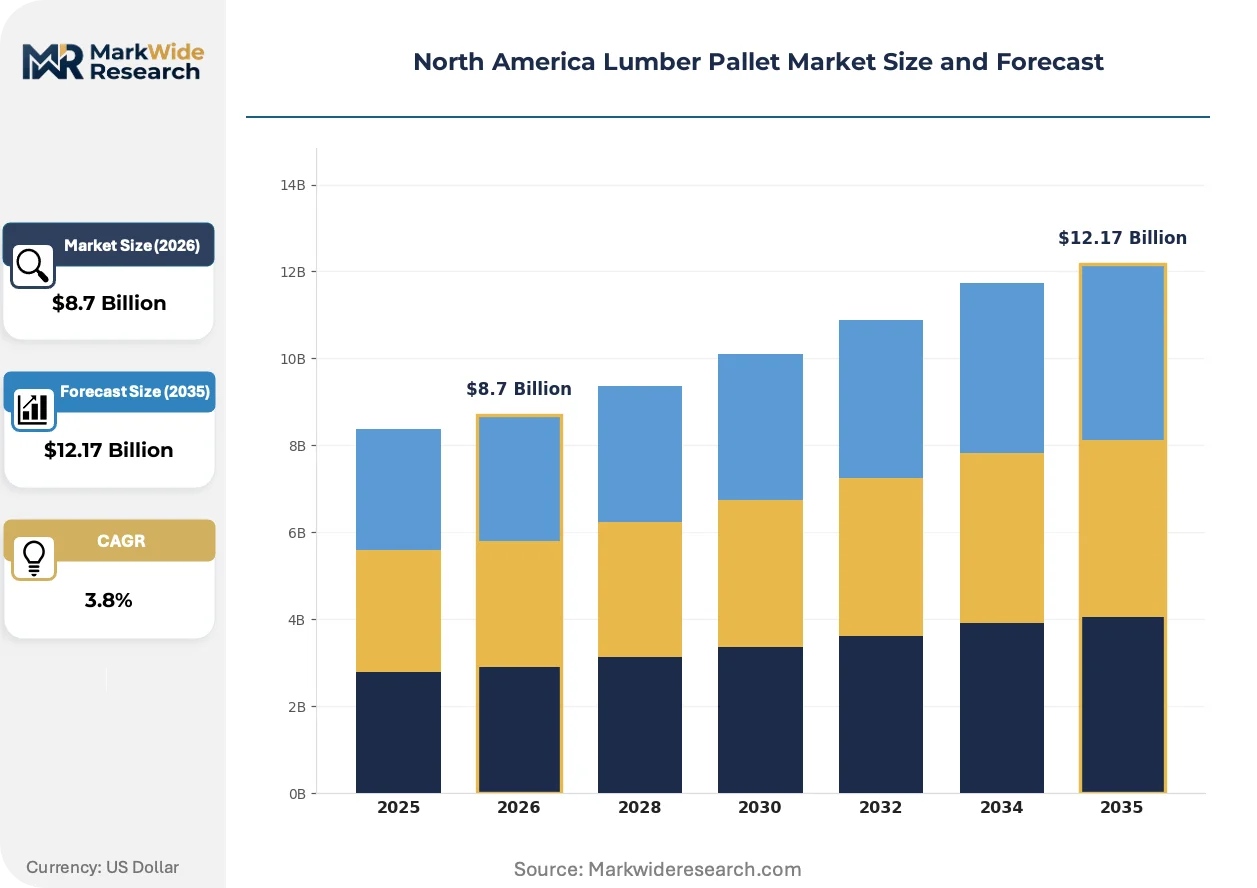
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plywood Pallets, Solid Wood Pallets, Block Pallets, Combo Pallets End User: Food & Beverage, Retail, Logistics, Pharmaceutical Size: 48x40, 48x48, 40x40, 36x36 Distribution Channel: Online, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Brambles Limited, PalletOne Inc., PECO Pallet, Inc., UFP Industries, Inc., Menasha Corporation, Millwood, Inc., John Rock Inc., Kamps Pallets Inc., ORBIS Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Lumber Pallet Market Evolving Landscape
Digital tracking technologies and material science advances are reconfiguring how pallet assets move through supply chains. These developments are compressing replacement cycles while opening new service revenue streams.
RFID-embedded lumber pallets are expanding into grocery and mass retail distribution networks where real-time location tracking reduces inventory shrinkage. Kroger and Walmart distribution centers in Illinois and Ohio are mandating tagged pallets for supplier compliance. This technology is expanding into secondary markets by enabling outcome-based pooling contracts that charge per-trip rather than per-unit.
USDA and CFIA harmonization efforts on heat-treatment certification are reducing duplicate inspection requirements at US-Canada border crossings. The streamlined documentation protocol cuts customs clearance time for automotive parts shipments. Midwest manufacturers with integrated treatment kilns are capturing share from non-compliant competitors facing detention penalties.
Buyer consolidation among third-party logistics providers is compressing supplier qualification timelines and unbundling repair services from new-build contracts. XPO and Ryder facilities in Texas are awarding multi-year pallet management agreements to vendors with dense service footprints. This concentration is most visible in the Great Lakes corridor where regional 3PL mergers have reduced qualified vendor pools by half.
North America Lumber Pallet Market Segmentation
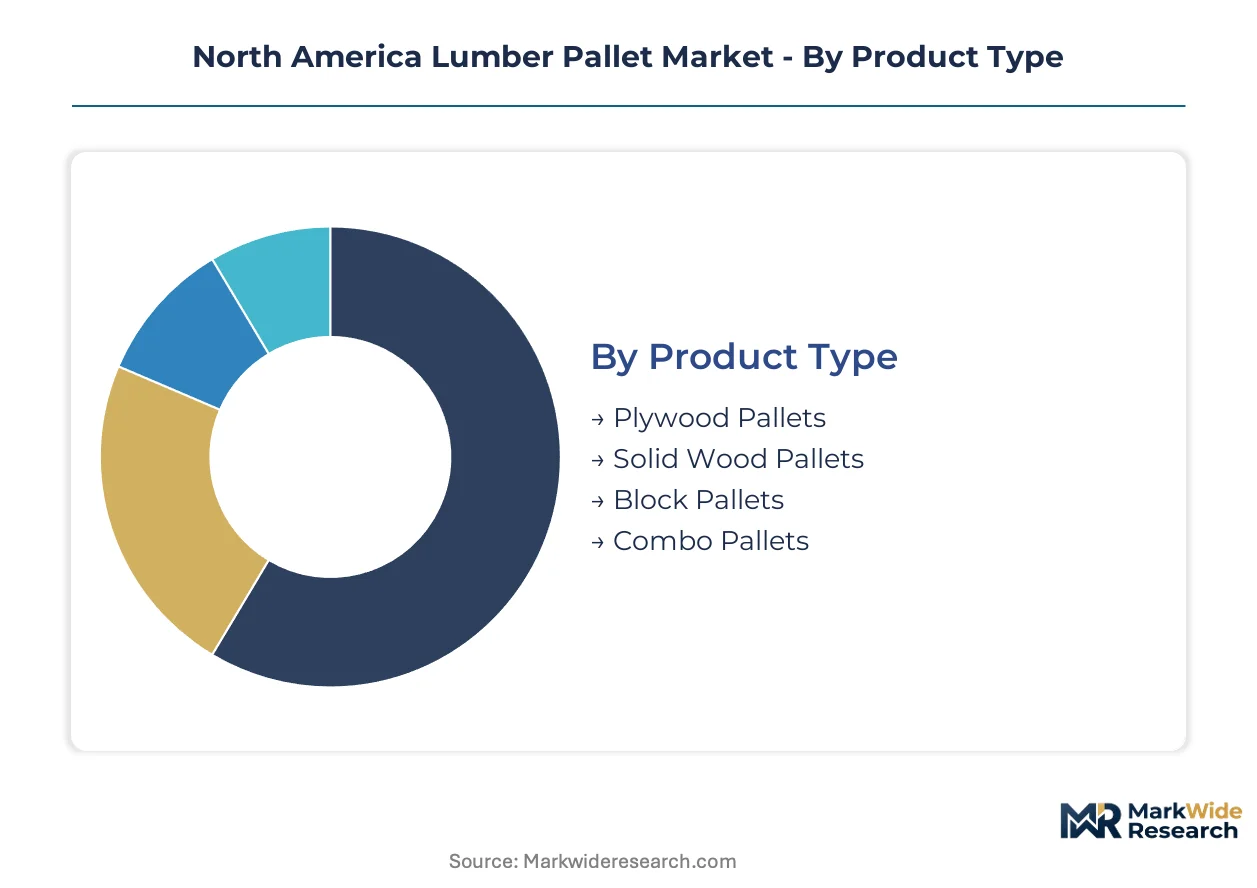
Lumber pallet segmentation reveals how material choice, dimensional standardization, and channel configuration shape procurement economics across North American supply chains. Each dimension carries distinct compliance burdens and automation compatibility requirements that influence supplier selection criteria.
Product Type:
Solid wood platforms dominate standalone deployment in conventional warehousing, while block and composite configurations embed into automated systems demanding four-way entry.
- Solid Wood Pallets:Fabricated from hardwood or softwood deckboards fastened to stringer runners, these platforms tolerate repeated repair cycles and absorb impact without catastrophic failure. Demand concentrates in Great Lakes automotive parts distribution where ISPM-15 heat treatment certification supports cross-border Mexico-Canada freight flows. The US Lacey Act verification requirements favor domestic oak and maple sourcing with documented chain-of-custody.
- Block Pallets:Engineered with nine rectangular wood blocks connecting top and bottom deckboards, enabling forklift entry from all four sides. Michigan and Ohio fulfillment centers specify these for automated storage retrieval systems where reduced handling cycle time justifies premium first cost. RFID embedding is standard for Kroger and Walmart supplier compliance mandates.
- Plywood Pallets:Laminated veneer construction offers uniform dimensional stability for lightweight pharmaceutical and electronics freight. Canadian CFIA wood packaging regulations require heat treatment certification for export-bound stock.
- Combo Pallets:Hybrid assemblies combining wood stringers with composite or metal components to reduce weight while maintaining load capacity. Texas and Florida 3PL facilities favor these for beverage pooling programs where moisture resistance extends asset life.
Solid wood pallets lead volumes today; block pallets are gaining share fastest.
End User:
Cost tier stratification separates commodity-sensitive food logistics from premium pharmaceutical cold chain requirements.
- Food & Beverage:Grocery distribution networks in Illinois and Ohio drive 48x40 specification standardization, with pooled pallet programs dominating high-volume produce and packaged goods movement. USDA harmonization with Canadian CFIA on heat-treatment documentation reduces border clearance friction for cross-border dairy and meat shipments.
- Retail:Mass merchant distribution centers mandate RFID-tagged pallets for real-time inventory tracking, compressing supplier qualification timelines to multi-year managed service contracts.
- Logistics:Third-party providers in Texas and Florida consolidate repair and new-build procurement under single-vendor agreements, unbundling legacy bundled service structures.
- Pharmaceutical:Temperature-validated lane requirements favor engineered wood composites with consistent moisture content to prevent contamination in FDA-regulated distribution environments.
Food and beverage anchors volume concentration; pharmaceutical applications are expanding most quickly.
Size:
Volume scale differentiates cross-border freight standards from niche industrial specifications.
- 48x40:The dominant North American footprint aligns with grocery industry racking standards and US-Mexico-Canada Agreement trade flows. Michigan automotive parts suppliers standardize on this dimension for just-in-time assembly plant replenishment.
- 48x48:Bulky appliance and HVAC equipment distribution favors this square configuration for stable drum and crate handling.
- 40x40:Asian import compatibility drives limited adoption in West Coast port corridors.
- 36x36:Specialized pharmaceutical and electronics freight employs this compact footprint for dense trailer cube utilization.
The 48x40 specification commands volume leadership; 48x48 is climbing the fastest on appliance supply chain standardization.
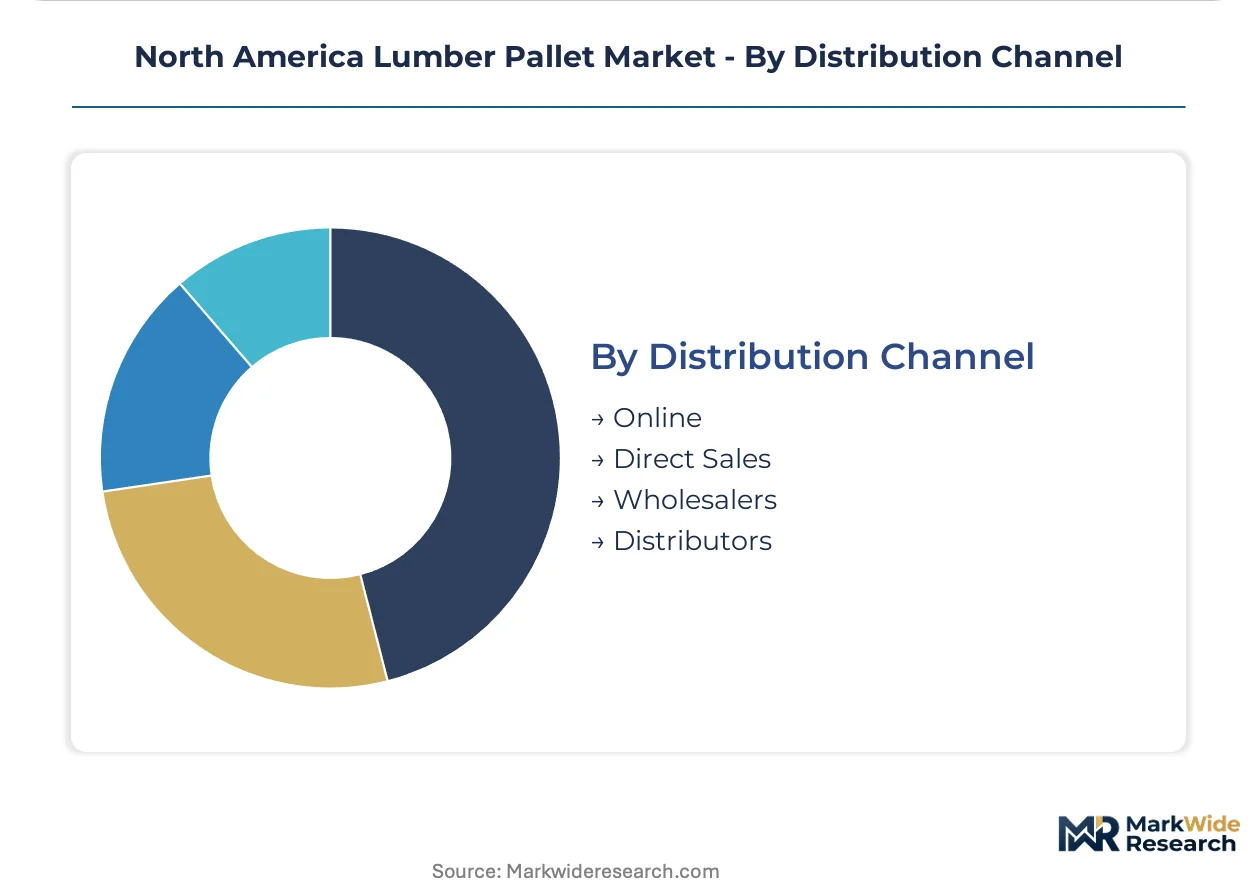
Distribution Channel:
Customer type and geography dictate channel selection between transactional spot buying and contracted managed services.
- Direct Sales:Large-volume automotive and appliance manufacturers in Ohio and Illinois negotiate multi-year supply agreements with integrated heat-treatment and RFID tagging services.
- Distributors:Regional pallet recyclers in Michigan and Texas maintain dense repair network footprints, capturing aftermarket service revenue through pooled program management.
- Wholesalers:Independent lumber yards and building material dealers serve construction and agricultural users with untreated stock for domestic-only applications.
- Online:E-procurement platforms facilitate spot purchasing for small and mid-sized 3PLs with irregular demand patterns.
Direct sales channels dominate value capture; distributor-managed pooling programs are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes industrial corridor spanning Michigan, Ohio, and Illinois anchors continental demand concentration. E-commerce fulfillment centers and automotive parts distribution networks drive pallet consumption across these interconnected manufacturing zones. Cross-border trade flows under the US-Mexico-Canada Agreement standardize procurement specifications throughout the region.
United States
Automotive assembly plants in Michigan and Ohio generate substantial just-in-time pallet demand for cross-border Mexico-Canada freight. The US Lacey Act amendments mandate illegal logging verification, compelling domestic manufacturers to document chain-of-custody for oak and maple sourcing. Chicago and Detroit distribution clusters specify RFID-embedded block pallets for automated warehouse compatibility.
Canada
CFIA wood packaging regulations require heat treatment or fumigation certification for all export-bound lumber pallets. Toronto and Montreal logistics hubs face compliance friction at US border crossings, favoring integrated treatment kiln investments. Canadian manufacturers with USDA-harmonized documentation protocols capture share from competitors facing detention penalties.
Mexico
Maquiladora manufacturing zones near the US border concentrate appliance and automotive parts production requiring standardized 48x40 pallet specifications. Mexican customs authorities align with USMCA trade documentation requirements, streamlining cross-border freight flows. Monterrey and Tijuana industrial corridors host dense pooling program networks serving multinational assembly operations.
North America Lumber Pallet Market Competitive Landscape
Backward integration into captive lumber supply dominates the current competitive landscape. The vendor base clusters around three strategic archetypes: vertically integrated sawmill operators, dense regional repair network specialists, and pooled asset management platforms. Consolidation pressure intensifies as labor scarcity in Midwest manufacturing zones favors scale-driven procurement consolidation. Geographic expansion and repair network digitization represent the two dominant competitive moves reshaping market positioning.
Among integrated fabricators, UFP Industries anchors the sawmill-backed archetype through in-house lumber production across the US Southeast. PalletOne exemplifies the dense manufacturing footprint model with rapid-turn delivery capabilities in Florida and Texas logistics corridors. Brambles Limited occupies the pooled asset management tier, representing the outcome-based service contracting approach that charges per-trip rather than per-unit.
| Leading Market Players |
|---|
| Brambles Limited |
| PalletOne Inc. |
| PECO Pallet, Inc. |
| UFP Industries, Inc. |
| Menasha Corporation |
| Millwood, Inc. |
| John Rock Inc. |
| Kamps Pallets Inc. |
| ORBIS Corporation |
| Others |
Value Network & Pricing Analysis
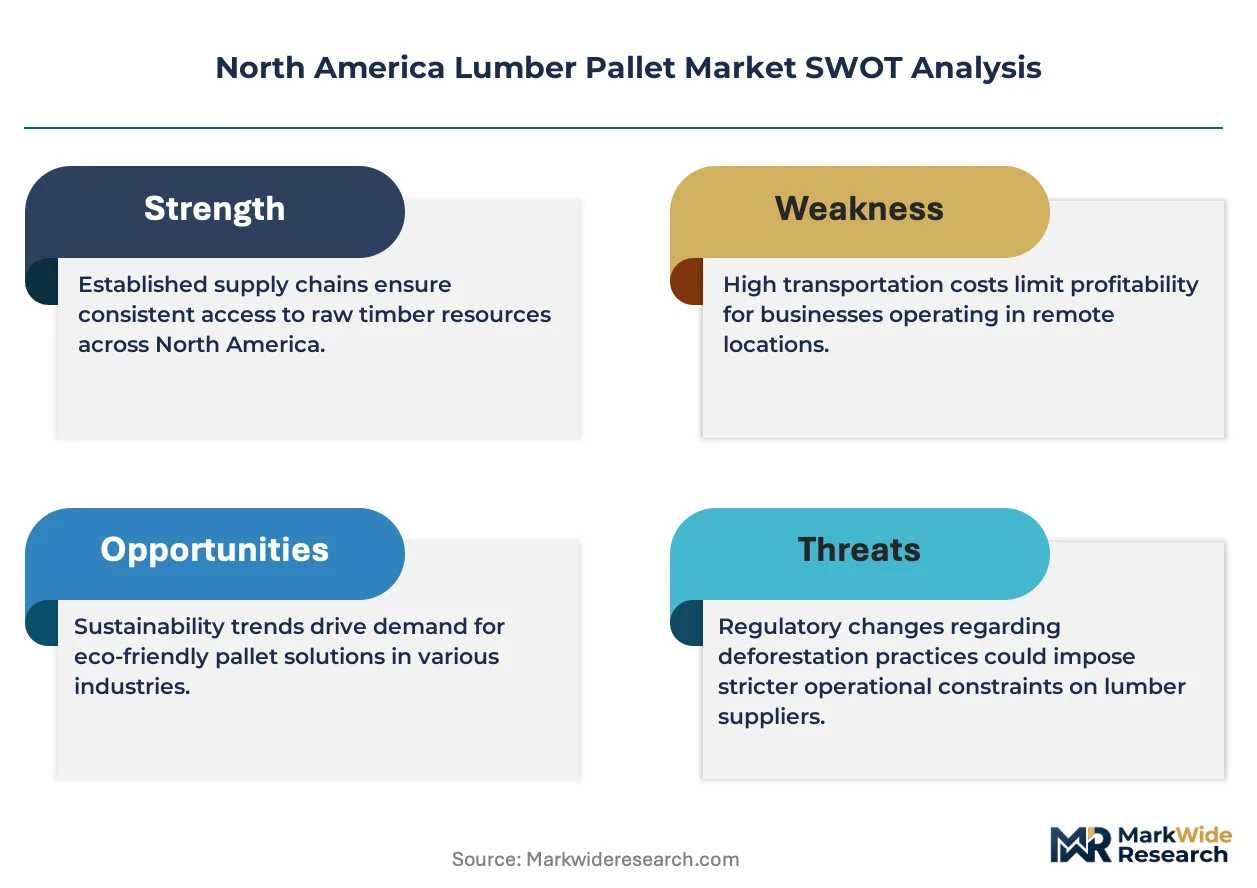
Family-owned mid-cap specialists across Michigan and Ohio anchor supply concentration, translating into pricing discipline that resists commoditization despite hardwood input volatility. Their captive repair networks and long-tenured customer relationships create switching costs that protect margin structures even when oak and maple prices fluctuate with housing construction cycles.
Pricing Analysis
Distributor margin layers separate direct-to-OEM contract pricing from spot-market transactions through regional recyclers. Three-tier pricing structure across ISPM-15 certified premium, heat-treated standard, and untreated economy levels reflects compliance burden and automation compatibility. Cost compression in the economy tier is intensifying because plastic substitution in beverage closed-loops siphons volume, while automotive OEMs demonstrate lowest price sensitivity due to just-in-time reliability requirements.
Supply Chain Analysis
Refurbishment flows from pooled program returns create a secondary lumber supply that dampens raw material price spikes across the US Southeast and Great Lakes corridors. Production draws from Appalachian oak forests, Canadian softwood imports, and Midwest maple stands, with ISPM-15 treatment capacity acting as the binding constraint. Single-source vulnerability concentrates at Midwest heat-treatment facilities facing compliance backlogs. Distribution runs through dense 3PL-managed networks in Texas and Florida rather than traditional lumber yard channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by e-commerce fulfillment centers mandating RFID-embedded block pallets that command sustained premium positioning over commodity stringer alternatives.
For Market Incumbents: Cement market position by deepening backward integration into captive sawmill operations across the US Southeast, insulating margin structures from hardwood price volatility. Expand ISPM-15 treatment kiln capacity in Michigan and Ohio to capture share from competitors facing export certification backlogs. Prioritize repair network digitization with IoT-enabled asset tracking to defend against pooled asset management platforms eroding aftermarket revenue. For New Entrants and Emerging Players: Third-party logistics consolidators represent the most penetrable channel partner type for rapid scale. Target underpenetrated rapid-turn pallet pooling services in Texas and Florida logistics corridors where population growth outstrips incumbent service density. Lead with lightweight engineered wood composites aligned to OSHA ergonomic guidelines, opening premium positioning in pharmaceutical and electronics verticals. For Investors and Strategic Acquirers: Valuations sit cheapest among regional repair network specialists with dense Midwest footprints and un-digitized asset bases. Long-term viability hinges on automation compatibility and compliance infrastructure rather than commodity manufacturing scale. Monitor ISPM-15 treatment capacity utilization rates and USDA-CFIA harmonization progress as inflection indicators for margin expansion potential.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sawmill Operations | UFP Industries anchors competitive positioning through captive lumber supply across the US Southeast. |
| Heat-Treatment Capacity Expansion | Midwest manufacturers with integrated kilns capture share from competitors facing CFIA detention penalties. |
| RFID Embedding and Asset Tracking | Kroger and Walmart distribution centers mandate tagged pallets for supplier compliance in Illinois and Ohio. |
| Repair Network Digitization | IoT-enabled predictive maintenance converges with pooled programs to capture aftermarket service revenue. |
| Geographic Expansion to Southeast Corridors | Texas and Florida port proximity creates underpenetrated demand for rapid-turn pooling services. |
Research Methodology
Multiple input streams — structured interviews with pallet manufacturing executives, procurement leads at third-party logistics providers, and sawmill operations managers, alongside regulatory filings from USDA and CFIA, customs trade data, and SEC disclosures from publicly traded fabricators — were reconciled through bottom-up volume triangulation and top-down value validation. Primary fieldwork captured operational constraints around ISPM-15 treatment capacity and hardwood sourcing patterns. Secondary sources included automotive production databases, e-commerce fulfillment center expansion trackers, and OSHA ergonomic guideline documentation.
Data-stream reconciliation across product type, end-user vertical, dimensional specification, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level demand modeling incorporating e-commerce penetration rates, cross-border trade flow standardization under USMCA, and automation adoption curves in Great Lakes distribution clusters. Industry-specific forecast inputs included hardwood lumber price indices and heat-treatment facility capacity utilization surveys.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to plastic substitution rates in beverage logistics and sawmill labor availability in Midwest manufacturing zones. Practitioners should monitor USDA-CFIA harmonization implementation and 3PL buyer consolidation velocity for early signals of competitive structure shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Wooden Pallet Collars Market
Pallets Packaging
PUR Shippers Market
Pallets Packaging
Middle East Pallets Market
Pallets Packaging
UK Pallets Market
Pallets Packaging
Corrugated Pallet Wrap Market
Pallets Packaging
Pallet Bands Market
Pallets Packaging
Pallet Banding Machine Market
Pallets Packaging
Empty Fruit Bunch Pallets Market
Pallets Packaging
Pallet Labeler Market
Pallets Packaging
Foldable and Collapsible Pallets Market
Pallets Packaging
Pallet Labelling System Market
Pallets Packaging
Canada Pallets Market
Pallets Packaging
China Pallets Market
Pallets Packaging
Italy Pallets Market
Pallets Packaging
Corrugated Pallets Market
Pallets Packaging
Stringer Pallets Market