
 Painting Robot Market | 2026-2036
Painting Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Painting Robot Market Intelligence
The unbundling of monolithic painting lines into modular, reconfigurable robotic cells is recalibrating buyer preferences toward flexibility and scalability. This shift allows for more customized automation solutions tailored to specific tasks. FANUC Corporation leverages its extensive range of industrial robotic arms to serve diverse payload requirements. ABB differentiates through its advanced process control software and simulation tools, while Dürr AG sustains its market position by providing integrated, turnkey paint shop solutions primarily for automotive clients.
A painting robot is an automated multi-axis manipulator designed to apply liquid or powder coatings onto a surface with high precision. These systems utilize specialized end-effectors like rotary atomizers or electrostatic spray guns to achieve consistent film thickness and finish quality. Their primary industrial purpose is to automate painting processes, enhancing transfer efficiency and reducing material waste. Demand from automotive manufacturers continues to anchor the market, while the furniture production segment shows significant adoption for finishing applications. Collaborative robots are emerging as a key product type for smaller workshops.
Regulatory frameworks directly influence system design and adoption. In the United States, EPA rules on VOC emissions drive demand for efficient robotic systems that minimize overspray. The EU's Machinery Directive, enforced through CE marking, imposes strict safety requirements on robotic work cells. Globally, compliance with ISO 10218 standards for industrial robot safety is critical for market access. Future investment decisions for end-users will hinge on balancing the upfront capital cost of automation against long-term gains in material efficiency and labor savings.
Market Dynamics
The central dynamic shaping the painting robot market is the strategic unbundling of large, fixed painting lines into smaller, reconfigurable robotic cells. This evolution prioritizes operational flexibility and scalability over monolithic throughput, altering procurement criteria for manufacturers globally.
Growth Catalysts
- Automotive Quality Standards:Demand from automotive manufacturers, particularly in China's industrial hubs, for flawless and consistent finishes on complex vehicle bodies necessitates the precision of multi-axis robotic painting to meet OEM specifications.
- Regulatory VOC Reduction Mandates:Regulations such as REACH in Europe impose strict limits on volatile organic compound emissions, compelling industries to adopt robotic systems with high transfer efficiency to minimize material waste and ensure compliance.
- Advancements in Application Technology:The development of sophisticated end-effectors, including electrostatic rotary atomizers, improves paint transfer efficiency and finish quality, justifying the investment for industries like furniture and aerospace manufacturing.
Market Restraints
- High Initial Capital Outlay:The significant upfront investment required for robotic systems, including integration and safety infrastructure, presents a substantial barrier to adoption for small and medium-sized enterprises (SMEs) in the general manufacturing sector.
- Programming Complexity:Creating and adjusting robot paths for custom or low-volume production runs requires specialized programming expertise, limiting flexibility for non-standardized painting tasks and increasing operational costs.
- Component Supply Concentration:A reliance on a limited number of global suppliers for critical components like specialized atomizers and controllers creates potential supply chain vulnerabilities and pricing pressure for system integrators.
Strategic Opportunities
- Expansion into Aerospace Finishing:The aerospace industry offers a significant opportunity for applying specialized coatings that require extreme precision and process documentation, a task well-suited for advanced robotic systems with integrated quality control.
- AI and Machine Vision Integration:Combining painting robots with AI-powered vision systems enables real-time defect detection and automatic path correction, creating a new value proposition centered on autonomous quality assurance.
- Adoption in Construction and Infrastructure:Emerging applications for painting large structural components, such as bridge sections or prefabricated building modules, in controlled factory environments represent a new frontier for large-payload painting robots.
Industry Challenges
- Skilled Technician Shortage:A persistent lack of technicians trained in robotic programming, diagnostics, and maintenance hinders the effective deployment and long-term upkeep of automated painting systems across various industries.
- Legacy System Integration:Integrating modern robotic cells with older, existing factory floor control systems and Manufacturing Execution Systems (MES) often results in complex, costly, and time-consuming projects.
- Compliance with Safety Standards:Adhering to stringent, and sometimes divergent, global and regional safety standards, such as ISO 10218, requires extensive risk assessments and specialized safety hardware, adding cost and complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Painting Robot Market |
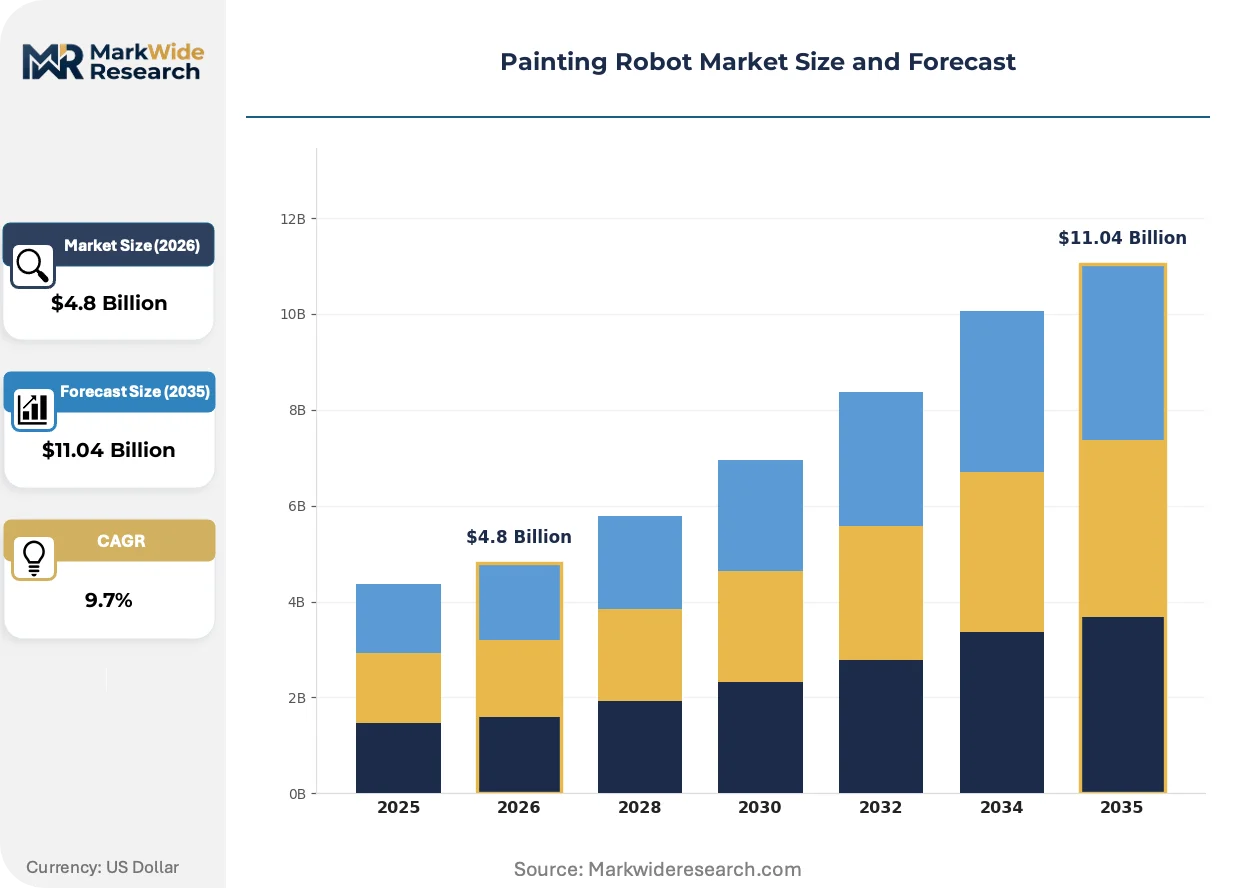
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collaborative Robots, Industrial Robots, Automated Guided Vehicles, Robotic Arms Technology: 3D Printing, AI Integration, Dry Spraying, Atomization End User: Automotive Manufacturers, Aerospace, Construction, Furniture Production Application: Surface Coating, Wall Painting, Furniture Finishing, Industrial Coating |
| Companies Covered | Yaskawa Electric Corporation, Dürr AG, ABB, Comau, Staubli International AG, FANUC Corporation, Kawasaki Heavy Industries, Nachi-Fujikoshi Corp, KUKA AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Painting Robot Market Strategic Shifts & Innovations
The market's evolution is defined by the fusion of advanced software control with more adaptable hardware, driven by sustainability mandates and the need for flexible production. This shift moves the focus from pure speed to intelligent, efficient, and data-driven coating application.
Collaborative robots, or cobots, designed for painting applications are gaining traction. These systems are adopted by small and medium-sized workshops, particularly in the furniture and metal fabrication sectors, due to their smaller footprint and ease of programming. A cobot is automating finishing tasks on high-mix, low-volume parts that were previously impractical for traditional industrial robot automation.
European Union regulations, specifically the Industrial Emissions Directive, are tightening controls on solvent use and emissions from industrial coating processes. This directive is forcing a re-evaluation of painting technologies to ensure compliance. The automotive and general metal finishing industries are most affected, accelerating investment in robotic systems that support waterborne paints or high-solids coatings.
A notable behavioral shift is the move away from purchasing individual hardware components toward acquiring fully integrated, task-specific modular work cells from a single-source supplier. This disrupts the traditional model where end-users managed multiple vendors and complex integration projects. This trend is most prominent in the North American electronics manufacturing sector, where rapid line reconfiguration is critical.
Painting Robot Market Segmentation
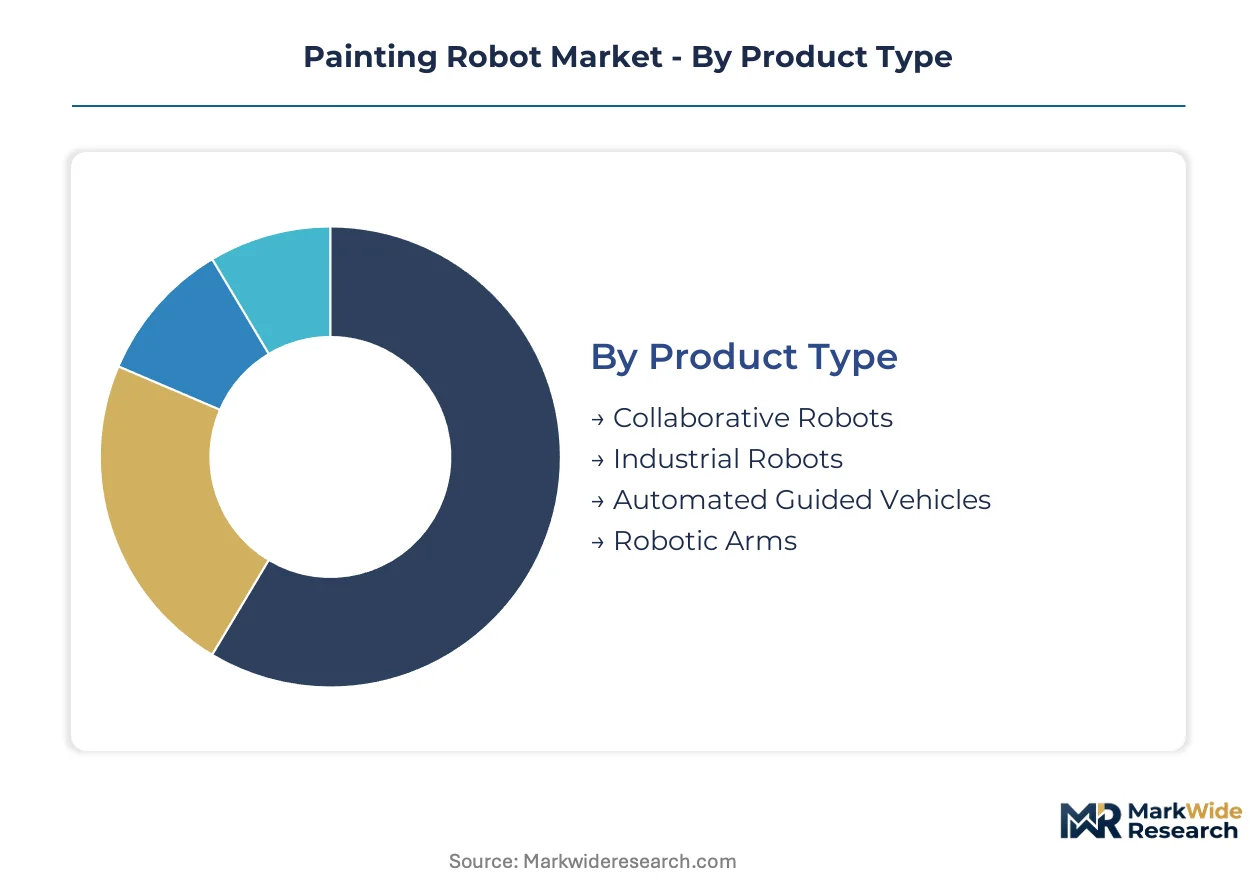
The Painting Robot Market is differentiated across various dimensions, reflecting the diverse requirements of industrial automation and coating processes. Understanding these segments clarifies the specific technological demands and operational contexts influencing buyer decisions.
Product Type:
The product type segmentation highlights the integration depth of painting robots, ranging from standalone manipulators to systems designed for human-robot interaction.
- Industrial Robots:These multi-axis manipulators are designed for high-volume, high-precision painting tasks in controlled environments. Their robust construction ensures consistent application of liquid and powder coatings, enhancing finish quality. Demand concentrates in automotive manufacturing hubs, particularly in China, to meet stringent quality standards.
- Collaborative Robots:These robots work safely alongside human operators without extensive safety caging, featuring smaller footprints and intuitive programming. They are adopted by small and medium-sized workshops, especially in furniture and metal fabrication, for automating high-mix, low-volume finishing tasks.
- Automated Guided Vehicles:AGVs integrate painting robots onto mobile platforms, enabling flexible deployment for painting large objects within a factory.
- Robotic Arms:This category encompasses the mechanical manipulator component of a painting robot, integrated with end-effectors for precise coating application.
Volume placements concentrate in Industrial Robots; the faster expansion belongs to Collaborative Robots.
Technology:
Segmentation by technology highlights the specific methods and integrated intelligence employed to achieve superior coating results and process efficiency.
- AI Integration:This combines painting robots with AI-powered vision systems for real-time defect detection and automatic path correction. Such integration creates autonomous quality assurance. Demand for AI-integrated systems emerges in aerospace finishing for specialized coatings.
- Atomization:This core technology uses specialized end-effectors like rotary atomizers to break paint into fine particles for uniform application. It achieves consistent film thickness and high transfer efficiency. Automotive and furniture production rely on advanced atomization for finish quality.
- 3D Printing:This technology creates custom jigs and fixtures for holding complex parts during robotic painting, enabling precise positioning for non-standardized components.
- Dry Spraying:This technique applies powder coatings without solvents, often using electrostatic charges. It offers environmental benefits by eliminating VOC emissions and reducing waste.
Demand for Atomization remains strong, while AI Integration shows significant potential for future growth.
End User:
The end-user segmentation highlights the primary industries driving demand and investment in painting robot systems, reflecting their specific operational needs and regulatory pressures.
- Automotive Manufacturers:This segment is the largest consumer of painting robots, using them for flawless, consistent finishes on complex vehicle bodies. The sector requires multi-axis robotic precision to meet OEM specifications. Demand is strong in China's industrial hubs due to high production volumes.
- Furniture Production:This segment shows significant adoption for finishing applications, utilizing robots for consistent coating of various furniture components. Robots enhance efficiency and reduce material waste. Small and medium-sized workshops increasingly adopt collaborative robots here.
- Aerospace:The aerospace industry employs painting robots for applying specialized coatings requiring extreme precision and process documentation on large components.
- Construction:Emerging applications involve painting large structural components, like bridge sections or prefabricated building modules, within controlled factory environments.
The Automotive Manufacturers segment drives current market value, while Furniture Production is expanding rapidly.
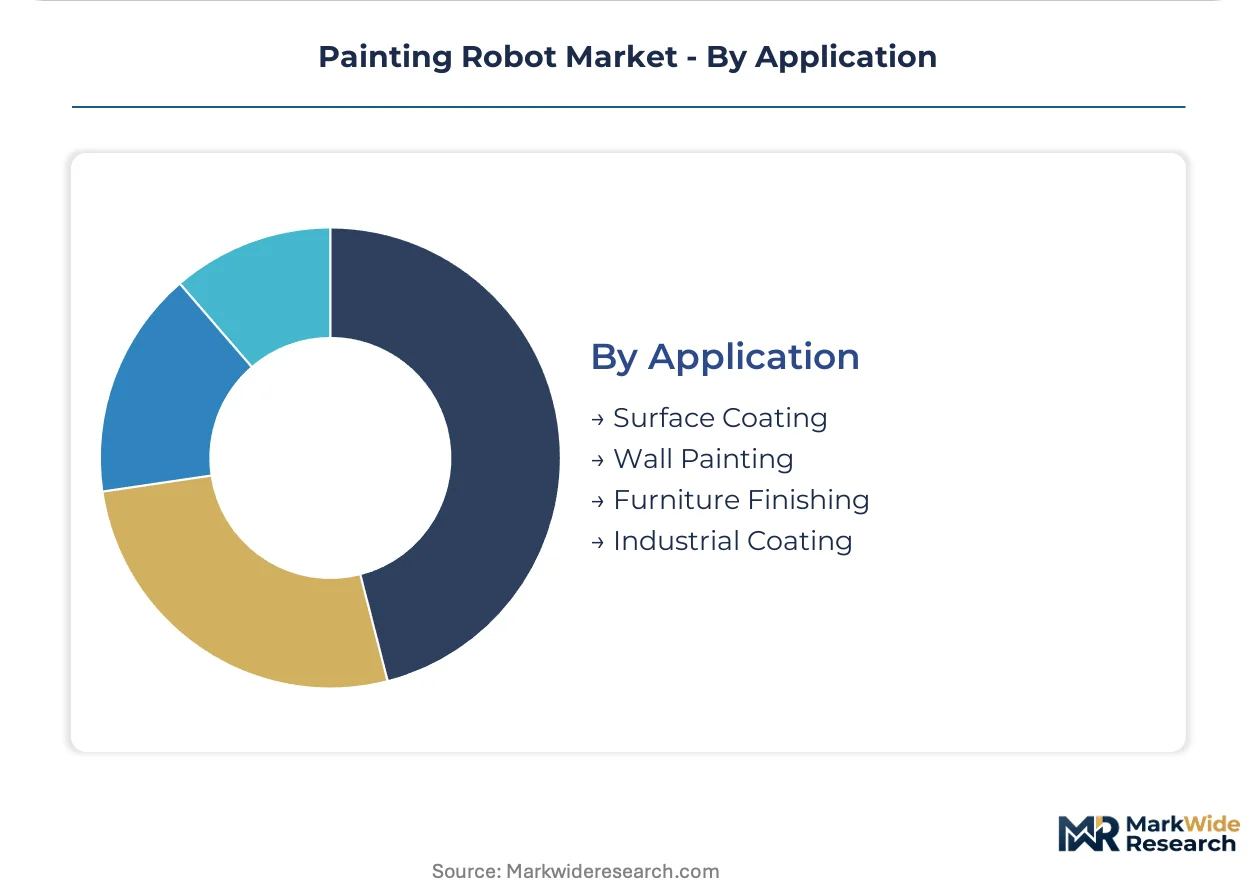
Application:
This segmentation outlines the specific tasks and environments where painting robots are deployed, ranging from broad industrial processes to highly specialized finishing operations.
- Industrial Coating:This broad application covers automated application of protective or decorative coatings across various industrial products and components. It enhances durability, aesthetics, and corrosion resistance. General metal finishing industries heavily invest in robotic systems for efficient and compliant coating processes.
- Furniture Finishing:This application uses robots to apply paints, stains, and lacquers to furniture pieces, ensuring consistent coverage and finish quality. It addresses precision needs for complex geometries and diverse material types, driven by efficiency gains.
- Surface Coating:This general category refers to applying any liquid or powder coating onto a surface for desired aesthetic or functional properties.
- Wall Painting:This emerging application involves robots painting interior or exterior walls, primarily in the construction sector, improving speed, consistency, and safety.
Market stability is provided by Industrial Coating, with Furniture Finishing demonstrating considerable evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Painting robot production is concentrated in a few industrial powerhouses, while consumption is more broadly distributed across diverse manufacturing hubs. This dynamic shapes regional investment patterns and technology adoption for automated coating solutions. Manufacturers seek both advanced technology and localized support.
China
Demand for flawless finishes in automotive and electronics manufacturing drives significant painting robot adoption. China's GB standards increasingly push for efficient and environmentally compliant industrial processes. The Yangtze River Delta and Pearl River Delta industrial hubs are rapidly expanding automation in paint shops.
United States
Automotive quality standards and the growing aerospace finishing sector necessitate high-precision painting robots. EPA rules on volatile organic compound emissions compel industries to invest in efficient robotic application systems. Michigan's automotive corridor and California's aerospace sector lead in robotic painting deployment.
Germany
High-precision manufacturing across the automotive and industrial machinery sectors fuels painting robot demand. The EU's REACH regulations and Machinery Directive guide system design and adoption for compliance. Bavaria and North Rhine-Westphalia house advanced paint shop solution providers and end-users.
Japan
The automotive and heavy industrial machinery sectors maintain strong demand for reliable painting automation. METI initiatives support the development and integration of advanced robotics in manufacturing processes. Aichi Prefecture's automotive cluster consistently leads in robotic painting technology deployment.
India
Emerging automotive manufacturing and expanding furniture production segments are driving painting robot adoption. India's PLI schemes encourage local manufacturing and automation across various industries. Chennai and Pune industrial zones are witnessing increasing robot integration for finishing applications.
Painting Robot Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the painting robot market. The market structure exhibits a tiered consolidation, with a few large industrial automation providers alongside niche solution integrators. Strategic archetypes include comprehensive system providers and specialized component manufacturers. Dominant competitive moves involve portfolio diversification and geographic expansion.
Within the comprehensive system provider archetype, FANUC Corporation and ABB exemplify global leaders offering extensive robotic arms and advanced control software. Dürr AG further anchors the market by providing integrated, turnkey paint shop solutions, particularly for automotive clients. These entities leverage their scale to address diverse industrial requirements.
| Leading Market Players |
|---|
| Yaskawa Electric Corporation |
| Dürr AG |
| ABB |
| Comau |
| Staubli International AG |
| FANUC Corporation |
| Kawasaki Heavy Industries |
| Nachi-Fujikoshi Corp |
| KUKA AG |
| Others |
Cost & Logistics Intelligence
Specialized end-effector components, crucial for consistent film thickness, influence the downstream pricing of integrated painting robot systems. Their concentration among a few global suppliers creates pricing power for component manufacturers, impacting system integrators' cost structures. This dynamic shapes the final investment decisions for end-users across various industrial segments.
Pricing Analysis
Cost-down pressure on standard industrial robot systems intensifies as competition from new market entrants and alternative automation solutions grows. The dominant pricing model remains project-based, reflecting the customized integration and setup required for each painting cell. Price differentiation drivers include the level of customization for specific application needs and the breadth of after-sales service and support. Automotive manufacturers, with high volume requirements, exhibit lower price sensitivity for mission-critical systems, while small and medium-sized enterprises remain highly price-sensitive.
Supply Chain Analysis
Skilled technician availability in key manufacturing geographies like China and Germany directly impacts the efficiency and cost of robotic system deployment. The supply chain for painting robots draws heavily from specialized robotic arm components, precision sensors, and advanced control software. A structural risk arises from the component supply concentration, particularly for specialized atomizers, creating potential single-source vulnerabilities. Distribution runs primarily through direct sales channels and specialized system integrators who customize solutions for end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The painting robot market presents a supply-constrained environment, where the scarcity of specialized integration expertise props up pricing for turnkey solutions.
For Market Incumbents: Acquire specialized software development firms to enhance AI and machine vision integration capabilities, directly addressing programming complexity. Invest in expanding global service networks, particularly in emerging markets like India, to counter the persistent skilled technician shortage. This approach mitigates threats from niche software providers and reinforces market leadership in comprehensive solutions.
For New Entrants and Emerging Players: Small and medium-sized workshops represent an underserved buyer archetype, particularly in furniture production and metal fabrication. Target the high-mix, low-volume segment with collaborative robot solutions featuring intuitive programming interfaces. A compelling go-to-market angle involves offering modular, reconfigurable cells that emphasize ease of deployment and lower total cost of ownership for non-standardized tasks.
For Investors and Strategic Acquirers: Distressed-cycle entries favor system integrators with deep vertical expertise in specific applications, particularly in Europe's industrial machinery sector. The long-term viability of this market hinges on continued automation adoption driven by regulatory compliance and efficiency demands. A critical signal to watch is the accelerated investment in AI and machine vision integration by leading players, indicating future competitive advantage.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Key Hubs | Increased production capabilities in China support rising automotive manufacturing demand. |
| AI & Machine Vision Integration | Enhanced autonomous quality assurance improves finish consistency and reduces material waste. |
| Strategic Partnerships with Software Developers | Access to advanced programming expertise addresses customization challenges for complex tasks. |
| Global Service Network Enhancement | Improved technical support and maintenance address the skilled technician shortage across regions. |
| Modular Robotic Cell Development | Offers greater flexibility and scalability, meeting evolving buyer preferences for customized automation. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this market analysis. Primary interviews with plant managers, automation engineers, procurement leads at automotive OEMs, and system integrators validated initial findings. This approach ensured a robust triangulation between qualitative insights from industry experts and quantitative data from official sources, supporting both bottom-up and top-down market sizing.
The analytical framework reconciled multiple data streams across the projection horizon to establish market volume and value. Segmentation dimensions modeled included product type, technology, end-user industry, application, and regional adoption patterns. Compound annual growth rates were derived from historical trends, future investment plans, and expected technological advancements, with key inputs including global automotive production forecasts and manufacturing investment trends.
Revisions become necessary when significant shifts in global trade policies, manufacturing investment cycles, or regulatory mandates materialize. Forecasts reflect assumptions documented at the time of analysis regarding technological progression and market dynamics. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Asia-Pacific AUV and ROV Market
Robotics and Automation
Robotics in Shipbuilding Market
Robotics and Automation
Intelligent Vending Machines Market
Robotics and Automation
SLAM Robots Market
Robotics and Automation
Long-Range Drone Package Delivery Market
Robotics and Automation
UV-C Disinfection Robots Market
Robotics and Automation
Robotics Technology Market
Robotics and Automation
Consumer Robotics Market
Robotics and Automation
Europe Warehouse Robotics Market
Robotics and Automation
Robot Market
Robotics and Automation
Canada Cloud Robotics Market
Robotics and Automation
Delta Robots Market
Robotics and Automation
Personal Robots Market
Robotics and Automation
GCC AUV Market
Robotics and Automation
Global Robotic Process Automation in Healthcare Market
Robotics and Automation
Vision Guided Robotics Market