
 Medical Automation Technologies Market | 2026-2036
Medical Automation Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Automation Technologies Market Analysis
The medical automation sector is restructuring around a sharp divergence between premium robotic surgery platforms and commodity-grade patient monitoring hardware. Intuitive Surgical dominates the high-margin surgical robotics tier through its installed base of da Vinci systems and recurring instrument revenue. Danaher Corporation anchors laboratory automation through its Beckman Coulter and Cepheid subsidiaries, leveraging diagnostic workflow integration across hospital networks. Tecan Group competes in mid-scale liquid handling automation for contract research organizations, specializing in modular configurations that reduce pharmaceutical assay setup time.
Medical automation technologies encompass electromechanical systems, software algorithms, and sensor networks that execute clinical tasks with minimal human intervention, typically operating with positional accuracy below 0.1 millimeter in surgical applications and processing throughput exceeding 1,000 samples per hour in laboratory settings. Their primary purpose centers on reducing clinical variability, compressing diagnostic turnaround times, and reallocating skilled labor toward complex decision-making. Robotic surgery systems command the largest revenue pool among product types due to capital intensity and disposable instrument attach rates, while laboratory automation systems represent the fastest expansion trajectory as diagnostic laboratories confront staffing shortages and rising test volumes. Artificial Intelligence within the technology dimension is displacing rules-based automation in radiology and pathology workflows, creating margin concentration among vendors with regulatory-cleared machine learning algorithms.
The FDA's Software as a Medical Device framework and the EU Medical Device Regulation reshape product development cycles, requiring clinical validation datasets and post-market surveillance infrastructure that smaller automation vendors struggle to fund. China's NMPA has tightened registration requirements for AI-enabled diagnostic devices, extending approval timelines for foreign manufacturers seeking hospital procurement eligibility. Stakeholders must monitor evolving reimbursement policies for autonomous surgical procedures and automated diagnostic interpretations, as payer acceptance will determine commercial velocity more than technical capability alone.
Market Dynamics
Artificial intelligence is displacing rules-based automation in radiology and pathology workflows, forcing vendors to rebuild product architectures around machine learning inference engines rather than deterministic control systems. This shift concentrates margin among firms with regulatory-cleared algorithms while commoditizing legacy electromechanical hardware.
Growth Catalysts
- FDA Software as a Medical Device framework:The pathway accelerates commercialization for AI-enabled diagnostic devices, reducing validation timelines and enabling faster hospital procurement cycles.
- Robotic surgery adoption:United States hospital networks are expanding system deployments to compress operative variability and improve patient throughput metrics tied to reimbursement.
- Laboratory automation infrastructure:Germany's university hospital networks anchor Europe's largest installed base, creating demand pull for modular liquid handling and sample processing systems.
Market Restraints
- Clinical validation dataset requirements:The EU Medical Device Regulation mandates extensive post-market surveillance infrastructure that smaller automation vendors cannot fund without dilutive capital raises.
- Extended foreign manufacturer timelines:China's NMPA has tightened registration requirements for AI-enabled diagnostic devices, delaying hospital procurement eligibility for non-domestic suppliers.
- Disposable instrument attach rates:Robotic surgery platforms require ongoing consumable purchases that concentrate lifetime cost ownership and limit adoption in budget-constrained health systems.
Strategic Opportunities
- Autonomous surgical procedure reimbursement:Payer acceptance for automated operative interventions remains unsettled, creating first-mover advantage for vendors that secure coverage determinations.
- Diagnostic workflow integration:Convergence of laboratory automation with AI-enabled interpretation creates white space for platforms that unify sample handling and algorithmic analysis.
- Contract research organization penetration:Mid-scale pharmaceutical assay automation remains underserved by modular configurations that reduce setup time for high-throughput screening.
Industry Challenges
- Machine learning engineering talent scarcity:Vendors compete for limited pools of clinicians with regulatory submission experience and software engineers with medical device quality systems expertise.
- Legacy health record interoperability:Integration complexity with entrenched hospital information systems extends deployment timelines and inflates implementation costs.
- Algorithm bias validation:Demonstrating equitable performance across demographic subgroups requires expanded clinical trial designs that compress development economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Automation Technologies Market |
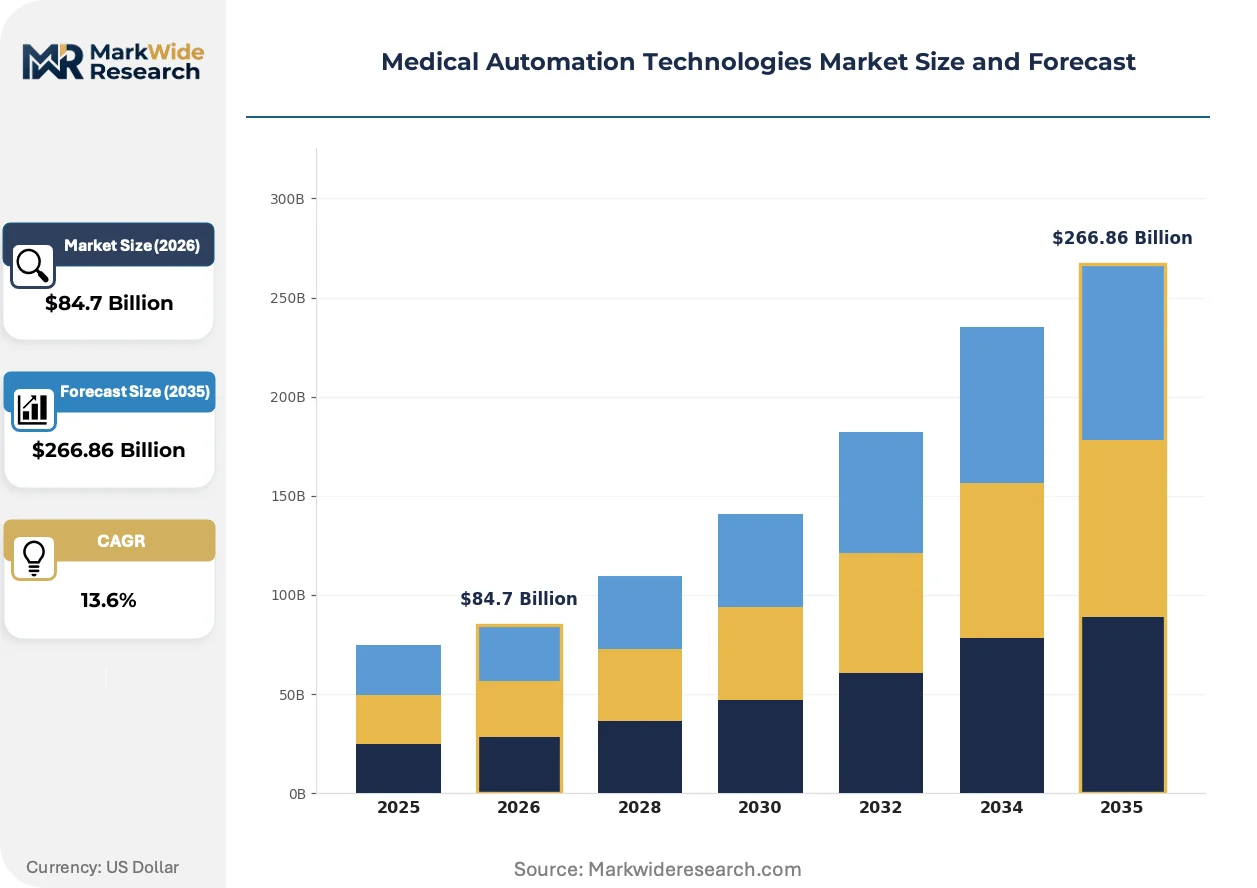
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $266.86 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Surgery Systems, Automated Medication Dispensers, Laboratory Automation Systems, Patient Monitoring Devices End User: Hospitals, Clinics, Diagnostic Laboratories, Outpatient Facilities Technology: Artificial Intelligence, Machine Learning, Internet of Things, Cloud Computing Application: Patient Care, Surgical Assistance, Workflow Optimization, Data Management |
| Companies Covered | Medtronic, Intuitive Surgical, GE Healthcare, Siemens Healthineers, Philips Healthcare, Tecan Group, Accuray, Stryker Corporation, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Automation Technologies Market Emerging Trajectories
Edge computing architectures are reshaping medical automation by relocating inference workloads from centralized cloud infrastructure to point-of-care devices. This migration reduces latency for time-critical diagnostic decisions while creating new hardware requirements for thermal management and data security.
Point-of-care ultrasound platforms is decentralizing diagnostic imaging by embedding AI-guided acquisition protocols into handheld devices. Emergency departments and rural clinics are adopting these systems at accelerating pace. The technology is decentralizing radiologist workflow by enabling non-specialist operators to capture diagnostic-quality images without specialist supervision.
The EU AI Act's risk classification framework for medical devices is restructuring product development roadmaps. High-risk autonomous diagnostic systems face mandatory conformity assessments and post-market monitoring obligations. Surgical robotics vendors are responding by segmenting product portfolios between fully autonomous functions and physician-supervised assistance modes.
Hospital procurement committees are consolidating vendor relationships around integrated platform contracts rather than point solutions. Group purchasing organizations are displacing direct manufacturer negotiations for capital equipment. This concentration is most visible in United States health systems pursuing standardization across multi-hospital networks.
Medical Automation Technologies Market Segmentation
Medical automation vendors pursue divergent margin strategies across product architectures, with capital-intensive surgical platforms commanding premium pricing while laboratory systems scale through modular configurations. Segmentation reveals how technology integration and end-user workflow requirements reshape competitive positioning across the value chain.
Product Type:
Supply concentration clusters around vendors controlling proprietary instrument ecosystems and recurring revenue streams.
- Robotic Surgery Systems:Electromechanical platforms with sub-millimeter positional accuracy integrate surgeon console, patient-side manipulators, and high-definition visualization towers. United States hospital networks anchor demand as reimbursement metrics reward reduced operative variability and compressed length-of-stay. Disposable instrument attach rates concentrate lifetime ownership costs and vendor lock-in.
- Laboratory Automation Systems:Modular liquid handling and sample processing configurations process diagnostic throughput exceeding 1,000 samples per hour. Germany's university hospital networks anchor Europe's largest installed base, pulling demand for workflow-integrated platforms that address staffing shortages and rising test volumes.
- Automated Medication Dispensers:Pharmacy robotics with barcode verification and inventory tracking reduce dispensing errors in high-volume hospital settings.
- Patient Monitoring Devices:Sensor networks for continuous vital sign acquisition represent commoditized hardware with compressed margins.
Today's leader: Robotic Surgery Systems. Tomorrow's challenger: Laboratory Automation Systems.
End User:
Procurement authority and capital allocation flexibility determine adoption velocity across institutional categories.
- Hospitals:Integrated delivery networks with centralized capital budgets deploy multi-system automation platforms across surgical, laboratory, and pharmacy departments. United States health systems pursue standardization across multi-hospital networks through consolidated vendor relationships.
- Diagnostic Laboratories:Independent and hospital-affiliated labs confront staffing shortages and rising test volumes, driving fastest expansion trajectory for modular automation that compresses turnaround times.
- Clinics:Limited capital budgets restrict adoption to point-of-care devices with lower infrastructure requirements.
- Outpatient Facilities:Ambulatory surgical centers and same-day clinics prioritize compact robotic platforms with reduced footprint.
Hospitals retain procurement dominance. Diagnostic Laboratories are gaining share fastest.
Technology:
Regulatory clearance timelines and engineering talent scarcity concentrate competitive advantage among algorithm-centric architectures.
- Artificial Intelligence:Machine learning inference engines displace rules-based automation in radiology and pathology workflows, requiring FDA Software as a Medical Device framework validation and clinical performance datasets across demographic subgroups.
- Machine Learning:Supervised learning models for diagnostic interpretation demand post-market surveillance infrastructure under EU Medical Device Regulation obligations.
- Internet of Things:Sensor networks and edge computing architectures relocate inference workloads to point-of-care devices, reducing latency for time-critical decisions.
- Cloud Computing:Centralized infrastructure for algorithm training and model deployment faces hospital cybersecurity and data residency constraints.
Artificial Intelligence commands R&D investment. Internet of Things is expanding most quickly at the edge.
Application:
Workflow integration depth and reimbursement clarity determine commercial scalability across use cases.
- Surgical Assistance:Physician-supervised robotic platforms with autonomous sub-functions command premium pricing and recurring instrument revenue, though payer acceptance for fully autonomous procedures remains unsettled.
- Workflow Optimization:Laboratory and pharmacy automation that reallocates skilled labor toward complex decision-making addresses staffing shortages with quantifiable operational returns.
- Patient Care:Continuous monitoring and medication management automation confront commoditization pressure from hardware competitors.
- Data Management:Interoperability with entrenched hospital information systems extends deployment timelines and inflates implementation costs.
Surgical Assistance dominates revenue concentration. Workflow Optimization offers steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized engineering talent concentrates in Germany's university hospital networks and the United States' surgical robotics corridors. These workforce clusters anchor the two dominant automation ecosystems shaping procurement patterns and regulatory benchmarks worldwide.
United States
Hospital networks in the United States deploy robotic surgery systems to compress operative variability and improve patient throughput metrics tied to reimbursement. The FDA's Software as a Medical Device framework accelerates commercialization timelines for AI-enabled diagnostic devices. The Boston-Cambridge corridor anchors medical device engineering talent, while the Research Triangle in North Carolina concentrates clinical validation infrastructure for automation vendors.
Germany
Siemens Healthineers and university hospital networks anchor Europe's largest installed base of laboratory automation infrastructure, creating demand pull for modular liquid handling systems. The EU Medical Device Regulation mandates extensive post-market surveillance infrastructure that reshapes vendor compliance strategies. The Rhine-Main region around Frankfurt concentrates diagnostic equipment manufacturing, while Baden-Württemberg hosts precision electromechanical suppliers feeding automation OEMs.
China
Domestic hospital procurement committees prioritize locally manufactured automation platforms as the NMPA tightens registration requirements for AI-enabled diagnostic devices. The regulator's extended approval timelines delay hospital procurement eligibility for foreign suppliers. The Yangtze River Delta around Shanghai anchors the country's largest concentration of medical robotics startups, while Shenzhen's hardware ecosystem supplies sensor components for patient monitoring devices.
Japan
METI funding programs support surgical robotics development as domestic manufacturers confront Intuitive Surgical's installed base dominance. The PMDA maintains rigorous clinical validation standards for autonomous diagnostic functions. The Kansai region around Osaka concentrates precision manufacturing capabilities for robotic manipulators, while Tokyo's hospital networks serve as early validation sites for automation platforms.
United Kingdom
NHS procurement frameworks favor automation platforms demonstrating quantifiable operational returns and workforce reallocation metrics. MHRA alignment with EU MDR requirements post-Brexit maintains stringent post-market surveillance obligations. The Oxford-Cambridge arc anchors AI-enabled diagnostic development, while London's hospital trusts pilot workflow optimization automation addressing staffing shortages.
Medical Automation Technologies Market Vendor Landscape
Top-tier vendors anchor the surgical robotics and laboratory automation tiers, while mid-scale specialists populate pharmaceutical assay automation and point-of-care device segments. The market structures around three strategic archetypes: integrated platform vendors controlling proprietary instrument ecosystems, modular configuration specialists serving contract research organizations, and AI-centric algorithm developers pursuing regulatory-cleared diagnostic workflows. Dominant competitive moves include strategic partnerships with hospital procurement committees and portfolio diversification into adjacent automation workflows.
Within the integrated platform tier, Intuitive Surgical and Siemens Healthineers exemplify vendors controlling proprietary instrument ecosystems with recurring revenue attach rates. Danaher Corporation occupies a position anchoring laboratory automation through diagnostic workflow integration. Among mid-scale specialists, Tecan Group represents the modular configuration approach targeting pharmaceutical assay automation with reduced setup time configurations.
| Leading Market Players |
|---|
| Medtronic |
| Intuitive Surgical |
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| Tecan Group |
| Accuray |
| Stryker Corporation |
| Danaher Corporation |
| Others |
Supply Flow & Price Mechanics
The EU AI Act's risk classification framework gates qualified supply for high-risk autonomous diagnostic systems, restricting premium-tier pricing access to vendors that complete mandatory conformity assessments and maintain post-market surveillance infrastructure. This regulatory filter concentrates pricing power among algorithm-centric architectures with regulatory-cleared machine learning inference engines while commoditizing legacy electromechanical hardware lacking AI integration.
Pricing Analysis
Bundled platform contracts dominate hospital procurement, with integrated surgical robotics vendors commanding recurring instrument revenue streams alongside capital equipment sales. Unbundled point solutions face commoditization pressure as group purchasing organizations consolidate vendor relationships around standardized configurations. Pricing stratifies across FDA-cleared AI tiers, CE-marked autonomous functions, and basic electromechanical assistance modes. Cost compression in patient monitoring hardware intensifies due to sensor component oversupply from Shenzhen manufacturing clusters. Diagnostic laboratories exhibit highest price sensitivity, while integrated delivery networks with centralized capital budgets absorb premium pricing for workflow-integrated platforms.
Supply Chain Analysis
Dual-sourcing requirements from United States hospital procurement committees mandate multi-supplier qualification for critical robotic manipulators and imaging sensors, reducing single-source vulnerability. Precision electromechanical components concentrate in Germany's Baden-Württemberg region, Japan's Kansai manufacturing corridor, and Switzerland's precision engineering clusters. Supply chains draw from Taiwan's semiconductor foundries for edge computing chips, China's Yangtze River Delta for sensor assemblies, and the United States' Boston-Cambridge corridor for AI training infrastructure. Tariff exposure on Chinese-manufactured components creates supply chain risk as NMPA registration timelines extend for foreign suppliers. Distribution runs through group purchasing organizations and regional hospital networks rather than direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical automation sector functions as a stable compounder, with chronic clinical staffing shortages across hospital networks and diagnostic laboratories driving steady replacement demand for workflow optimization technologies.
For Market Incumbents: Extend proprietary instrument ecosystems into adjacent laboratory and pharmacy automation workflows, leveraging installed base relationships to cross-sell modular configurations. Deepen backward integration into precision electromechanical component manufacturing to reduce exposure to Baden-Württemberg supplier concentration. Fortify regulatory submission capabilities against EU MDR post-market surveillance obligations that smaller competitors cannot fund. For New Entrants and Emerging Players: AI-guided point-of-care ultrasound platforms offer the most penetrable white space, with emergency departments and rural clinics adopting handheld devices at accelerating velocity. Target contract research organizations with pharmaceutical assay automation configurations that reduce high-throughput screening setup time. Pursue software-as-a-medical-device pathways under FDA frameworks to bypass capital-intensive hardware manufacturing barriers. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale laboratory automation specialists because hospital procurement consolidation favors integrated platform vendors with multi-department workflow coverage. Target firms with regulatory-cleared algorithms and established GPO contracts rather than hardware-only manufacturers. Monitor NMPA registration timeline trends for foreign AI-enabled diagnostic devices as an inflection indicator for China market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as Medical Device Submission | Accelerates commercialization timelines for AI-enabled diagnostic algorithms through streamlined validation pathways. |
| Hospital System Partnership | Secures multi-year integrated platform contracts with group purchasing organizations across United States health networks. |
| CE Marking Pathway Under EU MDR | Enables European hospital procurement eligibility through conformity assessment for high-risk autonomous functions. |
| Software Companion Development | Extends robotic surgery platform utility through AI-guided acquisition protocols and autonomous sub-functions. |
| Reimbursement Strategy for Autonomous Procedures | Determines commercial velocity for fully autonomous surgical interventions through payer coverage determinations. |
Methodological Framework
Coverage spans the United States, Germany, China, Japan, and the United Kingdom, with primary inputs from each market informing demand-side validation. The research combines structured interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs leads at automation vendors with secondary validation from FDA 510(k) filings, EUDAMED device registrations, NMPA approval databases, and hospital capital expenditure disclosures. Bottom-up modeling of installed base expansion and instrument attach rates triangulates against top-down spending analysis from health system financial reports.
Granularity extends to product-type splits across robotic surgery systems, laboratory automation configurations, and point-of-care devices, with technology segmentation distinguishing rules-based electromechanical platforms from AI-enabled inference architectures. End-user modeling separates integrated delivery network procurement patterns from independent diagnostic laboratory purchasing behavior. CAGRs derive from logistic diffusion curves fitted to historical adoption rates, adjusted for regulatory clearance timeline variations and reimbursement policy shifts. Forecast inputs incorporate surgical procedure volume projections, diagnostic test volume growth, and health system labor cost inflation.
The model holds under stable regulatory clearance timelines and continued hospital capital budget allocation toward automation; deviation in FDA enforcement discretion, EU MDR conformity assessment backlogs, or NMPA foreign manufacturer registration policies would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robotics and Automation Actuators Market
Robotics and Automation
Tool Tethering Market
Robotics and Automation
Intelligent Vending Machines Market
Robotics and Automation
Modular Robotics Market
Robotics and Automation
Africa Agricultural Robots and Mechatronics Market
Robotics and Automation
Europe Service Robotics Market
Robotics and Automation
Smart Exoskeleton Market
Robotics and Automation
Drone Package Delivery Market
Robotics and Automation
Europe AUV and ROV Market
Robotics and Automation
Robotic Waste Sorting System Market
Robotics and Automation
Robot Pedestal Market
Robotics and Automation
Cloud Robotics Market
Robotics and Automation
US Cloud Robotics Market
Robotics and Automation
Self-Driving Delivery Robot Market
Robotics and Automation
Marine Robots Market
Robotics and Automation
Dispensing Robots Market