
 SLAM Robots Market | 2026-2036
SLAM Robots Market Size, Share, and Industry Trends Forecast 2026-2036
SLAM Robots Market Outlook
Modular sensor-to-software bundling is restructuring procurement patterns for SLAM robot buyers who once sourced lidar, IMU, and navigation stacks separately. Amazon Robotics leverages captive warehouse density to refine its visual-SLAM stack at scale. KUKA AG anchors industrial-grade deployments through tight coupling of its manipulator arms with proprietary mapping engines. Clearpath Robotics differentiates by sustaining an open-platform model that lets research and defense clients swap sensor payloads without vendor lock-in.
SLAM robots employ simultaneous localization and mapping algorithms fused with depth sensors, lidar, or camera arrays to build real-time environmental maps while tracking their own position within them. These systems typically operate at update rates exceeding 20 Hz with centimeter-grade drift correction, serving primarily to enable autonomous navigation in dynamic, GPS-denied environments such as factory floors and fulfillment centers. Industrial Automation applications dominate current revenue owing to high unit values and integration complexity, while Warehouse Management represents the fastest-expanding application as e-commerce fulfillment networks retrofit existing facilities. Lidar-based technology still commands premium positioning for outdoor and high-vibration settings, though Visual-SLAM is gaining ground where cost sensitivity and indoor lighting stability permit camera-only stacks.
FDA device regulations and FCC wireless emissions standards shape hardware certification pathways for SLAM robots deployed in healthcare and logistics settings across the United States. OSHA workplace safety rules further constrain autonomous vehicle speeds and human-robot collaboration zones in manufacturing plants. Stakeholders must monitor how evolving liability frameworks around autonomous system failures will reshape insurance requirements and deployment risk models.
Market Dynamics
Modular sensor-to-software bundling is restructuring procurement patterns for SLAM robot buyers who once sourced lidar, IMU, and navigation stacks separately, compressing vendor relationships and collapsing traditional component margins.
Growth Catalysts
- EU AI Act compliance pathways:Manufacturers accelerating autonomous navigation certification for warehouse deployments across Germany, France, and the Netherlands.
- Automotive manufacturing corridors:Dense SLAM-enabled production lines in Stuttgart and Wolfsburg driving industrial automation demand for centimeter-grade localization.
- Lidar miniaturization:Shrinking hardware footprints enabling smaller-form-factor robots to penetrate constrained fulfillment center aisles previously inaccessible to larger units.
Market Restraints
- High-grade IMU supply concentration:Dependence on specialized inertial measurement unit foundries in Taiwan and Japan creates input vulnerability.
- OSHA workplace safety constraints:Autonomous vehicle speed limits and human-robot collaboration zone rules restrict deployment density in US manufacturing plants.
- Visual-SLAM lighting dependency:Camera-only stacks fail in variable illumination environments, limiting substitution of lidar in outdoor logistics yards.
Strategic Opportunities
- India's PLI scheme for robotics:Production-linked incentives attracting component assembly and software development for cost-sensitive warehouse automation.
- Healthcare facility navigation:FDA device regulations creating certified pathways for SLAM robots in hospital logistics and sterile supply chains.
- Edge-AI convergence with 5G:Real-time map processing offloading enabling lighter onboard compute and extended operational runtime.
Industry Challenges
- SLAM algorithm specialist scarcity:Shortage of engineers proficient in probabilistic robotics and sensor fusion constrains R&D velocity.
- FCC wireless emissions certification:Extended approval timelines for mesh-networked robot fleets delay commercial rollout in logistics settings.
- Legacy WMS integration friction:Proprietary warehouse management system architectures resist API-based fleet orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SLAM Robots Market |
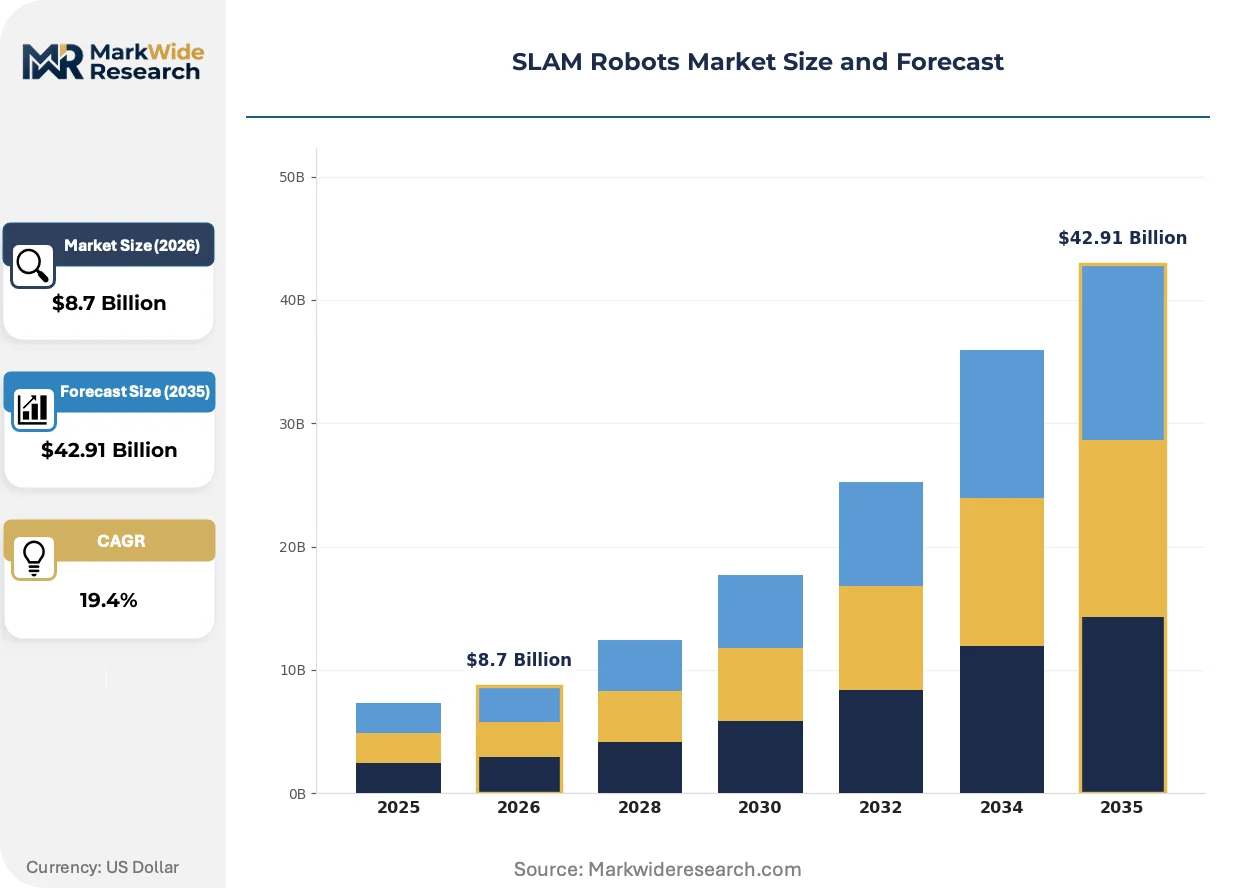
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Industrial Automation, Warehouse Management, Agriculture, Logistics Technology: Depth Sensors, Lidar, Visual-SLAM, IMU End User: Manufacturers, Retailers, Farmers, Service Providers Solution: Autonomous Navigation, Mapping Services, Data Analysis, Fleet Management |
| Companies Covered | Aethon, KUKA AG, Amazon Robotics, Shanghai Slamtec, Omron Adept Technologies, Clearpath Robotics, SLAMcore, Pudu Robotics, Locus Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SLAM Robots Market Strategic Shifts
Hardware abstraction layers and software-defined sensor stacks are dissolving traditional boundaries between robot OEMs and component suppliers, enabling faster iteration cycles and shifting value capture toward navigation intelligence.
Solid-state lidar is modularizing around standardized mechanical interfaces and driver protocols. Fulfillment center operators in the United States and Germany are adopting these units at accelerating pace to reduce spare parts inventory. The technology is modularizing procurement decisions, letting buyers swap sensor vendors without redesigning chassis or recertifying safety systems.
REACH substance restrictions and RoHS compliance deadlines are forcing lidar manufacturers to reformulate solder alloys and optical coatings. Industrial consequences include extended qualification periods for new sensor designs. European automotive integrators are responding by front-loading supplier audits and locking in multi-year component agreements.
Buyer concentration among large e-commerce fulfillment networks is compressing vendor negotiation cycles and unbundling after-sales service contracts. Third-party maintenance providers are displacing OEM service arms in North American warehouse deployments. Germany's automotive sector retains tighter vendor relationships, though tier-one suppliers face similar margin pressure.
SLAM Robots Market Segmentation
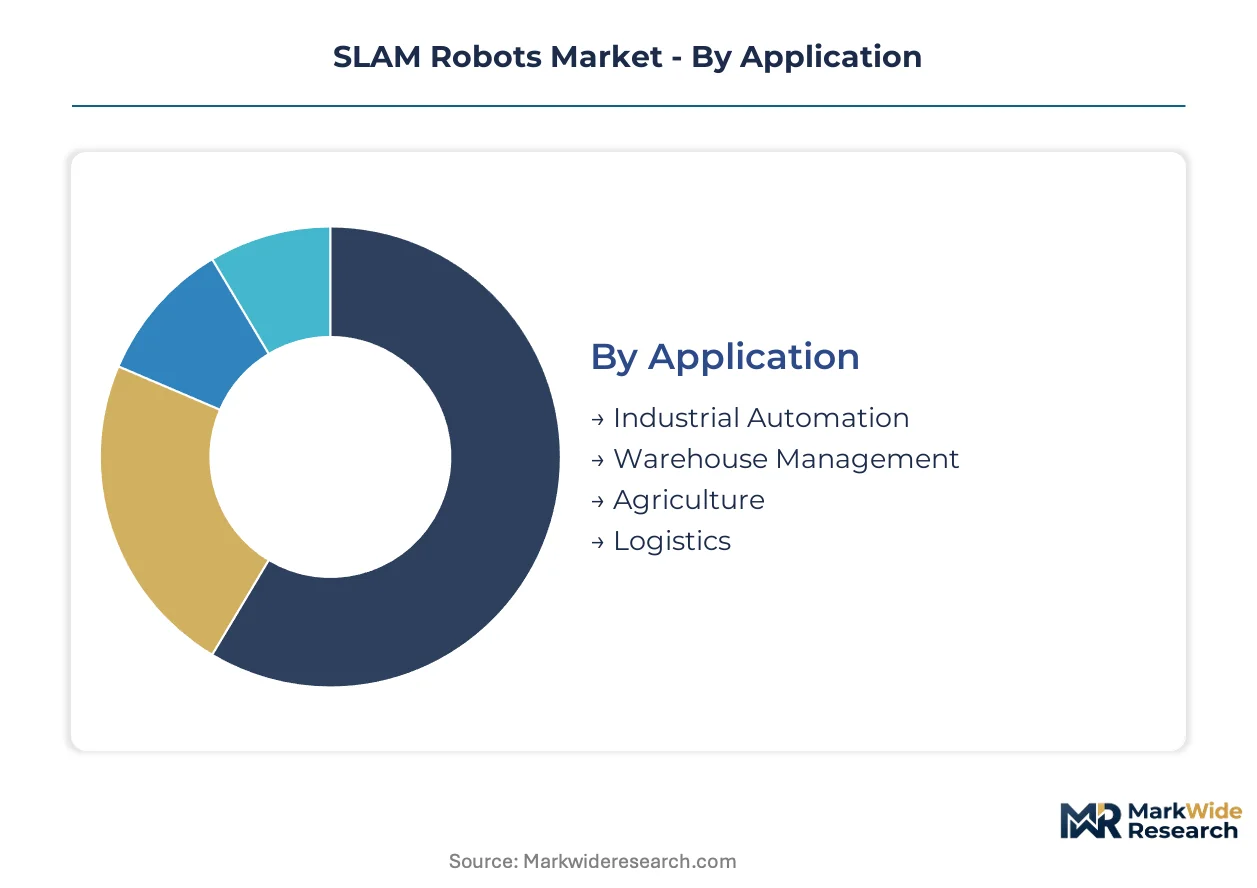
SLAM robot procurement splits sharply between regulated environments demanding FDA or CE device certification and cost-driven warehouse settings where FCC emissions clearance suffices. Buyers segment their vendor shortlists by the specific approval burden each deployment context imposes.
Application:
FDA device regulations constrain Industrial Automation and healthcare-adjacent deployments, while Warehouse Management navigates OSHA workplace safety rules and lighter FCC wireless certification pathways.
- Industrial Automation:Dense SLAM-enabled production lines in Stuttgart and Wolfsburg demand centimeter-grade localization fused with manipulator arms. KUKA AG anchors this segment through tight coupling of proprietary mapping engines with robotic hardware, driving premium integration complexity.
- Warehouse Management:E-commerce fulfillment networks retrofit existing facilities with smaller-form-factor units enabled by lidar miniaturization. Amazon Robotics leverages captive warehouse density to refine visual-SLAM stacks at scale, compressing vendor negotiation cycles among concentrated buyer pools.
- Agriculture:Variable illumination and GPS-denied outdoor terrain favor lidar-based stacks over camera-only alternatives. Farmers face lighter regulatory burdens than manufacturing or healthcare settings.
- Logistics:Outdoor logistics yards confront Visual-SLAM lighting dependency failures, limiting substitution of lidar in yard management applications.
Warehouse Management sits at the top of the volume ranking, with Industrial Automation climbing the fastest as automotive manufacturing corridors densify SLAM-enabled lines.
Technology:
Hardware cost tiers separate premium lidar deployments from budget Visual-SLAM alternatives, with certification requirements varying by sensor type and operational environment.
- Depth Sensors:Solid-state units modularizing around standardized mechanical interfaces enable faster spare parts turnover in fulfillment centers. REACH substance restrictions force reformulation of solder alloys and optical coatings, extending European qualification periods.
- Lidar:Miniaturization trends slash hardware footprints and enable penetration of constrained fulfillment center aisles previously inaccessible to larger units. Premium positioning persists for outdoor and high-vibration settings.
- Visual-SLAM:Camera-only stacks gain ground where cost sensitivity and indoor lighting stability permit, though they fail in variable illumination environments.
- IMU:High-grade inertial measurement unit supply concentrates in Taiwan and Japan, creating input vulnerability for manufacturers dependent on specialized foundries.
Lidar sits at the top of the volume ranking, with Visual-SLAM climbing the fastest as cost-sensitive indoor deployments multiply.
End User:
Customer procurement maturity separates integrated Manufacturers from fragmented Retailers and Farmers, with Service Providers occupying an emerging intermediary position.
- Manufacturers:Germany's automotive sector retains tighter vendor relationships than North American warehouse operators, though tier-one suppliers face similar margin compression from concentrated buyer power.
- Retailers:Large e-commerce fulfillment networks unbundle after-sales service contracts, displacing OEM service arms with third-party maintenance providers.
- Farmers:Cost sensitivity drives preference for camera-only stacks where lighting conditions permit, though outdoor operations often necessitate lidar premiums.
- Service Providers:Emerging category of fleet orchestration specialists bridging proprietary warehouse management system architectures with API-based robot coordination.
Manufacturers sit at the top of the volume ranking, with Service Providers climbing the fastest as WMS integration friction creates outsourcing demand.
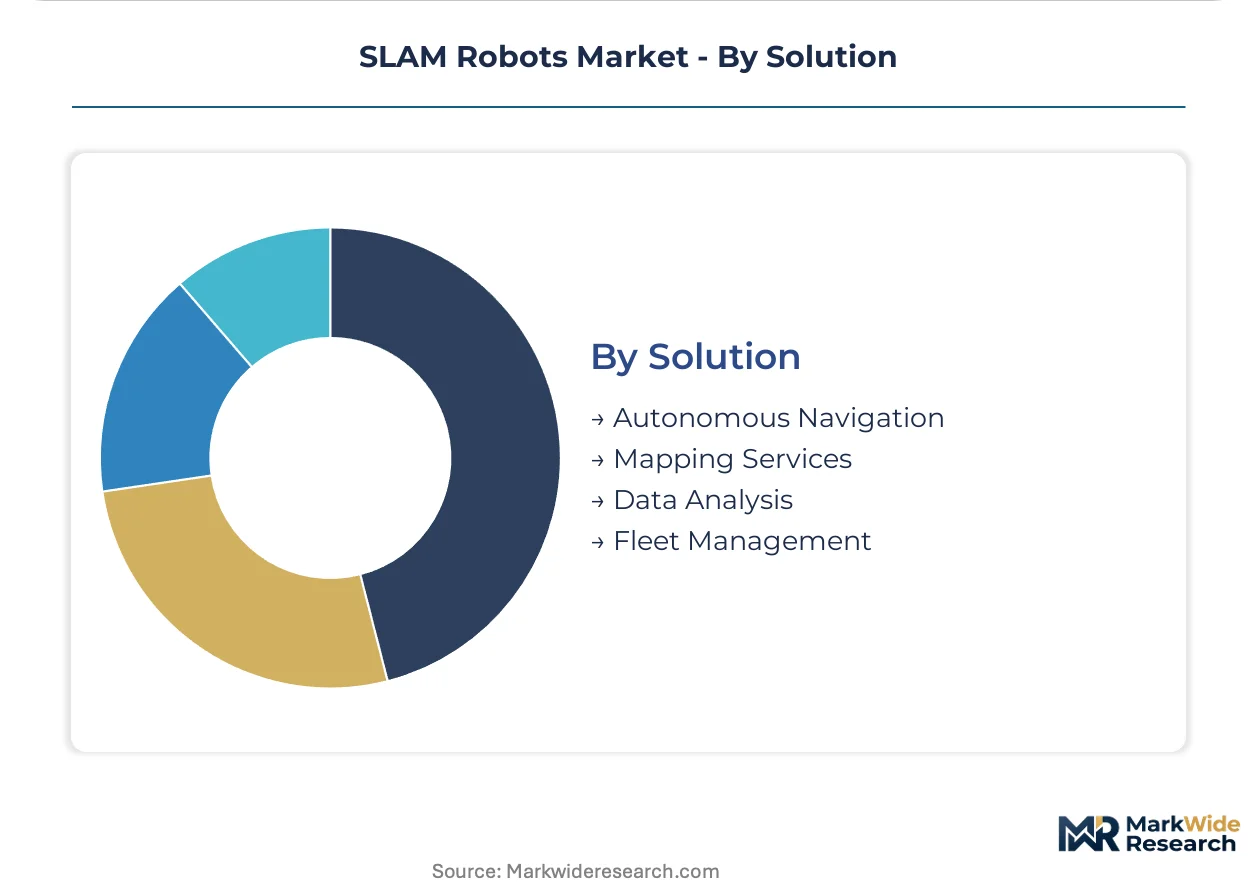
Solution:
Margin concentration shifts from hardware toward navigation intelligence as software-defined sensor stacks dissolve traditional OEM-component boundaries.
- Autonomous Navigation:Real-time environmental mapping at update rates exceeding 20 Hz with centimeter-grade drift correction serves GPS-denied factory floors and fulfillment centers.
- Mapping Services:Data-rich spatial intelligence offerings capture recurring revenue from facility operators lacking in-house SLAM algorithm expertise.
- Data Analysis:Fleet performance optimization and predictive maintenance layers add value atop raw sensor feeds.
- Fleet Management:API-based orchestration of multi-vendor robot populations addresses legacy WMS integration friction in logistics settings.
Autonomous Navigation sits at the top of the volume ranking, with Fleet Management climbing the fastest as mesh-networked robot deployments scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SLAM robotics originated in German automotive manufacturing corridors before spreading to North American fulfillment networks and Asian electronics assembly hubs. Early industrial deployments in Stuttgart and Wolfsburg established the technical baseline for centimeter-grade localization. Today's geographic expansion reflects divergent regulatory environments and labor cost pressures.
United States
Warehouse operators retrofit existing facilities with autonomous fleets to compress labor costs in fulfillment centers. FCC wireless emissions standards and OSHA workplace safety rules constrain deployment density and human-robot collaboration zones. Amazon Robotics leverages captive warehouse density in the Midwest and Southeast to refine visual-SLAM stacks at operational scale.
Germany
Automotive manufacturing corridors in Stuttgart and Wolfsburg drive dense SLAM-enabled production lines with manipulator arm integration. EU AI Act compliance pathways accelerate autonomous navigation certification for industrial deployments. KUKA AG anchors this segment through tight coupling of proprietary mapping engines with robotic hardware systems.
China
Electronics assembly and logistics automation create concentrated demand for cost-sensitive SLAM solutions in manufacturing hubs. MIIT standards and GB certification requirements shape hardware approval pathways for domestic and export markets. Shanghai Slamtec exemplifies the rise of indigenous navigation stack providers serving regional fulfillment networks.
Japan
Precision manufacturing and aging workforce demographics sustain demand for autonomous material handling in factory settings. METI industrial policy and JIS standards guide robot safety certification and workplace integration protocols. High-grade IMU supply concentrates in specialized foundries, creating input dependencies for domestic manufacturers.
India
Production-linked incentives under the PLI scheme for robotics attract component assembly and software development for cost-sensitive warehouse automation. BIS certification requirements and DGFT import regulations shape hardware procurement patterns. Emerging service provider ecosystems in Bangalore and Pune bridge proprietary WMS architectures with API-based fleet orchestration.
SLAM Robots Market Competitive Environment
Premium-margin players sit above commodity-margin players across integration complexity and certification burden. The market structures around three tiers: industrial-grade system integrators with captive software stacks, open-platform specialists serving research and defense clients, and fulfillment-focused operators leveraging captive facility density. Strategic archetypes include vertical manipulator coupling, modular sensor-agnostic platforms, and warehouse-native navigation refinement. Dominant competitive moves encompass backward integration into mapping engines and geographic expansion through regional certification partnerships.
Among Germany-based industrial automation providers, KUKA AG exemplifies tight hardware-software coupling in automotive manufacturing corridors. Amazon Robotics occupies a position as a fulfillment-native operator leveraging captive warehouse density for stack refinement at scale. Clearpath Robotics represents the open-platform archetype, enabling research and defense clients to sustain sensor payload flexibility without vendor lock-in constraints.
| Leading Market Players |
|---|
| Aethon |
| KUKA AG |
| Amazon Robotics |
| Shanghai Slamtec |
| Omron Adept Technologies |
| Clearpath Robotics |
| SLAMcore |
| Pudu Robotics |
| Locus Robotics |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between FDA-cleared healthcare units and FCC-compliant warehouse robots splits both pricing power and supplier relationships across divergent compliance pathways. Industrial automation buyers absorbing CE-marked systems in Germany's automotive corridors pay integration premiums that warehouse operators in the United States refuse, fragmenting vendor tiering and compressing component margins at the commodity end.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs SLAM robot transactions, with FDA device certification and multi-sensor fusion capability commanding top-tier positioning. Price differentiation hinges on regulatory burden intensity and after-sales service bundling, though unbundling trends among large e-commerce fulfillment networks are stripping service margins from OEMs. Cost compression in standard-tier warehouse units is intensifying because concentrated buyer power forces volume discounts. Retailers and third-party logistics operators exhibit highest price sensitivity, while German automotive manufacturers retain tolerance for integration complexity premiums.
Supply Chain Analysis
Refurbishment flows for solid-state lidar units are extending component lifecycles and reshaping spare parts economics in North American fulfillment networks. Hardware assembly concentrates in China, Taiwan, and Germany, with high-grade IMU fabrication anchored in specialized Japanese and Taiwanese foundries. Raw material dependencies span rare-earth optical coatings, precision-machined aluminum housings, and semiconductor-grade silicon photonics. Single-source vulnerability in inertial measurement unit supply creates chokepoint exposure for manufacturers lacking dual-qualified vendors. Distribution runs through direct OEM channels for industrial integrators and third-party maintenance providers for warehouse retrofit deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SLAM robotics functions as a stable compounder, with autonomous navigation demand in GPS-denied industrial environments delivering sustained replacement cycles and upgrade revenue.
For Market Incumbents: Deploy backward integration into proprietary mapping engines to escape component margin compression from solid-state lidar commoditization. KUKA-style tight hardware-software coupling in automotive manufacturing corridors defends against open-platform erosion, while certification investment in FDA pathways for healthcare logistics creates switching costs that warehouse-native competitors cannot easily replicate. For New Entrants and Emerging Players: Mid-tier manufacturers in India seeking PLI-supported automation present an underserved buyer archetype with lighter regulatory burdens than German or US equivalents. Agriculture and outdoor logistics applications remain penetrable due to Visual-SLAM lighting failures that incumbent camera-only stacks cannot solve. A sensor-agnostic platform positioning with modular payload swapping bypasses the vendor lock-in that Clearpath Robotics has proven defensible in research and defense segments. For Investors and Strategic Acquirers: Asymmetric upside sits with fleet orchestration software specialists bridging legacy WMS integration friction, as hardware margins compress toward component economics. Long-term viability across a 5-10 year window favors navigation intelligence providers over robot OEMs, with acquisition targeting focused on SLAM algorithm engineering teams possessing probabilistic robotics depth. Practitioners should monitor EU AI Act enforcement intensity and OSHA collaborative robot rule revisions as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mapping Engines | KUKA's proprietary navigation stack demonstrates margin capture that eludes hardware-only vendors in Stuttgart corridors. |
| Modular Sensor-Agnostic Platform Development | Clearpath's payload-swapping architecture sustains research and defense client retention without vendor lock-in constraints. |
| FDA Device Certification Pathway Investment | Healthcare facility deployments require cleared navigation systems that warehouse-grade FCC compliance cannot satisfy. |
| Fleet Orchestration Software Acquisition | API-based coordination layers address WMS integration friction that limits mesh-networked robot scaling in logistics. |
| PLI Scheme Manufacturing Localization | India's production-linked incentives attract cost-sensitive assembly for warehouse automation serving domestic fulfillment networks. |
Study Parameters
Bottom-up warehouse operator and automotive manufacturer modeling reconciled against top-down sensor supplier and integrator tracking forms the analytical core of this study. Primary interviews with warehouse engineering directors, robotics procurement leads, SLAM algorithm specialists, and aftermarket service managers combined with secondary validation from SEC filings, customs trade data, EU AI Act implementation guidance, and FCC equipment authorization databases. Triangulation across demand-side deployment metrics and supply-side component shipment patterns ensures consistency in volume and value estimates.
Historical trendline analysis of lidar miniaturization cost curves and Visual-SLAM adoption rates informed projection parameters across the analysis window. Segmentation modeling incorporated application intensity, technology tier, end-user procurement maturity, and solution type, with CAGRs derived from fitted growth curves adjusted for regulatory compliance timelines and labor cost substitution economics. Industry-specific forecast inputs included EU AI Act certification velocity and OSHA collaborative robot rule evolution.
Underlying measurement precision varies by segment; Warehouse Management and Industrial Automation carry tighter precision than emerging Agriculture and Service Provider categories due to disclosed deployment volumes. Forecasts reflect documented assumptions around lidar cost decline trajectories and regulatory approval timelines, with revision triggers including REACH substance restriction enforcement, Taiwan semiconductor supply disruptions, and Visual-SLAM algorithm reliability breakthroughs. Practitioners should monitor EU AI Act delegated act publications and FCC Part 15 waiver grants for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Robot Kitchen Market
Robotics and Automation
Global Underwater Robotics Market
Robotics and Automation
Agricultural Robots and Mechatronics Market
Robotics and Automation
Disinfectant Robot Market
Robotics and Automation
Robotic Desktop Automation (RDA) Market
Robotics and Automation
Global Indoor Robots Market
Robotics and Automation
APAC Service Robots Market
Robotics and Automation
Hospital Logistics Robots Market
Robotics and Automation
Metal Fabrication Robots Market
Robotics and Automation
Telepresence Robotics Market
Robotics and Automation
Indonesia Robotics Market
Robotics and Automation
Retail Robotics Market
Robotics and Automation
Self-Driving Delivery Robot Market
Robotics and Automation
Robotics Software Platforms Market
Robotics and Automation
Assistive Technology Market
Robotics and Automation
Canada Cloud Robotics Market