
 UV-C Disinfection Robots Market | 2026-2036
UV-C Disinfection Robots Market Size, Share, and Industry Trends Forecast 2026-2036
UV-C Disinfection Robots Market Outlook
The capital-intensity divergence between autonomous navigation specialists and static-lamp assemblers is redrawing competitive boundaries in UV-C robotics. UVD Robots leverages its autonomous mapping stack to command premium positioning in European healthcare systems. Xenex Disinfection Services anchors its position through pulsed-xenon differentiation rather than conventional mercury-arc UV-C tubes. Blue Ocean Robotics sustains manufacturing scale across its portfolio by operating a shared robotics platform architecture.
UV-C disinfection robots deploy germicidal ultraviolet-C radiation, typically at wavelengths between 254 nanometers and 222 nanometers, to inactivate microbial DNA through photochemical damage. These systems integrate robotic mobility with calibrated irradiance delivery to achieve log-reduction targets on surfaces and in air volumes without residual chemical burden. Mobile units incorporating automated navigation and sensor fusion are capturing the fastest expansion as hospitals prioritize labor-free terminal cleaning protocols. Static and hybrid configurations retain stable demand in fixed-location deployments such as operating theaters and pharmaceutical cleanrooms, where predictable duty cycles support amortization.
The FDA regulates UV-C devices as antimicrobial pest control equipment under FIFRA, while the EPA oversees efficacy claims and residual chemistry exemptions. OSHA's ionizing and non-ionizing radiation standards constrain operator exposure thresholds, shaping robot design toward autonomous operation with remote monitoring. The EU Medical Device Regulation and CE marking requirements under the MDR framework govern systems deployed in clinical settings across European member states. Stakeholders must weigh validated dosage documentation against autonomous platform costs as procurement committees sharpen total-cost-of-ownership scrutiny.
Market Dynamics
The UV-C Disinfection Robots Market is experiencing structural pressure from CMS reimbursement incentives that tie infection control metrics to capital equipment procurement cycles in acute care facilities. This policy linkage is compressing sales cycles and favoring vendors with validated dosage documentation over unverified efficacy claims.
Growth Catalysts
- CMS Reimbursement Incentives:United States hospitals face financial penalties for hospital-acquired infections, accelerating capital deployment toward autonomous disinfection systems that demonstrate measurable pathogen reduction.
- Mercury-Arc to Far-UVC Transition:Wavelength engineering at 222 nanometers enables human-safe continuous operation, expanding deployable environments beyond vacant-room protocols into occupied clinical spaces.
- European Healthcare Consolidation:Cross-border procurement frameworks in Germany, France, and the Netherlands are standardizing technical specifications and creating volume opportunities for compliant platform vendors.
Market Restraints
- Mercury Supply Concentration:Conventional UV-C lamp production depends on mercury sourcing from limited global suppliers, exposing assemblers to input cost volatility and RoHS compliance complexity.
- Validated Dosage Documentation Burden:FDA FIFRA enforcement requires extensive third-party efficacy testing, extending product development timelines and elevating fixed compliance costs for smaller entrants.
- Chemical Disinfection Substitution:Established hydrogen peroxide vapor systems retain installed-base loyalty in pharmaceutical cleanrooms, constraining UV-C penetration in high-validity environments.
Strategic Opportunities
- Underpenetrated Ambulatory Surgery Centers:United States outpatient facilities lack terminal cleaning infrastructure proportionate to surgical volume, creating whitespace for mobile autonomous units with rapid room-turnaround protocols.
- Sensor Fusion Convergence:Integration of LiDAR mapping with real-time irradiance monitoring enables dynamic dose adjustment, differentiating next-generation platforms from static-lamp configurations.
- EU Green Deal Procurement Mandates:Public healthcare tenders increasingly weight residual-chemical elimination criteria, favoring UV-C systems that eliminate quaternary ammonium compound runoff.
Industry Challenges
- Autonomous Navigation Talent Scarcity:Robotics firmware engineering for healthcare environments requires simultaneous expertise in sensor fusion, safety-critical systems, and clinical workflow integration.
- CE Marking Timeline Compression:EU MDR classification of UV-C robots as Class IIa medical devices extends notified body review periods, delaying market entry for revised product generations.
- Legacy HVAC Integration Complexity:Upper-room UV-C installations demand coordination with existing air-handling infrastructure, fragmenting deployment decisions across facilities and clinical engineering departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV-C Disinfection Robots Market |
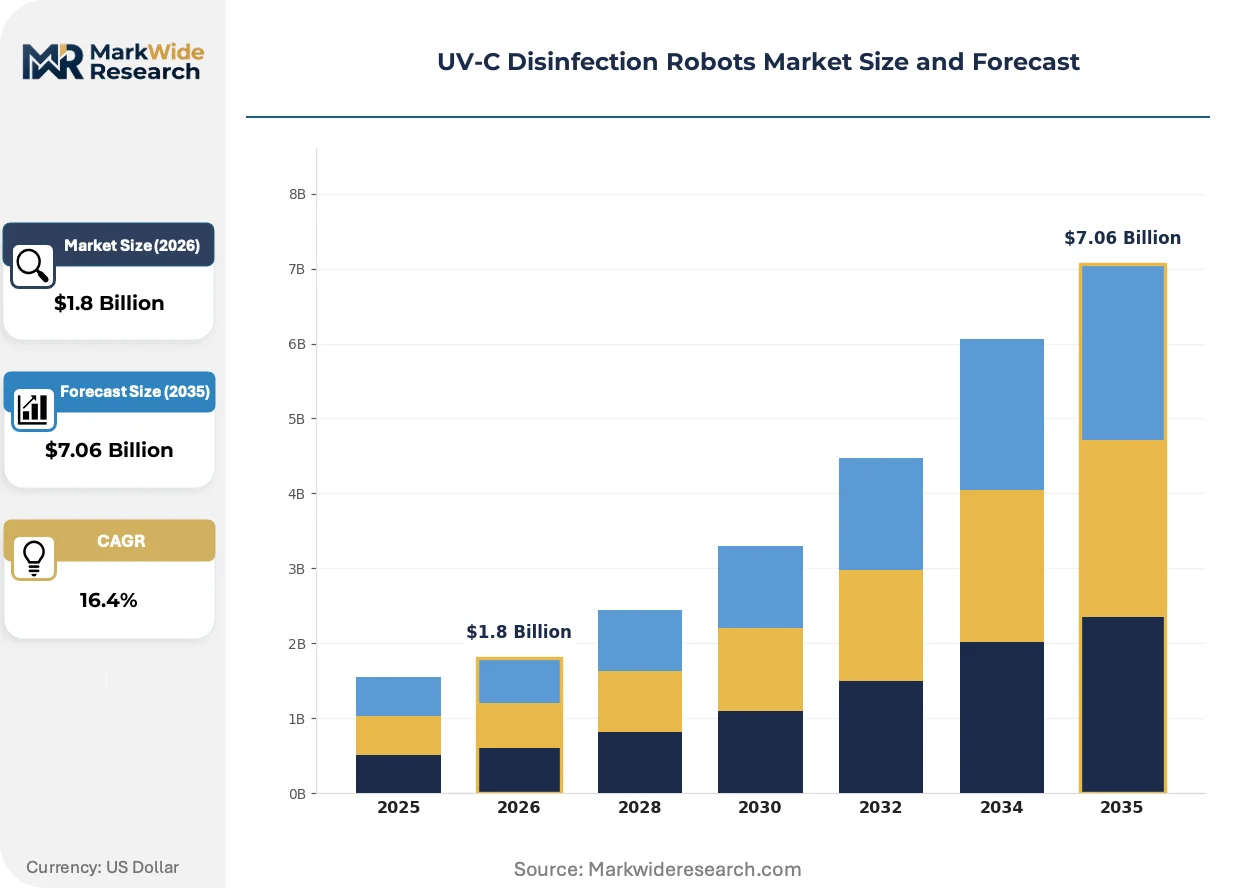
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static, Mobile, Hybrid, Portable Technology: UV-C Light, Automated Navigation, Remote Control, Sensor Fusion End User: Healthcare Facilities, Educational Institutions, Hospitality, Public Transport Application: Surface Disinfection, Air Purification, Equipment Sterilization, Water Treatment |
| Companies Covered | Tru-D SmartUVC, Finsen Technologies, UVD Robots, Omron Corporation, OTSAW Digital, Xenex Disinfection Services, Skytron, Nevoa Inc., Blue Ocean Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV-C Disinfection Robots Market Strategic Shifts
Technology trajectories in UV-C robotics are diverging between wavelength-engineered human-safe systems and high-output mercury-arc platforms, while regulatory documentation requirements intensify competitive sorting between validated and unvalidated vendors.
Far-UVC emitter technology at 222 nanometers is bifurcating the installed base between continuous-operation occupied-space systems and legacy vacant-room protocols. Acute care hospitals in the United States are piloting human-safe configurations for emergency department waiting areas and corridor disinfection. This wavelength shift is compressing the addressable market for conventional mercury-arc vendors while enabling new use cases previously excluded by OSHA exposure thresholds.
EU MDR enforcement through notified bodies in Germany and the Netherlands is elevating clinical evidence requirements for UV-C systems deployed in surgical suites. Manufacturers must now submit bioburden reduction studies under controlled clinical conditions rather than laboratory-simulated protocols. This regulatory tightening most affects static-lamp assemblers lacking autonomous platform differentiation, forcing consolidation toward vendors with dedicated regulatory affairs functions.
Hospital capital committees are unbundling equipment procurement from multi-year service agreements, compressing vendor revenue streams toward hardware margins and discrete validation consulting. This purchasing pattern shift is visible most acutely in United States health systems undergoing private equity consolidation, where standardized equipment lists and centralized sourcing functions displace individual facility autonomy. Regional distributors are responding by developing in-house technical service capabilities to capture recurring revenue previously retained by manufacturers.
UV-C Disinfection Robots Market Segmentation
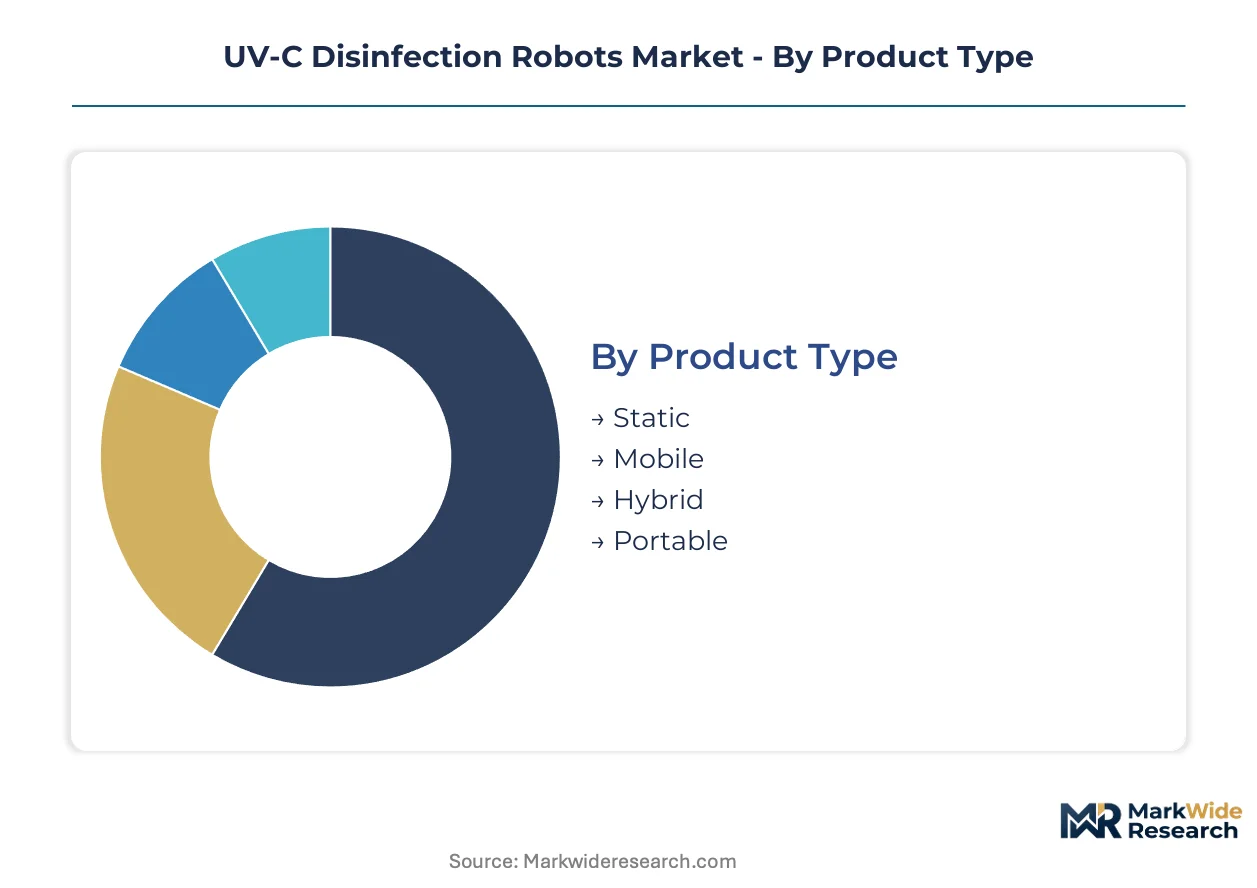
Segmentation in UV-C disinfection robotics reveals how procurement committees balance capital intensity against operational flexibility. Product architecture, navigation sophistication, and end-use environment constraints collectively determine vendor selection and pricing power across deployment scenarios.
Product Type:
Substitution pressure from hydrogen peroxide vapor systems and manual chemical protocols weighs most heavily on static configurations lacking autonomous mobility, while mobile units command premium positioning through labor displacement economics.
- Static:Fixed-installation mercury-arc or LED arrays deliver calibrated irradiance to predetermined zones without robotic mobility. Pharmaceutical cleanrooms in Germany and the Netherlands favor these systems for predictable duty cycles where room geometry remains constant, though FDA FIFRA validation requirements extend deployment timelines.
- Mobile:Autonomous platforms integrate LiDAR mapping with germicidal emitter positioning to navigate clinical corridors and patient rooms without human intervention. United States acute care hospitals concentrate procurement here as CMS infection control penalties compress capital approval cycles for labor-free terminal cleaning.
- Hybrid:Configurations combine fixed emitter banks with limited mobility for operating theater applications requiring rapid repositioning between procedures.
- Portable:Human-transported units serve ambulatory surgery centers and field deployment scenarios where infrastructure investment is constrained.
Static configurations anchor the volume base in regulated pharmaceutical environments while mobile platforms gain share at the steepest rate as healthcare labor costs escalate.
Technology:
Technology stack composition determines which vendors capture procurement contracts requiring documented efficacy under EU MDR or FDA enforcement frameworks.
- UV-C Light:Wavelength engineering at 254 nanometers or 222 nanometers constitutes the core germicidal mechanism. Mercury-arc tubes dominate installed base economics, though far-UVC emitter development at 222 nanometers enables OSHA-compliant occupied-space operation previously excluded by exposure thresholds.
- Automated Navigation:Simultaneous localization and mapping algorithms enable autonomous path planning through dynamic clinical environments. European healthcare systems in France and Germany prioritize vendors with proven navigation stacks that reduce training burden on environmental services staff.
- Remote Control:Operator-supervised movement retains demand in legacy facilities lacking Wi-Fi infrastructure or where clinical staff prefer direct oversight.
- Sensor Fusion:Integration of irradiance monitors with occupancy detection enables dynamic dose adjustment based on real-time environmental conditions.
UV-C light technology anchors the volume base through established mercury-arc economics while automated navigation climbs the fastest as hospitals eliminate manual positioning labor.
End User:
End-use environment dictates regulatory pathway complexity and amortization horizon expectations across procurement evaluations.
- Healthcare Facilities:Acute care hospitals, ambulatory surgery centers, and long-term care institutions face the most stringent bioburden reduction documentation requirements. United States health systems undergoing private equity consolidation drive standardized equipment list adoption that favors vendors with multi-site service capabilities.
- Educational Institutions:K-12 districts and university campuses prioritize rapid room-turnaround protocols between class sessions, favoring portable or mobile configurations with simplified operator interfaces.
- Hospitality:Hotel chains and cruise operators deploy units for guest room turnover and food service area maintenance, though capital budgets lag healthcare procurement cycles.
- Public Transport:Airport terminals and rail systems pilot overnight disinfection protocols for high-touch surfaces in passenger waiting areas.
Healthcare facilities anchor the volume base through infection control mandate compliance while educational institutions expand most quickly as federal relief funding enables capital deployment.
Application:
Application focus determines whether vendors compete on irradiance engineering or air-handling integration expertise.
- Surface Disinfection:Direct UV-C exposure targets high-touch surfaces in patient rooms, operating theaters, and pharmaceutical manufacturing suites. This application captures the majority of mobile robot deployments as log-reduction validation protocols mature under FDA and EPA oversight.
- Air Purification:Upper-room and in-duct configurations target airborne pathogen loads in densely occupied spaces. Integration with existing HVAC infrastructure fragments procurement decisions across facilities and clinical engineering departments in United States hospital systems.
- Equipment Sterilization:Enclosed chamber systems process reusable medical devices and laboratory instruments between uses.
- Water Treatment:UV-C reactor systems address municipal and industrial water disinfection requirements outside the core robotics market.
Surface disinfection anchors the volume base through terminal cleaning protocol standardization while air purification gains share fastest as building ventilation upgrades accelerate post-pandemic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare procurement committees in the United States demonstrate the lowest price elasticity, prioritizing validated dosage documentation over capital cost minimization. German and Dutch buyers exhibit moderate sensitivity, weighting CE marking compliance against total-cost-of-ownership metrics. Chinese and Indian facilities remain most price-responsive, favoring portable configurations over autonomous navigation premiums.
United States
CMS reimbursement incentives tie infection control performance to capital equipment budgets, accelerating procurement cycles for autonomous disinfection systems. FDA FIFRA enforcement pressures manufacturers toward third-party efficacy documentation. The Texas Medical Center in Houston anchors pilot deployments of far-UVC occupied-space systems in emergency department corridors.
Germany
Cross-border procurement frameworks standardize technical specifications across university hospital networks, creating volume concentration for compliant vendors. EU MDR classification as Class IIa medical devices extends notified body review timelines through TÜV Süd and DEKRA. The Munich-Düsseldorf corridor hosts validation laboratories serving robotic platform developers seeking CE marking.
Netherlands
Public healthcare tenders integrate EU Green Deal residual-chemical elimination criteria, favoring UV-C systems over quaternary ammonium compound protocols. The country's national pharmaceutical regulator enforces bioburden reduction documentation for surgical suite deployments. Eindhoven's high-tech campus clusters sensor fusion engineering talent for autonomous navigation stacks.
China
Hospital construction booms in tier-two cities drive demand for cost-optimized portable units over premium autonomous platforms. The National Medical Products Administration aligns antimicrobial device oversight with international efficacy standards. Shenzhen manufacturing ecosystems supply emitter components to domestic assemblers competing on price-positioned configurations.
Japan
Aging care facilities prioritize human-safe 222-nanometer configurations for continuous occupied-space operation. METI funding programs support wavelength engineering research through public-private partnerships. The Osaka-Kobe industrial corridor concentrates mercury-arc tube production for regional supply chain integration.
UV-C Disinfection Robots Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with autonomous navigation specialists commanding premium positioning against static-lamp assemblers competing on capital efficiency. The vendor base separates into three tiers: integrated platform developers with proprietary mapping stacks, component-assembly specialists sourcing emitters and drive systems, and regional distributors developing in-house service capabilities. Dominant competitive moves include backward integration into emitter manufacturing and strategic partnerships with hospital group purchasing organizations.
Among autonomous platform specialists, UVD Robots and Blue Ocean Robotics occupy positions emphasizing navigation sophistication, while Xenex Disinfection Services exemplifies wavelength-differentiation strategy through pulsed-xenon engineering. Tru-D SmartUVC and Skytron represent established tier-one vendors with multi-site service infrastructures. Component-assembly specialists include Finsen Technologies and Nevoa Inc., which source emitter subsystems and concentrate on regional distribution density. OTSAW Digital and Omron Corporation sit within diversified robotics conglomerates leveraging shared platform architectures across healthcare and industrial applications.
| Leading Market Players |
|---|
| Tru-D SmartUVC |
| Finsen Technologies |
| UVD Robots |
| Omron Corporation |
| OTSAW Digital |
| Xenex Disinfection Services |
| Skytron |
| Nevoa Inc. |
| Blue Ocean Robotics |
| Others |
Value Chain & Pricing Dynamics
Mercury-arc to far-UVC emitter substitution simultaneously redraws supply geography toward Japanese and South Korean wavelength-engineering specialists while compressing pricing power for legacy lamp assemblers tethered to volatile mercury sourcing.
Pricing Analysis
After-sales service contracts and validation consulting now drive lifetime value capture more than hardware margins alone. Three-tier pricing structure across premium autonomous platforms, standard mobile units, and economy portable configurations stratifies the market, with FDA FIFRA certification tier and multi-site service capability as the primary price differentiation levers. Pricing pressure stems from hospital capital committees unbundling equipment from service agreements. Ambulatory surgery centers exhibit the highest price sensitivity, while United States acute care hospitals undergoing private equity consolidation demonstrate the lowest.
Supply Chain Analysis
Strategic stockpiling of mercury-arc tubes persists among European assemblers wary of RoHS compliance volatility, while just-in-time sourcing dominates far-UVC emitter procurement from Japanese and South Korean suppliers. Manufacturing concentration centers on China for drive systems and mechanical components, Japan for 222-nanometer emitter engineering, and Germany for sensor fusion subsystems. Raw material dependencies include mercury for conventional lamps, aluminum nitride substrates for far-UVC chips, and rare-earth phosphors. Single-source vulnerability in mercury supply from limited global extractors poses structural risk. Distribution runs through regional healthcare equipment distributors developing in-house technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through United States health system private equity consolidation, fragmenting vendor pricing autonomy as standardized equipment lists displace individual facility procurement discretion.
For Market Incumbents: Shield market position through backward integration into far-UVC emitter manufacturing and captive validation laboratory capacity. The threat of wavelength-engineering specialists commoditizing legacy mercury-arc platforms demands defensive certification investment. Prioritize CE marking pathway acceleration to compress EU MDR timeline exposure. For New Entrants and Emerging Players: Post-installation bioburden monitoring and compliance documentation services represent a service-layer gap where incumbents under-serve mid-tier hospitals. Ambulatory surgery centers in the United States offer the most penetrable segment given whitespace in terminal cleaning infrastructure. A GPO partnership go-to-market angle accelerates access to consolidated health systems. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors autonomous navigation specialists with proprietary mapping stacks over static-lamp assemblers. Long-term viability hinges on wavelength-engineering differentiation and regulatory affairs infrastructure depth. Watch FDA FIFRA enforcement intensity as the inflection signal for competitive sorting between validated and unvalidated vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Far-UVC Emitter Backward Integration | Captive supply of 222-nanometer components insulates margin from mercury volatility and enables occupied-space product lines. |
| FDA FIFRA Validation Laboratory Investment | In-house efficacy documentation capability compresses product development timelines and differentiates against unverified competitors. |
| Hospital GPO Partnership Development | Preferred supplier status with consolidated United States health systems secures volume commitments through standardized equipment lists. |
| EU MDR Notified Body Relationship | Early engagement with TÜV Süd or DEKRA accelerates CE marking for Class IIa medical device classification. |
| Sensor Fusion Engineering Acquisition | LiDAR and irradiance monitoring talent scarcity makes specialist firms attractive targets for autonomous platform differentiation. |
Study Parameters
Initial hypotheses were tested against primary input from hospital purchasing committee members, biomedical engineers, GPO contracts managers, and environmental services directors and refined through secondary validation. Primary fieldwork encompassed structured interviews across United States, German, and Dutch healthcare systems. Secondary sources included FDA FIFRA registration databases, EU MDR notified body filings, hospital procurement contract repositories, and CMS infection control penalty records. Bottom-up unit economics triangulated against top-down market sizing.
Variance decomposition across product type, technology stack, end-user environment, and application focus shaped the analytical framework over the projection horizon. Segmentation dimensions modeled encompassed autonomous navigation sophistication, wavelength engineering approach, healthcare facility tier, and surface versus air treatment application. CAGRs were derived from installed base growth trajectories and replacement cycle dynamics. Industry-specific inputs included CMS reimbursement incentive elasticity and EU Green Deal procurement weighting trends.
Forecasts assume regulatory continuity in FDA FIFRA enforcement and EU MDR classification; material policy shifts would require re-modeling. Specific risk factors encompass mercury supply disruption, far-UVC human-safety study outcomes, and hospital capital budget contraction. Practitioners should keep alternative scenarios live as reimbursement incentive structures and wavelength-engineering cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Robotic Process Automation in Healthcare Market
Robotics and Automation
Underwater Drone Market
Robotics and Automation
Robotic Air Purifier Market
Robotics and Automation
Germany Cloud Robotics Market
Robotics and Automation
Hospital Robots Market
Robotics and Automation
Asia-Pacific Robotics Technology Market
Robotics and Automation
Europe AUV Market
Robotics and Automation
Automated Facade Contact Cleaning Robot Market
Robotics and Automation
Asia-Pacific Service Robotics Market
Robotics and Automation
Foundry and Forging Robots Market
Robotics and Automation
Global Automated Guided Vehicle (AGV) Software Market
Robotics and Automation
Europe Automated Guided Vehicle (AGV) Market
Robotics and Automation
Professional Service Robots Market
Robotics and Automation
Gantry Industrial Robots Market
Robotics and Automation
Africa Cloud Robotics Market
Robotics and Automation
Assistive Robotics Market