
 Acoustic Simulation Software Market | 2026-2036
Acoustic Simulation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Acoustic Simulation Software Market Insights
Automotive OEMs are unwinding legacy reliance on physical prototyping as electrification demands quieter cabin architectures. ANSYS leverages decades of finite-element acoustic heritage to anchor high-end automotive accounts. Siemens PLM Software extends its digital-twin stack into vibro-acoustic modules, competing for integrated platform contracts. COMSOL Multiphysics differentiates through multiphysics coupling that sustains appeal among research-intensive buyers.
Acoustic simulation software computes sound propagation, absorption, and radiation using numerical methods such as boundary-element analysis and finite-element discretization, enabling engineers to predict noise behavior without physical mock-ups. Cloud-based deployment is capturing fastest growth as engineering teams distribute compute-intensive jobs across elastic clusters, while on-premises installations retain dominance in defense and aerospace settings where data sovereignty governs infrastructure choice. Three-dimensional simulation commands the largest revenue pool, though room acoustics segments gain traction as immersive entertainment venues proliferate.
EPA pass-by noise standards and Euro 7 emission-acoustic limits compel automotive suppliers to validate designs virtually before physical homologation. ISO 3744 and ISO 9614 measurement protocols further shape software feature requirements across export-oriented manufacturing bases. Stakeholders must weigh cloud migration timelines against the regulatory permanence of localized compute mandates in defense and critical infrastructure sectors.
Market Dynamics
Automotive electrification is compressing NVH design cycles as powertrain noise signatures shift from mechanical roar to high-frequency whine, forcing OEMs to rebuild simulation workflows around electric motor acoustics and inverter switching harmonics.
Growth Catalysts
- Euro 7 acoustic-emission mandates:European regulators now tie emission compliance to pass-by noise thresholds, compelling powertrain suppliers to front-load virtual validation before physical homologation.
- Cloud HPC elasticity:Engineering teams at tier-one suppliers distribute boundary-element jobs across auto-scaling clusters, collapsing overnight solve times that previously required captive server farms.
- Immersive entertainment construction:Venue developers in Dubai, Las Vegas, and Singapore specify room-acoustic simulation for concert halls and esports arenas to meet ISO 3382 reverberation standards.
Market Restraints
- GPU memory ceilings:Full-vehicle acoustic models with million-element meshes exhaust current-generation graphics memory, fragmenting large-scale simulations across prohibitively expensive multi-GPU nodes.
- Defense data-sovereignty rules:Aerospace primes in the United States and United Kingdom cannot migrate acoustic signatures to commercial cloud, forcing parallel infrastructure investment.
- Open-source solver erosion:Free acoustic toolkits from university consortia satisfy basic radiation problems, pressuring commercial vendors at the entry tier.
Strategic Opportunities
- India automotive supplier base:Maruti Suzuki and Tata Motors suppliers currently underutilize vibro-acoustic simulation, presenting first-mover advantage for localized training and licensing.
- Digital-twin convergence:Coupling acoustic solvers with real-time IoT feedback enables predictive maintenance of rotating machinery in offshore wind installations.
- CE marking acoustic modules:EU machinery directives now require documented noise emission declarations, opening compliance-software subscriptions for industrial equipment exporters.
Industry Challenges
- Multiphysics talent scarcity:Engineers fluent in both structural dynamics and computational acoustics command premium compensation, constraining team scaling at mid-size consultancies.
- Legacy CAD-PLM integration:Acoustic preprocessing requires clean geometry extraction from decades-old automotive CAD hierarchies, consuming specialist hours before any physics computation begins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acoustic Simulation Software Market |
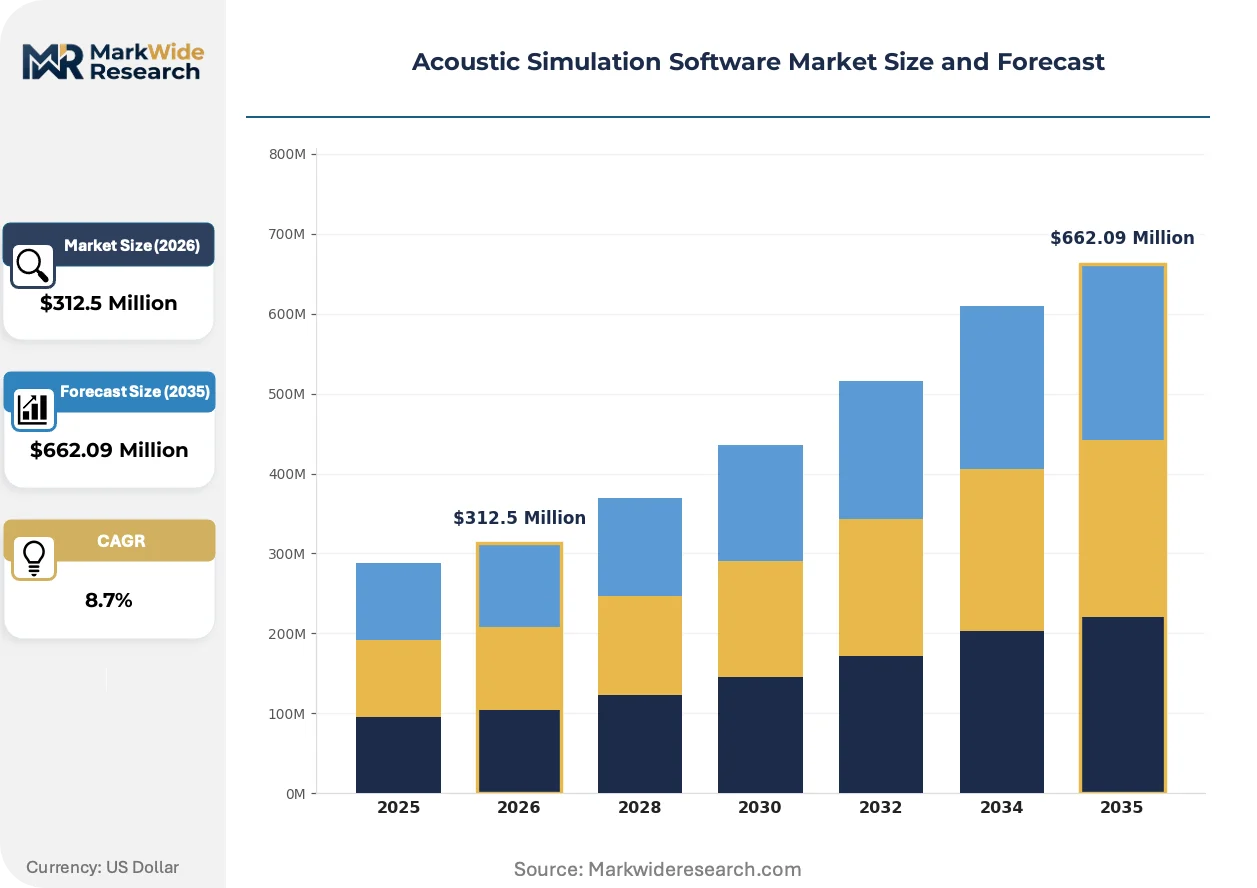
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Simulation, 3D Simulation, Room Acoustics, Noise Mapping Application: Architectural Design, Environmental Studies, Industrial Applications, Entertainment End User: Construction Firms, Acoustic Consultants, Educational Institutions, Research Organizations Deployment: On-Premises, Cloud-Based, Hybrid, Standalone |
| Companies Covered | Autodesk, Altair, ANSYS, COMSOL Multiphysics, ESI Group, Siemens PLM Software, Hexagon AB, PTC, Dassault Systèmes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acoustic Simulation Software Market Trends and Innovations
Wave-based simulation methods are displacing statistical energy analysis for mid-frequency problems, while regulatory pressure and procurement reform simultaneously reshape how engineering software is bought and deployed.
Reduced-order modeling is decomposing full-vehicle acoustic simulations into compact state-space representations that run in real-time. Automotive OEMs embed these surrogates into hardware-in-the-loop test rigs for active noise control calibration. The compression enables iterative design exploration that full-order solvers cannot support within program timelines.
EPA pass-by noise enforcement is tightening measurement tolerances for light trucks and SUVs, forcing suppliers to correlate simulation results against ISO 3744 microphone arrays with documented uncertainty budgets. Heavy-duty diesel manufacturers face the steepest recertification burden as they adapt to the 2027 model-year standards.
Subscription licensing is displacing perpetual seats among tier-two automotive suppliers who cannot forecast multi-year headcount. These buyers prefer monthly consumption models aligned to program phases, compressing vendor cash conversion cycles while expanding addressable accounts. German and Japanese tooling suppliers have been quickest to adopt the new commercial terms.
Acoustic Simulation Software Market Segmentation
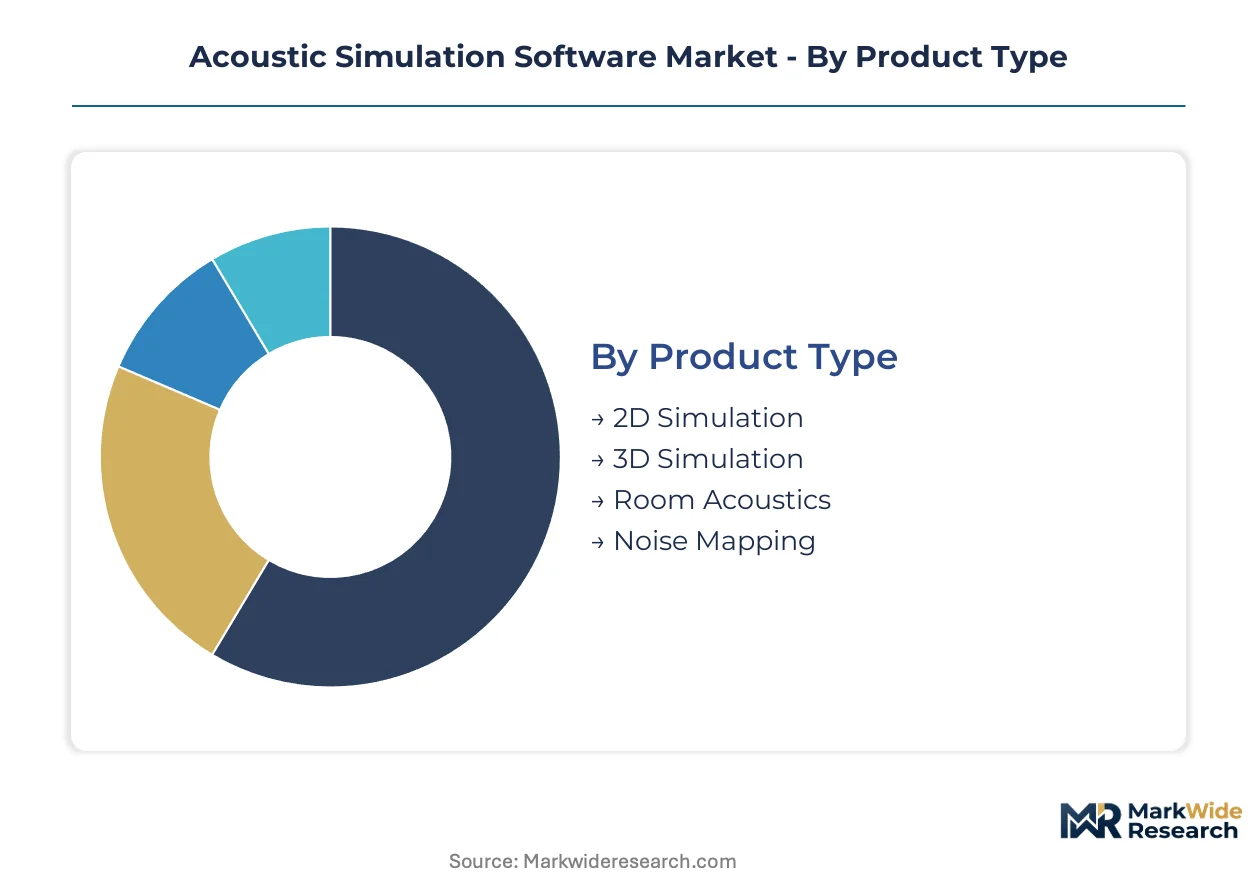
Acoustic simulation software segments reflect divergent compute requirements and regulatory exposure across industries. Procurement patterns split between capital-intensive perpetual licenses and elastic consumption models, with deployment choices increasingly shaped by data sovereignty mandates.
Product Type:
Domestic engineering teams favor 2D solvers for rapid iteration, while export-oriented automotive and aerospace suppliers require 3D capabilities to satisfy ISO certification protocols in Germany, Japan, and the United States.
- 3D Simulation:Full-wave boundary-element and finite-element discretization handle million-element meshes for vehicle pass-by noise validation. German automotive OEMs and Japanese tier-one suppliers anchor demand as Euro 7 and domestic emission-acoustic limits tighten.
- Room Acoustics:Geometric acoustics and wave-based methods model reverberation for concert halls and immersive venues. Dubai, Las Vegas, and Singapore developers specify these tools to meet ISO 3382 standards for esports arenas and performance spaces.
- 2D Simulation:Cross-sectional analysis supports duct and barrier optimization for HVAC and highway noise applications.
- Noise Mapping:Environmental propagation models calculate community noise exposure for urban planning and industrial siting.
3D Simulation holds the largest share; momentum sits with Room Acoustics.
Application:
Cost tiers separate turnkey solutions for small architectural practices from enterprise platforms integrating with PLM stacks at major manufacturers.
- Industrial Applications:Factory noise control and machinery compliance dominate procurement, with EU machinery directives mandating documented emission declarations for CE-marked equipment exports to Europe.
- Architectural Design:Building acoustic codes in Germany and the United States drive specification for residential and commercial developments.
- Environmental Studies:Regulatory impact assessments require propagation modeling for wind farms and transportation corridors.
- Entertainment:Venue acoustics for concert halls, studios, and gaming arenas climbs fastest as immersive experience construction expands.
Industrial Applications commands the revenue base; Entertainment climbs the fastest.
End User:
Customer type determines licensing flexibility, with research organizations demanding multiphysics coupling and construction firms prioritizing visualization speed.
- Acoustic Consultants:Independent engineering practices serving automotive and building sectors require portable licenses and cloud elasticity for project-based workflows.
- Research Organizations:National laboratories and university consortia drive wave-method development and reduced-order modeling innovation.
- Construction Firms:Large developers integrate acoustic checks into BIM workflows for code compliance in Germany and the United States.
- Educational Institutions:University programs train next-generation engineers, sustaining entry-tier solver demand.
Acoustic Consultants holds the largest share; Research Organizations gains share fastest.
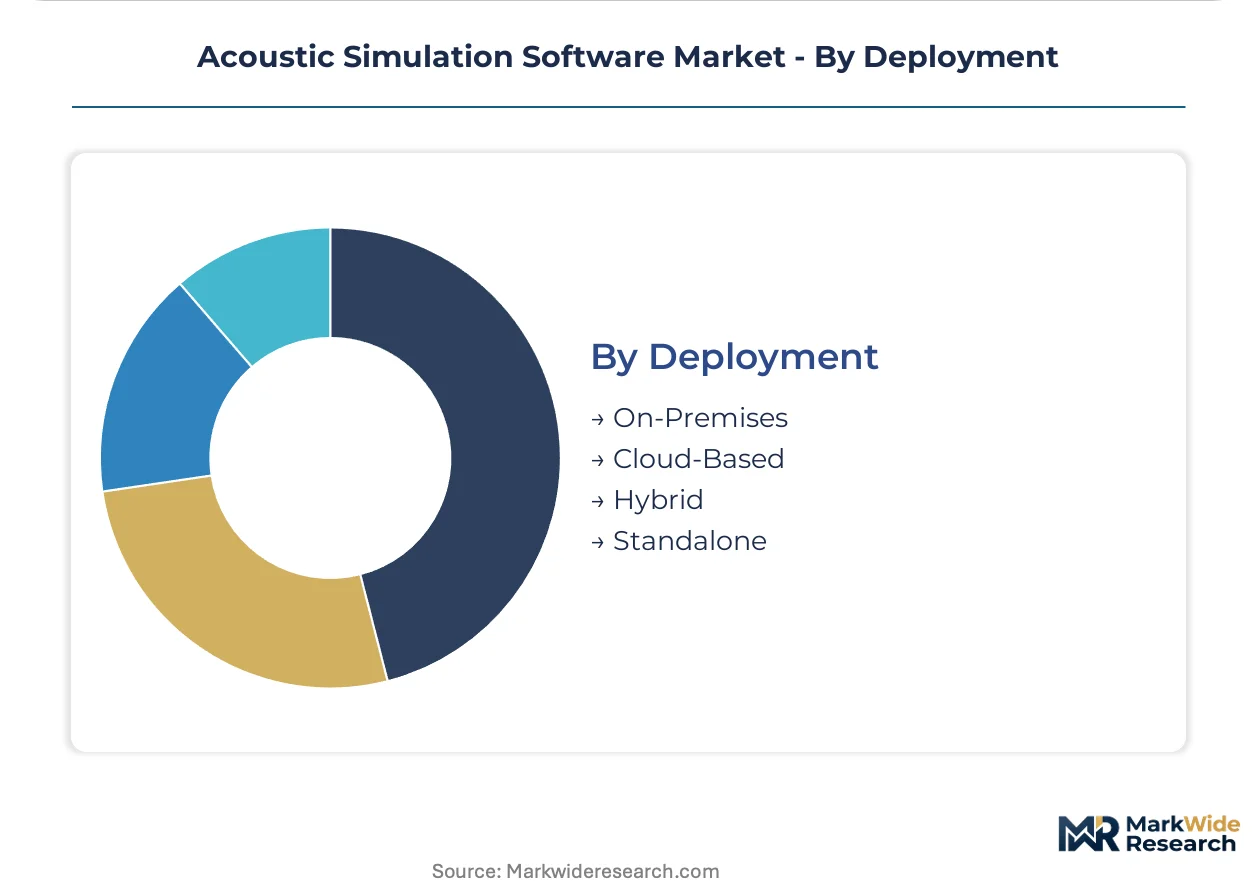
Deployment:
Volume concentration sits with cloud deployments at tier-two suppliers, while defense and aerospace primes retain on-premises infrastructure.
- Cloud-Based:Auto-scaling clusters collapse overnight solve times for boundary-element jobs, with German and Japanese tooling suppliers quickest to adopt subscription terms.
- On-Premises:Captive server farms persist where FAA and defense data-sovereignty rules prohibit commercial cloud migration.
- Hybrid:Split configurations balance elastic burst capacity with sensitive model retention on local hardware.
- Standalone:Perpetual licenses serve isolated workstations in field consulting and small-firm environments.
On-Premises retains the installed base; Cloud-Based expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and tier-one suppliers concentrate procurement in Germany, Japan, and the United States where Euro 7 and EPA pass-by noise standards enforce strict virtual validation mandates. Research institutions and venue developers in Singapore and the UAE drive secondary demand for room acoustics and immersive entertainment applications.
United States
EPA pass-by noise enforcement for light trucks and SUVs tightens measurement tolerances ahead of 2027 model-year standards. NHTSA coordinates with the EPA on acoustic-emission testing protocols. Detroit-area automotive engineering centers and Austin-based simulation software firms anchor domestic solver development and OEM procurement.
Germany
KBA homologation requirements and Euro 7 emission-acoustic limits compel powertrain suppliers to front-load virtual validation. The country's machinery directive mandates CE-marked equipment carry documented noise emission declarations. Stuttgart and Munich host dense clusters of automotive OEM simulation teams and PLM-integrated software vendors.
Japan
METI promotes domestic emission-acoustic standards aligned with international pass-by noise protocols. JIS certification requirements shape software feature specifications for export-oriented manufacturing. Toyota City and Nagoya concentrate tier-one supplier engineering centers deploying boundary-element methods for electric motor NVH analysis.
Singapore
Venue developers specify ISO 3382 reverberation compliance for esports arenas and concert halls in the entertainment district. The country's building control authority enforces strict acoustic codes for mixed-use developments. Marina Bay and Sentosa integrated resorts drive room acoustics software procurement from international consultants.
United Arab Emirates
MOHAP and municipal regulators mandate noise impact assessments for large-scale entertainment and hospitality projects. Dubai's building code requires documented acoustic performance for luxury residential towers. Downtown Dubai and Yas Island developments specify simulation-driven design for immersive experience venues.
Acoustic Simulation Software Market Competitive Landscape
Player mix skews toward diversified engineering software conglomerates with decades of finite-element heritage. The competitive structure consolidates around three tiers: integrated PLM platform vendors, specialized multiphysics specialists, and emerging cloud-native entrants. Dominant competitive moves include digital-twin stack extension and subscription licensing conversion to capture tier-two supplier accounts.
Within the integrated-platform tier, ANSYS, Siemens PLM Software, and Dassault Systèmes exemplify archetypes that couple acoustic solvers with broader CAE portfolios. ANSYS represents legacy finite-element depth, Siemens anchors digital-twin convergence, and Dassault Systèmes occupies the 3DEXPERIENCE integration position. These three exemplify how vendor consolidation around multiphysics workflows shapes procurement decisions at automotive OEMs.
| Leading Market Players |
|---|
| Autodesk |
| Altair |
| ANSYS |
| COMSOL Multiphysics |
| ESI Group |
| Siemens PLM Software |
| Hexagon AB |
| PTC |
| Dassault Systèmes |
| Others |
Pricing and Supply Chain Analysis
High fixed costs in solver development and HPC infrastructure utilization anchor supply concentration among incumbent engineering software conglomerates, compressing price floors for entry-tier toolkits while sustaining premium tiers for multiphysics-integrated platforms. Scale economies in cloud compute provisioning allow tier-two suppliers to access elastic simulation capacity without perpetual license commitment, fragmenting procurement patterns across subscription and perpetual models.
Pricing Analysis
Cost-plus contracts with CPU-hour indexation dominate cloud-based deployments, while perpetual licenses carry maintenance escalators tied to support tier. Pricing stratifies across enterprise PLM-integrated platforms, standalone multiphysics suites, and entry-tier SaaS offerings. Cost compression in the mid-market stems from open-source solver erosion and subscription fatigue among tier-two automotive suppliers. Small architectural practices exhibit highest price sensitivity; defense primes and automotive OEMs prioritize certification depth over license cost.
Supply Chain Analysis
GPU memory fabrication chokepoints in Taiwan and South Korea constrain solver performance scaling for million-element acoustic meshes. Core algorithm development concentrates in Germany, the United States, and Japan, drawing from academic research consortia and national laboratory partnerships. Single-source vulnerability in advanced semiconductor fabrication threatens hardware-in-the-loop deployment timelines. Distribution runs through direct enterprise sales for OEM accounts and value-added resellers serving mid-market consultancies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment around ISO certification protocols and Euro 7 validation workflows creates substantial switching costs for embedded automotive accounts.
For Market Incumbents: Shield core automotive relationships by deepening ISO 3744 correlation tool investments and preempting cloud-native entrants with consumption-based licensing for tier-two suppliers. Open-source solver erosion and GPU memory fragmentation threaten margin sustainability in the entry tier. Vertical integration into real-time reduced-order modeling preserves hardware-in-the-loop calibration revenue. For New Entrants and Emerging Players: CE marking fast-track services for industrial machinery exporters present immediate white-space opportunity, as EU machinery directives mandate documented noise emission declarations that incumbent platforms underprice. India's automotive supplier base remains underpenetrated for vibro-acoustic simulation training and localized licensing. Cloud-native deployment with pay-per-solve metering addresses subscription fatigue among German and Japanese tooling suppliers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with embedded regulatory workflow automation rather than point-solver specialists. Long-term viability hinges on digital-twin convergence with IoT feedback loops for predictive maintenance applications. Watch for EPA pass-by noise enforcement tightening as the signal for accelerated OEM procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Reduced-Order Modeling Integration | Enables real-time hardware-in-the-loop calibration for active noise control at automotive OEMs. |
| Cloud HPC Partnership | Auto-scaling clusters collapse overnight solve times for boundary-element jobs at tier-one suppliers. |
| Regulatory Workflow Certification | Euro 7 and EPA pass-by noise mandates embed vendor platforms into homologation pipelines. |
| Multiphysics Platform Extension | Coupling acoustic solvers with structural dynamics sustains premium pricing at research-intensive accounts. |
| Geographic Training Localization | India automotive supplier base presents first-mover advantage for vibro-acoustic simulation adoption. |
Research Methodology
A standing panel of NVH engineering directors, CAE platform managers, acoustic consultants, and cloud procurement officers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with tier-one automotive suppliers and defense primes with secondary validation against EPA enforcement bulletins, KBA homologation databases, and ISO standard revision timelines. Bottom-up license deployment counts and top-down engineering software spend estimates were triangulated to anchor market sizing.
Consistency checks validated volume and value outputs against hyperscaler HPC revenue disclosures and PLM vendor segment reporting across the projection horizon. The analytical framework modeled deployment mode, end-user type, simulation dimensionality, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from elasticity-adjusted adoption curves and enforcement timeline phasing, with electric motor NVH analysis demand and immersive entertainment construction permitting activity as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained Euro 7 and EPA enforcement timelines; material deviation in regulatory stringency or GPU memory scaling would warrant model refresh. Practitioners should keep alternative scenarios live as cloud data-sovereignty negotiations and open-source solver maturation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Application Server Market
Software & Services
Mobile Tracking Software Market
Software & Services
Global Product Lifecycle Management Software Market
Software & Services
Talent Acquisition Software Market
Software & Services
Global Maintenance Management Software Market
Software & Services
Global MSP Software Market
Software & Services
Session Support Software Market
Software & Services
On-Demand Wellness Software Market
Software & Services
United Kingdom HR Payroll Software Market
Software & Services
Spain HR Payroll Software Market
Software & Services
Global Application Management Services Market
Software & Services
Collaborative Applications Market
Software & Services
HACCP Software Market
Software & Services
CAM Software Market
Software & Services
Photo Editing Software Market
Software & Services
Car-Hailing Software Market