
 Consumer Robotics Market | 2026-2036
Consumer Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Robotics Market Intelligence
Direct-to-consumer online channels is reconfiguring how robot makers reach households, bypassing traditional retail markups and enabling faster feedback loops. Amazon.com Inc. leverages its logistics and marketplace infrastructure to control distribution for multiple robot brands. Samsung Electronics anchors its position through integrated smart-home ecosystems that bundle robots with appliances. Xiaomi competes on manufacturing scale, driving cost compression in vacuum and lawn segments.
Consumer robotics encompasses autonomous or semi-autonomous electromechanical devices designed for non-industrial, household, or personal use, typically integrating brushless DC motors, lithium-ion power systems, and sensor arrays operating at 2.4 GHz or 5 GHz wireless bands for navigation and task execution. These systems serve commercial purposes by automating domestic labor, delivering companionship, or enabling remote monitoring, thereby translating time savings into recurring hardware and software service revenue. Vacuum cleaners and lawn mowers occupy the mature volume tier, where margin pools have shifted toward replacement parts and subscription mapping services. Educational robots represent the fastest-growing product category as schools and parents prioritize STEM skill development. Artificial intelligence and computer vision technologies concentrate value capture, since proprietary algorithms differentiate performance in cluttered, unstructured home environments.
The Federal Communications Commission governs wireless spectrum allocation for robot connectivity in the United States, while the EU AI Act imposes risk-classification requirements on autonomous domestic systems sold in Europe. China's Ministry of Industry and Information Technology enforces GB standards for battery safety and electromagnetic compatibility, shaping which designs gain market access. Japan's Ministry of Economy, Trade and Industry promotes JIS certification for elder-care robots, directing R&D investment toward senior-assistance applications. Stakeholders must monitor how diverging AI liability frameworks across these jurisdictions affect product architecture and insurance costs.
Market Dynamics
Edge AI processing is compressing hardware costs while simultaneously elevating real-time navigation performance, forcing incumbents to re-architect product lines around on-device inference rather than cloud-dependent architectures.
Growth Catalysts
- EU AI Act risk-classification framework:The regulation's clarity on autonomous domestic system requirements accelerates product certification timelines for manufacturers targeting European households.
- STEM curriculum mandates:Educational institutions across Germany and South Korea are embedding robotics modules into primary education, expanding the addressable base for programmable robot kits.
- LiDAR sensor cost curves:Automotive-scale manufacturing is driving component prices downward, enabling premium navigation features in mid-tier vacuum and lawn segments.
Market Restraints
- Lithium-ion supply concentration:Battery cell production clusters in China's Jiangsu and Fujian provinces create single-source dependency risks for non-integrated robot assemblers.
- GB standards compliance overhead:MIIT electromagnetic compatibility testing adds six to nine months to market entry timelines for foreign brands.
- Manual cleaning substitution:Low-wage domestic labor in Southeast Asian markets limits price elasticity for autonomous floor-care devices.
Strategic Opportunities
- India smart-home infrastructure buildout:The country's PLI scheme for electronics manufacturing is attracting component suppliers to establish local assembly for cost-optimized regional SKUs.
- Elder-care robot certification pathway:METI's JIS standards for senior assistance create a regulated premium tier with dedicated reimbursement channels through Japanese municipal health programs.
- Direct-to-consumer subscription bundling:Mapping-as-a-service and consumable auto-replenishment models bypass retail margin extraction while capturing lifetime value.
Industry Challenges
- Edge AI firmware talent scarcity:Embedded machine-learning engineering commands premium compensation in Shenzhen and Seoul labor markets, constraining R&D velocity for mid-tier vendors.
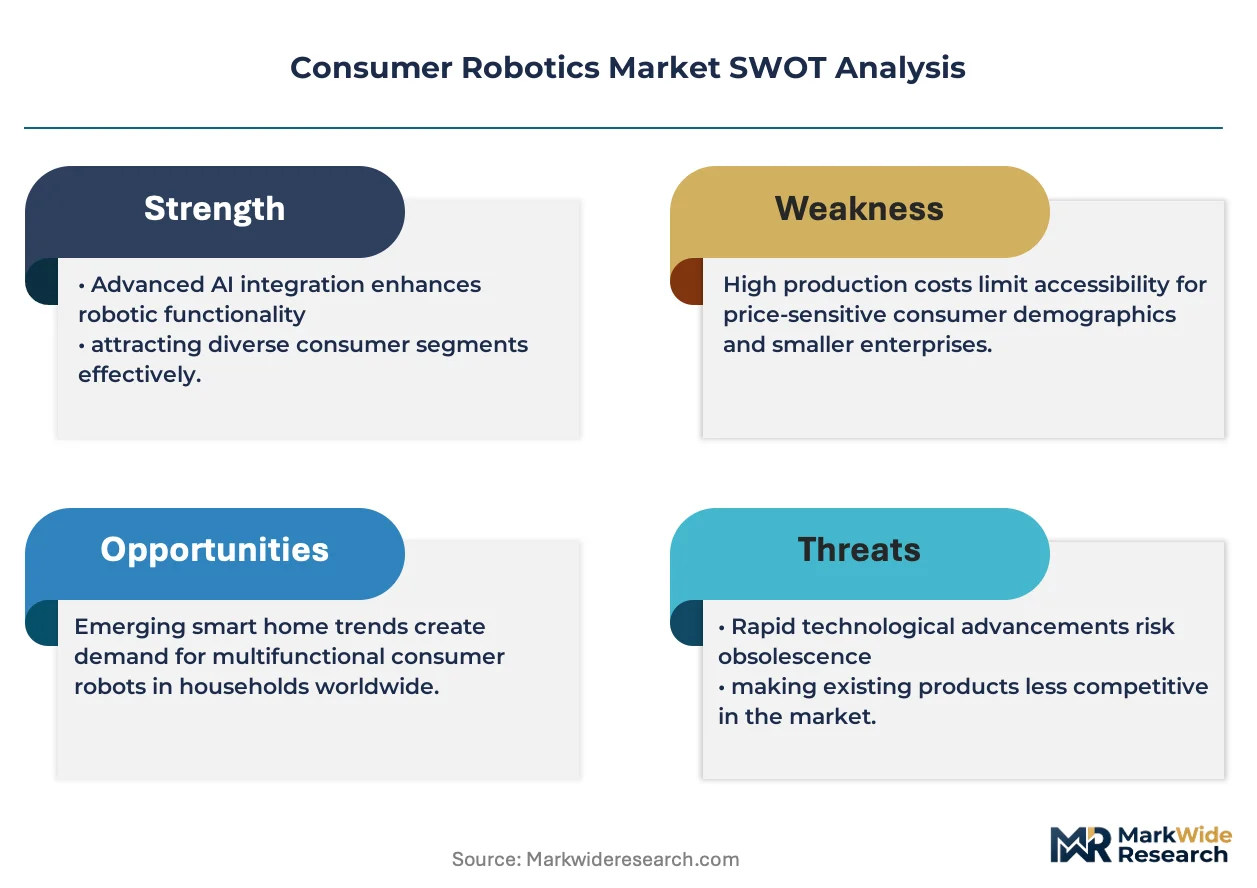
- Multi-jurisdiction liability fragmentation:Diverging product safety and AI accountability frameworks across the United States, European Union, and China force parallel legal architecture investments.
- Legacy smart-home protocol integration:Thread, Zigbee, and proprietary ecosystem standards create interoperability engineering burdens for cross-platform robot deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Robotics Market |
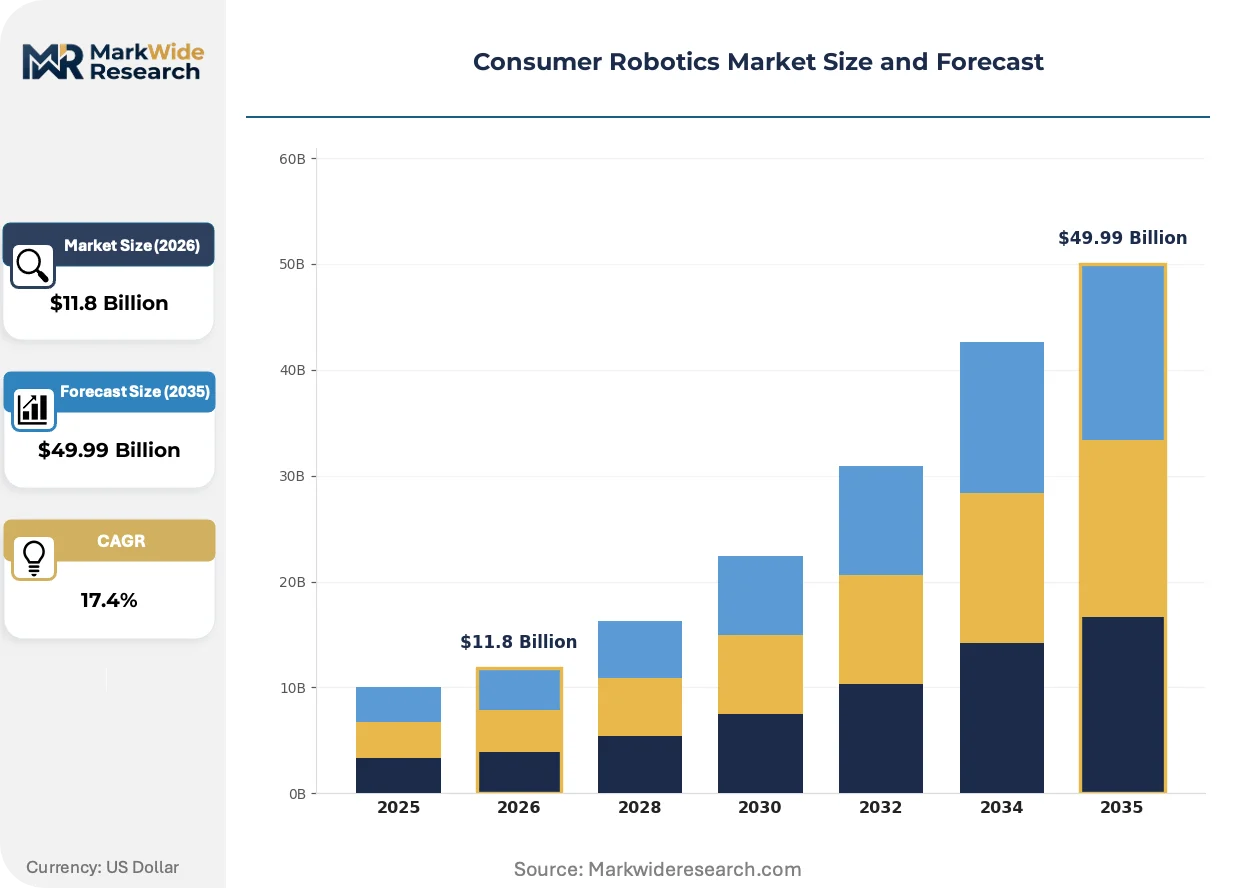
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Cleaners, Lawn Mowers, Educational Robots, Entertainment Robots, Security Robots Technology: Artificial Intelligence, Machine Learning, Computer Vision, Sensor Fusion, Voice Recognition, Connectivity Application: Home Automation, Personal Assistance, Child Education, Pet Care, Surveillance, Leisure End User: Households, Educational Institutions, Hobbyists, Seniors, Tech Enthusiasts |
| Companies Covered | LG Electronics, 1X Technologies, Amazon.com Inc., Apptronik, Boston Dynamics, Samsung Electronics, Xiaomi, Geek+, Honda Motor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Robotics Market Strategic Shifts & Innovations
Computational architectures and distribution channels are undergoing simultaneous transformation, compressing development cycles while expanding addressable household segments through lower entry price points.
Vision-based simultaneous localization and mapping (SLAM) is migrating from cloud-dependent processing to on-device neural engines. Mid-market vacuum manufacturers are adopting this shift within eighteen-month product refresh cycles. The migration from centralized inference is enabling real-time obstacle recognition without latency penalties or subscription dependencies, collapsing the performance gap between premium and standard tiers.
The EU AI Act's risk-classification requirements for autonomous domestic systems are reshaping product development roadmaps. High-risk categorization for elder-care and surveillance-capable robots mandates conformity assessment procedures that extend certification timelines. German and French distributors are prioritizing inventory positions for devices that achieve CE marking under the new framework ahead of competitors.
Households are consolidating robot purchases around ecosystem-integrated bundles rather than standalone devices. Samsung's SmartThings and Amazon's Alexa platforms are capturing attachment rates for complementary appliances through cross-device automation scripting. This concentration is most pronounced in United States metropolitan markets where whole-home renovation projects incorporate pre-configured robot docking infrastructure.
Consumer Robotics Market Segmentation
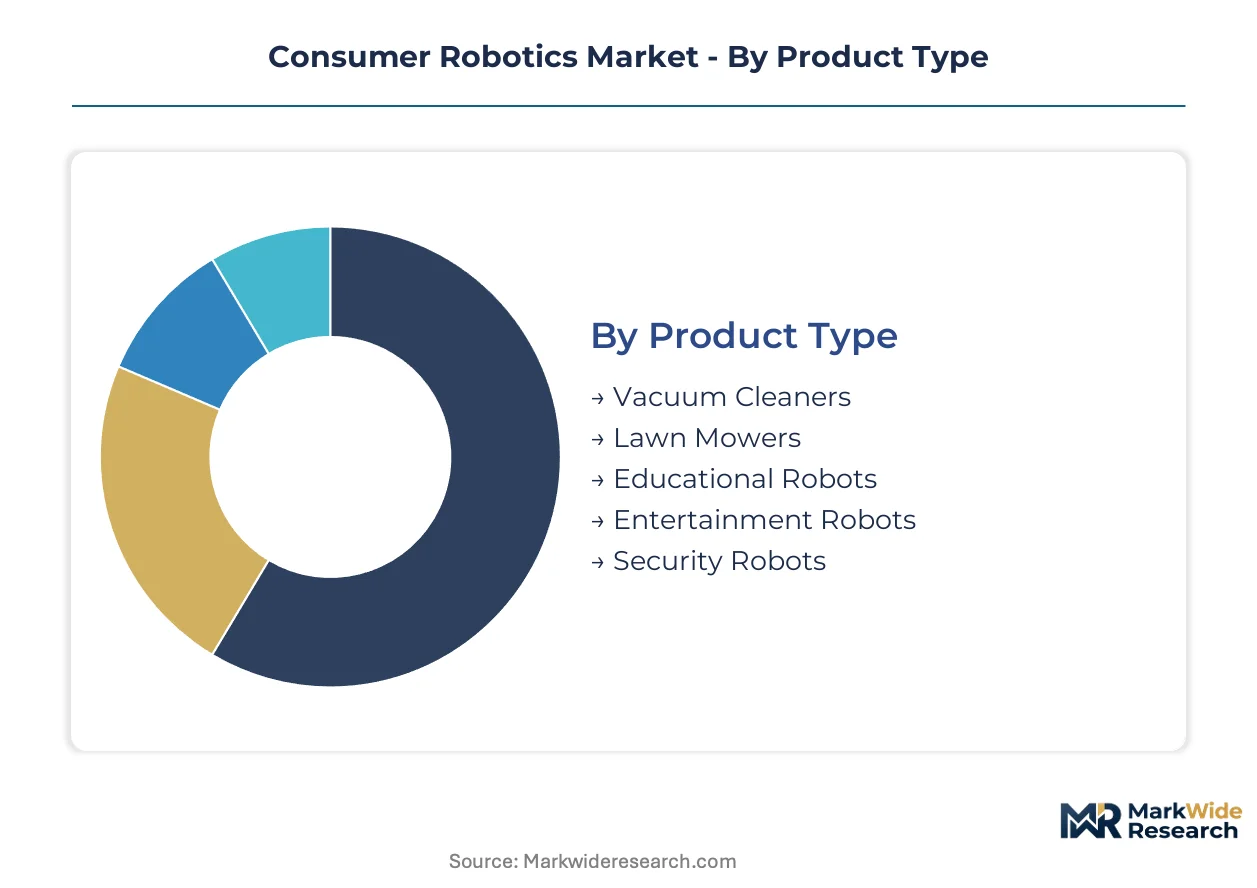
Segmentation in consumer robotics reveals how hardware refresh cycles, software monetization potential, and user sophistication intersect to create distinct profit pools. Understanding these divides helps manufacturers allocate R&D budgets between mature volume categories and emerging premium tiers.
Product Type:
Vacuum cleaners and lawn mowers turn over on 3-4 year replacement cycles as battery degradation and brush wear drive hardware refresh, while educational and entertainment robots face slower obsolescence unless curriculum standards or content libraries shift.
- Vacuum Cleaners:Autonomous floor-care units integrate brushless DC motors, LiDAR or vSLAM navigation, and HEPA filtration systems. Demand concentrates in United States metropolitan households where dual-income families prioritize time savings over manual cleaning labor.
- Lawn Mowers:Robotic grass-cutting systems deploy boundary wire or GPS-RTK positioning with rain sensors and anti-theft tracking. German suburban markets anchor adoption due to strict noise ordinances and large lot sizes that justify capital expenditure against landscaping services.
- Educational Robots:Programmable kits teaching coding and mechanical engineering fundamentals.
- Entertainment Robots:Companion and toy systems emphasizing social interaction and content delivery.
- Security Robots:Mobile surveillance platforms with patrol scheduling and anomaly detection capabilities.
Vacuum cleaners anchor the volume base while educational robots gain share at the steepest rate.
Technology:
Cost tier stratification separates premium on-device inference from cloud-dependent budget alternatives, with sensor fusion and voice recognition occupying mid-tier price bands.
- Artificial Intelligence:Proprietary neural networks enabling real-time decision-making without cloud latency. Edge AI deployment in United States and Chinese flagship products differentiates performance in cluttered residential environments.
- Computer Vision:Convolutional neural networks processing RGB-D feeds for object recognition and obstacle avoidance. German and Japanese manufacturers leverage this technology for elder-care navigation safety under METI and EU AI Act compliance frameworks.
- Machine Learning:Adaptive algorithms improving task efficiency through usage pattern analysis.
- Sensor Fusion:Integration of IMU, ultrasonic, and optical data streams for localization.
- Voice Recognition:Natural language interfaces for command input and status queries.
- Connectivity:Wi-Fi, Thread, and Zigbee protocols for ecosystem integration and remote monitoring.
Computer vision commands premium pricing while connectivity standardization expands addressable market breadth.
Application:
Application maturity correlates with task predictability—home automation and surveillance offer repeatable revenue streams while pet care and leisure remain experimental.
- Home Automation:Integrated cleaning, climate, and lighting control through centralized robot hubs. United States smart-home infrastructure buildout in California and Texas metropolitan clusters drives attachment rates for multi-function systems.
- Surveillance:Mobile monitoring with cloud storage and real-time alert distribution. Chinese urban households deploy these systems for property security in high-density residential complexes.
- Personal Assistance:Schedule management, medication reminders, and mobility support functions.
- Child Education:STEM skill development through interactive programming interfaces.
- Pet Care:Automated feeding, interaction, and activity monitoring for companion animals.
- Leisure:Gaming, photography, and social entertainment applications.
Home automation generates the highest recurring revenue per installed base while pet care applications expand most quickly among millennial households.
End User:
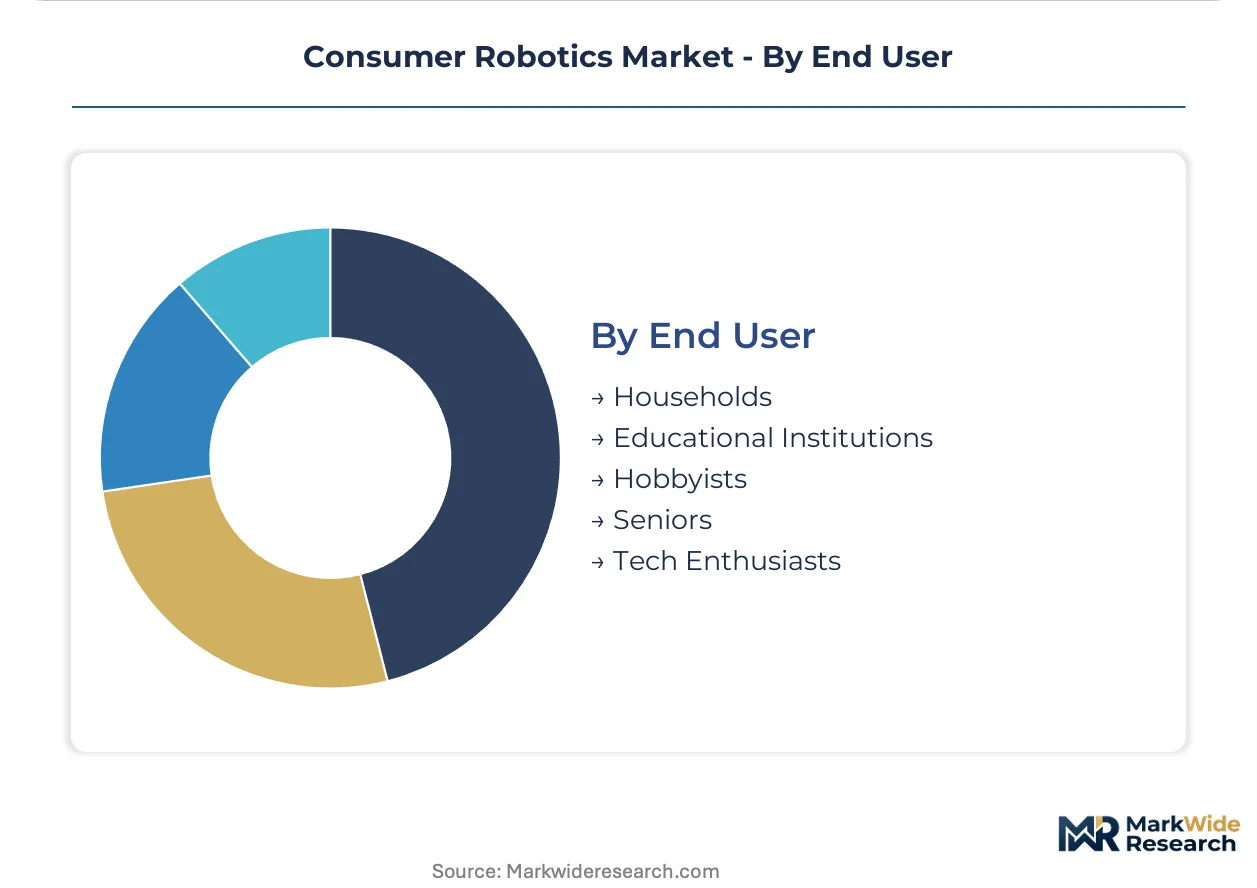
Customer sophistication spans from price-sensitive mass-market households to specification-driven hobbyists, with educational institutions representing institutional procurement cycles.
- Households:Residential purchasers seeking labor substitution and convenience enhancement. United States and German markets dominate this segment where smart-home penetration exceeds regional averages.
- Educational Institutions:Schools and universities procuring curriculum-integrated robotics platforms. South Korean public education mandates and German federal state STEM programs institutionalize demand.
- Hobbyists:Enthusiast builders and modders prioritizing customization over out-of-box functionality.
- Seniors:Aging populations requiring assistance with daily living tasks and remote health monitoring.
- Tech Enthusiasts:Early adopters evaluating cutting-edge features before mainstream availability.
Households provide the installed base foundation while educational institutions drive the steepest order volume expansion through centralized procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart-home grid interconnects in Austin and Dallas underwrite United States demand concentration. Submarine cable landing stations in Singapore and Hong Kong channel data traffic for Asia-Pacific robotics ecosystems. High-speed rail corridors between Beijing and Shanghai compress component logistics cycles for Chinese manufacturers.
United States
Metropolitan smart-home renovation projects in California and Texas drive multi-device ecosystem attachment. The FCC governs wireless spectrum allocation for robot connectivity under Part 15 rules. Seattle and San Francisco Bay Area clusters concentrate cloud robotics engineering talent for platform development.
Germany
Dual-income suburban households prioritize autonomous lawn systems amid strict municipal noise ordinances. The EU AI Act imposes risk-classification requirements on elder-care and surveillance-capable robots. Bavarian industrial zones around Munich host precision sensor manufacturers serving mid-tier vacuum producers.
China
High-density urban residential complexes generate demand for mobile surveillance and floor-care automation. MIIT enforces GB standards for battery safety and electromagnetic compatibility testing. Jiangsu and Fujian provinces concentrate lithium-ion cell production for robot power systems.
Japan
Aging demographics accelerate senior-assistance robot procurement through municipal health reimbursement channels. METI promotes JIS certification for elder-care applications, directing R&D investment toward mobility support functions. Tokyo-Osaka manufacturing corridors integrate precision motor production with domestic robot assembly.
South Korea
National STEM curriculum mandates institutionalize demand for programmable educational robot kits. The country's electronics regulator shapes wireless protocol standards for classroom device deployment. Seoul Capital Area clusters concentrate edge AI firmware engineering talent for navigation system development.
Consumer Robotics Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream controlling sensor and motor supply. The market structures around three tiers: ecosystem-anchored conglomerates, manufacturing-scale specialists, and venture-backed humanoid developers. Consolidation pressures concentrate around smart-home protocol integration and mapping software subscriptions. Dominant competitive moves include direct-to-consumer channel bypass of retail markups and edge AI firmware acquisitions.
Within the ecosystem-anchored tier, Amazon.com Inc. and Samsung Electronics represent platform integrators leveraging logistics infrastructure and appliance bundling respectively. Xiaomi occupies a position exemplifying manufacturing-scale cost compression in volume segments. Boston Dynamics anchors the venture-backed humanoid archetype, sitting within the premium-tier development trajectory for general-purpose mobility systems.
| Leading Market Players |
|---|
| LG Electronics |
| 1X Technologies |
| Amazon.com Inc. |
| Apptronik |
| Boston Dynamics |
| Samsung Electronics |
| Xiaomi |
| Geek+ |
| Honda Motor |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese lithium-ion cell manufacturing is compressing supplier margins while enabling aggressive pricing postures for robot assemblers. Jiangsu and Fujian province utilization rates below break-even thresholds force battery vendors to absorb cost volatility, transferring pricing power downstream to brands with volume commitments.
Pricing Analysis
Volume-discount tiering structures separate flagship edge-AI products from cloud-dependent standard units and white-label economy alternatives. Premium tiers command pricing power through proprietary SLAM algorithms and METI elder-care certification, while standard segments face margin erosion from Xiaomi's manufacturing scale. Price differentiation hinges on on-device inference capability and EU AI Act compliance grade. Budget-conscious Southeast Asian households exhibit highest price sensitivity; German dual-income suburban buyers prioritize performance over cost.
Supply Chain Analysis
Extended payment terms from Shenzhen contract manufacturers to Jiangsu battery suppliers indicate working capital stress propagating upstream. Component sourcing concentrates in China for lithium-ion cells, South Korea for OLED displays, and Japan for precision brushless motors. Raw material dependencies span cobalt from the DRC, rare earth magnets from China, and copper from Chile. Single-source vulnerability in MIIT-certified battery testing creates regulatory chokepoints. Distribution runs through Amazon marketplace infrastructure and direct-to-consumer channels, bypassing traditional retail markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge AI processing inflection is compressing product refresh cycles from thirty-six to eighteen months, creating asymmetric returns for firmware-capable vendors. EU AI Act risk-classification clarity accelerates certification timelines for compliant manufacturers.
For Market Incumbents: Build algorithmic moats through proprietary SLAM neural networks trained on cluttered residential environments. Acquire edge-AI firmware engineering teams in Seoul and Shenzhen to defend against venture-backed humanoid entrants. Invest in JIS elder-care certification to capture Japanese municipal reimbursement channels. Secure long-term lithium supply offtake from Fujian province to mitigate single-source battery risk. For New Entrants and Emerging Players: Mid-market educational robot kits in South Korean public schools represent the most penetrable entry point given national STEM curriculum mandates. Indian smart-home infrastructure buildout under PLI electronics schemes offers second-mover advantage for cost-optimized regional SKUs. Partner with local component assemblers in Noida and Chennai to bypass GB standards compliance overhead for foreign brands. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across vacuum and lawn segments as automotive-scale LiDAR cost curves enable mid-tier navigation features. Long-term viability favors platform-integrated conglomerates with mapping-as-a-service subscription revenue over hardware-only vendors. Monitor EU AI Act CE marking velocity as inflection indicator for European market access competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Firmware Acquisition | Proprietary on-device inference differentiates performance in cluttered home environments against cloud-dependent rivals. |
| Direct-to-Consumer Channel Expansion | Amazon marketplace infrastructure enables subscription bundling while capturing lifetime value beyond hardware margins. |
| EU AI Act Certification Investment | CE marking under risk-classification framework accelerates product approval timelines for elder-care and surveillance segments. |
| JIS Elder-Care Certification Pathway | METI standards unlock Japanese municipal health reimbursement channels for senior-assistance robot procurement. |
| LiDAR Sensor Supply Agreement | Automotive-scale component pricing enables premium navigation features in mid-tier vacuum and lawn product tiers. |
Research Approach
Operator-level perspectives from robot OEM product managers, smart-home platform engineers, lithium-ion procurement leads, and MIIT certification consultants anchored the qualitative base. Secondary validation drew from FCC Part 15 filings, EU AI Act implementation guidance, MIIT GB standard disclosures, and Amazon marketplace seller data. Bottom-up unit economics triangulated against top-down smart-home penetration curves across United States, German, and Chinese metropolitan clusters.
Scenario-bracketing framed demand trajectories across optimistic, baseline, and constrained adoption paths over the projection horizon. Segmentation dimensions modeled include product type, technology tier, application maturity, and end-user sophistication. CAGRs derived from hardware refresh cycle compression and software monetization attach rates. Forecast inputs incorporated LiDAR cost curve slopes and STEM curriculum mandate expansion timelines.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending, lithium commodity volatility, or cross-border semiconductor logistics would shift the trajectory. Forecasts reflect documented assumptions about edge-AI processing adoption curves and regulatory certification timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
France Cloud Robotics Market
Robotics and Automation
Japan Cloud Robotics Market
Robotics and Automation
Europe AUV Market
Robotics and Automation
Asrs and Ruos Market
Robotics and Automation
Smart Worker Market
Robotics and Automation
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market
Robotics and Automation
Global Construction Robot Market
Robotics and Automation
Pipetting Robots Market
Robotics and Automation
Hospital Robots Market
Robotics and Automation
Rehabilitation Robot Gloves Market
Robotics and Automation
Indonesia Robotics Market
Robotics and Automation
Robot As a Service Market
Robotics and Automation
Electric Power Intelligent Inspection Robot Market
Robotics and Automation
Middle East and Africa Underwater Robotics Market
Robotics and Automation
Underwater Exploration Robots Market
Robotics and Automation
Robotics Actuators Market