
 AI Powered Robot Market | 2026-2036
AI Powered Robot Market Size, Share, and Industry Trends Forecast 2026-2036
AI Powered Robot Market Analysis
The EU AI Act is broadening the compliance burden for autonomous robot deployments across European manufacturing floors. NVIDIA Corporation leverages its GPU-accelerated inference stacks to anchor real-time decision-making in dynamic environments. Boston Dynamics sustains leadership in legged locomotion platforms for unstructured terrain navigation. Fanuc dominates traditional industrial automation while integrating AI-driven predictive maintenance into its controller architectures.
An AI powered robot fuses artificial intelligence algorithms with electromechanical actuation to perceive, plan, and execute tasks without constant human oversight, typically incorporating lidar arrays, force-torque sensors, and edge-computing modules operating at sub-50-millisecond loop times for safety-critical feedback. Industrial robots retain the largest installed base across automotive and electronics manufacturing, though collaborative robots are capturing the fastest expansion as small-batch producers seek flexible redeployment without hard guarding. Machine learning underpins most advanced perception stacks, while computer vision handles the bulk of quality-inspection and pick-and-place workloads where pixel-level defect detection determines throughput economics.
The US FDA and FAA maintain parallel jurisdiction over medical and aerial robotic systems respectively, with the former scrutinizing surgical autonomy levels and the latter calibrating beyond-visual-line-of-sight waivers for commercial drone logistics. China's MIIT and SAMR jointly enforce GB standards for industrial robot safety and algorithmic transparency in public-facing service deployments. Japan's METI coordinates the national robotics roadmap through JIS certification benchmarks that manufacturers must clear for domestic procurement eligibility. Stakeholders must track which regulatory body claims primacy over multimodal robots that cross traditional sector boundaries, as jurisdictional overlap will determine market-access timelines before certification harmonization emerges.
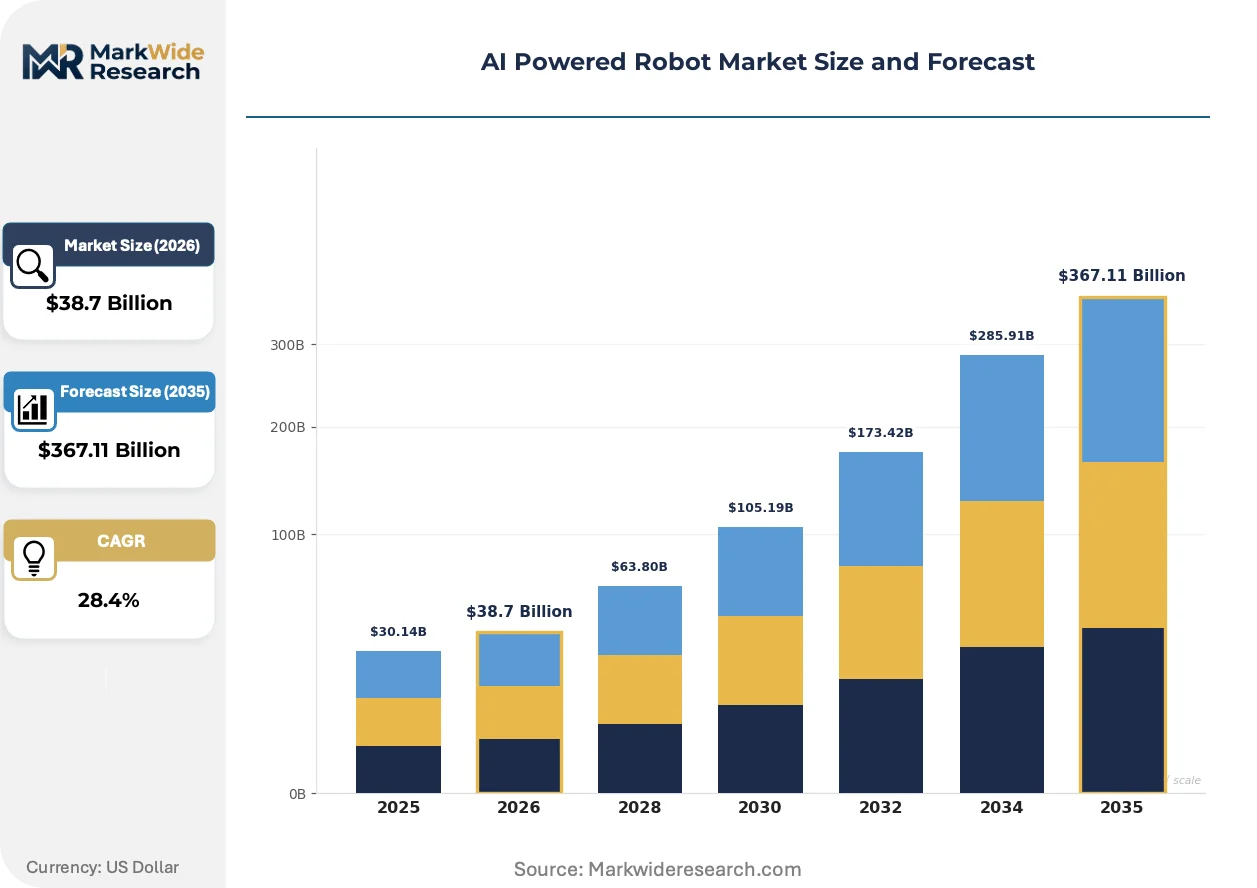
Market Dynamics
GPU-accelerated edge inference is compressing robot response latencies below human reaction thresholds, forcing traditional programmable logic controllers into obsolescence across safety-critical manufacturing cells.
Growth Catalysts
- EU AI Act Conformity Mandates:European manufacturers face mandatory algorithmic transparency requirements for autonomous systems, accelerating replacement cycles for legacy non-compliant robot fleets in German automotive plants.
- Collaborative Robot Density:Small-batch electronics producers in Shenzhen and Shanghai deploy force-limited cobots without hard guarding, slashing reconfiguration downtime between product generations.
- Edge Computing Module Integration:Sub-50-millisecond control loops enabled by onboard inference chips permit real-time trajectory adjustments in dynamic warehouse environments previously requiring human oversight.
Market Restraints
- High-Precision Sensor Cost Volatility:Lidar arrays and force-torque sensors constitute 35-40% of bill-of-materials costs, with supply concentrated among Japanese and German component specialists.
- GB Standard Certification Friction:China's MIIT and SAMR enforce divergent testing protocols for industrial safety versus algorithmic transparency, extending type-approval timelines for multimodal service robots.
- Residual Manual Labor Substitution:Contract electronics assembly in Vietnam and Mexico retains cost advantages for high-mix, low-volume production runs where robot programming overhead exceeds labor arbitrage savings.
Strategic Opportunities
- Indian Pharmaceutical Packaging:CDSCO's phased manufacturing program incentivizes domestic robot assembly for sterile fill-finish operations, creating first-mover advantages for compliant system integrators.
- Computer Vision-Force Control Convergence:Tactile sensing fused with pixel-level defect detection enables bin-picking of deformable objects in food processing, opening segments previously closed to rigid automation.
- Japan's JIS Certification Fast-Track:METI's streamlined benchmarks for domestic procurement eligibility reward manufacturers who co-develop controllers with Japanese semiconductor foundries.
Industry Challenges
- Multi-Domain Control Systems Integration:Synchronizing motion planning, safety interlocks, and AI inference stacks requires rare cross-functional expertise spanning mechanical, electrical, and machine learning engineering disciplines.
- FDA Surgical Autonomy Documentation:Medical robot developers face 18-24 month premarket submission timelines for autonomous tissue manipulation features, compressing competitive windows against manual laparoscopic alternatives.
- Legacy PLC Architecture Migration:Brownfield facilities in Michigan and Stuttgart struggle to retrofit decades-old relay logic without production halt windows exceeding available capex depreciation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Powered Robot Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $367.11 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Service Robots, Industrial Robots, Collaborative Robots, Humanoid Robots Technology: Machine Learning, Natural Language Processing, Computer Vision, Sensor Integration End User: Manufacturing, Healthcare, Agriculture, Retail Application: Assembly, Cleaning, Delivery, Surveillance |
| Companies Covered | ABB, Boston Dynamics, NVIDIA Corporation, Fanuc, SoftBank Group Corp, Hanson Robotics, YASKAWA ELECTRIC CORPORATION, Figure AI, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Powered Robot Market Emerging Trajectories
Foundation model architectures trained on synthetic manipulation datasets are crossing the sim-to-real gap, enabling zero-shot generalization to novel objects without task-specific engineering.
Transformer-based vision-language models are consolidating perception and planning into unified neural architectures, eliminating the hand-engineered feature extraction pipelines that previously dominated industrial computer vision. Tier-one automotive suppliers in Germany and Japan deploy these systems for unstructured bin-picking of irregular castings, achieving pick success rates above human baseline within weeks rather than months of deployment. The compression of integration timelines is consolidating competitive advantage toward firms with proprietary synthetic data generation capabilities.
The EU AI Act's risk-classification framework for autonomous systems is tightening conformity assessment requirements for robots operating in public spaces and collaborative manufacturing environments. Industrial robot OEMs must now maintain technical documentation spanning training data provenance, model performance metrics, and human oversight protocols for high-risk applications. German automotive manufacturers are responding by pre-certifying controller architectures through notified bodies, front-loading compliance costs to secure preferential procurement positioning under the EU Green Deal's automation incentives.
Japanese electronics assemblers are unbundling robot hardware from software service contracts, shifting from perpetual licensing to usage-based pricing indexed by operational hours and successful cycle completions. This consumption model is displacing traditional capex-heavy procurement committees with operational expenditure approvals managed by plant engineering managers directly. The shift is most visible in South Korea's display panel sector, where MFDS-registered medical device manufacturers now demand similar flexibility for cleanroom automation retrofits.
AI Powered Robot Market Segmentation
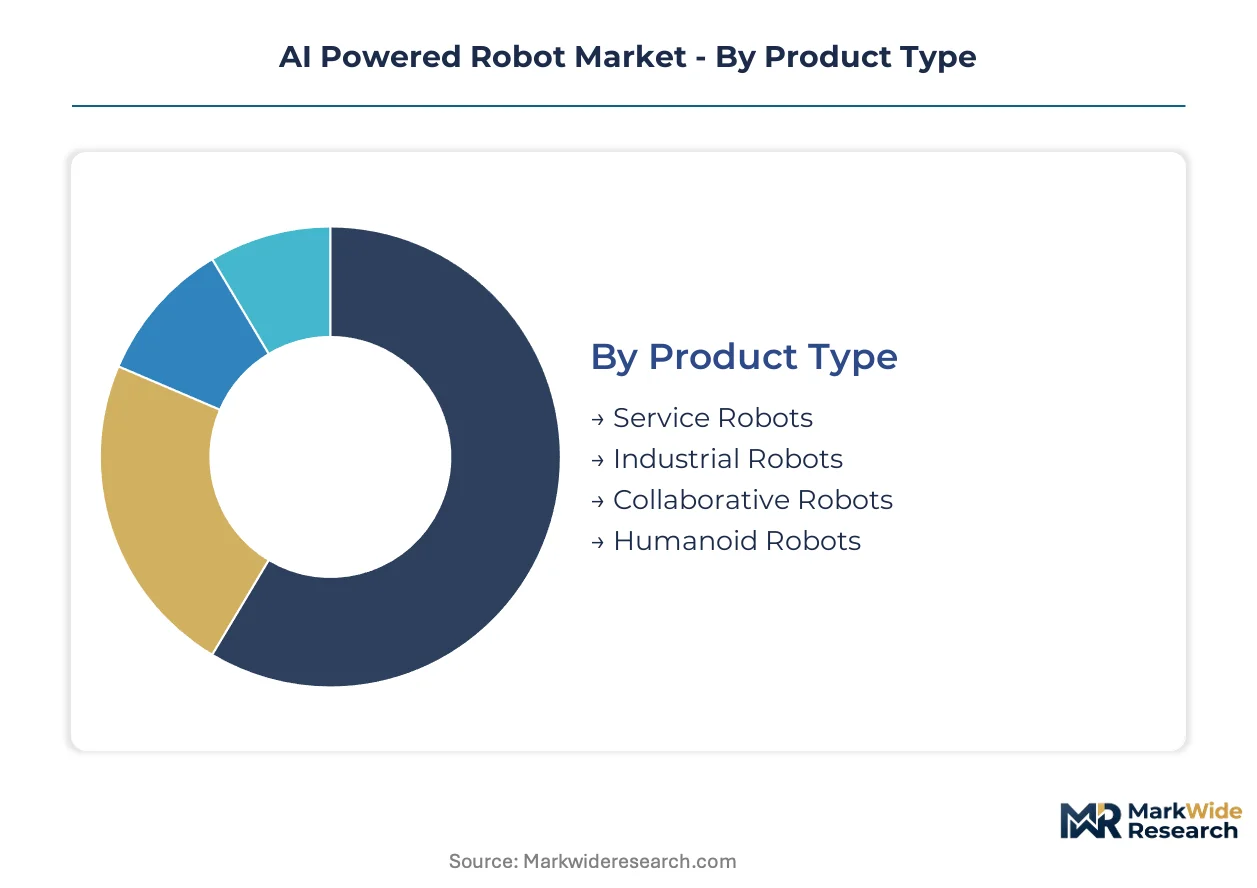
Segmentation in the AI powered robot market reveals how hardware configurations, software stacks, and deployment contexts determine procurement criteria. Buyers prioritize different performance thresholds across manufacturing floors versus public spaces. Understanding these divides clarifies why certain technology combinations command premium positioning while others compete on reconfiguration speed.
Product Type:
Customization intensity varies sharply across this category, from mass-produced industrial arms to bespoke humanoid platforms requiring extensive task-specific tuning.
- Service Robots:Mobile platforms integrate lidar arrays and edge inference modules for navigation in unstructured environments like hospital corridors and retail aisles. Healthcare networks in Germany and Japan deploy these for medication delivery, driven by EU AI Act transparency requirements for autonomous public-space operation.
- Industrial Robots:Six-axis articulated arms dominate automotive welding and electronics assembly with sub-millimeter repeatability. German OEMs anchor demand as they retrofit Stuttgart and Wolfsburg plants with predictive maintenance controllers to meet EU Green Deal automation incentives.
- Collaborative Robots:Force-limited arms operate without hard guarding, enabling small-batch producers to slash reconfiguration downtime between product generations.
- Humanoid Robots:Bipedal platforms target logistics and inspection tasks requiring human-scale manipulation in legacy facilities designed around anthropometric workspaces.
Leading the category by volume: Industrial Robots. Growing fastest: Collaborative Robots.
Technology:
Cost tier stratification separates capital-intensive sensor fusion from software-only perception stacks that run on commodity compute.
- Machine Learning:Neural networks trained on synthetic manipulation datasets enable zero-shot generalization to novel objects without task-specific engineering. Foundation model architectures are compressing integration timelines for automotive suppliers in Germany and Japan.
- Computer Vision:Pixel-level defect detection pipelines handle quality inspection and pick-and-place workloads where throughput economics hinge on false-negative rates. Transformer-based vision-language models are consolidating perception and planning into unified architectures.
- Natural Language Processing:Voice interfaces enable non-technical operators to reprogram service robots without scripting expertise, expanding deployability in small-facility settings.
- Sensor Integration:Lidar arrays and force-torque sensors constitute 35-40% of bill-of-materials costs, with supply concentrated among Japanese and German component specialists.
Commanding the highest R&D allocation: Machine Learning. Expanding most quickly: Computer Vision.
End User:
Application maturity determines whether buyers prioritize proven reliability or experimental flexibility in their procurement specifications.
- Manufacturing:Automotive and electronics producers deploy the largest installed base, with German plants accelerating cobot density to meet EU AI Act conformity mandates.
- Healthcare:Surgical systems and medication delivery robots face FDA premarket timelines of 18-24 months for autonomous tissue manipulation features. German hospital networks are pre-certifying architectures through notified bodies to front-load compliance costs.
- Agriculture:Computer vision-force control convergence enables bin-picking of deformable produce, opening segments previously closed to rigid automation.
- Retail:Inventory scanning and customer service robots operate in public spaces, triggering EU AI Act risk-classification requirements for algorithmic transparency documentation.
Dominating current installations: Manufacturing. Gaining share fastest: Healthcare.
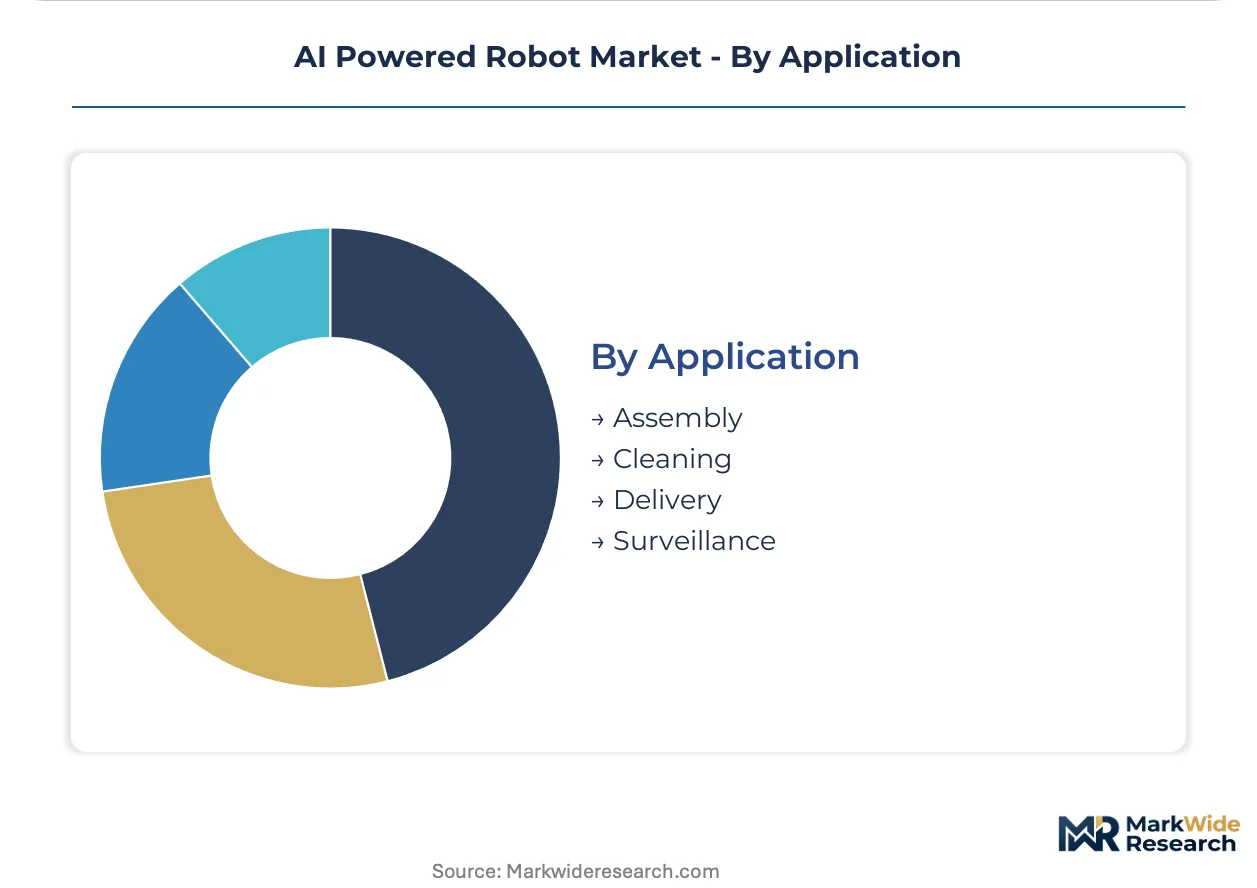
Application:
Customer type differentiation separates high-volume repetitive tasks from intermittent, condition-dependent deployments requiring adaptive decision-making.
- Assembly:Force-controlled insertion and precision fastening operations demand sub-50-millisecond control loops for safety-critical feedback. German automotive suppliers deploy these systems for unstructured bin-picking of irregular castings.
- Delivery:Last-mile logistics robots require beyond-visual-line-of-sight waivers from the FAA in the US and equivalent permissions from China's CAAC for commercial drone operations.
- Cleaning:Autonomous floor-scrubbing platforms integrate SLAM navigation with detergent dosing optimization for facility management contracts.
- Surveillance:Perimeter monitoring robots fuse thermal imaging with acoustic anomaly detection for critical infrastructure protection.
Highest automation penetration: Assembly. Steepest expansion trajectory: Delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's Qianhai Free Trade Zone concentrates contract electronics manufacturers deploying force-limited cobots for rapid product line switches. German automotive clusters around Stuttgart and Wolfsburg retrofit legacy plants with predictive maintenance controllers to secure EU Green Deal automation incentives.
United States
FDA premarket submission timelines of 18-24 months for surgical autonomy features compress competitive windows for medical robot developers in Massachusetts and California clusters. FAA beyond-visual-line-of-sight waivers for commercial drone logistics concentrate testing corridors around Nevada and North Dakota. Detroit's brownfield automotive facilities struggle with legacy PLC migration without production halt windows.
Germany
EU AI Act conformity mandates accelerate replacement cycles for legacy non-compliant robot fleets in Wolfsburg and Stuttgart automotive plants. KBA and notified bodies pre-certify controller architectures to front-load compliance costs. Bavaria's industrial corridor anchors demand for six-axis articulated arms with sub-millimeter repeatability.
China
MIIT and SAMR enforce divergent testing protocols for industrial safety versus algorithmic transparency, extending type-approval timelines for multimodal service robots. Shenzhen and Shanghai electronics assemblers deploy force-limited cobots without hard guarding. Pearl River Delta small-batch producers slash reconfiguration downtime between product generations.
Japan
METI coordinates national robotics roadmap through JIS certification benchmarks that manufacturers must clear for domestic procurement eligibility. Nagoya's automotive suppliers integrate transformer-based vision-language models for unstructured bin-picking. Tokyo medical networks deploy medication delivery robots under PMDA scrutiny for autonomous public-space operation.
India
CDSCO's phased manufacturing program incentivizes domestic robot assembly for sterile fill-finish operations in pharmaceutical packaging. Maharashtra and Gujarat contract manufacturers evaluate cobot deployment against Vietnam labor arbitrage. National capital region integrators seek first-mover advantages in compliant system integration.
AI Powered Robot Market Vendor Landscape
German and Japanese producers anchor one tier; American specialists hold another in GPU-accelerated inference and legged locomotion. The vendor base stratifies between consolidated industrial automation incumbents and fragmented humanoid startup entrants. Three archetypes dominate: legacy PLC integrators retrofitting brownfield plants, GPU-stack vendors supplying real-time decision chips, and cobot pure-plays targeting small-batch electronics. Competitive moves center on strategic partnerships for synthetic data generation and geographic expansion into Indian pharmaceutical corridors.
Within the industrial automation tier, ABB and Fanuc represent entrenched positions in six-axis articulated systems, while Boston Dynamics exemplifies the legged locomotion specialist archetype for unstructured terrain. NVIDIA Corporation anchors the GPU-accelerated inference segment supplying real-time decision chips to tier-one automotive suppliers. These three occupy positions spanning legacy hardware dominance, frontier mobility platforms, and semiconductor-enabled intelligence layers.
| Leading Market Players |
|---|
| ABB |
| Boston Dynamics |
| NVIDIA Corporation |
| Fanuc |
| SoftBank Group Corp |
| Hanson Robotics |
| YASKAWA ELECTRIC CORPORATION |
| Figure AI |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
EU AI Act conformity mandates for algorithmic transparency documentation are compelling German automotive buyers to pre-certify controller architectures through notified bodies, forcing Japanese and German sensor suppliers to expand technical documentation capacity and compressing margins on non-compliant legacy component lines.
Pricing Analysis
Short lead-time premiums of 15-25% apply to force-torque sensors and lidar arrays sourced from Japanese component specialists for urgent reconfiguration projects in Shenzhen electronics plants. Three-tier pricing structure across premium certified, standard industrial, and economy retrofit tiers separates EU AI Act-compliant systems from legacy PLC architectures. Pricing pressure stems from Chinese MIIT and SAMR divergent testing protocols extending type-approval timelines for multimodal service robots. Small-batch electronics producers in the Pearl River Delta exhibit highest price sensitivity, while German automotive OEMs absorbing front-loaded compliance costs show lowest sensitivity.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific to European manufacturing corridors adds 8-12% landed cost variance for GPU-accelerated inference modules and edge computing chips. Component manufacturing concentrates in Japan, Germany, and Taiwan for high-precision sensors; China dominates commodity actuator production. Critical dependencies include rare-earth magnets for servo motors, silicon carbide substrates for power electronics, and specialized optical glass for lidar arrays. Single-source vulnerability runs through Japanese force-torque sensor specialists supplying 60% of global cobot bill-of-materials. Distribution runs through tier-one system integrators in Stuttgart, Nagoya, and Detroit who bundle hardware with software service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundation model training capacity for synthetic manipulation datasets represents the binding constraint propping pricing power for AI-powered robot vendors with proprietary data generation pipelines.
For Market Incumbents: Acquire synthetic data generation capabilities to compress customer integration timelines from months to weeks. Defend against transformer-based vision-language model entrants by embedding predictive maintenance controllers deeper into German automotive procurement specifications. Prioritize JIS certification fast-track partnerships with METI to lock in Japanese domestic market access.
For New Entrants and Emerging Players: Enter via Indian pharmaceutical packaging corridors where CDSCO's phased manufacturing program creates first-mover advantages for compliant system integrators. Target sterile fill-finish operations in Maharashtra and Gujarat contract manufacturers evaluating cobot deployment against Vietnam labor arbitrage. Lead with usage-based pricing indexed by operational hours rather than perpetual licensing to bypass capex-heavy procurement committees.
For Investors and Strategic Acquirers: Re-rating potential sits with GPU-stack vendors supplying real-time decision chips given edge inference module integration accelerating across automotive and logistics deployments. Long-term viability over a decade hinges on controlling proprietary synthetic data pipelines rather than hardware manufacturing. Watch for FDA surgical autonomy documentation timelines compressing competitive windows for medical robot developers as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Data Pipeline Acquisition | Compresses sim-to-real integration timelines for German automotive bin-picking deployments. |
| JIS Certification Fast-Track Partnership | Secures METI procurement eligibility for domestic Japanese robotics markets. |
| Edge Inference Module Integration | Enables sub-50-millisecond control loops for safety-critical manufacturing cells. |
| Indian Pharmaceutical Corridor Expansion | Captures CDSCO incentives for sterile fill-finish automation in Maharashtra. |
| Usage-Based Pricing Model Transition | Displaces capex committees with opex approvals from plant engineering managers. |
Methodological Framework
SEC 10-K filings, EU notified body certification databases, and Japanese METI robotics roadmap publications formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with plant engineering managers at German automotive OEMs, procurement leads at Shenzhen electronics assemblers, regulatory affairs specialists navigating FDA and PMDA submissions, and aftermarket service heads at industrial automation distributors provided operating context. Bottom-up unit economics from sensor bill-of-materials and top-down spend analysis from national automation incentive programs were triangulated to validate market estimates.
Historical trendline analysis of industrial robot installed base growth, collaborative robot density trajectories, and GPU-accelerated edge inference adoption curves informed the projection framework across the analysis window. Segmentation dimensions modeled include product type (industrial, collaborative, service, humanoid), technology stack (machine learning, computer vision, sensor fusion), and end-use vertical (automotive, electronics, healthcare, logistics). CAGRs derived from regression analysis against manufacturing automation spending and regulatory compliance cost absorption rates. Industry-specific inputs incorporated EU AI Act implementation timelines and Chinese GB standard certification friction.
Revisions become necessary when EU AI Act enforcement intensity shifts, Chinese MIIT and SAMR harmonize divergent testing protocols, or foundation model architectures achieve zero-shot generalization without synthetic data dependencies. Forecasts reflect documented assumptions about regulatory compliance cost trajectories and sensor supply concentration. Stakeholders should weight assumptions against their own operating context regarding brownfield PLC migration capabilities and workforce retraining bandwidth.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Cloud Robotics Market
Robotics and Automation
Robot End-Effector Market
Robotics and Automation
Japan Articulated Robot Market
Robotics and Automation
Europe Data Center Robotics Market
Robotics and Automation
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market
Robotics and Automation
China Autonomous Mobile Robot Market
Robotics and Automation
Robotic Process Automation in Legal Services Market
Robotics and Automation
Global Enterprise Robotic Process Automation Market
Robotics and Automation
Medical Automation Technologies Market
Robotics and Automation
Europe Service Robotics Market
Robotics and Automation
North America Collaborative Robots Market
Robotics and Automation
South America AUV and ROV Market
Robotics and Automation
Autonomous Polishing Machine Market
Robotics and Automation
Latin America Autonomous Mobile Robot Market
Robotics and Automation
Autonomous Navigation Robots Market
Robotics and Automation
Top Robotics Market