
 Delta Robots Market | 2026-2036
Delta Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Delta Robots Market Analysis
China is rewriting delta robot supply dynamics as domestic automation clusters scale precision manufacturing capacity. ABB Group leverages its Swiss-Chinese engineering footprint to anchor high-speed packaging lines across Asia-Pacific assembly plants. FANUC Corporation sustains dominance in multi-axis controller integration for automotive tier-one suppliers. Yaskawa Electric Corporation differentiates through proprietary servo motor density in compact delta architectures.
Delta robots are parallel kinematic machines with three or four arms connected to a common base plate, achieving positional accuracy below 0.1 millimeter at cycle speeds exceeding 300 picks per minute for lightweight payload sorting and assembly tasks. High-speed delta robots capture the dominant share of electronics end-user demand where sub-50-millisecond cycle times determine line economics. Cleanroom delta robots command premium positioning in pharmaceutical aseptic filling operations governed by ISO 14644-1 particle count standards. Multi-arm configurations represent the fastest-growing product type as medical device manufacturers adopt twin-payload synchronous handling for catheter and syringe assembly.
EU MDR and FDA 21 CFR Part 11 compliance frameworks mandate electronic batch records and machine-level traceability, directly elevating demand for validated cleanroom delta robot installations in pharmaceutical packaging. China's GB/T robot safety standards and SAMR certification requirements shape market access for imported delta systems in domestic food processing lines. Stakeholders must monitor convergence between pneumatic and electric hybrid actuation technologies as energy efficiency regulations tighten across European and North American factory automation procurement specifications.
Market Dynamics
EU MDR traceability mandates are compressing validation timelines for pharmaceutical delta robot installations while electronics contract manufacturers in Southeast Asia prioritize sub-50-millisecond cycle specifications over capital cost minimization.
Growth Catalysts
- EU MDR Electronic Batch Records:Pharmaceutical packaging lines across Germany and Switzerland require validated cleanroom delta robots with machine-level serialization, expanding replacement demand for legacy pneumatic systems.
- Servo Motor Density Improvements:Compact delta architectures now achieve positional accuracy below 0.1 millimeter through proprietary motor integration, enabling catheter and syringe assembly automation.
- Southeast Asian Electronics Clusters:Contract manufacturers in Vietnam and Thailand are standardizing high-speed pick-and-place delta configurations for smartphone component sorting at volumes exceeding 300 picks per minute.
Market Restraints
- Rare Earth Magnet Supply Concentration:High-performance servo motors depend on neodymium supply chains centered in China, creating input cost volatility and procurement risk for European and Japanese system integrators.
- ISO 14644-1 Cleanroom Certification Burden:Pharmaceutical delta robot installations require extended particle count validation protocols that extend commissioning timelines by 4-6 months versus standard industrial deployments.
- Collaborative Robot Substitution:Six-axis cobot platforms with force-limiting safety systems are capturing lightweight assembly tasks below 2 kilograms payload, constraining delta robot expansion in small-batch medical device production.
Strategic Opportunities
- India Pharmaceutical Manufacturing:CDSCO compliance requirements and PLI scheme incentives for domestic medical device production are creating first-mover advantage for validated cleanroom delta robot suppliers establishing local service networks.
- Electric-Pneumatic Hybrid Actuation:Convergence of servo-driven precision with pneumatic cost efficiency addresses energy efficiency regulations tightening across European factory automation procurement specifications.
- Twin-Payload Synchronous Handling:Multi-arm delta configurations enable simultaneous catheter and packaging material manipulation, opening medical device assembly applications previously requiring separate handling stations.
Industry Challenges
- Parallel Kinematics Programming Expertise:Delta robot path optimization requires specialized motion control knowledge scarce among traditional PLC programmers, forcing integrators to retain vendor-certified technicians at premium rates.
- Legacy SCADA Integration Complexity:Pharmaceutical manufacturers operating validated batch management systems face protocol translation barriers when connecting modern delta robot controllers to 1990s-era distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Delta Robots Market |
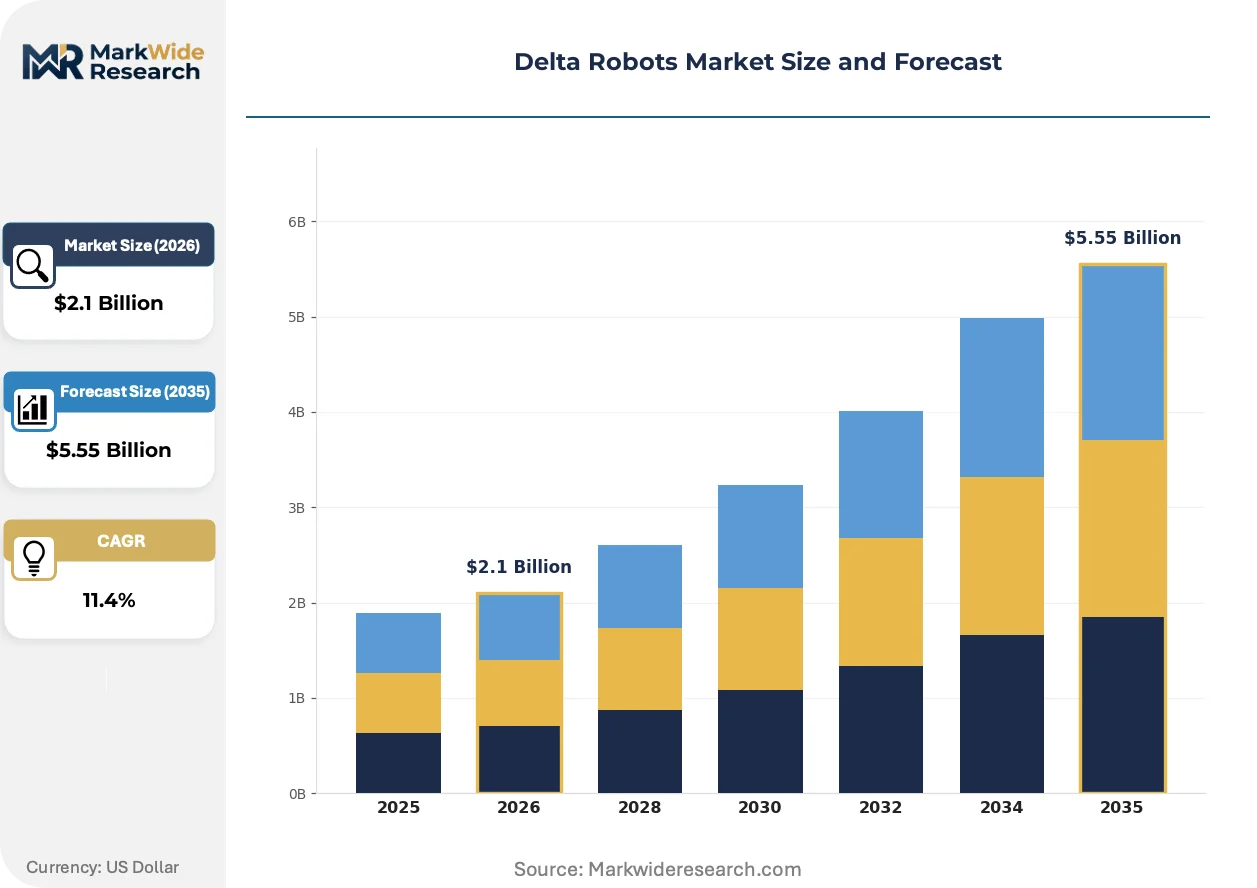
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Delta Robots, High-Speed Delta Robots, Multi-Arm Delta Robots, Cleanroom Delta Robots Application: Packaging, Pick and Place, Assembly, Quality Control End User: Automotive, Electronics, Food & Beverage, Pharmaceuticals Technology: Electric, Pneumatic, Hybrid, Cartesian |
| Companies Covered | ABB Group, Yaskawa Electric Corporation, FANUC Corporation, DENSO Corporation, Staubli International AG, Omron Corporation, KUKA AG, Seiko Epson Corporation, Codian Robotics B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Delta Robots Market Emerging Trajectories
Digital twin technology is virtualizing delta robot commissioning workflows, compressing validation timelines while enabling predictive maintenance models that shift service revenue from reactive repair to uptime guarantees.
Digital twin platforms are virtualizing complete delta robot cell behavior before physical installation, allowing pharmaceutical manufacturers to validate pick-and-place sequences against EU MDR traceability requirements in simulated environments. Medical device producers in Switzerland and Germany are adopting these virtual commissioning tools to reduce cleanroom downtime during line changeovers. The technology is virtualizing traditional hardware-in-the-loop testing, collapsing validation cycles from months to weeks.
FDA 21 CFR Part 11 electronic records requirements are mandating audit trail functionality in delta robot controllers deployed for aseptic pharmaceutical filling operations. System integrators must now embed cryptographic timestamping and user authentication modules directly into motion control firmware. Cleanroom delta robot suppliers serving US pharmaceutical packaging lines are reengineering controller architectures to satisfy these data integrity mandates.
Electronics contract manufacturers are consolidating delta robot procurement through direct OEM relationships, bypassing traditional distributor channels that previously dominated industrial automation equipment sales. Large Southeast Asian assembly plants now negotiate enterprise service agreements spanning multiple facilities rather than site-by-site equipment purchases. This channel compression is most visible in Vietnam and Thailand, where smartphone component manufacturers demand localized spare parts inventory guarantees as a condition of contract awards.
Delta Robots Market Segmentation
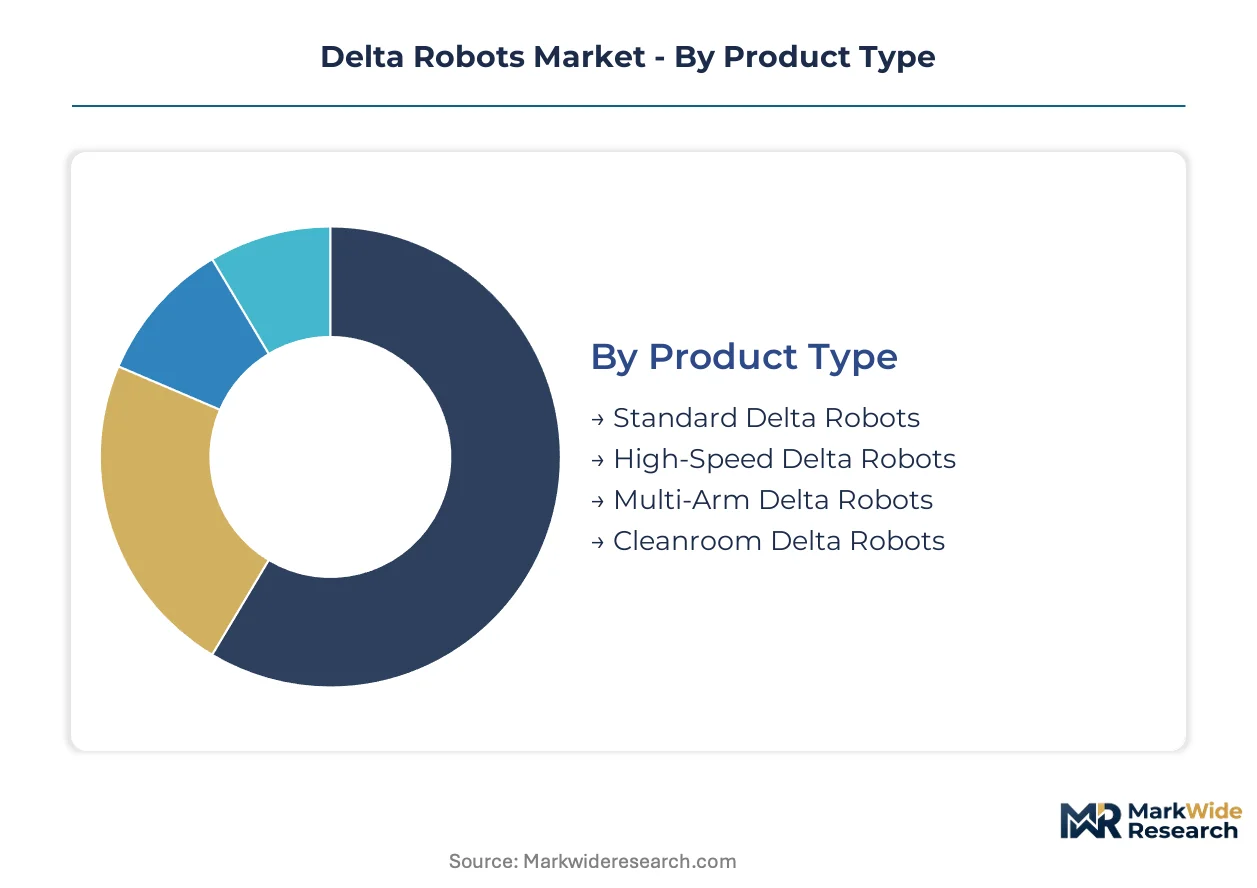
Delta robot segmentation reveals divergent service intensity profiles across product architectures. After-sales requirements vary dramatically between validated pharmaceutical installations and standard industrial deployments.
Product Type:
After-sales service intensity escalates sharply with environmental certification requirements and precision specifications.
- High-Speed Delta Robots:These systems achieve cycle speeds exceeding 300 picks per minute through lightweight carbon-fiber arm constructions and direct-drive servo configurations. Electronics contract manufacturers in Vietnam and Thailand standardize these units for smartphone component sorting, prioritizing sub-50-millisecond cycle specifications over capital cost minimization.
- Cleanroom Delta Robots:Aseptic-rated systems incorporate sealed housing designs and ISO 14644-1 compliant particle control for pharmaceutical filling operations. EU MDR traceability mandates in Germany and Switzerland are compressing validation timelines while extending commissioning service contracts by 4-6 months versus standard industrial deployments.
- Standard Delta Robots:General-purpose three-arm configurations serve food processing lines with moderate precision requirements and standard IP54 environmental protection.
- Multi-Arm Delta Robots:Twin-payload synchronous architectures enable simultaneous catheter and packaging material manipulation in medical device assembly.
High-Speed Delta Robots holds the largest share; momentum sits with Multi-Arm Delta Robots.
Application:
Application segmentation tracks directly to line economics and throughput sensitivity in target industries.
- Pick and Place:High-throughput sorting operations dominate electronics manufacturing where positional accuracy below 0.1 millimeter determines yield rates. Southeast Asian contract manufacturers deploy these systems at volumes exceeding 300 picks per minute for smartphone component handling.
- Packaging:End-of-line carton loading and palletizing applications in food processing require washdown-compatible actuator sealing and rapid format changeover capabilities.
- Assembly:Medical device catheter and syringe production demands validated motion sequences with cryptographic timestamping for FDA 21 CFR Part 11 compliance.
- Quality Control:Vision-integrated delta configurations perform inline inspection at cycle speeds matching production line throughput without buffer stations.
Pick and Place commands the dominant application share; Packaging is climbing the fastest on food safety automation requirements.
End User:
End user segmentation reflects divergent regulatory exposure and precision requirements across manufacturing verticals.
- Electronics:Smartphone and semiconductor component manufacturers drive demand for sub-50-millisecond cycle specifications. Contract manufacturers in Vietnam and Thailand are consolidating procurement through direct OEM relationships with localized spare parts inventory guarantees.
- Pharmaceuticals:Aseptic filling and packaging operations require ISO 14644-1 certified systems with embedded audit trail functionality. EU MDR electronic batch record mandates in Germany and Switzerland are accelerating replacement of legacy pneumatic installations.
- Automotive:Tier-one suppliers integrate multi-axis delta configurations for lightweight component assembly alongside existing FANUC controller ecosystems.
- Food & Beverage:China's GB/T robot safety standards and SAMR certification requirements shape market access for imported systems in domestic processing lines.
Electronics represents the largest end user segment; Pharmaceuticals shows the steepest expansion trajectory on regulatory compliance investments.
Technology:
Technology segmentation tracks the convergence between precision servo control and cost-efficient pneumatic actuation.
- Electric:Servo motor-driven systems achieve positional accuracy below 0.1 millimeter through proprietary motor density integration. Yaskawa Electric Corporation differentiates through compact actuator architectures enabling catheter and syringe assembly automation.
- Hybrid:Electric-pneumatic combinations address energy efficiency regulations tightening across European factory automation procurement specifications. These configurations blend servo precision with pneumatic cost structure for mid-speed packaging applications.
- Pneumatic:Compressed air actuation persists in legacy food processing installations where explosion protection and washdown compatibility outweigh precision requirements.
- Cartesian:Linear gantry alternatives compete for pick-and-place tasks in large-workspace applications where delta kinematics impose reach constraints.
Electric technology dominates current installations; Hybrid configurations are gaining share fastest on energy efficiency compliance pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Delta robot supply chains concentrate heavily in East Asian manufacturing corridors, with Chinese domestic automation clusters now challenging traditional Japanese and European engineering centers. Component sourcing for precision servo systems remains geographically concentrated, creating procurement dependencies that shape regional deployment strategies.
China
Domestic automation clusters in the Yangtze River Delta are scaling precision manufacturing capacity for delta robot subassemblies. SAMR certification requirements and GB/T robot safety standards regulate market access for both indigenous and imported systems. Shenzhen and Suzhou industrial parks host expanding cleanroom delta robot production lines serving pharmaceutical packaging demand.
Germany
Pharmaceutical manufacturers in Baden-Württemberg and Bavaria are accelerating cleanroom delta robot deployments under EU MDR electronic batch record mandates. EMA compliance frameworks and ISO 14644-1 particle count standards govern aseptic filling automation investments. Stuttgart-area automotive tier-one suppliers integrate multi-axis delta configurations alongside existing controller ecosystems.
Japan
Precision servo motor density improvements originate from Nagoya and Tokyo industrial corridors, enabling sub-0.1 millimeter positional accuracy in compact delta architectures. METI industrial automation incentives support medical device assembly applications. Osaka-area electronics contract manufacturers standardize high-speed pick-and-place configurations for semiconductor component handling.
United States
FDA 21 CFR Part 11 electronic records requirements are mandating audit trail functionality in delta robot controllers for aseptic pharmaceutical operations. EPA energy efficiency regulations shape procurement specifications for hybrid electric-pneumatic actuation systems. Boston and Research Triangle pharmaceutical clusters drive validated cleanroom installation demand.
Switzerland
Medical device producers in the Lake Geneva region adopt digital twin virtual commissioning tools to compress EU MDR validation timelines. Swissmedic regulatory frameworks govern aseptic manufacturing automation investments. Basel-area pharmaceutical packaging facilities are replacing legacy pneumatic systems with validated electric delta robot installations.
Delta Robots Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in servo motor and motion controller supply. The vendor base organizes around three strategic archetypes: diversified industrial automation conglomerates with controller ecosystem lock-in, precision component specialists with proprietary motor density advantages, and regional system integrators with localized service networks. Competitive moves center on geographic service expansion and controller architecture licensing to capture pharmaceutical validation requirements.
Among diversified automation conglomerates, ABB Group and FANUC Corporation exemplify platform integrators with established controller ecosystems. Yaskawa Electric Corporation occupies a position within the precision component specialist tier, representing proprietary servo motor density integration. These three anchors illustrate the competitive structure: diversified platforms compete on system integration breadth while component specialists differentiate through compact actuator architectures.
| Leading Market Players |
|---|
| ABB Group |
| Yaskawa Electric Corporation |
| FANUC Corporation |
| DENSO Corporation |
| Staubli International AG |
| Omron Corporation |
| KUKA AG |
| Seiko Epson Corporation |
| Codian Robotics B.V. |
| Others |
Supply Flow & Price Mechanics
Rare earth magnet supply concentration in China determines both the pricing tier spreads across electric, hybrid, and pneumatic delta robot configurations and the geographic shape of component sourcing networks. Neodymium procurement volatility compresses margins on high-precision servo-driven systems while creating arbitrage opportunities for hybrid actuation technologies that reduce magnet intensity.
Pricing Analysis
EU MDR electronic batch record mandates dictate the pricing tier structure across validated cleanroom installations, standard industrial deployments, and economy-grade food processing units. Three-tier pricing structure across premium certification, standard performance, and economy pneumatic levels separates pharmaceutical-grade systems with embedded audit trail functionality from general-purpose configurations. Pricing pressure stems from collaborative robot substitution in sub-2-kilogram payload applications, forcing delta robot suppliers to bundle extended service contracts. Electronics contract manufacturers in Southeast Asia demonstrate lowest price sensitivity, prioritizing sub-50-millisecond cycle specifications over capital cost minimization.
Supply Chain Analysis
Neodymium magnet feedstock draws from Chinese rare earth processing facilities, Japanese precision servo motor foundries, and German motion controller assembly operations. Carbon-fiber arm constructions hinge on Taiwan and South Korea composite manufacturing, while sealed cleanroom housings source from Swiss and German precision machining clusters. Single-source vulnerability concentrates in Chinese rare earth oxide refining, exposing European and Japanese system integrators to input cost volatility. Distribution runs through direct OEM relationships with large Southeast Asian contract manufacturers, bypassing traditional industrial automation distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Delta robot adoption sits in early-cycle expansion as EU MDR and FDA 21 CFR Part 11 compliance mandates force pharmaceutical manufacturers to replace legacy pneumatic systems with validated electric installations. Regulatory tailwinds in medical device automation create penetration headroom before market maturation.
For Market Incumbents: Harden controller ecosystem lock-in by embedding cryptographic timestamping and audit trail modules directly into motion control firmware, addressing FDA 21 CFR Part 11 mandates before competitors achieve certification parity. Deepen backward integration into compact servo motor production to offset neodymium cost volatility and protect margin structure against hybrid actuation challengers. For New Entrants and Emerging Players: India's pharmaceutical manufacturing corridors represent underpenetrated white space where CDSCO compliance requirements and PLI scheme incentives create first-mover advantage for validated cleanroom delta robot suppliers establishing local service networks. Target medical device assembly applications with twin-payload synchronous handling configurations that incumbent platforms have not optimized. Pursue direct OEM relationships with large contract manufacturers, offering localized spare parts inventory guarantees as entry wedge. For Investors and Strategic Acquirers: Regional system integrators with localized pharmaceutical validation expertise and established technician certification programs present the most defensible acquisition archetype in a market where parallel kinematics programming knowledge remains scarce. Long-term viability favors vendors controlling both motion controller architectures and service network density. Watch for inflection when digital twin virtual commissioning compresses validation timelines from months to weeks, shifting competitive advantage from hardware specification to software-enabled uptime guarantees.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Certification Investment | EU MDR electronic batch record mandates in Germany and Switzerland accelerate replacement demand for legacy pneumatic systems. |
| Servo Motor Density R&D | Proprietary compact actuator integration enables sub-0.1 millimeter positional accuracy in medical device catheter assembly. |
| Digital Twin Platform Development | Virtual commissioning tools collapse pharmaceutical validation cycles while enabling predictive maintenance revenue models. |
| Direct OEM Relationship Expansion | Channel compression in Vietnam and Thailand bypasses distributors through enterprise service agreements spanning multiple facilities. |
| Hybrid Actuation Technology Convergence | Electric-pneumatic combinations address tightening energy efficiency regulations across European factory automation procurement. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical packaging engineers, electronics contract manufacturing procurement leads, automotive tier-one supplier automation directors, and industrial system integrators. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA compliance frameworks, SAMR certification databases, METI industrial automation incentive disclosures, and customs trade data on servo motor and rare earth magnet flows. Bottom-up unit deployment estimates across product type, application, end user, and technology segments were triangulated against top-down market size assessments derived from equipment manufacturer revenue disclosures.
Calibration against historical deployment trajectories in comparable industrial automation equipment categories anchored growth rate assumptions across the projection horizon. Segmentation modeling incorporated product architecture, environmental certification tier, actuation technology, precision specification, and regional regulatory cluster dimensions. CAGRs were derived from slope analysis of adoption curve penetration rates, adjusted for compliance mandate acceleration effects and substitution risk from collaborative robot platforms. Industry-specific forecast inputs included EU MDR implementation timelines, Southeast Asian electronics contract manufacturing capacity expansion plans, and pharmaceutical cleanroom automation investment cycles.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic automation clusters or accelerated collaborative robot substitution in sub-2-kilogram applications would shift outcomes beyond modeled ranges. Cross-checking against pharmaceutical capital expenditure survey data and electronics manufacturing equipment procurement indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Surgical Robots Market
Robotics and Automation
Japan Articulated Robot Market
Robotics and Automation
North America Underwater Robotics Market
Robotics and Automation
Logistics Robots Market
Robotics and Automation
Clean Room Robot Market
Robotics and Automation
Europe Agricultural Robot Market
Robotics and Automation
Robotic Air Purifier Market
Robotics and Automation
Hospital Logistics Robots Market
Robotics and Automation
Hospital Robots Market
Robotics and Automation
Global Robot Kitchen Market
Robotics and Automation
Top Robotics Market
Robotics and Automation
Mobile Robotics Software Market
Robotics and Automation
AGV Software Market
Robotics and Automation
Global Robotic Process Automation in Healthcare Market
Robotics and Automation
Asia-Pacific Service Robotics Market
Robotics and Automation
Europe Robotics and Automation Actuators Market