
 Robotics in Shipbuilding Market | 2026-2036
Robotics in Shipbuilding Market Size, Share, and Industry Trends Forecast 2026-2036
Robotics in Shipbuilding Market Intelligence
REACH compliance is hardening the cost-of-entry calculus for European shipyards adopting robotic painting and welding systems. ABB leverages its marine automation heritage to anchor premium positioning in Scandinavian naval fabrication. Hyundai Robotics dominates Korean mega-yard deployments through captive supply of heavy-payload articulated arms. FANUC sustains R&D intensity across arc-welding controller architectures for thick-plate hull construction.
Robotics in shipbuilding encompasses programmable multi-axis manipulators, typically payload-rated above 500 kg with IP67 environmental sealing, deployed for arc welding, abrasive blasting, and large-structure assembly in outdoor or semi-enclosed yard conditions. These systems execute repetitive or hazardous operations on curved steel surfaces where manual precision degrades across 12-hour shifts. Automated welding systems lead technology adoption due to penetration depth requirements in double-hull tanker construction, while surface inspection robots represent the fastest-growing category as classification societies mandate digital weld documentation. Hull construction commands the largest application share, though maintenance and repair is expanding as aging fleets require dry-dock automation retrofits.
EU F-Gas Regulation and REACH constrain coating robot chemistry and volatile compound recovery, while Korea's KOSHA industrial safety standards mandate collaborative robot fencing protocols in automated workshops. Classification societies including DNV and Lloyd's Register now require traceable digital weld records, directly stimulating inspection robot procurement. Stakeholders must weigh capital intensity against yard automation maturity curves when sequencing deployment across painting, welding, and outfitting workcells.
Market Dynamics
Classification societies now mandate traceable digital weld documentation, forcing shipyards to automate inspection workflows or lose certification eligibility. This regulatory compression is accelerating robot deployment faster than labor cost savings alone would justify.
Growth Catalysts
- EU F-Gas Regulation:Tightened emissions standards for marine coatings are compelling European yards to replace manual spraying with closed-loop robotic systems that capture volatile compounds.
- Double-hull tanker construction:Penetration depth requirements in thick-plate welding exceed human precision limits across extended shifts, driving articulated arm adoption in Korean mega-yards.
- KOSHA industrial safety standards:Korea's mandatory collaborative robot fencing protocols in automated workshops are standardizing human-robot workcell configurations across Asian shipbuilding clusters.
Market Restraints
- Heavy-payload servo motor supply:Concentration of high-torque actuator manufacturing in East Asian supplier bases creates vulnerability for European and North American integrators.
- REACH compliance costs:Chemical registration requirements for coating robot feedstock harden the cost-of-entry calculus for mid-tier European yards considering automation retrofits.
- Manual welding substitution ceiling:Complex outfitting operations in confined machinery spaces resist full automation due to access constraints and part variability.
Strategic Opportunities
- Dry-dock maintenance automation:Aging tanker fleets in Singapore and Rotterdam harbor zones create retrofit demand for hull-cleaning and inspection robotics.
- AI-powered weld quality prediction:Machine vision convergence with thermal sensing enables real-time defect prevention, reducing rework rates in thick-plate construction.
- India's shipbuilding subsidies:PLI scheme incentives for domestic manufacturing are attracting system integrators to establish regional service hubs near Cochin and Visakhapatnam yards.
Industry Challenges
- Robot programmer scarcity:Specialized skills in arc-welding path planning for curved steel surfaces command wage premiums that erode automation ROI calculations.
- Classification society certification timelines:DNV and Lloyd's Register approval processes for novel inspection robot configurations extend deployment schedules by 8-14 months.
- Legacy shipyard infrastructure:Overhead crane clearances and power distribution in 1970s-era facilities require costly reconfiguration to accommodate modern workcell footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotics in Shipbuilding Market |
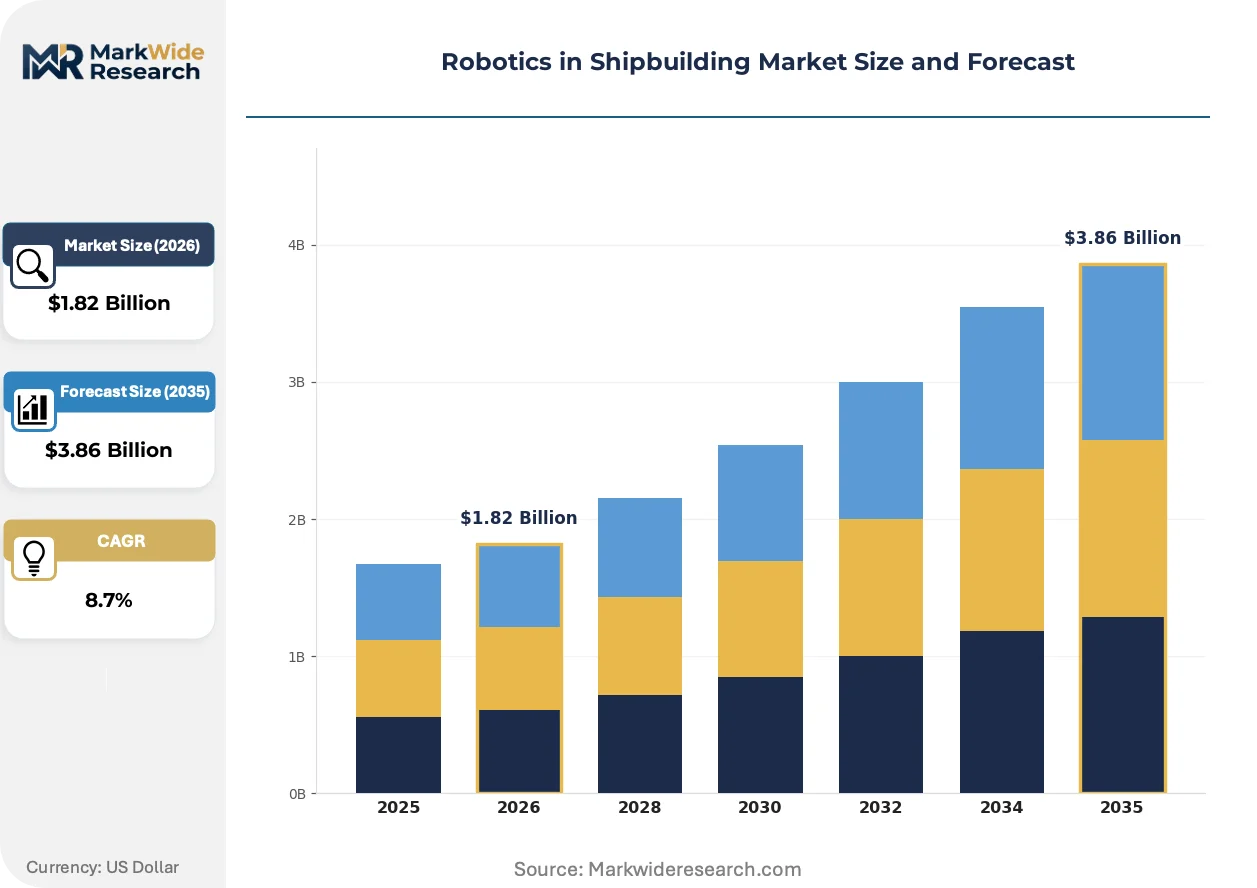
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.86 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Automated Welding, Surface Inspection Robots, Material Handling Robots, Painting Robots, Assembly Robots Application: Hull Construction, Propulsion System Assembly, Outfitting, Maintenance & Repair, Quality Control End User: Shipyards, Naval Contractors, Offshore Fabrication Units, Repair Yards, Marine Engineering Firms Deployment: Onboard Integration, Dockside Installation, Automated Workshops, Remote Operation Systems, Collaborative Workcells |
| Companies Covered | Yaskawa, Comau, ABB, Universal Robots, Hyundai Robotics, FANUC, Kawasaki Robotics, Staubli, KUKA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotics in Shipbuilding Market Strategic Shifts & Innovations
Digital documentation mandates are rewiring competitive advantage toward data-capture capabilities rather than mechanical precision alone. Shipyards now differentiate through weld traceability systems that satisfy classification society auditors.
Machine vision systems with sub-millimeter resolution are integrating thermal profiling and laser seam tracking to compensate for heat distortion in thick-plate arc welding. Korean mega-yards deploy these systems across double-hull tanker sections where manual rework costs exceed robot capital depreciation within eighteen months. The technology is integrating quality assurance directly into the production flow, compressing inspection bottlenecks that previously stalled hull block assembly sequences.
REACH and EU F-Gas Regulation are tightening volatile compound recovery requirements for marine coating operations. Robotic spraying systems with closed-loop solvent capture now qualify for accelerated permitting in German and Dutch port zones. Scandinavian naval fabricators are responding by specifying coating robots with integrated emission monitoring to preempt regulatory delays in defense procurement cycles.
Buyer procurement is consolidating around lifecycle service agreements that bundle robot hardware with predictive maintenance software and spare part availability guarantees. Korean shipbuilders now favor integrators offering 10-year total cost commitments over capital purchase models. This preference shift is most visible in Ulsan and Geoje clusters where yard operators prioritize operational expenditure predictability over upfront equipment ownership.
Robotics in Shipbuilding Market Segmentation
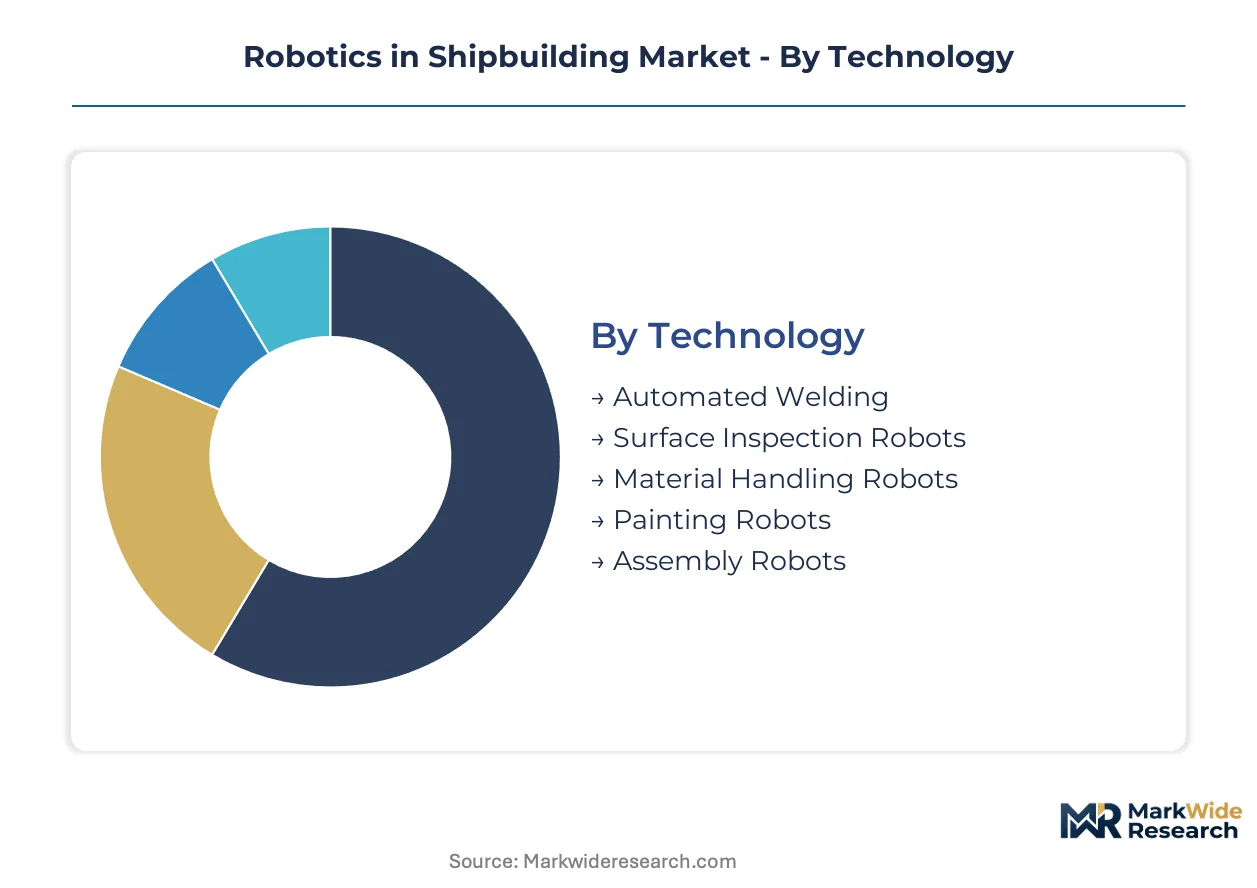
Shipbuilding robotics procurement hinges on workcell durability under salt-air exposure and payload capacity for steel plate manipulation. Segmentation reveals how yard operators sequence automation investments across hazardous operations versus precision assembly tasks.
Technology:
Capital allocation prioritizes systems with immediate regulatory compliance benefits and measurable rework reduction.
- Automated Welding:Articulated arms with arc-welding controllers execute thick-plate penetration for double-hull tanker sections. Korean mega-yards in Ulsan and Geoje deploy these systems where manual precision degrades across extended shifts.
- Surface Inspection Robots:Machine vision platforms with sub-millimeter resolution capture digital weld documentation for DNV and Lloyd's Register certification. Singapore and Rotterdam harbor zones drive retrofit demand as aging fleets require dry-dock automation.
- Material Handling Robots:Heavy-payload manipulators rated above 500 kg transport hull blocks across outdoor yard conditions.
- Painting Robots:Closed-loop spraying systems with volatile compound recovery satisfy EU F-Gas Regulation and REACH compliance for marine coatings.
- Assembly Robots:Multi-axis systems integrate curved steel sections where manual alignment tolerances exceed classification society standards.
Volume sits with Automated Welding; growth tilts toward Surface Inspection Robots.
Application:
Work sequencing follows hull block assembly flows from raw steel through outfitting completion.
- Hull Construction:Double-hull tanker construction commands the largest technology deployment, with penetration depth requirements exceeding human welding precision across 12-hour shifts. Hyundai Heavy Industries and Samsung Heavy Industries anchor demand in South Korean mega-yards.
- Maintenance & Repair:Dry-dock automation retrofits for aging tanker fleets create fastest-expanding demand in Singapore and Rotterdam harbor zones. Hull-cleaning and inspection robotics address classification society mandates for traceable digital weld records.
- Propulsion System Assembly:Precision integration of engine mounts and shaft alignment systems in enclosed machinery spaces.
- Outfitting:Complex operations in confined spaces resist full automation due to access constraints and part variability.
- Quality Control:Automated documentation workflows satisfy DNV and Lloyd's Register certification timelines.
Hull Construction captures current spend; Maintenance & Repair shows the steepest expansion trajectory.
End User:
Procurement authority concentrates with operators managing defense procurement cycles and commercial newbuild programs.
- Shipyards:Korean operators in Ulsan and Geoje clusters favor 10-year lifecycle service agreements bundling hardware with predictive maintenance software. These buyers prioritize operational expenditure predictability over upfront equipment ownership.
- Naval Contractors:Scandinavian fabricators specify coating robots with integrated emission monitoring to preempt EU F-Gas Regulation delays in defense procurement cycles.
- Offshore Fabrication Units:Heavy-structure builders deploy similar robotic systems for platform construction.
- Repair Yards:Singapore and Rotterdam operators retrofit automation for aging fleet maintenance.
- Marine Engineering Firms:Specialized integrators provide path planning expertise for curved steel surfaces.
Shipyards dominate installed base; Naval Contractors are gaining share fastest on defense automation mandates.
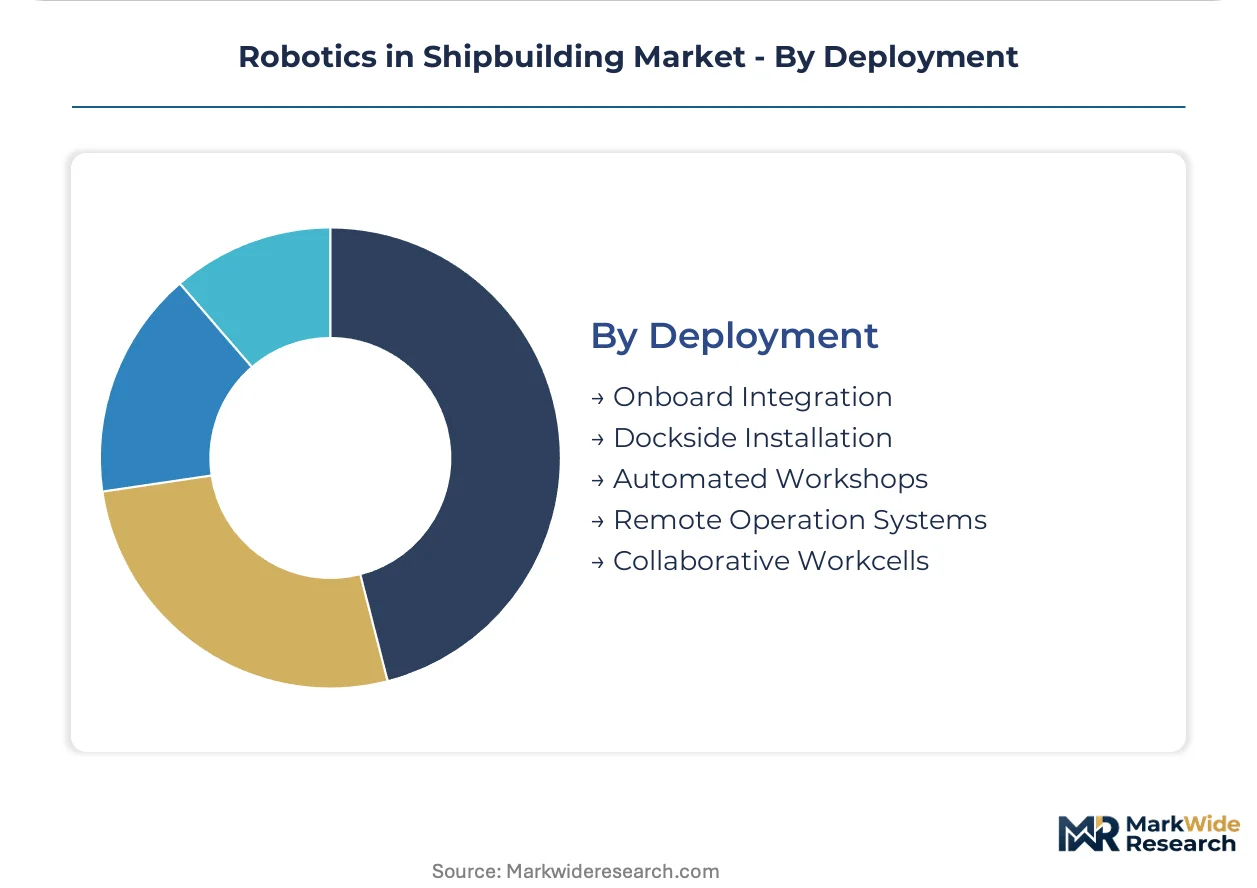
Deployment:
Physical configuration decisions trade off environmental protection against operational flexibility.
- Automated Workshops:KOSHA industrial safety standards in South Korea mandate collaborative robot fencing protocols, standardizing human-robot workcell configurations across Asian shipbuilding clusters. These enclosed environments protect precision equipment from salt-air corrosion.
- Collaborative Workcells:Human-robot proximity configurations address programmer scarcity by reducing specialized path planning requirements. Korean yards deploy these where skilled labor premiums erode traditional automation ROI.
- Onboard Integration:Ship-mounted systems for at-sea maintenance operations.
- Dockside Installation:Portable units for hull cleaning and inspection in dry-dock configurations.
- Remote Operation Systems:Tethered platforms for hazardous blasting operations in confined tank spaces.
Automated Workshops hold volume concentration; Collaborative Workcells climb the fastest on labor cost arbitrage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in South Korea, Singapore, and the Netherlands concentrate shipbuilding robotics procurement through bonded warehousing advantages and accelerated customs clearance for heavy-payload equipment imports.
South Korea
Ulsan and Geoje clusters drive demand for double-hull tanker welding automation where Hyundai Heavy Industries and Samsung Heavy Industries operate. KOSHA industrial safety standards mandate collaborative robot fencing protocols in automated workshops. Korean yards favor 10-year lifecycle service agreements bundling predictive maintenance with hardware procurement.
China
Yangtze River Delta shipbuilders deploy heavy-payload manipulators for hull block assembly amid dual carbon goals tightening emissions standards. MIIT guidelines promote domestic robot controller development for thick-plate arc welding. Shanghai and Jiangsu province yards integrate closed-loop coating systems to satisfy volatile compound recovery mandates.
Germany
Scandinavian naval fabricators source coating robots through German integrators to satisfy EU F-Gas Regulation emission monitoring requirements. REACH compliance hardens cost-of-entry for mid-tier yards considering automation retrofits. Hamburg and Bremen harbor zones service aging tanker fleets requiring dry-dock inspection robotics.
Japan
Kawasaki and Nagoya industrial corridors sustain demand for precision assembly robots in naval and commercial shipbuilding. METI industrial policy supports human-robot collaborative workcells addressing programmer scarcity. Japanese classification society coordination with DNV accelerates digital weld documentation standardization.
Singapore
Jurong and Tuas shipyard zones anchor Southeast Asian demand for hull-cleaning and inspection robotics serving aging tanker fleets. The Maritime and Port Authority coordinates with classification societies on traceable weld record mandates. Regional repair yards retrofit automation to capture dry-dock maintenance contracts from Rotterdam and Middle East operators.
Robotics in Shipbuilding Market Key Industry Players
East Asian producers anchor one tier; European specialists hold premium positioning in naval fabrication and emission-compliant coating systems. The vendor base concentrates around heavy-payload articulated arm manufacturers and marine-focused system integrators. Two strategic archetypes dominate: captive shipyard-affiliated robot suppliers and independent automation houses with classification society certification expertise. Competitive moves center on 10-year lifecycle service agreements and predictive maintenance software bundling.
Within the captive-supply tier, Hyundai Robotics exemplifies yard-affiliated deployment concentration. Among independent automation specialists, ABB and FANUC occupy positions spanning arc-welding controller architectures and marine workcell integration. KUKA represents European-based fabrication expertise serving naval contractors with REACH-compliant system configurations. These anchors illustrate how geographic origin and corporate structure shape competitive positioning across Korean mega-yards, Scandinavian naval clusters, and German port-zone service networks.
| Leading Market Players |
|---|
| Yaskawa |
| Comau |
| ABB |
| Universal Robots |
| Hyundai Robotics |
| FANUC |
| Kawasaki Robotics |
| Staubli |
| KUKA |
| Others |
Cost & Logistics Intelligence
Steel plate price indices from South Korean commodity exchanges cascade through heavy-payload articulated arm production into three distinct procurement tiers for shipyard buyers. EU F-Gas Regulation compliance costs for closed-loop coating systems widen the spread between premium REACH-certified configurations and standard industrial robotics.
Pricing Analysis
Lead-time premiums compress standard configurations while spot inventory of heavy-payload servo motors commands discounts from East Asian suppliers. Korean mega-yards negotiate 10-year lifecycle service agreements bundling predictive maintenance with hardware, shifting pricing models from capital purchase toward operational expenditure contracts. Price differentiation hinges on classification society certification tier and after-sales spare part availability guarantees. Cost compression in mid-tier European yards intensifies as REACH registration expenses for coating robot feedstock erode margins. Naval contractors show least price sensitivity, prioritizing emission monitoring integration to preempt defense procurement delays.
Supply Chain Analysis
Regional distribution centers in Ulsan, Shanghai, and Rotterdam anchor hub-and-spoke patterns for heavy-payload equipment serving shipbuilding clusters. Manufacturing concentration in South Korea, Japan, and Germany feeds from rare earth magnet supplies and high-torque actuator components. Supply chain risk centers on single-source vulnerability for precision servo motors from East Asian supplier bases. Distribution runs through bonded warehousing in free trade zones with accelerated customs clearance for IP67-sealed articulated arms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is mounting as classification society certification timelines extend deployment schedules, forcing capital-constrained integrators toward acquisition or exit.
For Market Incumbents: Lock in yard-affiliated supply relationships through captive maintenance service contracts spanning the analysis window. Deepen backward integration into arc-welding controller architectures to defend against emerging AI-powered weld quality prediction specialists. Prioritize predictive maintenance software bundling to capture lifecycle revenue streams as Korean buyers shift from ownership to service models. For New Entrants and Emerging Players: System integrators with classification society certification expertise represent the most penetrable channel partner type for dry-dock maintenance automation retrofits in Singapore and Rotterdam harbor zones. Target aging tanker fleet operators with portable hull-cleaning robotics configured for dockside installation. Pursue India's PLI scheme subsidies through regional service hub establishment near Cochin and Visakhapatnam yards. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European automation houses with REACH-compliant system configurations in German and Dutch port zones. Long-term viability over the projection horizon rests on digital weld documentation capabilities satisfying DNV and Lloyd's Register mandates. Monitor KOSHA collaborative robot fencing protocol adoption rates across Asian shipbuilding clusters as inflection indicator for human-robot workcell standardization demand.| Strategic Initiative | Industry Significance |
|---|---|
| Classification Society Certification Investment | DNV and Lloyd's Register approval accelerates procurement eligibility for inspection robot configurations. |
| Predictive Maintenance Software Bundling | Korean mega-yards in Ulsan and Geoje prioritize operational expenditure predictability over capital ownership. |
| Backward Integration into Servo Motor Production | East Asian supplier concentration creates vulnerability for European integrators dependent on imported actuators. |
| Regional Service Hub Establishment | India's PLI scheme incentives attract system integrators to Cochin and Visakhapatnam shipyard zones. |
| Closed-Loop Coating System Development | EU F-Gas Regulation compliance qualifies robotics for accelerated permitting in German and Dutch ports. |
Research Approach
Classification society technical bulletins, customs trade databases for heavy-payload equipment, and Korean shipyard procurement disclosures formed the secondary backbone for market sizing. Primary interviews with shipyard automation directors, marine coating system integrators, arc-welding path planning specialists, and predictive maintenance software vendors validated installation base estimates. Bottom-up triangulation across technology segments and top-down cross-check against regional production capacity anchored volume projections.
Bottom-up modeling segmented the market by automated welding, surface inspection, material handling, painting, and assembly robot categories across hull construction, maintenance and repair, and propulsion system assembly applications. Deployment configurations spanned automated workshops, collaborative workcells, and dockside installations. CAGR derivation incorporated Korean KOSHA safety standard adoption curves, EU F-Gas Regulation implementation timelines, and classification society digital documentation mandate penetration.
Caveats apply where heavy-payload servo motor supply disruptions or REACH compliance cost escalations could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Motion Control Software in Robotics Market
Robotics and Automation
Global Robot Kitchen Market
Robotics and Automation
Europe Warehouse Robotics Market
Robotics and Automation
Warehouse Robotics Market
Robotics and Automation
Healthcare Robots Market
Robotics and Automation
Bot Services Market
Robotics and Automation
APAC Service Robots Market
Robotics and Automation
Industrial Robots Market
Robotics and Automation
Asia-Pacific AUV Market
Robotics and Automation
Smart Worker Market
Robotics and Automation
Healthcare Mobile Robots Market
Robotics and Automation
Smart Machines Market
Robotics and Automation
Mobile Robotics Software Market
Robotics and Automation
Robot Charging Station Market
Robotics and Automation
AGV Intelligent Management Systems Market
Robotics and Automation
Autonomous Polishing Machine Market