
 Autonomous Mobile Manipulator Robots (AMMR) Market | 2026-2036
Autonomous Mobile Manipulator Robots (AMMR) Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Mobile Manipulator Robots (AMMR) Market Outlook
ISO 10218 safety certification is rotating as the primary gatekeeper for AMMR market participation, forcing vendors to redesign control architectures before commercial deployment. FANUC Corporation leverages its captive servo motor production to sustain margin control across integrated arm-and-mobile systems. KUKA AG anchors European manufacturing demand through deep relationships with German automotive producers. Boston Dynamics differentiates via legged mobility platforms that navigate unstructured environments conventional wheeled bases cannot access.
Autonomous Mobile Manipulator Robots combine articulated robotic arms mounted on self-navigating mobile bases, typically incorporating six-to-seven-axis manipulators with 10-20 kg payload capacity and SLAM-based localization operating within 2-5 mm repeatability. Their primary purpose is to execute pick-place, assembly, and material handling tasks across dynamic factory and warehouse floors without fixed infrastructure or human teleoperation. The mobile platforms segment captures the steepest growth trajectory as facilities prioritize fleet flexibility over stationary automation, while robotic arms retain the largest installed value pool due to precision actuator costs. Artificial Intelligence and computer vision technologies now determine competitive positioning, with edge inference latency below 50 milliseconds becoming the threshold for real-time grasp adaptation in mixed-SKU environments.
FDA device regulations govern AMMR deployments in U.S. surgical and patient-care settings, while OSHA workplace safety standards mandate collaborative speed and force limits for human-robot interaction zones. The EU AI Act introduces risk-classification requirements for autonomous decision-making systems, directly affecting AMMR navigation and task-planning software architectures. Stakeholders must monitor how divergent transatlantic compliance frameworks reshape R&D allocation between North American and European product variants.
Market Dynamics
ISO 10218 safety certification is rotating as the primary gatekeeper for AMMR market participation, forcing vendors to redesign control architectures before commercial deployment. This regulatory pivot is compressing R&D timelines while elevating compliance costs across the supplier base.
Growth Catalysts
- EU AI Act risk classification:The EU AI Act mandates conformity assessments for autonomous decision-making systems, creating certified-product preference among European automotive OEMs and tier suppliers.
- Warehousing automation intensity:E-commerce fulfillment centers are deploying fleet-scale AMMR systems to replace fixed conveyor infrastructure and enable dynamic slotting optimization.
- SLAM-based localization maturation:Simultaneous localization and mapping algorithms now achieve 2-5 mm repeatability without facility retrofits, eliminating infrastructure barriers for brownfield deployment.
Market Restraints
- Precision actuator supply concentration:High-torque servo motors and harmonic drives concentrate among Japanese and German suppliers, exposing lead times to geopolitical friction.
- EU AI Act compliance timeline:The EU AI Act's phased implementation creates certification bottlenecks, delaying product launches for systems classified as high-risk autonomous applications.
- Collaborative force limitation constraints:ISO/TS 15066 speed and force thresholds restrict payload-to-weight ratios, capping throughput in human-robot collaborative zones.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO-regulated facilities are piloting AMMR systems for sterile material handling, creating first-mover advantage for vendors achieving cleanroom certification.
- Edge inference latency convergence:Sub-50 millisecond grasp adaptation via GPU-accelerated edge computing is enabling mixed-SKU bin picking without pre-programmed SKUs.
- German automotive reshoring incentives:Federal production subsidies for domestic battery and component manufacturing are expanding addressable factory floor space for AMMR deployment.
Industry Challenges
- Multi-axis calibration expertise scarcity:Six-to-seven-axis manipulator integration with mobile platforms requires rare combinations of kinematic modeling and real-time control engineering.
- Legacy MES integration complexity:Brownfield facilities running proprietary manufacturing execution systems demand costly middleware development for fleet orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Mobile Manipulator Robots (AMMR) Market |
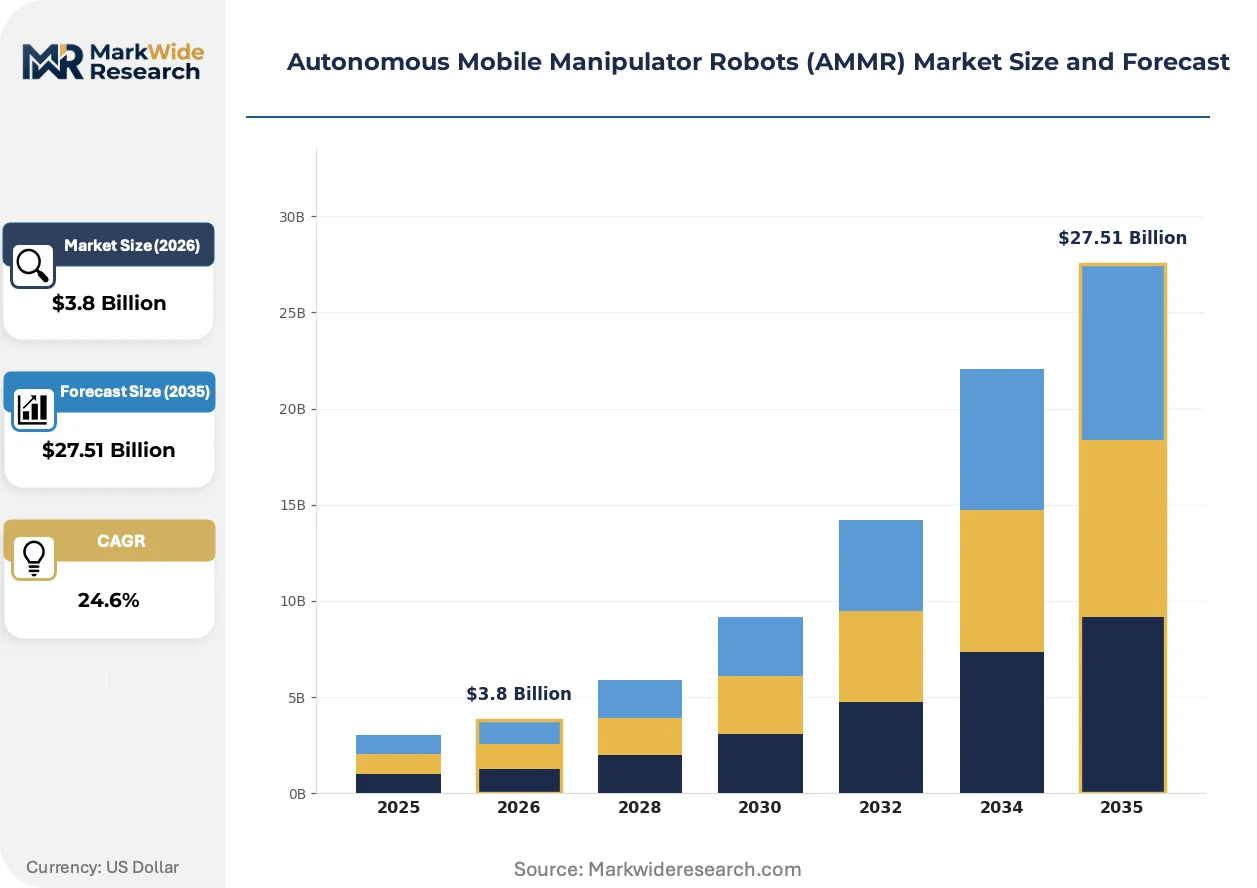
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Arms, Mobile Platforms, Grippers, Sensors End User: Manufacturing, Healthcare, Logistics, Hospitality Technology: Artificial Intelligence, Computer Vision, Machine Learning, IoT Application: Assembly, Packing, Delivery, Inspection |
| Companies Covered | ABB, FANUC Corporation, KUKA AG, Omron Corporation, Boston Dynamics, Yaskawa Electric Corporation, Clearpath Robotics, Robotnik, Stäubli International AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Mobile Manipulator Robots (AMMR) Market Strategic Shifts
Artificial intelligence and computer vision technologies now determine competitive positioning in AMMR systems, with inference architecture choices separating deployable products from laboratory demonstrations. Three forces are actively restructuring how value accumulates across the value chain.
Edge-based neural inference is fragmenting the traditional cloud-dependent AI pipeline for robotic grasping. Automotive tier suppliers in Germany are deploying GPU-accelerated onboard processors to achieve sub-50 millisecond latency for mixed-SKU bin picking. This distributed architecture is fragmenting vendor competitive sets between semiconductor suppliers, pure-play software firms, and integrated system builders.
The EU AI Act introduces mandatory conformity assessments for autonomous navigation and task-planning algorithms classified as high-risk AI systems. Industrial consequence includes mandatory human oversight interfaces and traceability requirements for training data. German automotive OEMs are responding by pre-certifying platforms against anticipated ISO/IEC 42001 AI management standards.
Buyers are unbundling after-sales service contracts from initial hardware procurement, preferring performance-based maintenance agreements tied to uptime guarantees. System integrators and third-party service providers are displacing manufacturer-captive service organizations in European warehousing deployments. This shift is most visible in German logistics hubs where fleet scale justifies dedicated on-site technical staff.
Autonomous Mobile Manipulator Robots (AMMR) Market Segmentation
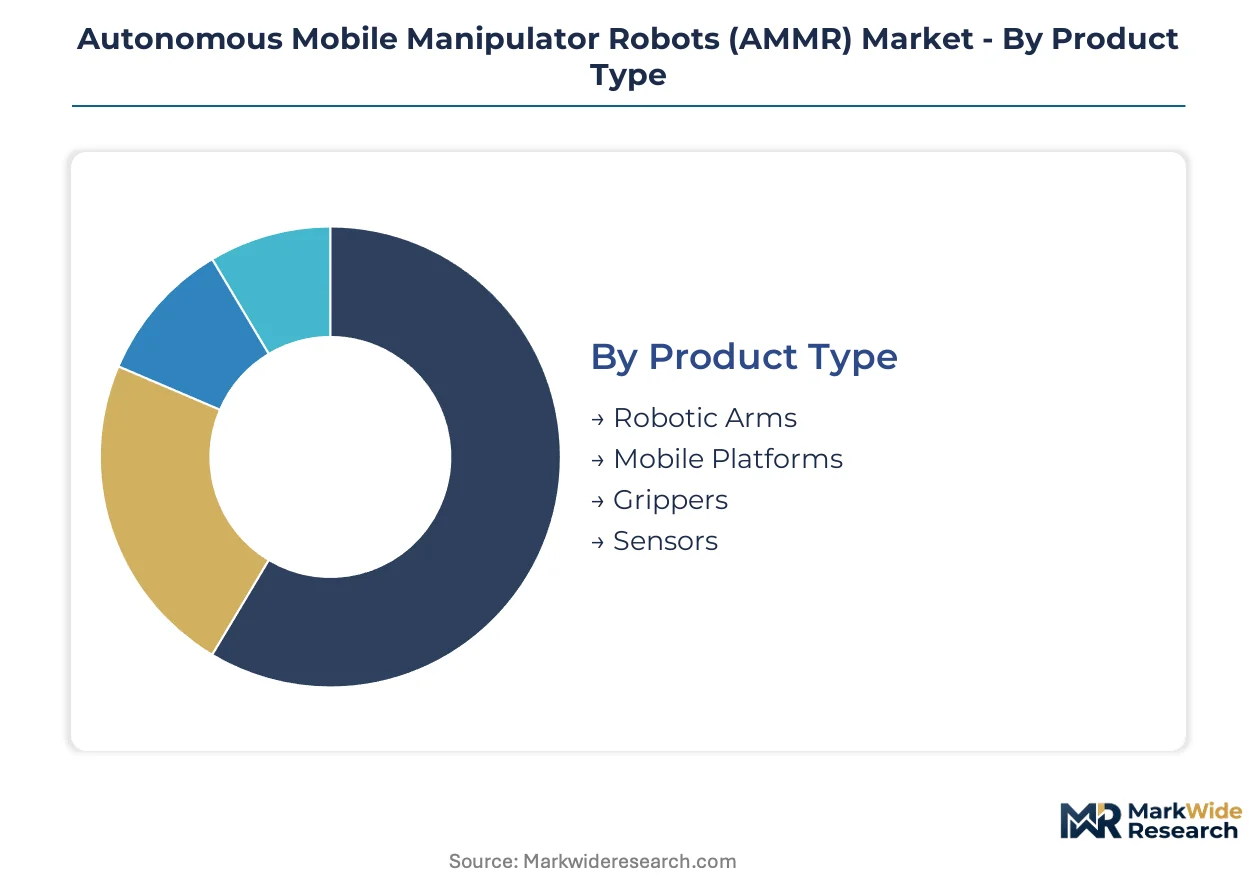
AMMR market segmentation reveals how value concentrates in precision hardware versus distributed software architectures. Vendors must calibrate R&D allocation across these dimensions to capture margin pools in automotive manufacturing and e-commerce logistics.
Product Type:
Margin pools concentrate in precision actuation and sensor fusion hardware, with software-enabled services emerging as a secondary profit center.
- Robotic Arms:Six-to-seven-axis manipulators with harmonic drive actuators and 10-20 kg payload ratings command premium pricing due to Japanese and German supplier concentration. German automotive OEMs and tier suppliers absorb the majority of unit volume as factory automation programs accelerate.
- Mobile Platforms:SLAM-enabled autonomous bases with 2-5 mm repeatability eliminate fixed infrastructure requirements for brownfield deployment. E-commerce fulfillment centers in Germany are deploying fleet-scale systems to replace conveyor infrastructure and enable dynamic slotting optimization.
- Grippers:Adaptive end-effectors with force-torque sensing for mixed-SKU handling.
- Sensors:LiDAR, depth cameras, and tactile arrays enabling real-time environmental perception.
The dominant share belongs to Robotic Arms, while Mobile Platforms is closing the gap fastest.
End User:
Application intensity varies sharply by sector, with capital expenditure cycles and labor cost structures determining adoption velocity.
- Manufacturing:Automotive battery assembly and component reshoring programs in Germany are expanding addressable floor space for AMMR deployment. Federal production subsidies are compressing payback periods to under 24 months for qualified investments.
- Logistics:Warehousing operations now represent the dominant demand source, with fulfillment centers prioritizing fleet flexibility over stationary automation. Dynamic slotting optimization is displacing fixed conveyor infrastructure at scale.
- Healthcare:FDA-regulated surgical and patient-care settings in the US impose device-level compliance requirements.
- Hospitality:Service robotics for cleaning and delivery functions in commercial facilities.
Manufacturing retains the largest installed base, though Logistics is expanding most quickly.
Technology:
Competitive positioning now hinges on inference architecture choices, separating deployable products from laboratory demonstrations.
- Artificial Intelligence:Edge-based neural inference is fragmenting traditional cloud-dependent pipelines for robotic grasping. GPU-accelerated onboard processors achieve sub-50 millisecond latency for mixed-SKU bin picking in German automotive tier supplier facilities.
- Computer Vision:Real-time object detection and pose estimation algorithms enable grasp adaptation without pre-programmed SKUs. EU AI Act conformity assessments for high-risk autonomous systems are mandating human oversight interfaces and training data traceability.
- Machine Learning:Reinforcement learning for motion planning in dynamic environments.
- IoT:Fleet orchestration middleware connecting AMMR systems to manufacturing execution systems.
Artificial Intelligence captures the steepest growth trajectory, while Computer Vision maintains the broadest deployment footprint.
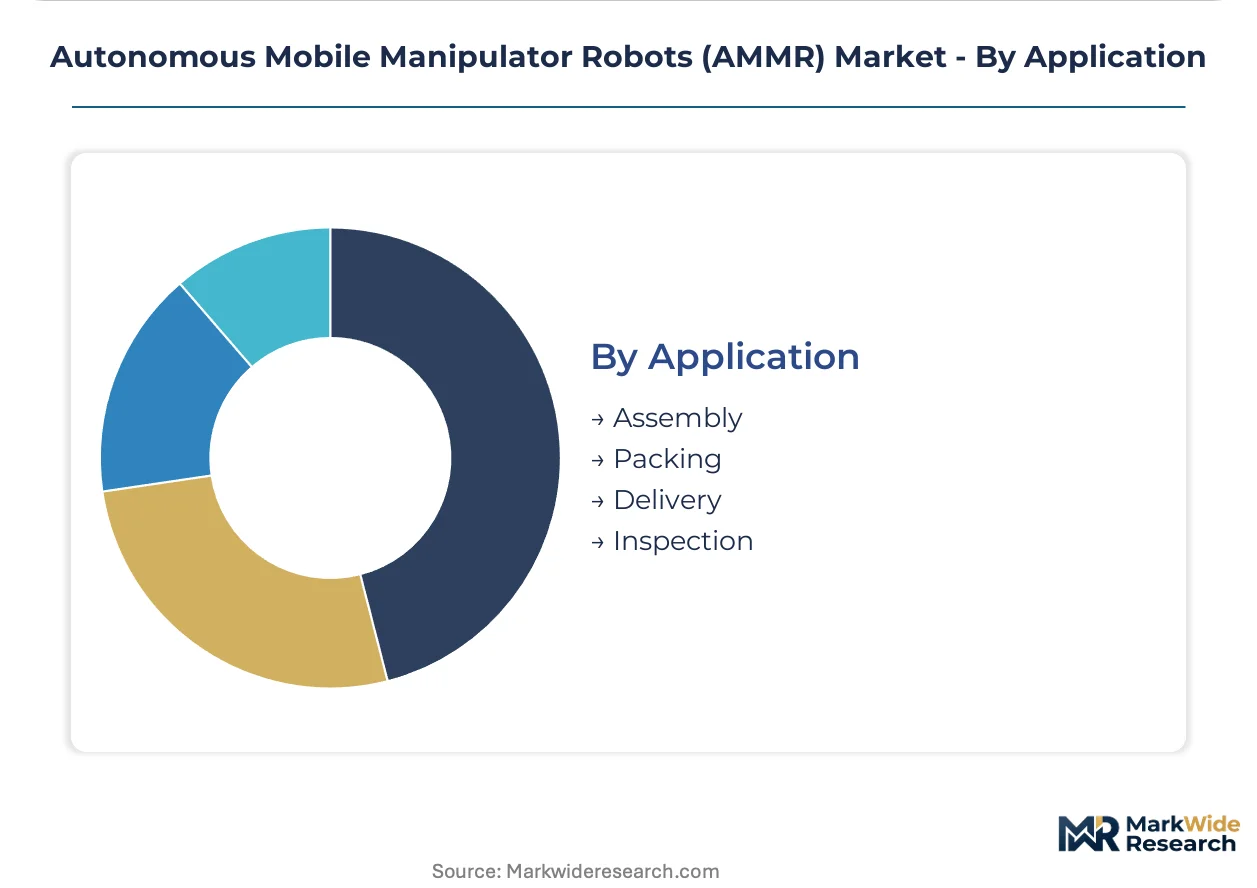
Application:
Task complexity and throughput requirements determine hardware configuration and software customization intensity.
- Assembly:Precision joining and fastening operations requiring force-controlled manipulation. German automotive producers are deploying collaborative systems for human-robot interaction zones, though ISO/TS 15066 speed and force thresholds restrict payload-to-weight ratios.
- Packing:Mixed-SKU order consolidation with dynamic carton selection. E-commerce fulfillment centers are driving demand for sub-50 millisecond grasp adaptation to handle unpredictable SKU mixes.
- Delivery:Intra-facility material transport between workstations and storage zones.
- Inspection:Quality verification using integrated vision systems for defect detection.
Assembly commands premium system pricing, while Packing is scaling fastest in unit terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and tier suppliers concentrate procurement authority in Germany, while e-commerce fulfillment networks drive deployment scale in the United States and China. Regulatory divergence between the EU AI Act and OSHA standards is fragmenting product architectures across Atlantic markets.
Germany
Federal production subsidies for domestic battery manufacturing are accelerating factory automation programs among automotive producers. The EU AI Act mandates conformity assessments for high-risk autonomous systems, compressing R&D timelines for navigation software. Stuttgart and Wolfsburg industrial clusters are absorbing fleet-scale AMMR deployments for component assembly and material transport.
United States
OSHA workplace safety standards govern collaborative speed and force limits in human-robot interaction zones across warehousing operations. FDA device regulations impose additional compliance layers for surgical and patient-care AMMR applications. Detroit automotive suppliers and California e-commerce fulfillment centers represent the dominant demand concentrations.
China
MIIT industrial automation directives prioritize domestic robot production capacity expansion under national manufacturing upgrade programs. GB standards for collaborative robotics establish force-limitation thresholds comparable to ISO/TS 15066. Yangtze River Delta electronics manufacturers and Pearl River Delta logistics hubs are piloting SLAM-based systems for brownfield deployment.
Japan
METI robotics industry roadmaps target precision actuator supply chain resilience through domestic harmonic drive and servo motor production. JIS safety standards align with ISO 10218 for industrial robot certification. Nagoya automotive manufacturing corridors and Osaka precision machinery clusters anchor AMMR integration programs.
India
CDSCO-regulated pharmaceutical facilities are piloting AMMR systems for sterile material handling in cleanroom environments. PLI scheme incentives for electronics manufacturing are expanding addressable factory floor space for automation deployment. Maharashtra and Karnataka industrial corridors are emerging as early adoption centers for assembly and packing applications.
Autonomous Mobile Manipulator Robots (AMMR) Market Competitive Environment
Player mix skews toward diversified industrial automation conglomerates with captive component production. Market structure concentrates margin capture among vertically integrated arm manufacturers and specialized mobility platform developers. Two strategic archetypes dominate: precision actuator suppliers with downstream system integration, and pure-play mobility specialists with legged locomotion differentiation. Competitive moves center on ISO 10218 pre-certification against EU AI Act timelines and backward integration into servo motor supply.
Within the integrated automation tier, FANUC Corporation and KUKA AG represent contrasting geographic anchoring strategies for arm-and-mobile system offerings. Boston Dynamics occupies a distinct position among legged mobility specialists navigating unstructured environments. These three companies exemplify how vendor competitive sets fragment between precision hardware incumbents and locomotion architecture innovators.
| Leading Market Players |
|---|
| ABB |
| FANUC Corporation |
| KUKA AG |
| Omron Corporation |
| Boston Dynamics |
| Yaskawa Electric Corporation |
| Clearpath Robotics |
| Robotnik |
| Stäubli International AG |
| Others |
Value Chain & Pricing Dynamics
Scale economies in precision actuator manufacturing concentrate pricing power among Japanese and German component suppliers, compressing margin pools for system integrators while elevating floor prices for ISO 10218-certified platforms. German automotive OEMs absorb premium pricing for six-to-seven-axis manipulators with harmonic drive actuators, while e-commerce fulfillment centers negotiate fleet-scale discounts on SLAM-enabled mobile bases.
Pricing Analysis
Cost-plus contracts with rare-earth and semiconductor indexation dominate precision actuator procurement, shielding Japanese suppliers from input volatility while exposing integrators to margin compression. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10218-certified collaborative systems from uncertified industrial variants and refurbished legacy units. Pricing pressure stems from Chinese MIIT industrial automation directives accelerating domestic robot production capacity. Logistics buyers exhibit highest price sensitivity due to thin e-commerce margins, whereas German automotive tier suppliers prioritize certification compliance over unit cost.
Supply Chain Analysis
Strategic stockpiling of harmonic drives and high-torque servo motors has replaced just-in-time preferences as Japanese suppliers face allocation constraints from semiconductor foundry bottlenecks. Component supply concentrates in Japan, Germany, and China, with FANUC and Yaskawa Electric anchoring precision actuator production. Raw material dependencies span rare-earth magnets, copper windings, and silicon carbide power semiconductors. Single-source vulnerability in harmonic drive manufacturing exposes lead times to geopolitical friction. Distribution runs through authorized system integrators with captive service capabilities in European and North American warehousing hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of multi-axis calibration engineers combining kinematic modeling with real-time control expertise is constraining deployment velocity and inflating implementation costs across brownfield facilities.
For Market Incumbents: Consolidate backward integration into servo motor supply to defend margin position against Japanese component concentration. Accelerate ISO 10218 pre-certification ahead of EU AI Act high-risk system deadlines to lock in German automotive procurement cycles. Expand captive service headcount in Stuttgart and Wolfsburg industrial clusters to counter third-party integrator displacement. For New Entrants and Emerging Players: Differentiate on sub-50 millisecond edge inference latency for mixed-SKU bin picking, targeting Indian pharmaceutical cleanroom pilots where CDSCO certification barriers deter established vendors. Penetrate Maharashtra and Karnataka electronics manufacturing corridors via PLI scheme-qualified automation investments. Pursue performance-based maintenance contracts with uptime guarantees rather than bundled hardware-service pricing. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors GPU-accelerated edge computing specialists with software-defined grasp adaptation capabilities over legacy arm manufacturers tethered to cloud-dependent AI pipelines. Long-term viability hinges on EU AI Act compliance infrastructure and traceable training data architectures. Acquisition targets should demonstrate ISO/IEC 42001 pre-certification progress. The signal to watch is German automotive OEM consolidation of fleet orchestration middleware procurement away from proprietary MES vendors.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10218 Pre-Certification Investment | EU AI Act high-risk classification mandates conformity assessments, compressing R&D timelines for navigation software. |
| Backward Integration into Servo Motors | FANUC's captive production shields margin control against Japanese supplier concentration and rare-earth volatility. |
| GPU-Accelerated Edge Inference Deployment | Sub-50 millisecond latency enables mixed-SKU bin picking without pre-programmed configurations in German tier supplier facilities. |
| Performance-Based Maintenance Contracts | Uptime-guarantee pricing displaces manufacturer-captive service organizations in European warehousing deployments. |
| Cleanroom Certification for Pharmaceutical Handling | CDSCO-regulated Indian facilities create first-mover advantage for sterile material handling automation. |
Study Parameters
A standing panel of plant engineers, OEM procurement managers, aftermarket service heads, and system integration specialists provided ongoing calibration against deployment realities. Primary interviews with German automotive tier supplier automation directors and Indian pharmaceutical facility engineering leads were cross-validated against secondary sources including SEC filings from industrial automation conglomerates, customs records for precision actuator trade flows, and EU AI Act implementation guidance documents. Bottom-up unit economics for SLAM-enabled mobile platforms were triangulated with top-down market sizing from warehousing automation capex disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation by product type, end-user industry, technology architecture, and application task complexity. CAGRs were derived from installed base expansion rates and replacement cycle analysis. Industry-specific forecast inputs incorporated EU AI Act compliance timeline phasing and German federal production subsidy qualification thresholds for battery manufacturing automation.
Decision-makers should treat outputs as directional under assumptions of sustained German automotive reshoring incentives and stable rare-earth magnet supply from established extraction corridors; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding ISO 10218 certification adoption velocity and edge computing cost curves. Revision becomes warranted when EU AI Act enforcement intensity or Chinese MIIT domestic production targets cross thresholds that restructure competitive supplier geography.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Autonomous Navigation Robots Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Market
Robotics and Automation
Global Automated Guided Vehicle (AGV) Software Market
Robotics and Automation
Autonomous Drilling Robots Market
Robotics and Automation
Quadruped Robot Market
Robotics and Automation
Assistive Technology Market
Robotics and Automation
Robot for Public Service Market
Robotics and Automation
Singapore Cloud Robotics Market
Robotics and Automation
Pipetting Robots Market
Robotics and Automation
Medical Service Robots Market
Robotics and Automation
US Cloud Robotics Market
Robotics and Automation
Europe Underwater Robotics Market
Robotics and Automation
North America Agricultural Robots and Mechatronics Market
Robotics and Automation
Claytronics Market
Robotics and Automation
Medical Robots Market
Robotics and Automation
GCC AUV Market