
 Long-Range Drone Package Delivery Market | 2026-2036
Long-Range Drone Package Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Long-Range Drone Package Delivery Market Analysis
A shift from single-source to multi-source airframe procurement is decoupling fleet economics from captive manufacturing. Zipline International Inc. anchors East African and U.S. healthcare networks with fixed-wing infrastructure. Wingcopter GmbH differentiates through tilt-rotor versatility across maritime and alpine delivery corridors. Amazon.com Inc. sustains capital intensity in autonomous sorting and hub-to-hub trunk routes.
Long-range drone package delivery denotes unmanned aerial systems capable of transiting beyond visual line of sight, typically exceeding 15 kilometers, using fixed-wing, multirotor, or hybrid propulsion architectures with payload capacities from 2 to 200 kilograms. These platforms serve commercial logistics by replacing ground-based last-mile and middle-mile transport with direct aerial routing. Hybrid drones occupy the highest growth trajectory as operators seek to merge vertical takeoff flexibility with cruise efficiency over extended distances. Medical supply transport commands premium margin pools due to temperature-controlled payload requirements and contracted service agreements with hospital networks. Autonomous navigation technology leads R&D allocation as beyond-visual-line-ofsight operations demand redundant sense-and-avoid systems.
The FAA's Part 135 certification framework and the EASA's specific category operational authorizations govern commercial drone carriage in the United States and European Union, respectively, while Australia's Civil Aviation Safety Authority enforces remote operator accreditation for long-range routes. These regulatory architectures shape market access by mandating airworthiness certification, pilot qualification tiers, and operational risk assessments that filter entrants by compliance capital. Stakeholders must monitor evolving detect-and-avoid mandates and airspace integration protocols as regulators balance safety thresholds against network scale ambitions.
Market Dynamics
The FAA's Part 135 air carrier certification is restructuring operational legality by mandating airworthiness standards that filter entrants by compliance capital rather than engineering capability alone. This regulatory pivot is decoupling fleet economics from captive manufacturing and forcing operators toward multi-source airframe procurement strategies.
Growth Catalysts
- Beyond-Visual-Line-of-Sight waivers:The FAA's BVLOS exemptions are enabling healthcare networks in Rwanda and Ghana to establish dedicated drone corridors for blood product transport.
- Hybrid propulsion architectures:Tilt-rotor and fixed-wing hybrid designs are merging vertical takeoff flexibility with cruise efficiency, opening alpine and maritime delivery corridors previously inaccessible to pure multirotor platforms.
- Cold-chain payload specialization:Temperature-controlled compartments for vaccine and biologic transport are commanding premium service contracts from hospital procurement departments.
Market Restraints
- Detect-and-avoid hardware costs:Redundant sense-and-avoid sensor suites add substantial unit economics burden to airframe procurement, compressing margins on sub-five-kilogram payload routes.
- Aviation-grade battery supply concentration:High-density lithium-sulfur cell production concentrates in South Korean and Chinese manufacturing facilities, exposing operators to input cost volatility and export control friction.
- Airspace integration latency:EASA's specific category operational authorizations impose multi-month certification timelines that throttle network expansion velocity across European Union member states.
Strategic Opportunities
- Australia's remote healthcare logistics:The Civil Aviation Safety Authority's remote operator accreditation framework is opening long-range routes across the Northern Territory and Western Australia where ground infrastructure is sparse.
- Hub-to-hub trunk routing:Autonomous sorting facilities connected by fixed-wing drones are displacing short-haul ground transport between distribution centers, creating new middle-mile service tiers.
- Maritime last-mile delivery:Offshore oil platforms and coastal shipping lanes represent underpenetrated corridors where tilt-rotor endurance exceeds helicopter economics.
Industry Challenges
- Certified remote pilot scarcity:The FAA's three-tier pilot qualification system requires type-specific ratings that outpace training pipeline output, constraining fleet scaling.
- Legacy logistics integration:Warehouse management systems and route optimization software require API reconfiguration to ingest real-time drone telemetry, delaying hybrid fleet deployments.
- Airframe interoperability standards:Absence of unified charging, payload, and communication protocols forces operators into single-vendor lock-in or expensive adapter development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Long-Range Drone Package Delivery Market |
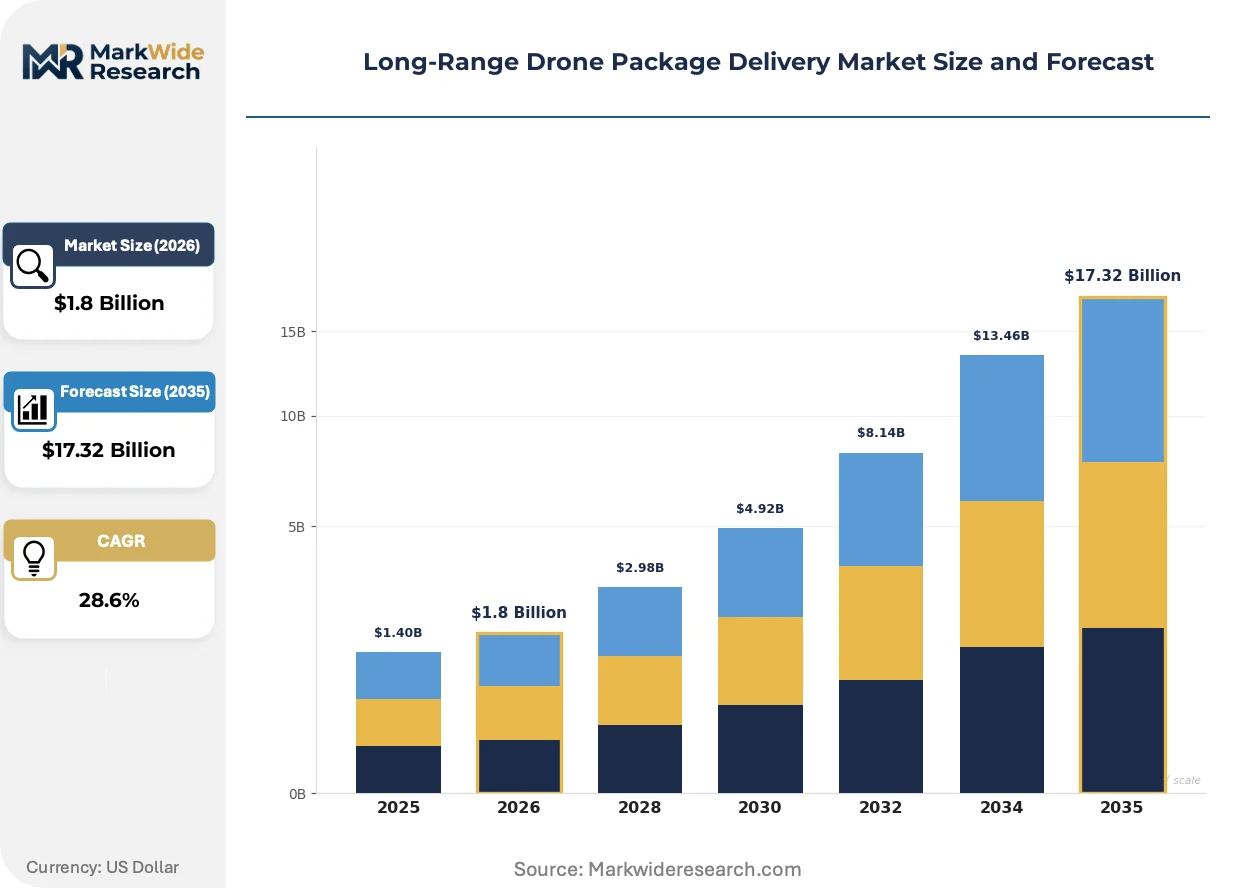
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing Drones, Multirotors, Hybrid Drones, Delivery Bots Technology: Autonomous Navigation, GPS Tracking, AI Surveillance, Sensor Integration End User: E-commerce, Retail, Healthcare, Logistics Application: Food Delivery, Medical Supply Transport, Package Shipment, Last-Mile Logistics |
| Companies Covered | Zipline International Inc., Wing Aviation LLC, Matternet Inc., United Parcel Service Inc., Wingcopter GmbH, Elroy Air, Dronamics, Flytrex Inc., Amazon.com Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Long-Range Drone Package Delivery Market Emerging Trajectories
Autonomous navigation systems are converging with detect-and-avoid hardware to enable single-pilot oversight of multi-aircraft fleets, compressing labor intensity per delivery. This technological fusion is reshaping unit economics and regulatory risk profiles simultaneously.
Hybrid propulsion engineering is converging with aviation-grade battery chemistry to extend operational radius beyond fifty kilometers while maintaining payload flexibility. Hospital networks in East Africa and Southeast Asia are adopting these platforms for inter-facility medical supply shuttles. The structural consequence is converging with hub-and-spoke distribution models that displace ground-based middle-mile transport.
EASA's specific category operational authorizations are mandating standardized risk assessments and operational safety cases for commercial drone carriage across European Union airspace. This framework is elevating compliance capital requirements and consolidating market access among well-capitalized operators. Medical supply transport segments are responding by pre-certifying entire route networks rather than seeking ad-hoc flight approvals.
Buyer procurement patterns are rotating toward contracted service agreements with guaranteed uptime and temperature-compliance penalties rather than per-flight transactional pricing. Hospital procurement departments are displacing traditional courier contracts with multi-year drone logistics partnerships. This shift is most visible in Australia's rural healthcare networks where ground transport reliability is seasonal and costly.
Long-Range Drone Package Delivery Market Segmentation
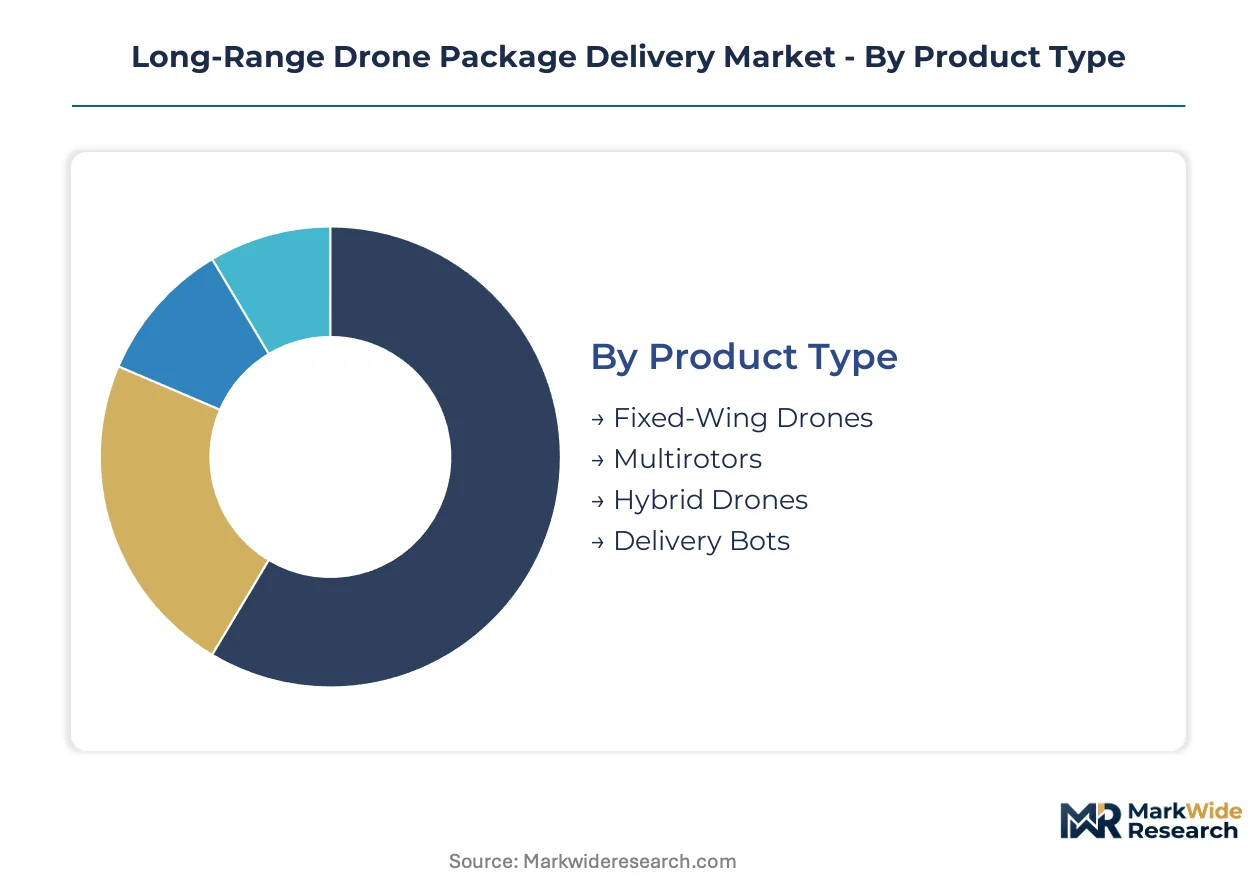
Segmentation in long-range drone logistics separates platforms by flight physics, operational intelligence, and contractual buyer type. Procurement decisions hinge on route distance, payload thermal requirements, and regulatory certification tier rather than unit cost alone.
Product Type:
Buyers select airframes based on runway access, payload density, and corridor topography rather than acquisition price.
- Fixed-Wing Drones:These platforms deploy high-aspect-ratio wings for extended range with minimal energy expenditure. Hospital networks in Rwanda and Ghana favor fixed-wing infrastructure for inter-facility blood product shuttles where vertiport scarcity eliminates multirotor options.
- Hybrid Drones:Tilt-rotor architectures merge vertical takeoff capability with cruise-phase efficiency. Maritime logistics operators across Australia's Northern Territory deploy hybrid systems for offshore platform resupply where helicopter economics prove unsustainable.
- Multirotors:Pure rotary platforms dominate sub-fifteen-kilogram payload routes with dense urban vertiport access.
- Delivery Bots:Ground-crawling autonomous systems handle final-meter handoff in campus and residential cluster environments.
Volume sits with fixed-wing platforms; growth tilts toward hybrid architectures.
Technology:
Technology procurement prioritizes redundancy certification and sense-and-avoid hardware integration over algorithmic sophistication.
- Autonomous Navigation:Beyond-visual-line-of-sight operations demand redundant flight control systems with real-time path replanning. FAA Part 135 certification mandates specific autonomy tiers that filter vendors by validation capital rather than feature depth.
- Sensor Integration:Multi-modal perception stacks combining LiDAR, radar, and optical flow enable single-pilot oversight of multi-aircraft fleets. Australian Civil Aviation Safety Authority remote operator accreditation requires demonstrated sensor redundancy for long-range corridor approval.
- GPS Tracking:Dual-band GNSS receivers with RTK correction support precision landing in GPS-denied environments.
- AI Surveillance:Machine learning-based anomaly detection flags mechanical degradation before flight-critical failure.
Deployment concentrates on sensor integration; capability expansion centers on autonomous navigation.
End User:
Contract structure and uptime penalties vary sharply across buyer categories with divergent reliability thresholds.
- Healthcare:Hospital procurement departments negotiate multi-year service agreements with temperature-compliance penalties and guaranteed availability clauses. Cold-chain payload specialization commands premium pricing for vaccine and biologic transport.
- Logistics:Third-party carriers seek hub-to-hub trunk routing to displace short-haul ground transport between distribution centers. EASA specific category operational authorizations impose certification timelines that throttle network expansion velocity.
- E-commerce:Direct-to-consumer retailers prioritize last-mile density over route distance.
- Retail:Brick-and-mortar chains deploy drones for inter-store inventory balancing and same-day fulfillment.
Revenue concentrates with healthcare networks; contract velocity accelerates fastest in logistics.
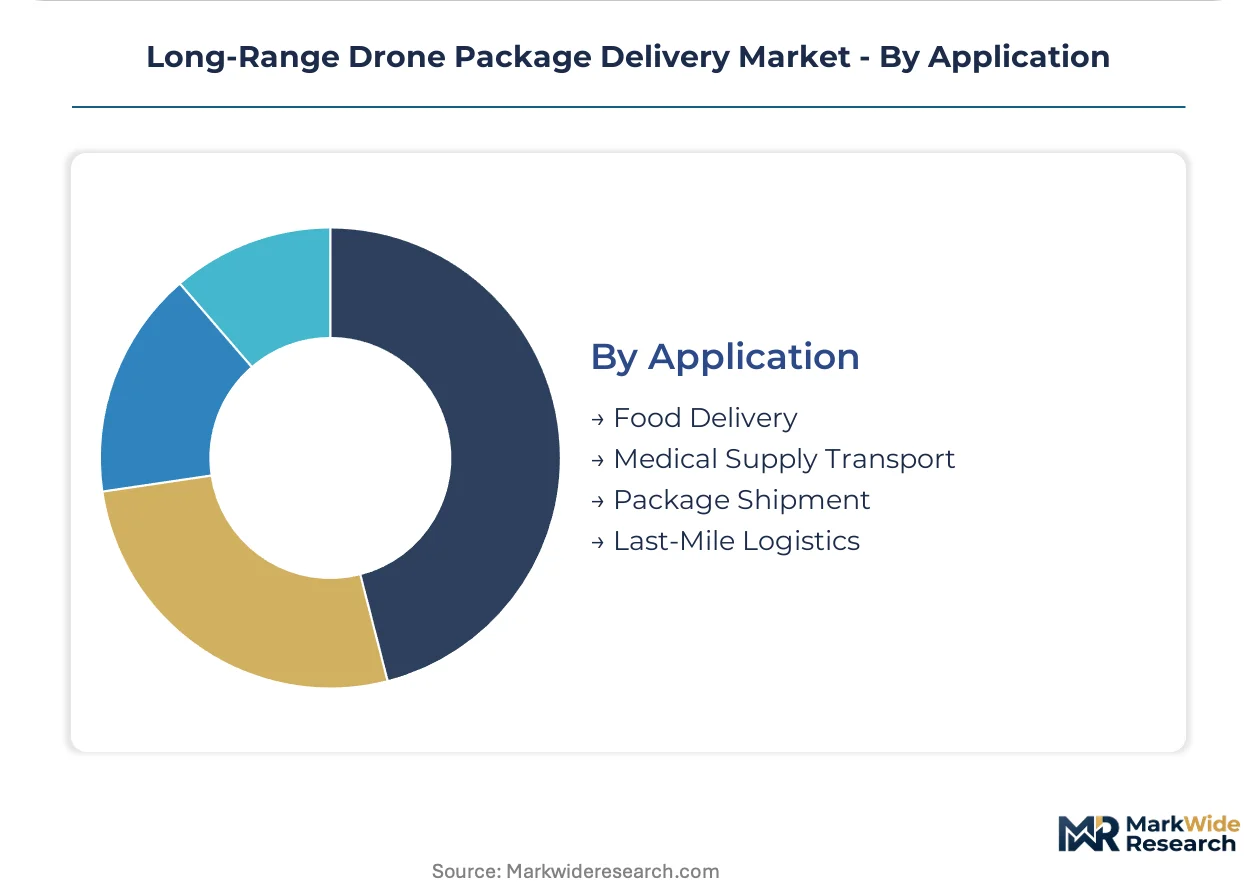
Application:
Application selection determines payload compartment specification, battery chemistry grade, and pilot qualification tier.
- Medical Supply Transport:Temperature-controlled compartments with active cooling maintain biologic viability across extended routes. East African healthcare corridors have established dedicated drone networks for blood product distribution.
- Last-Mile Logistics:Dense urban delivery requires precision landing systems and noise abatement profiles compatible with residential zoning. Australia's remote healthcare logistics corridors demonstrate how ground infrastructure gaps create aerial substitution economics.
- Food Delivery:Insulated payload bays with thermal retention prioritize speed over extended range.
- Package Shipment:General freight applications standardize on modular payload containers with rapid swap capability.
Deployment scale favors medical supply transport; route expansion accelerates fastest in last-mile logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium-sulfur cell production concentrates in South Korean and Chinese manufacturing facilities, anchoring Asia-Pacific supply chains for aviation-grade drone batteries. Regulatory divergence across jurisdictions is fragmenting operational approval timelines and reshaping network deployment sequences.
United States
The FAA's Part 135 air carrier certification mandates airworthiness standards that filter entrants by compliance capital rather than engineering capability alone. BVLOS waivers enable healthcare networks in North Carolina and Arkansas to establish dedicated drone corridors for blood product transport. Zipline International Inc. anchors East African and U.S. healthcare networks with fixed-wing infrastructure extending into American rural markets.
Germany
EASA's specific category operational authorizations impose multi-month certification timelines that throttle network expansion velocity across European Union member states. The country's national aviation regulator enforces standardized risk assessments and operational safety cases for commercial drone carriage. Wingcopter GmbH differentiates through tilt-rotor versatility across maritime and alpine delivery corridors originating from German engineering clusters.
Australia
The Civil Aviation Safety Authority's remote operator accreditation framework is opening long-range routes across the Northern Territory and Western Australia where ground infrastructure is sparse. Temperature-controlled payload requirements for vaccine transport command premium service contracts from hospital procurement departments in remote healthcare logistics corridors. Demand concentrates in rural and remote healthcare logistics corridors where seasonal ground transport reliability fails.
Rwanda
Beyond-visual-line-of-sight exemptions enable healthcare networks to establish dedicated drone corridors for blood product transport across mountainous terrain. The country's national civil aviation authority enforces remote operator accreditation for long-range routes connecting rural clinics to urban hospital hubs. Zipline International Inc. operates fixed-wing infrastructure for inter-facility medical supply shuttles serving East African healthcare networks.
China
Aviation-grade battery supply concentration exposes operators to input cost volatility and export control friction from high-density lithium-sulfur cell production. The country's national aviation regulator governs commercial drone carriage through airworthiness certification and operational risk assessment mandates. Manufacturing clusters in the Yangtze River Delta supply sense-and-avoid sensor suites for redundant flight control systems demanded by BVLOS operations.
Long-Range Drone Package Delivery Market Vendor Landscape
Capacity expansion dominates the current landscape as operators scale fleet deployment ahead of regulatory harmonization. The vendor base stratifies across three tiers: well-capitalized logistics integrators, specialized healthcare corridor operators, and component-focused airframe fabricators. Two strategic archetypes have emerged: tilt-rotor versatility specialists and fixed-wing healthcare network anchors. Competitive intensity concentrates on M&A activity for airframe procurement capabilities and strategic partnerships for detect-and-avoid hardware integration.
Within the healthcare corridor tier, Zipline International Inc. and Matternet Inc. exemplify fixed-wing and multirotor specialization archetypes respectively. Wingcopter GmbH occupies a position among European tilt-rotor engineering specialists. These three entities represent contrasting responses to regulatory fragmentation: Zipline International Inc. anchors pre-certified route networks, Matternet Inc. sits within urban last-mile density plays, and Wingcopter GmbH exemplifies alpine and maritime corridor penetration strategies.
| Leading Market Players |
|---|
| Zipline International Inc. |
| Wing Aviation LLC |
| Matternet Inc. |
| United Parcel Service Inc. |
| Wingcopter GmbH |
| Elroy Air |
| Dronamics |
| Flytrex Inc. |
| Amazon.com Inc. |
| Others |
Supply Flow & Price Mechanics
Aviation-grade battery recycling mandates from the EU Battery Regulation are gating qualified supply access and premium-tier pricing for certified operators, forcing procurement departments to validate supplier ESG credentials before contract award. This sustainability filter concentrates purchasing power among operators with compliance capital to absorb traceability costs.
Pricing Analysis
Extended warranty and airworthiness certification bundling separates premium-tier contracts from unbundled transactional pricing. Three-tier pricing structure across premium, standard, and economy levels reflects FAA Part 135 certification grade and detect-and-avoid hardware redundancy. Cost compression in economy-tier sub-five-kilogram payload routes is intensifying because redundant sensor suite requirements outscale route economics. Hospital procurement departments exhibit lowest price sensitivity due to temperature-compliance penalty structures; e-commerce retailers face highest pressure on per-delivery unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale operator demand for aviation-grade lithium-sulfur cells, while specialized distributors serve mid-fleet procurement. High-density battery cell production concentrates in South Korean and Chinese manufacturing facilities. Sense-and-avoid sensor suites draw from Taiwanese optical component foundries and German radar module specialists. Single-source vulnerability in lithium-sulfur cathode chemistry exposes operators to export control friction. Distribution runs through certified component aggregators with FAA airworthiness documentation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FAA Part 135 certification creates a barrier-to-entry moat that rewards operators with pre-certified route networks and filters out capital-constrained entrants.
For Market Incumbents: Deepen detect-and-avoid hardware integration partnerships to compress single-pilot oversight ratios and defend against emerging tilt-rotor specialists. Expand multi-source airframe procurement to decouple fleet economics from captive manufacturing exposure. Prioritize certification investment in Australia's remote operator accreditation framework to anchor Asia-Pacific corridor control.
For New Entrants and Emerging Players: Enter via maritime last-mile corridors for offshore oil platforms where helicopter economics prove unsustainable and regulatory density remains lowest. Australia's Northern Territory and Western Australia represent the most penetrable geography given sparse ground infrastructure and active CASA accreditation pathways. Pursue contracted service agreements with guaranteed uptime clauses rather than per-flight transactional pricing to align buyer incentives.
For Investors and Strategic Acquirers: EASA specific category operational authorization approval timelines compressing below six months is the leading indicator that European network expansion velocity is inflecting toward scalable deployment. Long-term viability centers on operators with pre-certified healthcare corridor density and backward integration into aviation-grade battery supply. Monitor BVLOS waiver grant velocity at FAA as the primary demand signal for U.S. market readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Airframe Procurement | Decouples fleet economics from captive manufacturing and reduces single-vendor lock-in risk. |
| Detect-and-Avoid Hardware Integration | Enables FAA Part 135 certification compliance and single-pilot multi-aircraft oversight. |
| Remote Operator Accreditation Investment | Secures CASA approval for Australia's Northern Territory healthcare logistics corridors. |
| Cold-Chain Payload Specialization | Commands premium service contracts from hospital procurement departments with temperature penalties. |
| Hub-to-Hub Trunk Routing Deployment | Displaces short-haul ground transport between distribution centers with fixed-wing efficiency. |
Methodological Framework
Trade data filings, aviation regulator certification databases, and hospital procurement contract registries formed the secondary backbone, supplemented by primary interviews with FAA certification leads, CASA remote operator assessors, hospital supply chain directors, and lithium-sulfur battery procurement managers at fleet operators. Bottom-up airframe deployment counts triangulated against top-down logistics spend allocation models across healthcare and e-commerce verticals.
Historical BVLOS waiver grant rates and fleet certification timelines anchored the projection framework across the analysis window. Segmentation dimensions modeled include propulsion architecture, payload thermal requirement tier, pilot qualification level, and regional regulatory cluster. CAGRs derived from fitted adoption curves weighted by corridor infrastructure maturity and buyer contract velocity. Forecast inputs incorporated aviation-grade battery cell production capacity announcements and EASA operational authorization processing rate trends.
Forecast precision tightens around the base case; tail outcomes carry wider variance under detect-and-avoid mandate acceleration or lithium-sulfur export restriction scenarios. Periodic stress-testing of base assumptions is recommended, particularly around FAA Part 135 certification timeline assumptions and healthcare network contract renewal rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Pipe Inspection Robot Market
Robotics and Automation
Global Smart Robots Market
Robotics and Automation
Bot Services Market
Robotics and Automation
Robot Coffee Kiosk Market
Robotics and Automation
Middle East Cloud Robotics Market
Robotics and Automation
Delta Robots Market
Robotics and Automation
Global Adaptive Robotics Market
Robotics and Automation
Automotive Robotics Market
Robotics and Automation
South America AUV Market
Robotics and Automation
Electric Power Intelligent Inspection Robot Market
Robotics and Automation
Europe Agricultural Robots and Mechatronics Market
Robotics and Automation
Agricultural Robots Market
Robotics and Automation
Telepresence Robot Market
Robotics and Automation
US Cloud Robotics Market
Robotics and Automation
Nanorobotics Market
Robotics and Automation
Robotics for NDT Market