
 Intelligent Vending Machines Market | 2026-2036
Intelligent Vending Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Vending Machines Market Analysis
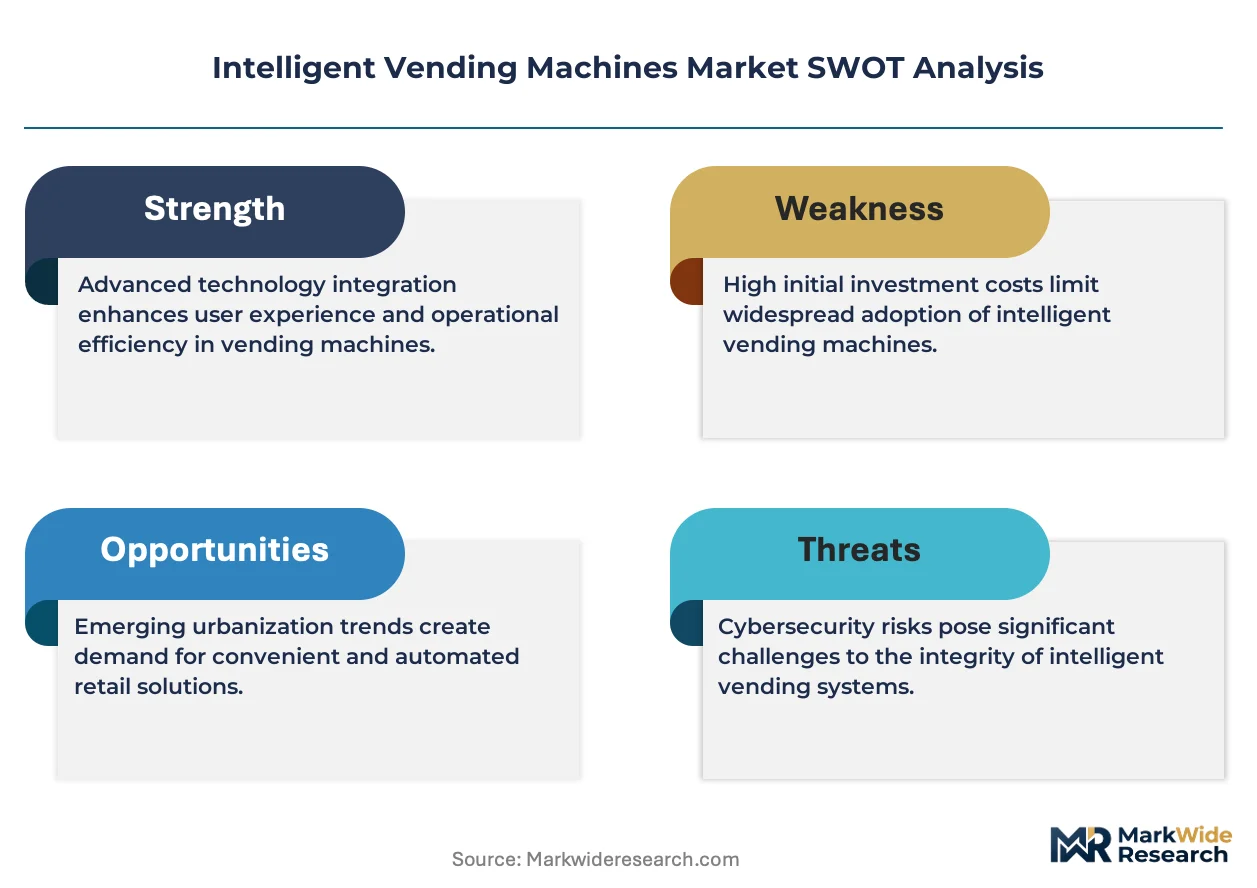
The intelligent vending machine sector is pivoting between premium connected systems and commodity hardware as operators split capital budgets between touchscreen-enabled units and basic mechanical dispensers. Crane Co. leverages its payment-system integration to anchor the North American airport channel. Fuji Electric Co., Ltd. sustains technology leadership in refrigeration-efficient designs for fresh-food applications. Azkoyen Group differentiates through specialized coffee-vending platforms that occupy premium positions in European office buildings.
Intelligent vending machines are automated retail terminals integrating sensors, payment processors, and telemetry modules to execute unattended transactions; typical units operate on 110-240V AC with embedded ARM-based controllers managing temperature, inventory, and cashless protocols for 24/7 commercial service. Beverage vending retains the largest installed base but fresh food vending is expanding fastest as cold-chain reliability improves. IoT connectivity and remote monitoring together capture the strongest margin pools because operators pay recurring fees for predictive maintenance and real-time inventory dashboards. Touchscreen interface adoption lags in cost-sensitive channels where basic button interfaces still dominate unit economics.
FDA food-safety standards and the EU Green Deal efficiency mandates together shape product design, forcing manufacturers to certify refrigeration systems and disclose energy consumption before market access. Japan's METI operational-technology guidelines and the EU GDPR data-localization rules constrain how consumer transaction data flows across cloud architectures. Stakeholders must decide whether to build compliant data infrastructure regionally or accept fragmented platform architectures that limit cross-border fleet management.
Market Dynamics
The intelligent vending machine market is bifurcating between premium connected units and basic mechanical dispensers as operators allocate capital across touchscreen-enabled telemetry systems and cost-optimized hardware for price-sensitive channels.
Growth Catalysts
- EU AI Act compliance mandates:Embedded data-protection architectures are becoming standard features as manufacturers redesign controller firmware to satisfy GDPR data-localization requirements across European deployments.
- Transportation hub retail expansion:Airports and railway stations in Germany, Japan, and the United States are deploying smart dispensing systems to capture 24/7 passenger traffic with minimal labor overhead.
- Fresh-food cold-chain reliability:Improved refrigeration monitoring and predictive temperature alerts are enabling operators to stock perishables with confidence, expanding addressable SKU categories beyond traditional packaged snacks.
Market Restraints
- ARM-based controller supply concentration:Semiconductor fabrication bottlenecks for embedded processors create lead-time volatility for manufacturers assembling telemetry-enabled units.
- 110-240V AC power infrastructure heterogeneity:Regional voltage standards force hardware variants that fragment production scale and inflate certification costs per geography.
- Mechanical dispenser substitution:Basic button-interface units retain unit economics advantages in cost-sensitive channels, capping premium system penetration in emerging markets.
Strategic Opportunities
- India urban transit corridors:Metro systems in Delhi, Mumbai, and Bangalore present underpenetrated installation bases for cashless payment-integrated units as digital wallet penetration accelerates.
- EU Green Deal efficiency incentives:Energy consumption disclosure mandates create competitive differentiation for refrigeration systems certified under updated F-Gas Regulation standards.
- Computer vision and weight-sensor convergence:Grab-and-go checkout architectures are absorbing frictionless retail concepts, enabling new deployment models in corporate campuses and healthcare facilities.
Industry Challenges
- Embedded systems firmware certification:Multi-jurisdiction compliance timelines for FDA food-safety validation and METI operational-technology guidelines extend product launch cycles.
- Legacy payment protocol integration:Field retrofit of magnetic-stripe and contactless EMV hardware into installed mechanical bases demands specialized technician networks that operators struggle to scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Vending Machines Market |
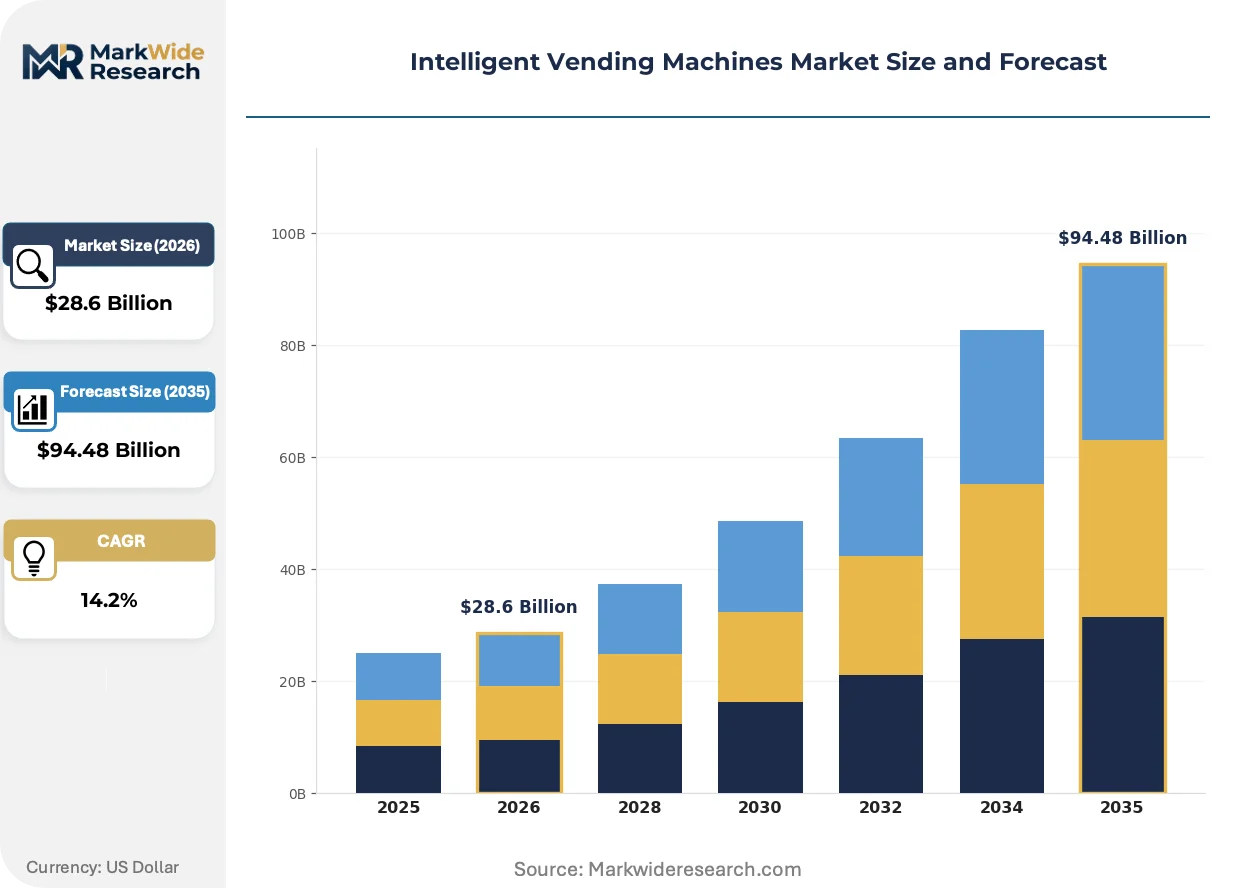
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snack Vending, Beverage Vending, Fresh Food Vending, General Merchandise Vending Technology: Cashless Payment, IoT Connectivity, Touchscreen Interface, Remote Monitoring End User: Retail Outlets, Airports, Schools, Office Buildings Installation Type: Indoor, Outdoor, Mobile, Permanent |
| Companies Covered | Crane Co., Azkoyen Group, FAS International S.p.A., Bianchi Vending Group S.p.A., N&W Global Vending S.p.A., Rhea Vendors Group, Fuji Electric Co., Ltd., Sanden Corporation, Seaga, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Vending Machines Market Emerging Trajectories
Telemetry modules and remote monitoring capabilities are absorbing the strongest margin pools as operators shift from capital equipment sales toward recurring SaaS revenue models for fleet management.
Edge computing architectures with localized AI inference are absorbing latency-sensitive functions like inventory recognition and predictive maintenance alerts. Airport and railway operators in Germany and Japan are deploying these systems fastest, prioritizing sub-second transaction processing over cloud-dependent alternatives. The technology is absorbing margin from traditional centralized platforms by reducing data egress costs and satisfying GDPR data-residency requirements without architectural fragmentation.
The EU AI Act risk-classification framework is compelling manufacturers to document algorithmic decision-making for consumer-facing interfaces. Vending systems with biometric age-verification or personalized recommendation engines now face conformity assessment procedures previously reserved for higher-risk AI applications. Fresh-food vending platforms with automated quality grading are most affected, with European manufacturers redesigning sensor fusion pipelines to maintain audit trails.
Corporate procurement departments are consolidating vending service contracts under facility-management umbrella agreements rather than standalone equipment leases. This bundling displaces fragmented local operator relationships with national managed-service providers in the United States and United Kingdom. The shift is most visible in premium office buildings where landlords specify integrated amenity packages including coffee, fresh food, and retail automation from single vendors.
Intelligent Vending Machines Market Segmentation
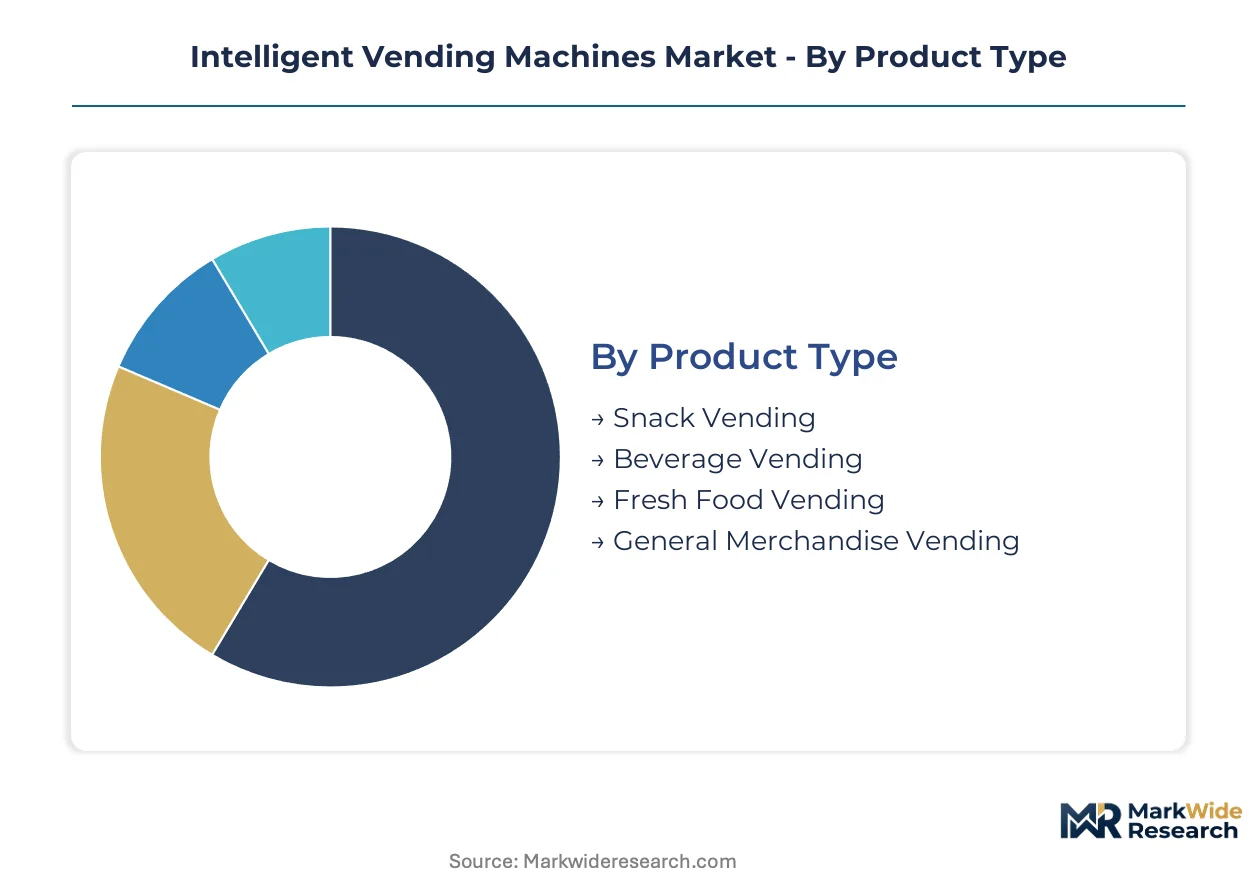
Segmentation in intelligent vending machines reveals how capital allocation splits between premium connected systems and cost-optimized hardware. Each dimension exposes distinct buyer priorities: SKU mix determines refrigeration requirements, technology choices separate recurring-revenue operators from equipment sellers, and installation type dictates enclosure durability standards.
Product Type:
Buyers in this category differentiate by cold-chain complexity and margin per transaction rather than unit volume alone.
- Beverage Vending:Units integrate multi-zone refrigeration (2-8°C for dairy, ambient for shelf-stable) with can-bottle handling mechanisms rated for 500+ daily vends. Demand clusters in Japan's railway corridors and German airports where 24/7 beverage access commands premium placement fees.
- Fresh Food Vending:Systems deploy HACCP-compliant temperature logging with ±0.5°C precision and automated expiration alerts tied to SKU-level tracking. Japan's METI guidelines and FDA food-safety standards drive certification costs, concentrating demand in corporate campuses and healthcare facilities willing to absorb higher equipment premiums.
- Snack Vending:Ambient-temperature spiral dispensing dominates unit economics with minimal sensor requirements.
- General Merchandise Vending:Locker-style configurations accommodate irregular SKU dimensions for electronics and personal care items.
Beverage vending leads volumes today; fresh food vending is gaining share fastest.
Technology:
Technology selection tracks operator business model: capital equipment sellers prioritize hardware differentiation while managed-service providers optimize for recurring telemetry revenue.
- Remote Monitoring:Cloud-connected telemetry modules transmit inventory levels, temperature excursions, and predictive maintenance alerts to operator dashboards. German deployments under GDPR data-localization rules favor edge-processing architectures that minimize cross-border data flows.
- Cashless Payment:EMV contactless and mobile wallet integration requires PCI-DSS certified payment terminals with encrypted transaction processing. Demand concentrates in United States airports and Japanese transit hubs where cashless penetration exceeds 85%.
- IoT Connectivity:Cellular and Wi-Fi modules enable real-time fleet management with over-the-air firmware updates.
- Touchscreen Interface:Android-based displays support dynamic pricing and personalized recommendations but inflate unit costs 30-40% over button interfaces.
Cashless payment leads installed base today; remote monitoring is expanding most quickly as operators shift toward SaaS revenue models.
End User:
End-user segmentation reflects traffic density patterns and labor-cost sensitivity rather than absolute footfall.
- Airports:High-dwell-time environments with 18-22 hour daily operation windows justify premium telemetry-enabled units. Germany's Frankfurt and Munich airports, Japan's Narita and Haneda, and United States hub airports are deploying smart dispensing systems fastest as concession operators seek minimal-staff retail models.
- Office Buildings:Landlord-specified amenity packages increasingly bundle coffee, fresh food, and retail automation under single-vendor facility management contracts. Premium towers in London and New York specify integrated platforms with grab-and-go checkout.
- Retail Outlets:Transportation-adjacent convenience stores and fuel stations deploy compact footprint units for extended-hours service.
- Schools:Nutritional compliance requirements and limited capital budgets favor basic mechanical dispensers with cashless retrofits.
Airports anchor premium system deployment; office buildings are absorbing connected platforms fastest through bundled procurement.
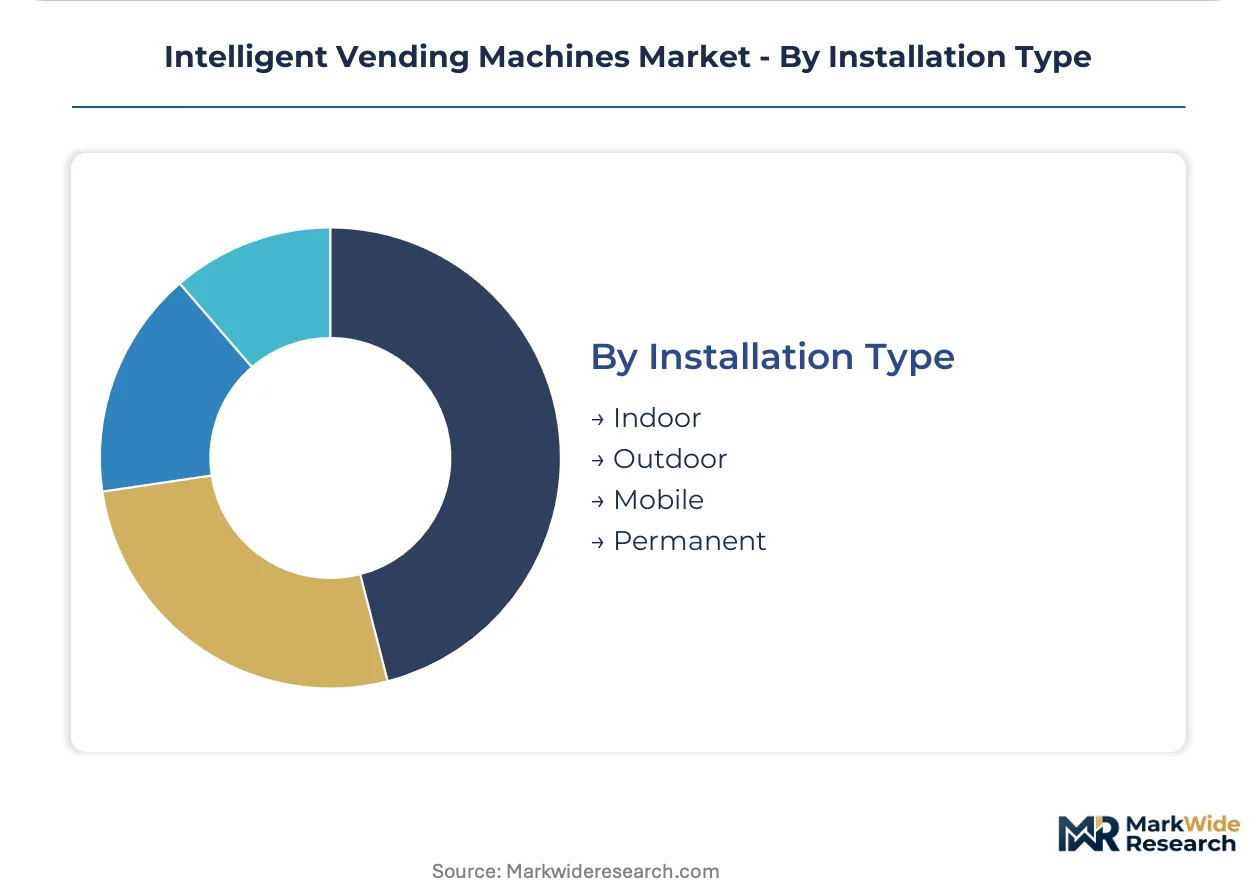
Installation Type:
Installation choices split between environmental protection requirements and relocation flexibility needs.
- Indoor:Climate-controlled environments enable standard IP20 enclosures with reduced sealing costs. United States and German retail channels favor indoor placement for electronics longevity and lower insurance premiums.
- Outdoor:IP65+ rated enclosures with heating elements for display visibility and corrosion-resistant finishes for coastal deployment. Japan's dense urban vending culture sustains outdoor installation rates unmatched elsewhere.
- Permanent:Anchored installations with hardwired power and data connections maximize uptime reliability.
- Mobile:Battery or generator-powered units on wheeled chassis serve event and construction-site markets with seasonal demand patterns.
Indoor installations dominate unit economics today; outdoor configurations are climbing fastest in urban transit corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Germany, Japan, and the United States anchor intelligent vending machine development, with each geography deploying distinct regulatory frameworks and infrastructure investment patterns that shape regional competitive dynamics.
United States
Airport concession operators drive premium system deployment across hub facilities in Atlanta, Dallas-Fort Worth, and Denver. FDA food-safety validation requirements extend product launch cycles for fresh-food platforms. Chicago O'Hare and Los Angeles International anchor the largest connected-fleet installations, with operators prioritizing cashless payment integration above 85% penetration rates.
Germany
Railway station retail expansion concentrates demand in Frankfurt, Munich, and Berlin transit corridors. EU AI Act conformity assessment procedures now apply to biometric age-verification interfaces, forcing firmware redesigns. The Rhine-Ruhr industrial cluster houses embedded controller manufacturing that supplies telemetry modules across European deployments.
Japan
Urban vending density sustains outdoor installation rates unmatched elsewhere, with Tokyo and Osaka metropolitan areas hosting millions of units. METI operational-technology guidelines constrain cloud data architectures, favoring edge-processing designs. Nagoya-based engineering centers refine refrigeration-efficient controllers for fresh-food applications in corporate campuses.
India
Metro corridor expansion in Delhi, Mumbai, and Bangalore creates underpenetrated installation bases for cashless-integrated units. Digital wallet penetration acceleration outpaces hardware deployment capacity. The National Capital Region attracts facility-management providers bundling vending under corporate amenity contracts.
United Kingdom
London premium office towers specify integrated amenity packages combining coffee, fresh food, and retail automation. GDPR data-localization rules favor edge-computing architectures that minimize cross-border data flows. The Southeast England logistics corridor supports spare-parts distribution for European fleet maintenance networks.
Intelligent Vending Machines Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the intelligent vending machine sector, with integrated manufacturers owning refrigeration and payment-system fabrication against specialists assembling third-party subsystems. The vendor base splits between diversified industrial conglomerates with captive component supply and focused vending-platform developers outsourcing controller and compressor sourcing. Three archetypes dominate: refrigeration-integrated industrials, payment-system specialists, and coffee-vending platform developers. Competitive moves concentrate on strategic partnerships for telemetry software licensing and geographic expansion through concession operator alliances.
Within the diversified industrial tier, Crane Co. and Fuji Electric Co., Ltd. exemplify capital-intensive positioning with integrated manufacturing footprints. Azkoyen Group occupies a specialized position among European platform developers. These three anchors demonstrate how scale-driven refrigeration capabilities, payment-system integration depth, and beverage-platform specialization respectively define viable competitive positions.
| Leading Market Players |
|---|
| Crane Co. |
| Azkoyen Group |
| FAS International S.p.A. |
| Bianchi Vending Group S.p.A. |
| N&W Global Vending S.p.A. |
| Rhea Vendors Group |
| Fuji Electric Co., Ltd. |
| Sanden Corporation |
| Seaga |
| Others |
Supply Flow & Price Mechanics
Edge computing architectures with localized AI inference are simultaneously compressing hardware margins and concentrating controller procurement among semiconductor fabricators capable of GDPR-compliant firmware integration. This technology shift forces manufacturers to absorb recurring certification costs while competing against basic mechanical dispensers in price-sensitive channels.
Pricing Analysis
The bundled-vs-unbundled service split separates equipment sellers from managed-service providers across the intelligent vending machine sector. Three-tier pricing structure across premium telemetry-enabled, standard cashless-integrated, and economy mechanical levels reflects certification grade and after-sales service bundling. Price differentiation stems from FDA food-safety validation tiers and remote monitoring SaaS attach rates. Pricing pressure intensifies in the economy tier as ARM-based controller shortages inflate production costs while buyers resist pass-through. Corporate facility-management buyers show lowest price sensitivity; emerging market transit operators exhibit highest.
Supply Chain Analysis
ARM-based controller supply rests on Taiwanese and South Korean semiconductor fabricators with secondary sourcing from Japanese specialty producers. Refrigeration compressors draw from Chinese and German industrial manufacturers; payment terminal modules source from United States and European PCI-DSS certified suppliers. Single-source vulnerability concentrates in embedded processor supply where geopolitical friction threatens allocation priority. Distribution runs through national vending operators and concession management companies with direct-to-fleet procurement emerging in airport and railway channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU AI Act compliance costs in Germany and France exceed India's regulatory burden by multiples, creating margin expansion for manufacturers with modular firmware architectures.
For Market Incumbents: Acquire telemetry software platforms to anchor recurring revenue streams against hardware margin erosion from mechanical dispenser substitution. Crane Co. and Fuji Electric Co., Ltd. should deepen backward integration into refrigeration compressor manufacturing to defend against Chinese cost competitors. Certification investment in FDA and METI dual compliance creates switching costs that protect installed base in premium channels.
For New Entrants and Emerging Players: Capture underpenetrated metro corridors in Delhi, Mumbai, and Bangalore where digital wallet penetration exceeds hardware deployment capacity. White-space targets include grab-and-go checkout architectures for corporate campuses and healthcare facilities with minimal incumbent presence. Partner with national facility-management providers rather than fragmented local operators to bypass channel establishment costs.
For Investors and Strategic Acquirers: Valuations sit cheapest among payment-system integration specialists lacking refrigeration manufacturing depth. The five-to-ten-year viability window favors asset-light designers with captive telemetry software licensing over capital-heavy integrated manufacturers facing semiconductor supply volatility. Watch ARM-based controller allocation priority shifts as the inflection signal for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Architecture Deployment | GDPR-compliant data residency reduces cross-border cloud costs for German railway operators. |
| Fresh-Food Cold-Chain Certification | FDA validation opens corporate campus and healthcare facility placement premiums. |
| Cashless Payment Terminal Integration | EMV contactless modules capture 85%-plus penetration in United States airports. |
| Telemetry SaaS Platform Licensing | Recurring fleet management fees displace capital equipment margin dependence. |
| Grab-and-Go Checkout Convergence | Computer vision and weight-sensor fusion enables frictionless retail in premium office buildings. |
Methodological Framework
Multiple input streams — executive interviews with vending fleet operators, technical discussions with embedded controller manufacturers, and regulatory consultations with EU AI Act compliance specialists — were reconciled against secondary validation from FDA 510(k) filings, METI operational-technology guideline publications, and customs records for refrigeration compressor trade flows. Bottom-up unit economics modeling across airport, office building, and transit corridor deployments was triangulated with top-down market sizing from concession operator contract disclosures and facility-management procurement databases.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type (beverage, fresh food, snack, general merchandise), technology tier (remote monitoring, cashless payment, IoT connectivity, touchscreen interface), and end-user channel (airport, office building, retail outlet, school). CAGRs were derived from installed base growth rates and average revenue per unit trajectories, incorporating ARM-based controller supply constraints and EU Green Deal efficiency mandate compliance timelines as industry-specific forecast inputs.
Semiconductor fabrication bottlenecks, GDPR data-localization enforcement intensity, and fresh-food cold-chain liability litigation are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about telemetry module adoption curves and cashless payment penetration rates across geographies. A small set of named triggers — controller allocation priority shifts, biometric age-verification regulatory rulings, and corporate procurement bundling velocity — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Europe AUV and ROV Market
Robotics and Automation
Europe Underwater Robotics Market
Robotics and Automation
Smart Lawn Robot Market
Robotics and Automation
Robotic Tool Changer Market
Robotics and Automation
Healthcare Mobile Robots Market
Robotics and Automation
North America Robotics and Automation Actuators Market
Robotics and Automation
North America Underwater Robotics Market
Robotics and Automation
Global Robot Kitchen Market
Robotics and Automation
Middle East and Africa Medical Robots Market
Robotics and Automation
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market
Robotics and Automation
Robot Market
Robotics and Automation
Service Robotics Market
Robotics and Automation
Soft Exoskeleton Market
Robotics and Automation
North America Collaborative Robots Market
Robotics and Automation
Industrial Robotics Market
Robotics and Automation
Cyber-Physical System Market