
 Robotics Technology Market | 2026-2036
Robotics Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Robotics Technology Market Intelligence
Market Dynamics
Direct-to-factory distribution is fragmenting as regional system integrators bypass traditional distributors to source collaborative robots and mobile platforms directly from manufacturers. ABB leverages its European service network to sustain aftermarket revenue streams alongside new unit sales. FANUC anchors its competitive stance through captive production of servo motors and controllers in Japan. Nvidia competes by supplying GPU-accelerated perception stacks that power third-party autonomous navigation systems.
Technology and Segmentation
Robotics technology encompasses electromechanical systems integrating actuators, sensors, control architectures, and software algorithms to perform physical tasks with programmable autonomy, typically operating at positional accuracies below 0.1 millimeter in industrial configurations. The primary purpose spans repetitive manufacturing operations, hazardous material handling, precision surgery assistance, and autonomous logistics fulfillment. Industrial robots occupy the largest installed base across automotive and electronics assembly, while collaborative robots represent the fastest-expanding category as force-limited designs penetrate small-batch manufacturing without safety fencing. AI and machine learning segments command premium pricing as vision-guided picking and predictive maintenance modules displace rule-based programming.
Regulatory Environment
ISO 10218 and the EU AI Act establish conformance baselines for robot safety and algorithmic transparency in European deployments, while OSHA guidelines govern workplace robot integration in the United States. China's MIIT issues GB standards for industrial robot reliability testing that manufacturers must satisfy for domestic procurement tenders. Stakeholders must monitor divergence between regional certification regimes as export compliance costs escalate for multi-market platform vendors.
Market Dynamics
Direct-to-factory procurement is fragmenting traditional distribution channels as regional system integrators in China's Yangtze River Delta and Germany's automotive belt source collaborative robots and autonomous mobile platforms directly from manufacturers, bypassing conventional distributors entirely.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for autonomous mobile platforms are accelerating replacement cycles in European logistics operations as operators upgrade to certified systems.
- Electronics assembly automation:Shenzhen-based battery production lines are deploying force-limited collaborative robots for small-batch manufacturing without safety fencing, expanding addressable tasks.
- Servo motor controller integration:Tighter coupling between motion control hardware and perception software is reducing commissioning time for new robotic workcells.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium sourcing dependency on Chinese processing facilities creates input cost volatility for high-torque actuator production.
- ISO 10218 certification timelines:Extended safety validation periods for collaborative robot deployments are delaying revenue recognition for system integrators.
- Vision system substitution:Low-cost 2D camera arrays paired with open-source software are displacing proprietary 3D sensing modules in basic pick-and-place applications.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for electronics and automotive sectors are creating first-mover advantages for robot vendors establishing local assembly.
- 5G-enabled edge computing convergence:Ultra-low latency wireless networks combined with GPU-accelerated perception stacks are enabling cloud-orchestrated robot fleets in warehouse environments.
- Japan's METI carbon neutrality roadmap:Energy efficiency mandates for industrial facilities are driving retrofit demand for lighter, lower-power collaborative robots.
Industry Challenges
- Multi-axis motion programming expertise:Shortage of technicians capable of integrating kinematic chains with force-torque sensing is constraining deployment velocity.
- Legacy PLC interoperability:Proprietary communication protocols in existing factory automation infrastructure are complicating robot controller integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotics Technology Market |
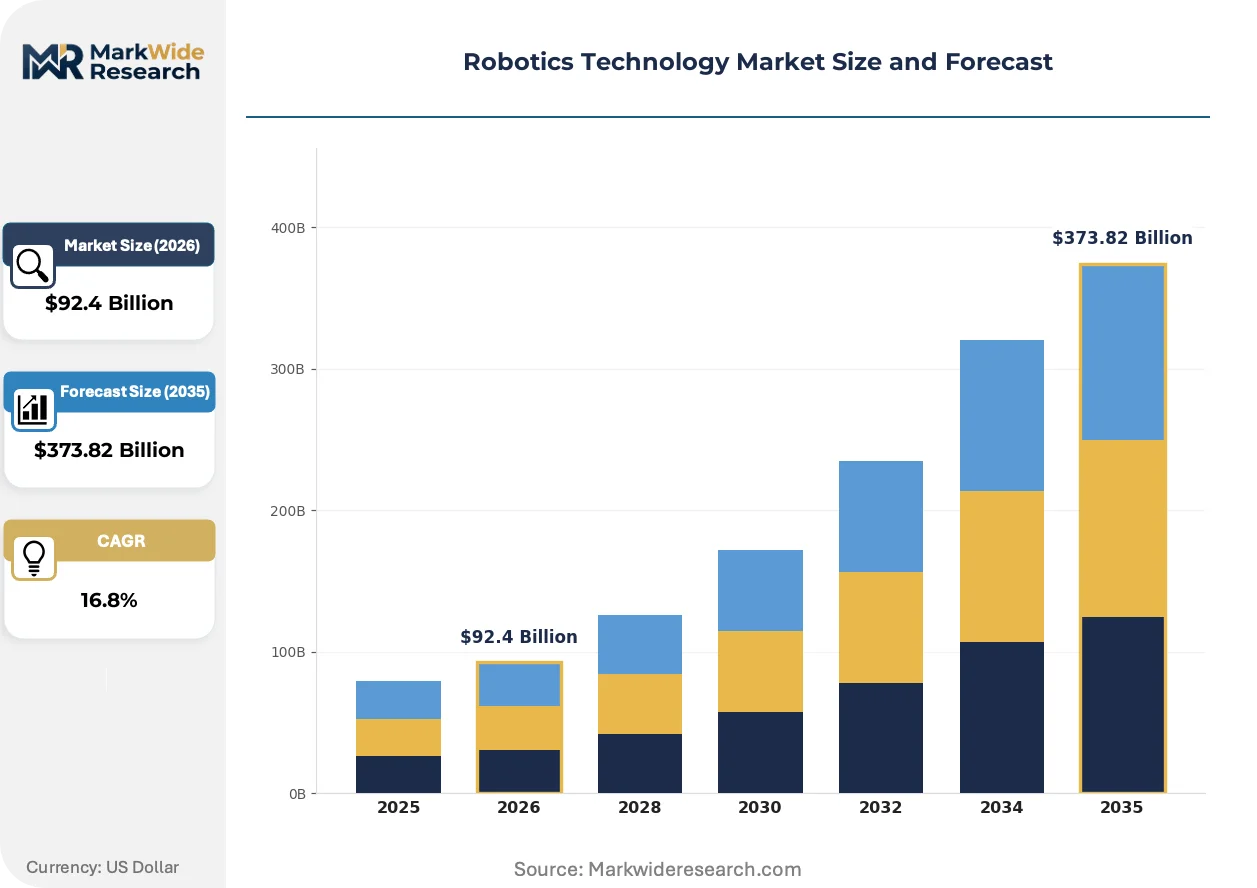
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $373.82 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Robots, Service Robots, Collaborative Robots, Mobile Robots Technology: AI, Machine Learning, Control Systems, Sensor Technology Application: Manufacturing, Healthcare, Logistics, Agriculture End User: OEMs, System Integrators, Enterprises, Research Institutions |
| Companies Covered | ABB, FANUC, Yaskawa Electric Corporation, KUKA AG, Universal Robots, Nvidia, Tesla, UBTECH Robotics, Beijing Roborock Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotics Technology Market Strategic Shifts & Innovations
Force-limited collaborative architectures and AI-driven perception modules are compressing the traditional boundary between industrial automation and human-occupied workspaces, enabling new deployment models that were previously excluded by safety requirements.
Deep learning-based vision guidance is collapsing the historical trade-off between robotic speed and adaptability. Automotive OEMs in Germany and Japan are deploying these systems for bin-picking unstructured components. The technology is collapsing cycle time variance that previously mandated dedicated feeding mechanisms.
The EU AI Act's risk classification framework for autonomous systems is mandating algorithmic documentation and human oversight protocols for mobile robots operating in public-adjacent logistics corridors. Warehouse operators in the Netherlands and France are restructuring fleet management software to satisfy conformity assessment requirements. High-velocity e-commerce fulfillment centers face the steepest compliance cost escalation.
Factory operators are unbundling after-sales service contracts from initial equipment purchases, pressuring OEMs to compete on transparent hourly maintenance rates rather than bundled lifecycle pricing. German automotive suppliers and Japanese electronics assemblers are driving this shift through competitive tender processes. The Yangtze River Delta manufacturing corridor exhibits the most aggressive unbundling behavior.
Robotics Technology Market Segmentation
Robotics technology segments exhibit divergent replacement cycles that reshape procurement patterns. Industrial robots operate on decade-long depreciation schedules while AI modules face 18-month obsolescence pressures. Understanding these temporal dynamics enables vendors to align R&D pipelines with revenue recognition timing.
Product Type:
Cycle times stretch from five-year collaborative robot refreshes to fifteen-year industrial robot installations, creating asynchronous revenue windows across hardware categories.
- Industrial Robots:Heavy-duty articulated arms with six-axis kinematic chains deliver sub-0.1 millimeter repeatability for automotive welding and paint operations. German OEMs in Stuttgart and Wolfsburg anchor demand as electrification transitions force production line reconfigurations.
- Collaborative Robots:Force-limited designs with power and force limiting (PFL) compliance enable fenceless human-robot collaboration. Shenzhen battery manufacturers and Japan's precision electronics assemblers drive fastest uptake as small-batch flexibility outweighs cycle time penalties.
- Service Robots:Autonomous units perform non-industrial tasks including cleaning, surveillance, and hospitality delivery.
- Mobile Robots:Autonomous mobile platforms navigate warehouse corridors using LiDAR and vision fusion for inventory transport.
Industrial robots anchor the volume base while collaborative robots gain share at the steepest rate.
Technology:
Cost tiers separate premium perception stacks from commoditized control hardware, with GPU-accelerated modules commanding multiples over legacy PLC architectures.
- AI:Deep learning frameworks enable real-time object recognition and adaptive motion planning without explicit programming. Netherlands logistics operators deploying EU AI Act-compliant fleets drive replacement demand as algorithmic documentation mandates tighten.
- Machine Learning:Predictive maintenance modules analyze vibration and current signatures to forecast actuator failures before unplanned downtime occurs. German automotive suppliers prioritize these capabilities to minimize line stoppage costs.
- Control Systems:Real-time operating systems coordinate multi-axis motion with deterministic latency guarantees.
- Sensor Technology:Tactile, proximity, and vision sensors provide environmental awareness for closed-loop operation.
Control systems anchor the volume base while AI gains share at the steepest rate.
Application:
Customer type segmentation reveals divergent procurement authority, with system integrators controlling specification decisions even when enterprises hold budget authority.
- Manufacturing:Assembly, material handling, and quality inspection operations dominate robot deployment density. China's Yangtze River Delta electronics corridor and Japan's automotive belt concentrate installed base as labor cost arbitrage fades against automation economics.
- Logistics:E-commerce fulfillment centers deploy high-velocity picking and sortation systems. France and Netherlands warehouse operators face steepest EU AI Act compliance cost escalation for autonomous mobile platforms.
- Healthcare:Surgical assistance and rehabilitation applications demand ISO 13482 safety conformance.
- Agriculture:Precision harvesting and crop monitoring systems address seasonal labor scarcity.
Manufacturing anchors the volume base while logistics gains share at the steepest rate.
End User:
Supply concentration among Japanese servo motor manufacturers and Chinese rare earth processors shapes procurement risk profiles across buyer categories.
- OEMs:Original equipment manufacturers specify robot architectures for integration into capital equipment. Germany's automotive OEMs and Japan's electronics manufacturers drive standardization through captive engineering specifications.
- System Integrators:Regional specialists commission workcells and assume deployment risk. Yangtze River Delta integrators increasingly bypass distributors to source directly from manufacturers, fragmenting traditional channels.
- Enterprises:End-user manufacturers operate robot fleets directly without integrator intermediation.
- Research Institutions:Universities and national laboratories prototype next-generation architectures.
System integrators anchor the volume base while OEMs gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese servo motor supply chains while Chinese rare earth processing dominance compresses margins for European actuator assemblers. Germany's automotive OEMs absorb premium costs for precision components. Shenzhen integrators exploit direct sourcing to undercut distributor markups by double-digit percentages.
China
Shenzhen battery manufacturers and Yangtze River Delta electronics assemblers drive collaborative robot demand for small-batch production without safety fencing. MIIT's GB standards for industrial robot reliability testing gate domestic procurement tenders. The Pearl River Delta cluster concentrates system integrators bypassing traditional distribution channels to source directly from manufacturers.
Germany
Stuttgart and Wolfsburg automotive OEMs deploy force-limited robots for final assembly tasks amid electrification-driven production line reconfigurations. The EU AI Act's algorithmic transparency mandates accelerate replacement cycles for autonomous mobile platforms in logistics corridors. Bavaria's precision engineering belt anchors demand for sub-0.1 millimeter repeatability systems.
Japan
Precision electronics assemblers and automotive suppliers prioritize predictive maintenance modules to minimize unplanned line stoppages. METI's carbon neutrality roadmap for industrial facilities drives retrofit demand for lighter, lower-power collaborative robots. The Nagoya-Toyota manufacturing corridor concentrates captive servo motor and controller production.
United States
E-commerce fulfillment centers deploy high-velocity picking systems as labor cost arbitrage fades against automation economics. OSHA workplace robot integration guidelines govern collaborative deployments without safety fencing. The Midwest automotive belt and Southeast logistics hubs concentrate warehouse automation investment.
India
Electronics and automotive sectors absorb production-linked incentive schemes to establish local robot assembly operations. The central bank's manufacturing credit facilities support capital equipment procurement for first-mover integrators. Maharashtra and Gujarat industrial corridors concentrate PLI-scheme beneficiaries scaling collaborative workcells.
Robotics Technology Market Key Industry Players
Industrial incumbents and AI-native entrants split the market into vertically integrated hardware specialists and perception-stack licensors. Consolidation concentrates around Japanese servo manufacturers and Chinese rare earth processors, with European system integrators occupying fragmented mid-tier positions. Two archetypes dominate: captive component producers controlling upstream supply, and software-layer vendors monetizing GPU-accelerated navigation algorithms. Competitive moves center on backward integration into magnet processing and strategic partnerships for 5G-enabled fleet orchestration.
Among established industrial automation groups, ABB leverages its European service network to sustain aftermarket revenue alongside new unit sales, while FANUC anchors competitive positioning through captive production of servo motors and controllers in Japan. Nvidia occupies the AI acceleration tier, supplying GPU-based perception stacks that power third-party autonomous navigation systems without direct robot manufacturing exposure.
| Leading Market Players |
|---|
| ABB |
| FANUC |
| Yaskawa Electric Corporation |
| KUKA AG |
| Universal Robots |
| Nvidia |
| Tesla |
| UBTECH Robotics |
| Beijing Roborock Technology |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta freight corridor's container cost dynamics expose how Chinese rare earth processing concentration enables upstream price control, while downstream buyers in Germany and Japan face widening spreads between standard catalog robots and configured-to-order precision systems.
Pricing Analysis
The customization-premium spread separates configured-to-order collaborative robots with force-torque sensing integration from standard six-axis arms sold through distributor channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under ISO 10218 and EU AI Act compliance tiers. Price erosion runs through the economy tier as Shenzhen-based integrators source direct from manufacturers, bypassing traditional markup layers. System integrators in China's manufacturing belt exhibit highest price sensitivity, while German automotive OEMs absorb premiums for sub-0.1 millimeter repeatability specifications.
Supply Chain Analysis
Upstream feedstock for high-torque actuators draws from Chinese neodymium and dysprosium processing facilities, Japanese servo motor manufacturing clusters, and German precision gearbox producers. Raw material dependencies span rare earth magnets, high-grade copper windings, and silicon carbide power semiconductors. Single-source vulnerability concentrates in Chinese rare earth refining capacity, where export licensing shifts create input cost volatility. Distribution runs through direct manufacturer relationships with regional system integrators, fragmenting traditional distributor networks in the Yangtze River Delta and Germany's automotive belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The robotics market functions as a service-attach opportunity where predictive maintenance software and hourly maintenance contracts expand faster than hardware unit sales, driven by German automotive suppliers and Japanese electronics assemblers unbundling lifecycle pricing.
For Market Incumbents: Build captive servo motor production moats to insulate margin structures from rare earth magnet volatility. ABB's European service network model demonstrates how aftermarket revenue streams offset new unit pricing pressure. Integrate backward into magnet processing partnerships or secure long-term offtake agreements with Chinese refiners. ISO 10218 certification investment creates switching costs that defend against low-cost vision system substitutes. For New Entrants and Emerging Players: India's Maharashtra and Gujarat industrial corridors underpenetration by established collaborative robot vendors creates first-mover windows under PLI scheme incentives. Target battery production line integrators in Shenzhen seeking force-limited architectures without safety fencing. Deploy GPU-accelerated perception stacks as software-layer entry points, licensing navigation algorithms rather than manufacturing hardware. Cloud-orchestrated fleet management for 5G-enabled warehouse environments offers lowest capital barrier to scale. For Investors and Strategic Acquirers: Perception-stack specialists with GPU-accelerated navigation algorithms represent the highest-conviction acquisition archetype as autonomous mobile platform demand accelerates under EU AI Act compliance mandates. Long-term viability centers on software recurring revenue attachment rates rather than hardware shipment volumes. Monitor algorithmic documentation audit pass rates as the inflection signal separating compliant fleet operators from replacement-cycle casualties in Netherlands and France logistics corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Processing | Captive magnet supply secures cost predictability for high-torque actuator production against Chinese export licensing shifts. |
| EU AI Act Compliance Certification Investment | Algorithmic documentation capabilities unlock Netherlands and France logistics fleet replacement cycles ahead of enforcement deadlines. |
| 5G-Enabled Fleet Orchestration Platform Launch | Ultra-low latency wireless integration enables cloud-managed robot fleets for high-velocity e-commerce fulfillment centers. |
| Predictive Maintenance Software Companion Development | Vibration and current signature analytics reduce unplanned downtime for German automotive suppliers prioritizing line continuity. |
| Direct-to-Integrator Distribution Channel Expansion | Bypassing traditional distributors captures margin compression opportunities in Yangtze River Delta electronics manufacturing corridors. |
Research Approach
Desk research of trade customs data, MIIT GB standard filings, and EU regulatory guidance documents preceded structured interviews with plant engineers at German automotive OEMs, system integrators in Shenzhen, aftermarket service heads at Japanese manufacturers, and procurement leads at Netherlands logistics operators. Secondary validation drew from SEC filings of listed automation groups, ISO certification registries, and production statistics from national manufacturing associations. Bottom-up unit shipment estimates triangulated against top-down value projections across hardware and software revenue streams.
Assumption sets held fixed the EU AI Act enforcement trajectory and Chinese rare earth export licensing regimes, while varying electrification-driven production line reconfiguration intensity and 5G network deployment pace across warehouse corridors. Segmentation dimensions modeled include robot kinematic architecture, AI module integration depth, end-use application density, and regional regulatory compliance cluster. CAGRs were derived from installed base growth rates adjusted for replacement cycle compression in collaborative categories and extension in industrial arm installations. Forecast inputs incorporated servo motor lead time fluctuations and GPU availability constraints for perception stack production.
Practitioners should monitor EU AI Act audit failure rates, Chinese rare earth export quota announcements, and 5G private network deployment timelines for early signals requiring forecast revision. Cross-checking against IHS Markit industrial automation shipment data and national robotics association membership growth is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Entertainment Robots Market
Robotics and Automation
Consumer Robotics Market
Robotics and Automation
Thailand Cloud Robotics Market
Robotics and Automation
Airport Robots Market
Robotics and Automation
Inspection Robots Market
Robotics and Automation
Autonomous Navigation Robots Market
Robotics and Automation
Europe AUV and ROV Market
Robotics and Automation
Top Robotics Market
Robotics and Automation
Global Underwater Robotics Market
Robotics and Automation
Robot As a Service Market
Robotics and Automation
Gantry (Cartesian) Robot Market
Robotics and Automation
Healthcare Assistive Robot Market
Robotics and Automation
Automated Plate Handlers Market
Robotics and Automation
Global Robot Kitchen Market
Robotics and Automation
Asia-Pacific Logistics Robotics Market
Robotics and Automation
Medical Automation Technologies Market