
 Europe Warehouse Robotics Market | 2026-2036
Europe Warehouse Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Warehouse Robotics Market Foresight
Buyer concentration in European e-commerce is decoupling from traditional retail distribution patterns, with fulfillment networks fragmenting across specialized logistics providers and direct-to-consumer brands. Dematic leverages its deep integration with grocery and fashion supply chains to sustain project throughput across Northern Europe. Swisslog anchors automated pharmaceutical warehousing through its pharmacy-focused robotic systems. KION Group AG competes across forklift-to-robot transitions, extending its industrial truck installed base into automated guided vehicle conversions.
Warehouse robotics encompasses electromechanical systems designed for material transport, sortation, and manipulation within enclosed storage and distribution facilities, typically operating on load capacities from 50 kg to 1,500 kg and navigation accuracies within ±10 mm for dense racking environments. Autonomous mobile robots navigate without fixed infrastructure, enabling rapid reconfiguration of fulfillment layouts that static conveyor systems cannot match. Robotic arms in picking applications remain technically immature for unstructured SKU environments, concentrating margin pools in vision-guided piece-picking subsystems where AI and RTLS convergence creates performance differentiation. Mobile robots lead volume deployment, though order fulfillment as an application segment captures disproportionate value relative to its hardware footprint due to software orchestration premiums.
The EU AI Act imposes risk-classification requirements on AI-enabled vision systems in warehouse robotics, compelling manufacturers to document algorithmic transparency and human oversight protocols before CE marking. REACH and RoHS constrain battery chemistry and electronic component sourcing, particularly for lithium-based power systems in mobile robot fleets. The F-Gas Regulation phases down hydrofluorocarbon use in cold-chain warehouse climate control, indirectly affecting robot operating environment specifications. Stakeholders must monitor how the EU Green Deal's embodied carbon reporting rules under CSRD reshape procurement criteria for robotics hardware across European distribution networks.
Market Dynamics
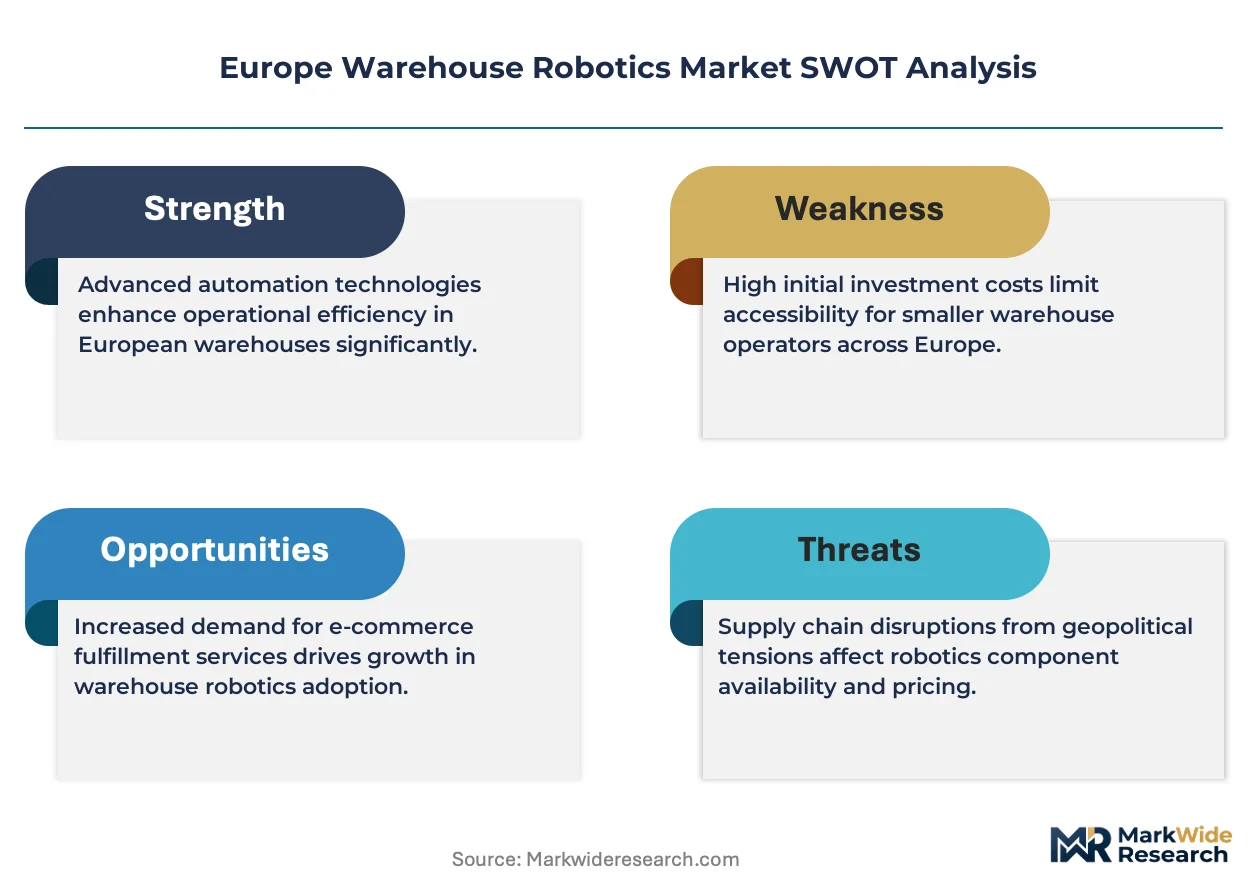
The EU AI Act's risk-classification framework is forcing warehouse robotics OEMs to reengineer vision systems documentation before CE marking, compressing product development timelines while fragmenting compliance costs across mid-tier suppliers.
Growth Catalysts
- Rotterdam-Antwerp logistics corridor density:Europe's largest container port cluster generates concentrated demand for autonomous mobile robots in cross-dock operations, with throughput requirements exceeding 15 million TEU annually.
- EU Green Deal procurement criteria:Corporate Sustainability Reporting Directive rules on embodied carbon are redirecting capital toward energy-efficient robotic fleets in German and Dutch distribution centers.
- Pharmaceutical cold-chain expansion:Temperature-controlled warehousing for biologics is accelerating adoption of climate-resilient automation in Belgium and Switzerland.
Market Restraints
- Lithium supply concentration:Battery chemistry constraints under REACH and RoHS create dependency on limited European cell suppliers, inflating mobile robot power system costs.
- F-Gas Regulation phase-down:Hydrofluorocarbon restrictions in warehouse climate control are raising retrofit costs for cold-chain robot deployments.
- Vision system maturity gaps:Unstructured SKU picking remains technically unviable for fashion and grocery assortments, limiting addressable application scope.
Strategic Opportunities
- Polish e-commerce fulfillment:Underpenetrated Central European logistics networks offer first-mover positioning for autonomous mobile robot vendors outside the Rhine-Ruhr corridor.
- AI-RTLS convergence:Real-time location systems fused with machine learning enable dynamic slotting optimization in high-velocity French apparel distribution.
- EU AI Act transparency mandates:Algorithmic documentation requirements create service revenue streams for compliance consulting around CE marking pathways.
Industry Challenges
- Mechatronics talent scarcity:Shortages of robotics integration engineers in the Netherlands and Germany are extending deployment timelines for multi-vendor fleet orchestration.
- Legacy WMS interoperability:Proprietary warehouse management systems in established Northern European facilities resist API standardization, complicating robot fleet software integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Warehouse Robotics Market |
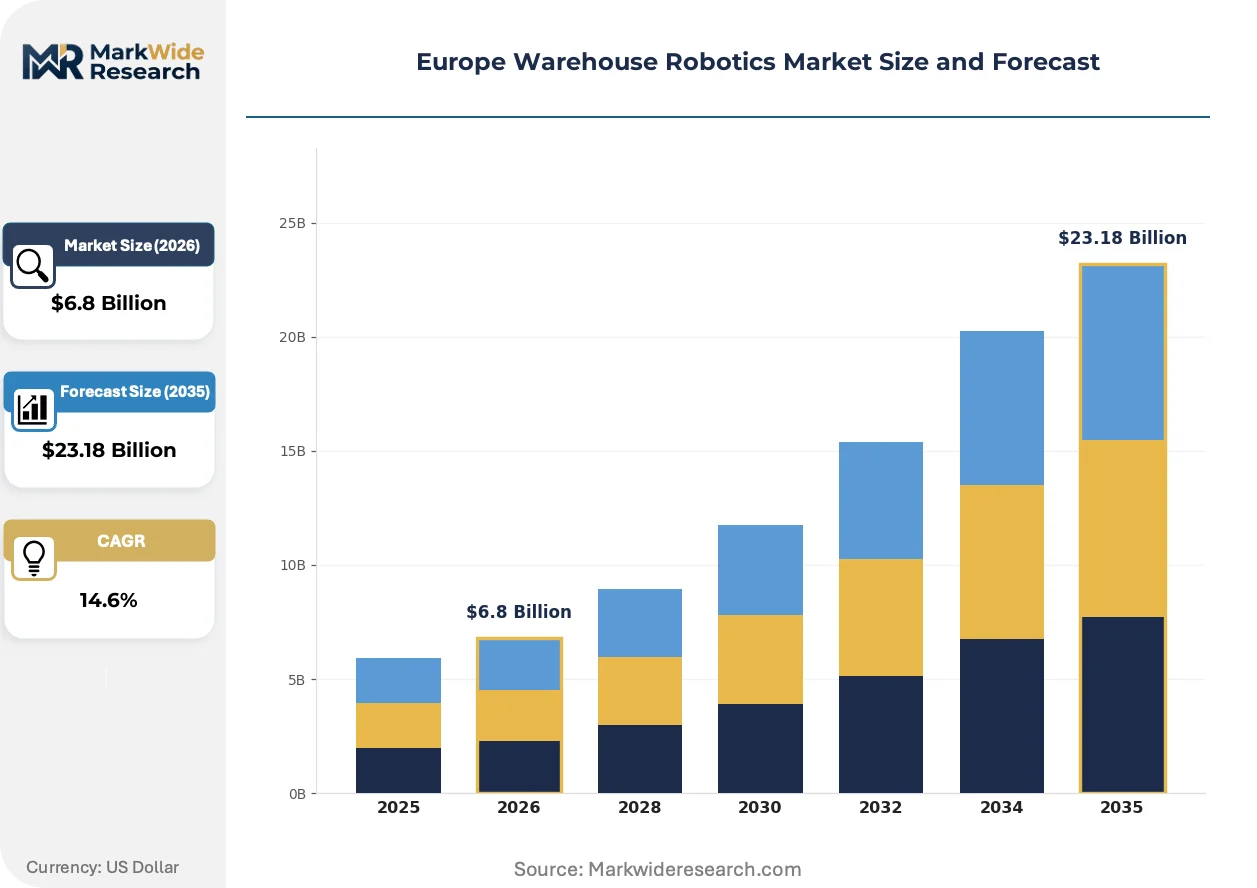
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $23.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Robots, Automated Guided Vehicles, Autonomous Mobile Robots, Robotic Arms End User: E-Commerce, Retail, Manufacturing, Logistics Technology: RTLS, Vision Systems, AI, IoT Application: Order Fulfillment, Inventory Management, Picking, Packaging |
| Companies Covered | Dematic, Swisslog, SSI Schaefer AG, Vanderlande, KNAPP AG, KUKA AG, ABB Ltd., KION Group AG, Swisslog Holding AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Warehouse Robotics Market Shifts & Advancements
Three distinct vectors are reconfiguring competitive advantage in European warehouse robotics: vision-AI convergence, regulatory documentation burdens, and procurement model fragmentation toward robotics-as-a-service structures.
Machine vision for piece-picking is converging with edge computing architectures to reduce latency in SKU identification. German grocery fulfillment centers are piloting these systems for produce handling. This compression of decision-making to the device level is converging with 5G private network deployments to enable sub-100ms response times in dense racking environments.
REACH substance restrictions on lithium-ion battery chemistries are tightening material sourcing requirements for mobile robot fleets. Manufacturers must now document full supply chain provenance for electrolyte salts and cathode materials. Polish and Hungarian assembly plants are most affected, with several operators accelerating solid-state battery evaluation programs to preempt 2027 compliance deadlines.
Capital deployment preferences among third-party logistics providers are rotating away from outright robot ownership toward performance-based fleet contracts. Dutch fashion distributors are leading this shift, unbundling hardware procurement from software orchestration and maintenance obligations. This reconfiguration is most visible in the Benelux corridor, where specialized robotics fleet managers are displacing traditional system integrators in contract negotiations.
Europe Warehouse Robotics Market Segmentation
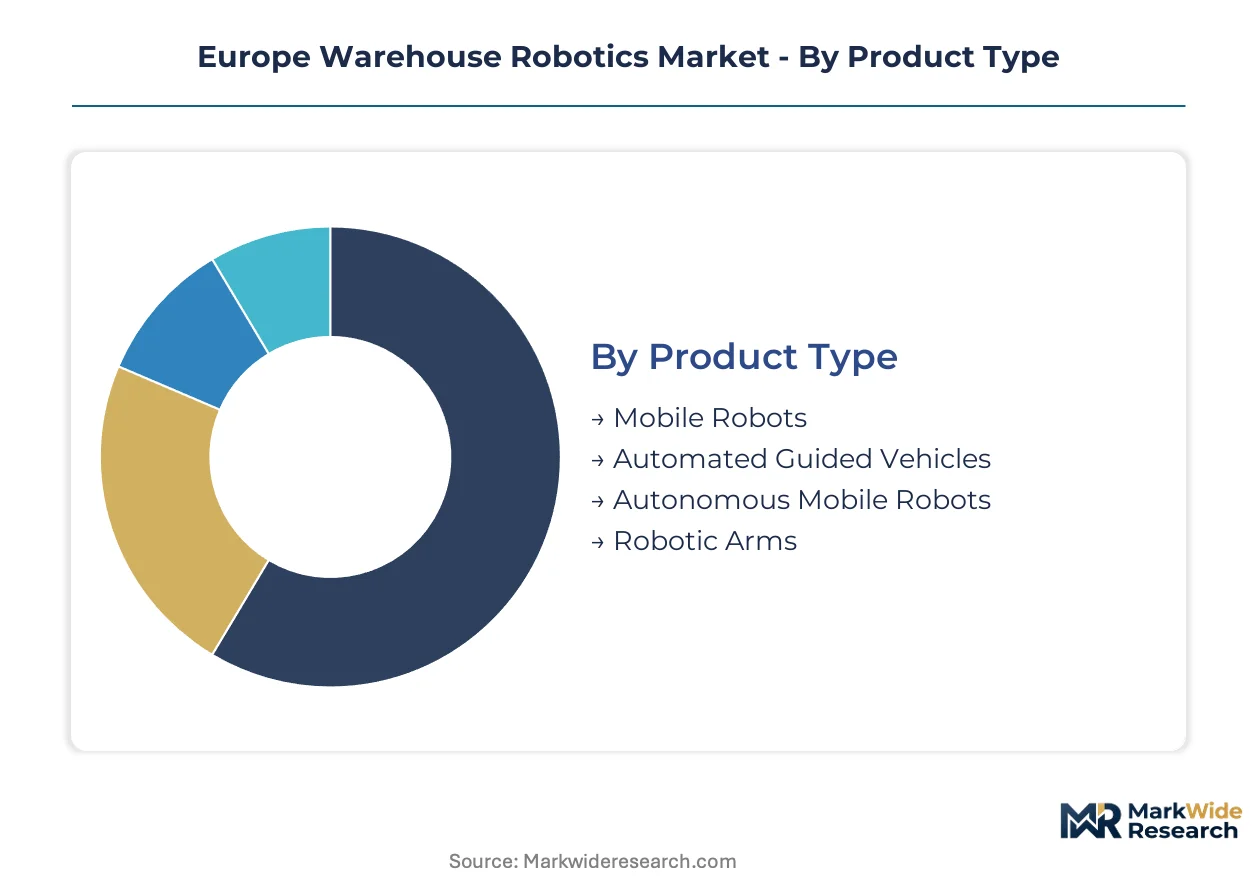
Segmentation in European warehouse robotics reveals how hardware categories, software layers, and use-case combinations create distinct margin profiles. Product type determines capital intensity and deployment velocity, while technology integration depth separates standalone systems from embedded intelligence architectures.
Product Type:
Standalone mobile platforms dominate initial automation investments, whereas embedded robotic subsystems require deeper facility integration and longer commissioning cycles.
- Mobile Robots:Battery-powered autonomous units navigate dynamic warehouse floors without fixed infrastructure, typically handling 50-150 kg payloads. German e-commerce fulfillment centers deploy these for rapid layout reconfiguration during seasonal demand spikes.
- Automated Guided Vehicles:Wire-guided or magnetic-tape-dependent transport systems follow predetermined paths with high repeatability. Dutch port logistics clusters favor AGVs for container yard movements where route predictability exceeds flexibility requirements.
- Autonomous Mobile Robots:Sensor-fusion navigation enables obstacle avoidance and collaborative operation alongside human workers. French pharmaceutical distributors prioritize AMRs for cleanroom-compliant material handling.
- Robotic Arms:Articulated manipulators execute pick-and-place operations in structured environments. Belgian grocery fulfillment pilots these for case-level depalletizing where SKU variability remains constrained.
Volume placements concentrate in mobile robots and AGVs; the faster expansion belongs to autonomous mobile robots as software-defined navigation displaces fixed-path alternatives.
End User:
Customer archetypes differ in fleet scale, uptime requirements, and in-house technical capabilities, shaping vendor engagement models across Northern Europe.
- E-Commerce:Direct-to-consumer fulfillment networks demand high-velocity SKU handling with extreme seasonality. Polish distribution centers are emerging as deployment hotspots for automated sortation systems serving Central European delivery networks.
- Retail:Omnichannel grocery and fashion retailers operate hybrid facilities combining store replenishment with online order picking. Swiss cold-chain automation for perishables exemplifies temperature-resilient robotic specifications.
- Manufacturing:Production-integrated warehousing requires synchronization with assembly line cadence. German automotive suppliers employ AGVs for just-in-sequence component delivery to final assembly.
- Logistics:Third-party providers operate multi-tenant facilities serving fragmented shipper bases. Rotterdam's port-centric 3PLs drive dense AMR fleets for cross-dock consolidation.
Capital deployment skews toward e-commerce; manufacturing applications are climbing the fastest as production reshoring intensifies intralogistics automation.
Technology:
Technology layers stack from location-awareness foundations through perceptual intelligence to orchestration platforms, with integration depth determining system autonomy levels.
- RTLS:Real-time location systems anchor fleet coordination through UWB, BLE, or RFID triangulation. Dutch fashion distributors leverage RTLS-AMR fusion for dynamic slotting optimization in high-velocity environments.
- Vision Systems:Camera arrays and depth sensors enable object recognition and quality inspection. EU AI Act compliance documentation is compressing development timelines for vision-guided piece-picking subsystems.
- AI:Machine learning models optimize path planning, demand forecasting, and predictive maintenance. Edge computing compression reduces latency for German grocery produce handling pilots.
- IoT:Sensor networks monitor equipment health, environmental conditions, and energy consumption. CSRD-aligned embodied carbon reporting is redirecting procurement toward IoT-enabled fleet efficiency analytics.
RTLS and vision systems capture current installation volume; AI integration is gaining share fastest as algorithmic transparency mandates create service revenue adjacencies.
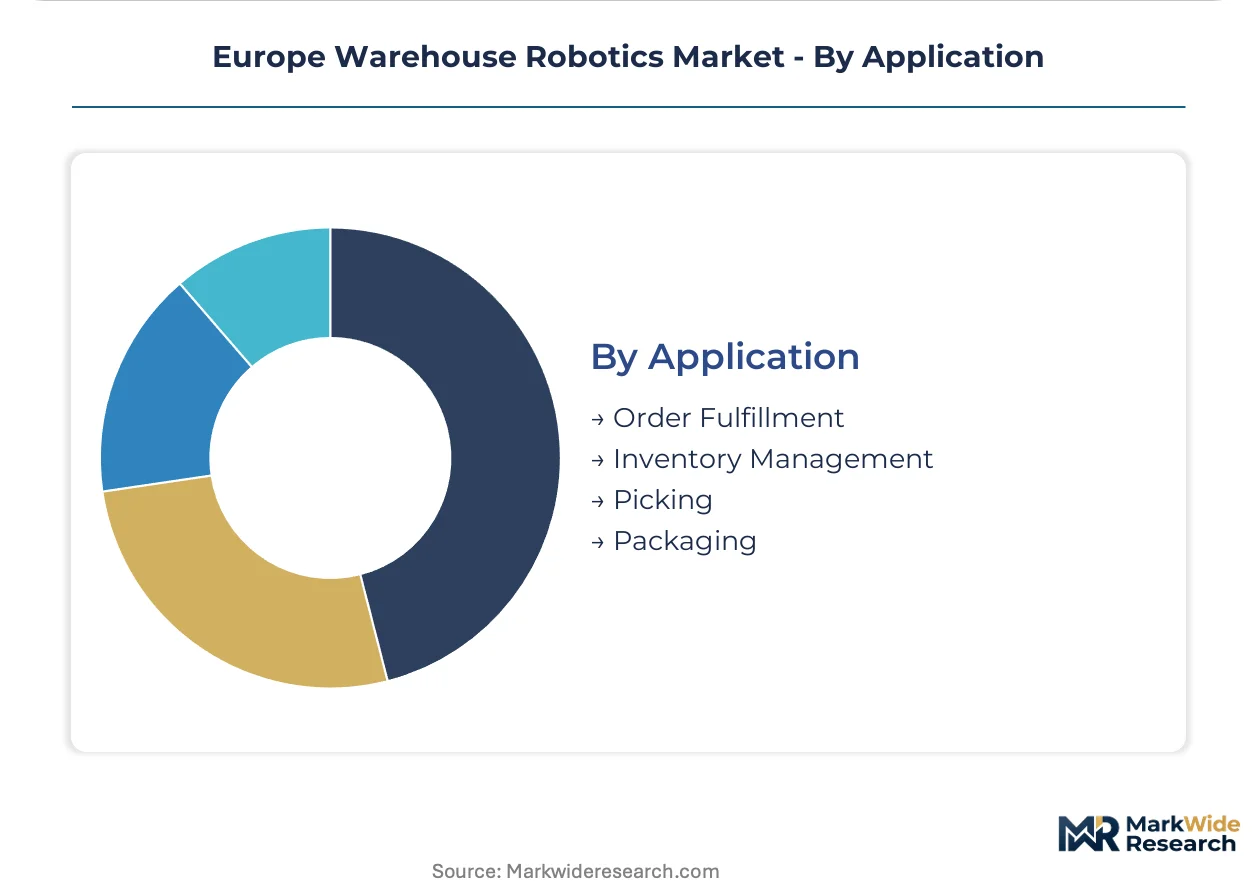
Application:
Functional use cases span the inbound-to-outbound workflow, with automation maturity varying sharply across handling complexity tiers.
- Order Fulfillment:Complete customer order assembly combines picking, consolidation, and shipping preparation. Benelux fashion distributors unbundle hardware from software orchestration through performance-based fleet contracts.
- Inventory Management:Cycle counting, replenishment triggering, and stock location optimization. German pharmaceutical warehouses deploy autonomous drones for high-bay inventory verification.
- Picking:Item-level retrieval from storage locations remains technically challenging for unstructured assortments. Vision-AI convergence is narrowing viability gaps for fashion and grocery SKU environments.
- Packaging:Automated carton selection, void fill, and label application complete shipment preparation. Belgian e-commerce hubs prioritize packaging automation for labor cost reduction in last-mile preparation.
Order fulfillment commands the largest installed base; picking applications are expanding most quickly as vision system maturity unlocks previously inaccessible SKU categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for warehouse robotics clusters along the Rhine corridor and North Sea port systems, with capital deployment tracking logistics infrastructure density rather than national GDP distribution.
Germany
E-commerce fulfillment centers in the Rhine-Ruhr and Bavaria regions drive autonomous mobile robot procurement for seasonal peak handling. The EU AI Act's risk-classification framework compels OEMs to document algorithmic transparency before CE marking. Stuttgart's automotive supplier networks employ AGVs for just-in-sequence component delivery to assembly lines.
Netherlands
Rotterdam's port logistics cluster generates Europe's densest AMR deployment for cross-dock operations exceeding 15 million TEU annually. CSRD rules on embodied carbon redirect procurement toward energy-efficient robotic fleets. Eindhoven's high-tech manufacturing corridor integrates vision-guided systems for semiconductor warehousing.
Belgium
Pharmaceutical cold-chain expansion in Flanders accelerates climate-resilient automation for biologics storage. REACH substance restrictions on lithium-ion batteries tighten material sourcing requirements for mobile robot fleets. Antwerp's port complex mirrors Rotterdam's automation density for container yard movements.
Switzerland
Temperature-controlled warehousing for precision pharmaceuticals anchors automated storage in the Basel-Zurich corridor. Swissmedic's medical device regulations intersect with EU AI Act compliance for vision systems in cleanroom environments. Geneva's luxury goods distribution centers pilot robotic piece-picking for high-value SKU assortments.
Poland
Underpenetrated Central European logistics networks attract first-mover AMR vendors outside established Western corridors. EU Green Deal procurement criteria reshape capital allocation toward sustainable automation in emerging distribution hubs. Warsaw's e-commerce fulfillment sector expands automated sortation capacity for Central European delivery networks.
Europe Warehouse Robotics Market Competitive Landscape
German producers anchor one tier; Swiss and Austrian specialists hold differentiated positions in pharmaceutical and high-bay automation. The vendor base organizes around three strategic archetypes: port-logistics system integrators, pharmaceutical cold-chain specialists, and forklift-to-robot conversion platforms. Consolidation pressure intensifies as mid-tier suppliers fragment compliance costs for EU AI Act documentation. Dominant competitive moves include M&A for software orchestration capabilities and strategic partnerships for solid-state battery supply chains.
Within the integrated-system tier, Dematic and Swisslog occupy positions shaped by deep vertical relationships with grocery and fashion supply chains. KION Group AG sits within the industrial-truck conversion segment, extending its installed base into automated guided vehicle architectures. SSI Schaefer AG exemplifies the high-bay storage specialist archetype, anchoring automated pharmaceutical warehousing through rack-integrated robotic systems.
| Leading Market Players |
|---|
| Dematic |
| Swisslog |
| SSI Schaefer AG |
| Vanderlande |
| KNAPP AG |
| KUKA AG |
| ABB Ltd. |
| KION Group AG |
| Swisslog Holding AG |
| Others |
Supply & Pricing Matrix
Performance-grade divergence between CE-marked AI-enabled systems and legacy automation hardware manifests in procurement premiums for algorithmic transparency documentation, while REACH-compliant battery chemistries concentrate supply leverage among German and Dutch system integrators with established electrolyte-salt sourcing relationships.
Pricing Analysis
Volume deployments of mobile robots and AGVs operate on thin hardware margins, whereas AI-integrated vision systems and compliance consulting services capture disproportionate value through software orchestration premiums. Price differentiation hinges on CE marking tier under EU AI Act risk classification and after-sales maintenance bundling. Cost compression in mid-tier AGV segments is intensifying because Polish assembly plants face REACH substance restrictions on lithium-ion cathode materials. Third-party logistics providers exhibit highest price sensitivity due to robotics-as-a-service contract structures, while pharmaceutical cold-chain operators accept premium positioning for climate-resilient specifications.
Supply Chain Analysis
EU Green Deal local-content requirements and CSRD embodied-carbon reporting rules are reshaping component sourcing toward European cell suppliers and recycled-cathode-material providers. Battery chemistry inputs draw from limited German and Hungarian electrolyte processors, with cathode active materials anchored in Polish precursor refineries. Single-source vulnerability concentrates in solid-state battery evaluation programs racing toward 2027 compliance deadlines. Distribution runs through Rotterdam-Antwerp port logistics clusters for cross-dock consolidation, with final-mile deployment managed by specialized robotics fleet managers displacing traditional system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into solid-state battery supply chains and captive software orchestration platforms is separating consolidators from component-dependent assemblers across the European warehouse robotics landscape.
For Market Incumbents: Hedge against REACH lithium supply concentration by securing long-term cathode material offtake agreements with Polish and Hungarian refiners, while accelerating in-house AI transparency documentation capabilities to capture compliance service revenue streams before EU AI Act enforcement fragments mid-tier supplier margins.
For New Entrants and Emerging Players: Capture underpenetrated Polish e-commerce fulfillment networks and Central European automated sortation demand outside the Rhine-Ruhr corridor, leveraging RTLS-AMR fusion as a differentiated entry point for high-velocity apparel distribution in Warsaw and Krakow logistics hubs.
For Investors and Strategic Acquirers: Re-rating potential sits with pharmaceutical cold-chain specialists given Swissmedic-EU AI Act intersection creating compliance moats, with acquisition focus on vision-guided piece-picking subsystem developers and solid-state battery integration capabilities as signals of technology-readiness inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Orchestration Platform Acquisition | CE marking documentation services under EU AI Act create recurring revenue streams for compliance-enabled vendors. |
| Solid-State Battery Supply Partnership | REACH substance restrictions on lithium-ion chemistries favor early movers in European cell supplier relationships. |
| Polish E-Commerce Fulfillment Expansion | Warsaw distribution centers offer first-mover positioning for AMR vendors outside saturated Western corridors. |
| Pharmaceutical Cold-Chain Certification | Swissmedic regulations intersect with EU AI Act for cleanroom-compliant vision systems in Basel-Zurich warehousing. |
| RTLS-AMR Convergence Development | Dutch fashion distributors leverage real-time location fusion for dynamic slotting optimization in high-velocity environments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted across robotics OEM engineering directors, third-party logistics fleet procurement managers, pharmaceutical warehouse operations heads, and EU regulatory compliance consultants. ECHA substance restriction databases, CE marking documentation repositories, and port authority throughput statistics provided validation layers. Bottom-up installation tracking across German e-commerce fulfillment centers and Dutch port logistics clusters was triangulated against top-down capital expenditure disclosures from KION Group AG and SSI Schaefer AG segment reporting.
Data-stream reconciliation across mobile robot shipment volumes, AGV retrofit conversions, and AI-enabled vision system placements informed analytical framework construction across the projection horizon. Segmentation dimensions modeled include product type mobility architecture, end-user vertical concentration, technology integration depth from RTLS through edge-AI, and application functional maturity from inventory management through piece-picking. CAGRs were derived from installation velocity curves and software attach-rate projections, with pharmaceutical cold-chain expansion and Polish e-commerce fulfillment penetration serving as industry-specific demand inputs.
The model holds under stable EU AI Act implementation timelines and REACH substance restriction phase-ins; deviation in solid-state battery commercialization schedules or F-Gas Regulation enforcement intensity would shift hardware cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Clean Room Robot Market
Robotics and Automation
Global Mobile Robots Market
Robotics and Automation
Japan Cloud Robotics Market
Robotics and Automation
North America Service Robotics Market
Robotics and Automation
Industrial Robots Market
Robotics and Automation
Robotics Actuators Market
Robotics and Automation
United States Articulated Robot Market
Robotics and Automation
Robotic Process Automation in Legal Services Market
Robotics and Automation
Bionic Glove's Market
Robotics and Automation
Global IT Robotic Automation Market
Robotics and Automation
Healthcare Mobile Robots Market
Robotics and Automation
Europe Automated Guided Vehicle (AGV) Market
Robotics and Automation
Global Adaptive Robot Market
Robotics and Automation
Automated Plate Handlers Market
Robotics and Automation
Cyber-Physical System Market
Robotics and Automation
Cleanroom Robots in Healthcare Market