
 Asia-Pacific AUV and ROV Market | 2026-2036
Asia-Pacific AUV and ROV Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific AUV and ROV Market Outlook
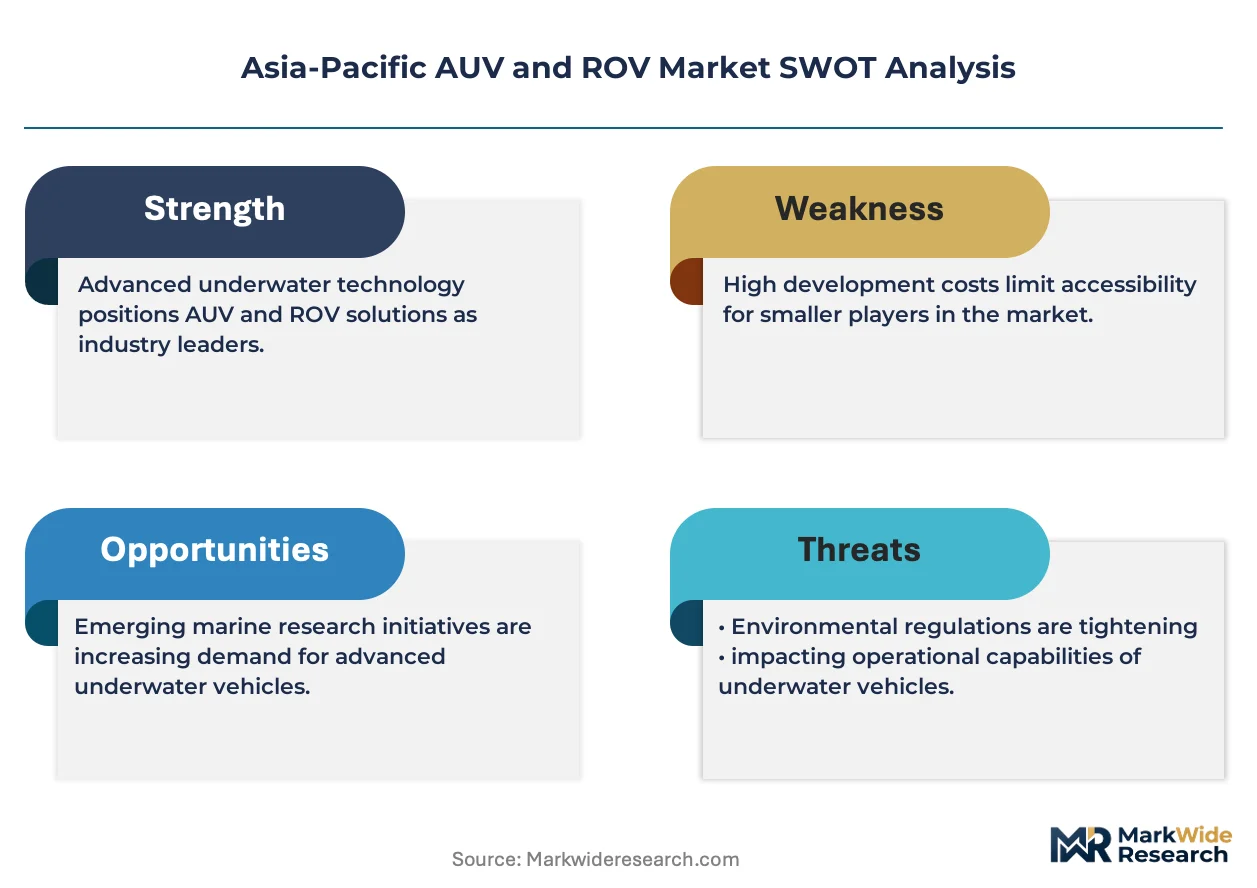
China's GB standards for underwater vehicle safety is pivoting the cost-of-entry calculus for regional manufacturers. Kongsberg Gruppen ASA leverages its navigation technology leadership to anchor premium positioning across Southeast Asian defense tenders. Kawasaki Heavy Industries sustains manufacturing scale through captive shipyard integration in Japan. Fugro Group differentiates by controlling proprietary data acquisition workflows for offshore wind site surveys.
Asia-Pacific AUV and ROV systems are untethered or tethered underwater vehicles powered by electric propulsion or hydraulic systems, typically operating at depths from shallow coastal zones to full ocean trenches, designed for subsea inspection, intervention, and data collection in environments inaccessible to human divers. Oil and gas exploration applications dominate current revenue pools due to legacy infrastructure inspection demand, while marine research represents the fastest-growing application segment driven by deep-sea biodiversity mapping programs. Hybrid systems are capturing margin concentration as end users seek platform flexibility across government and commercial deployments without duplicating capital expenditure.
Japan's METI enforces domestic content requirements for subsea robotics deployed in territorial waters, while Australia's TGA-equivalent maritime safety regulator mandates certification for vehicles operating near Great Barrier Reef protected zones. India's CEA and PLI scheme for advanced manufacturing are creating new demand pathways for domestic AUV assembly. Stakeholders must weigh certification reciprocity agreements against the cost of maintaining parallel compliance systems as procurement standards fragment across the region.
Market Dynamics
China's dual carbon goals are accelerating capital deployment into autonomous marine systems, while Southeast Asian offshore energy operators expand subsea inspection programs and Australia's Great Barrier Reef protection mandates reshape certification requirements for territorial water operations.
Growth Catalysts
- GB standards for underwater vehicle safety:China's national standards framework is lowering regulatory friction for domestic manufacturers, compressing time-to-market for certified AUV platforms.
- Offshore wind site surveys:Proprietary data acquisition workflows are capturing premium pricing as developers demand bathymetric precision for foundation placement across Southeast Asian lease blocks.
- Japan:METI domestic content requirements for subsea robotics in territorial waters are creating captive demand for locally assembled intervention systems.
Market Restraints
- Pressure-rated hull materials:Titanium alloy and carbon composite supply concentrates in Japanese and South Korean specialty metal foundries, exposing procurement to input cost volatility.
- Great Barrier Reef protected zones:Australia's TGA-equivalent maritime safety certification creates regulatory friction for vehicles operating near ecological sensitive areas, extending compliance timelines.
- Tethered ROV bandwidth limitations:Copper and fiber-optic umbilical technology faces substitution pressure from acoustic modem and satellite relay systems in deep-water applications.
Strategic Opportunities
- India's PLI scheme for advanced manufacturing:Domestic AUV assembly incentives are creating new demand pathways as CEA procurement standards favor local content in port security applications.
- Deep-sea biodiversity mapping:Marine research programs represent white space as hybrid systems capture margin concentration through platform flexibility across government and commercial deployments.
- Acoustic positioning convergence with AI-based navigation:Technology fusion is enabling untethered operation in GPS-denied environments, opening intervention tasks previously reserved for manned submersibles.
Industry Challenges
- Pressure vessel welding certification:Skilled technician scarcity in hyperbaric fabrication extends production lead times for full ocean depth rated hulls.
- Legacy oil and gas infrastructure integration:Intervention tooling compatibility with decades-old subsea wellhead designs requires custom engineering, compressing project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific AUV and ROV Market |
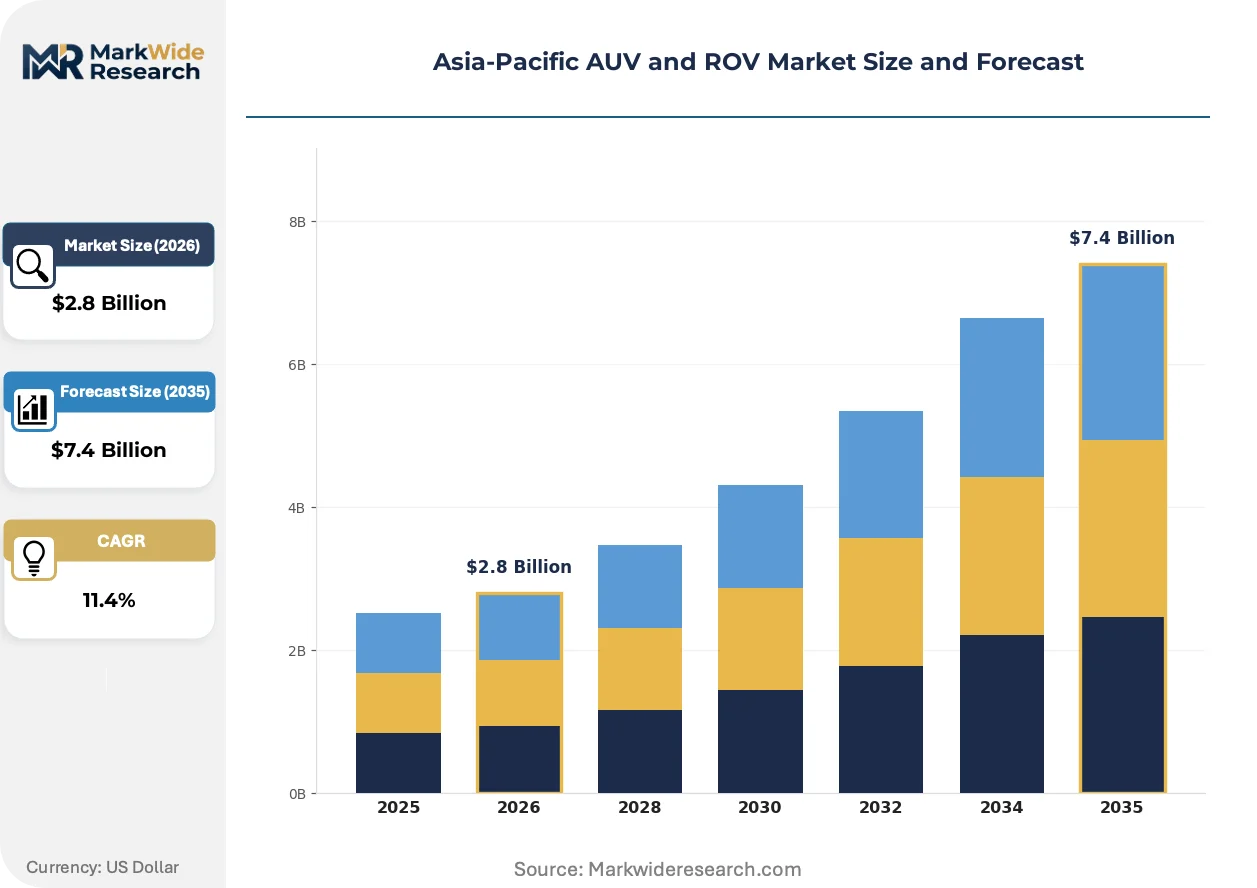
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AUVs, ROVs, Hybrid Systems, Autonomous Underwater Vehicles Application: Marine Research, Oil & Gas Exploration, Defense, Environmental Monitoring End User: Government, Commercial, Research Institutions, Educational Entities Technology: Electric Propulsion, Hydraulic Systems, Data Acquisition, Navigation Systems |
| Companies Covered | Teledyne Technologies Incorporated, Kongsberg Gruppen ASA, Oceaneering International, Inc., Fugro Group, Subsea 7 S.A., Saipem S.p.A., Larsen & Toubro Ltd, Kawasaki Heavy Industries, DOF Subsea AS, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific AUV and ROV Market Strategic Shifts
Hybrid electric-hydraulic propulsion architectures are unifying previously separate vehicle classes, while regulatory fragmentation across Asia-Pacific maritime zones and compressed procurement cycles for defense tenders reshape competitive positioning.
Hybrid AUV-ROV platforms are unifying autonomous survey capability with real-time operator intervention through detachable tether modules. Offshore wind developers in Australian and Vietnamese lease blocks are adopting these systems at pace to eliminate duplicate capital expenditure. The technology is unifying inspection and intervention workflows into single-asset deployments, compressing fleet size requirements for integrated energy companies.
China's MEE enforcement of GB standards for underwater vehicle emissions and safety is mandating design modifications for foreign OEMs seeking territorial water access. Industrial consequence includes accelerated localization partnerships as certification reciprocity remains limited. Deep-water oil and gas contractors operating in South China Sea blocks are responding by dual-sourcing domestic and imported platforms to maintain operational flexibility.
Defense procurement in Southeast Asia is compressing vendor qualification timelines as navies accelerate subsea domain awareness programs. Traditional multi-year tender cycles are contracting to 18-month windows, displacing incumbent suppliers unable to adapt proposal workflows. This pattern is most visible in Indonesian and Malaysian maritime security tenders, where rapid fleet modernization priorities override legacy supplier relationships.
Asia-Pacific AUV and ROV Market Segmentation
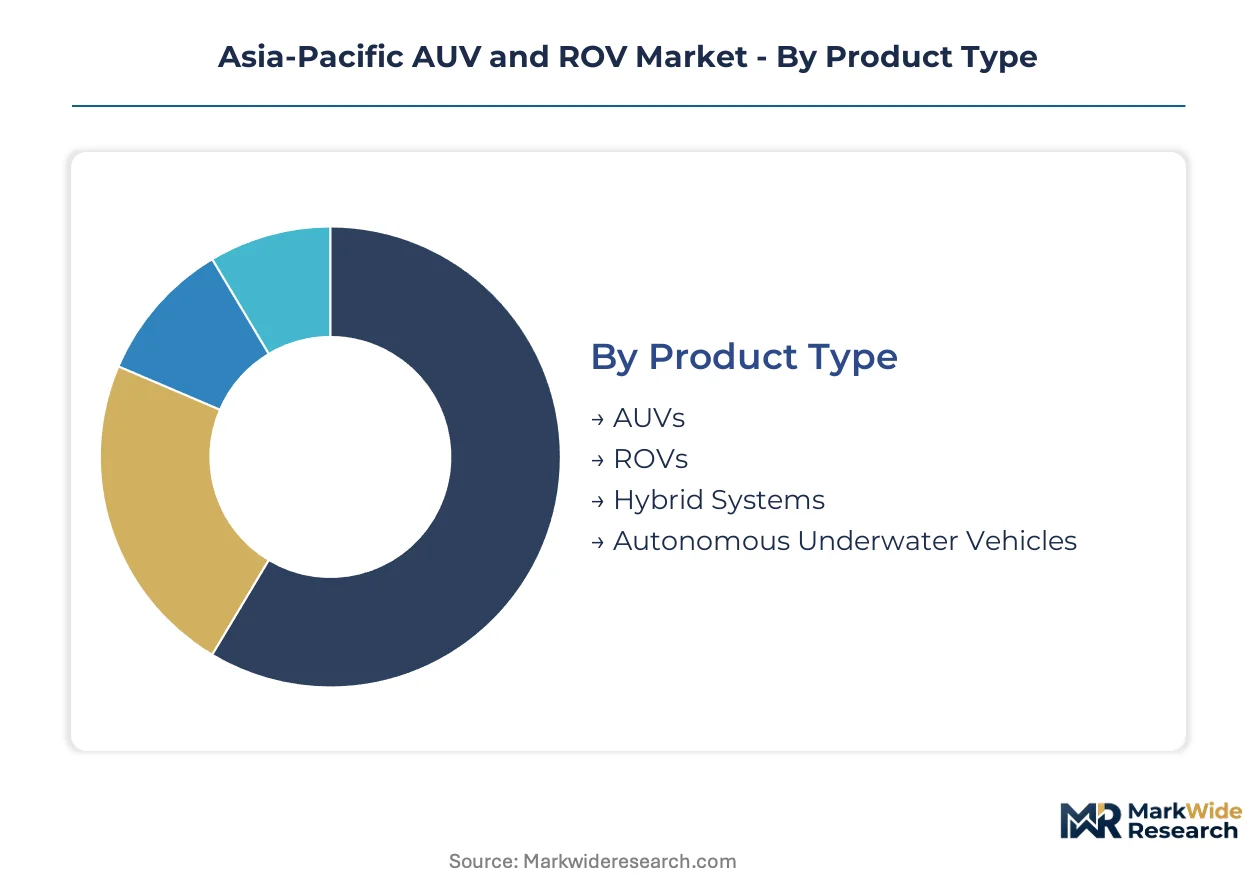
Asia-Pacific AUV and ROV procurement patterns diverge sharply across product architectures, with platform choice determining operational envelope, crew requirements, and total cost of ownership. Segmentation reveals how end-users balance mission flexibility against capital constraints across defense, energy, and research verticals.
Product Type:
Customization intensity spans fully configurable intervention systems to standardized survey platforms, with engineering complexity driving procurement channel selection.
- AUVs:Self-propelled untethered vehicles carry onboard power and processing for pre-programmed survey missions. Australia's offshore oil and gas corridor deploys these for pipeline inspection where surface vessel support is limited by weather windows.
- ROVs:Tethered platforms draw power and real-time control through umbilical connections, enabling precision manipulation tasks. Southeast Asian offshore energy operators favor work-class ROVs for subsea infrastructure intervention where human-in-the-loop decision-making is mandatory.
- Hybrid Systems:Modular architectures switch between autonomous survey and tethered intervention modes through detachable tether modules. Offshore wind developers in Vietnamese and Australian lease blocks adopt these to eliminate duplicate fleet capital expenditure.
- Autonomous Underwater Vehicles:Long-endurance gliders and propelled AUVs optimized for persistent oceanographic monitoring. Japan's territorial water programs under METI domestic content requirements drive assembly localization for these platforms.
Most installed capacity flows through ROVs. Expansion is steepest in Hybrid Systems.
Application:
Mission-criticality varies from regulatory-mandated infrastructure inspection to discretionary research funding, shaping contract duration and pricing power.
- Marine Research:Deep-sea biodiversity mapping and oceanographic sampling programs. China's MEE enforcement of GB standards for emissions and safety is mandating design modifications for foreign OEMs seeking territorial water access for research deployments.
- Oil & Gas Exploration:Legacy infrastructure inspection and well intervention across mature basins. Australia's Great Barrier Reef protection mandates reshape certification requirements for vehicles operating near ecological sensitive areas in the Northwest Shelf.
- Defense:Subsea domain awareness and mine countermeasures. Indonesian and Malaysian maritime security tenders are compressing vendor qualification timelines to 18-month windows, displacing incumbent suppliers unable to adapt proposal workflows.
- Environmental Monitoring:Water quality assessment and protected zone surveillance. India's CEA procurement standards favor local content in port security applications, creating demand pathways for domestic AUV assembly.
Contract value concentrates in Oil & Gas Exploration. Volume growth is climbing fastest in Marine Research.
End User:
Procurement sophistication ranges from centralized defense acquisition with multi-year budgets to fragmented research grants with annual funding cycles.
- Government:Defense ministries and maritime agencies with sovereign capability requirements. Japan's METI domestic content requirements for subsea robotics in territorial waters create captive demand for locally assembled intervention systems.
- Commercial:Integrated energy companies and offshore wind developers with fleet standardization priorities. Proprietary data acquisition workflows capture premium pricing as developers demand bathymetric precision for foundation placement.
- Research Institutions:Universities and oceanographic institutes with grant-dependent acquisition timelines. Deep-sea biodiversity mapping programs represent white space as hybrid systems capture margin concentration through platform flexibility.
- Educational Entities:Training programs and technology demonstration initiatives with budget-constrained procurement. These users typically acquire refurbished or entry-class platforms for curriculum development.
Capital deployment is heaviest among Commercial end users. Procurement volume is expanding most quickly through Government channels.
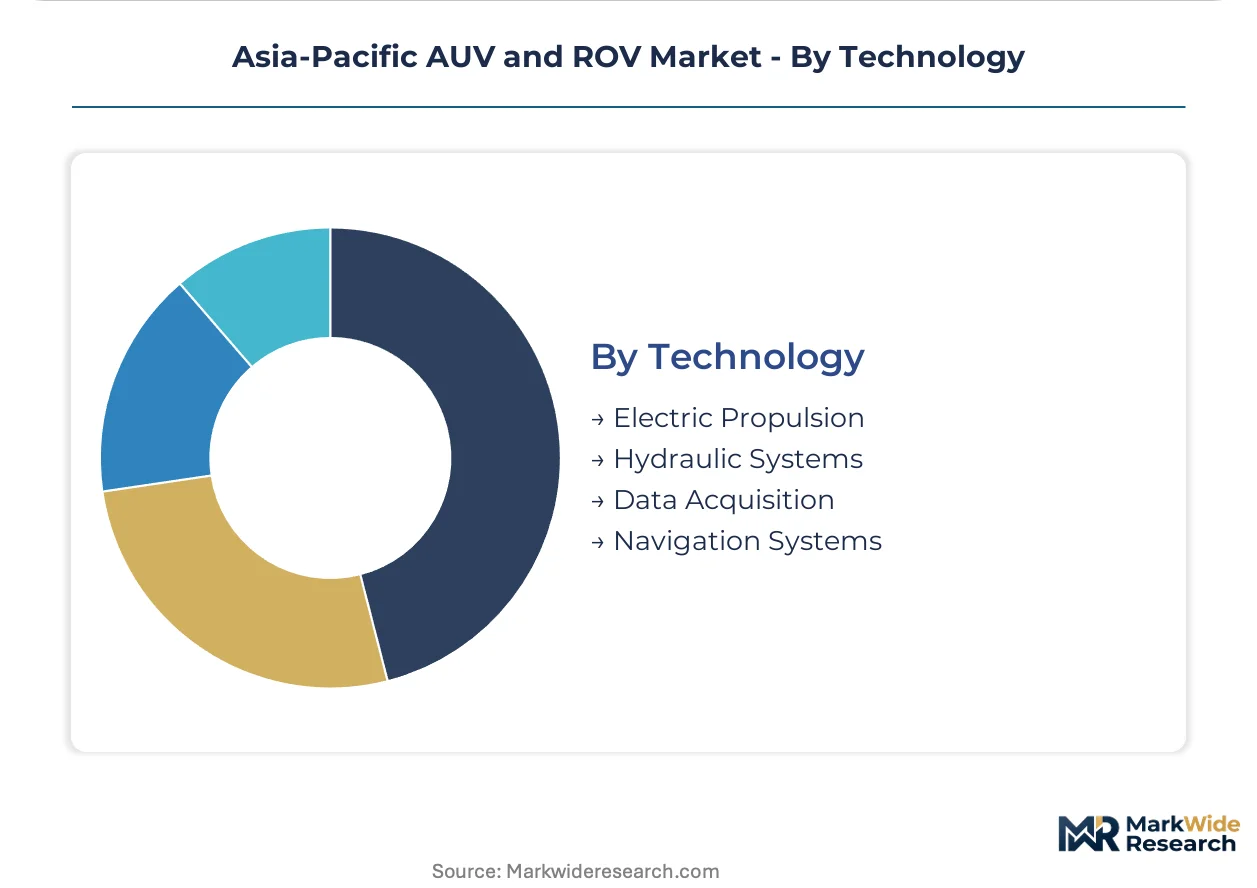
Technology:
Performance differentiation hinges on propulsion efficiency, sensor integration density, and navigation accuracy in GPS-denied environments.
- Electric Propulsion:Battery-powered motor systems offering precise thrust control and reduced acoustic signature. China's dual carbon goals are accelerating capital deployment into autonomous marine systems with electric architectures.
- Hydraulic Systems:High-force actuation for heavy intervention tooling and manipulator arms. Work-class ROVs in Southeast Asian offshore energy programs rely on these for subsea construction tasks.
- Data Acquisition:Multibeam sonar, sub-bottom profilers, and optical sensors integrated into survey payloads. Offshore wind site surveys demand proprietary workflows controlling sensor fusion and real-time quality assurance.
- Navigation Systems:Acoustic positioning, inertial measurement units, and AI-based path planning for untethered operation. Technology fusion is enabling intervention tasks previously reserved for manned submersibles in South China Sea blocks.
Revenue concentration sits with Navigation Systems. Technology investment is climbing fastest in Data Acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hyperbaric welders and acoustic engineers concentrate in Japanese shipyard clusters and Australian offshore service hubs, anchoring regional technical capability for pressure-rated hull fabrication and subsea navigation systems.
China
Dual carbon policy targets are redirecting state capital toward electric-propulsion marine robotics for offshore wind development. MEE enforcement of GB standards for underwater vehicle emissions and safety is mandating design modifications for foreign OEMs seeking territorial water access. Yangtze River Delta manufacturing clusters are absorbing localization partnerships as certification reciprocity remains limited.
Japan
METI domestic content requirements for subsea robotics deployed in territorial waters are creating captive demand for locally assembled intervention systems. Kawasaki Heavy Industries sustains manufacturing scale through captive shipyard integration in Kobe and Yokohama. Kanto region engineering centers are advancing hybrid electric-hydraulic propulsion architectures for defense and commercial dual-use platforms.
Australia
Offshore oil and gas corridor operators in the Northwest Shelf are expanding autonomous inspection programs for legacy infrastructure. TGA-equivalent maritime safety certification mandates reshape compliance requirements for vehicles operating near Great Barrier Reef protected zones. Perth-based service companies are consolidating proprietary data acquisition workflows for offshore wind site surveys in Bass Strait lease blocks.
India
CEA procurement standards and PLI scheme incentives for advanced manufacturing are creating new demand pathways for domestic AUV assembly in port security applications. Mumbai-Gujarat maritime industrial corridors are attracting component suppliers for navigation and sensor systems. Tamil Nadu coastal manufacturing zones are positioning for submarine mine countermeasure system integration under naval modernization programs.
Southeast Asia
Indonesian and Malaysian maritime security tenders are compressing vendor qualification timelines to 18-month windows as navies accelerate subsea domain awareness programs. Singapore's deep-water oil and gas contractors operating in South China Sea blocks are dual-sourcing domestic and imported platforms. Vietnamese offshore wind developers in southern lease blocks are adopting hybrid systems to eliminate duplicate capital expenditure.
Asia-Pacific AUV and ROV Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across a tiered vendor structure. The market fragments across three strategic archetypes: integrated energy service companies controlling proprietary survey workflows, defense-electronics conglomerates leveraging navigation technology leadership, and captive shipyard-integrated manufacturers serving domestic content requirements. Competitive moves concentrate on strategic partnerships for certification reciprocity and portfolio diversification into hybrid platform architectures.
Among European-integrated energy service providers, Kongsberg Gruppen ASA and Fugro Group exemplify contrasting positioning archetypes. Kongsberg leverages its navigation technology leadership to anchor premium positioning across Southeast Asian defense tenders. Fugro occupies a position defined by proprietary data acquisition workflow control for offshore wind site surveys. Japanese shipyard-integrated manufacturers including Kawasaki Heavy Industries represent the captive-scale archetype, sustaining production volume through METI-mandated domestic content programs.
| Leading Market Players |
|---|
| Teledyne Technologies Incorporated |
| Kongsberg Gruppen ASA |
| Oceaneering International, Inc. |
| Fugro Group |
| Subsea 7 S.A. |
| Saipem S.p.A. |
| Larsen & Toubro Ltd |
| Kawasaki Heavy Industries |
| DOF Subsea AS |
| Others |
Value Chain & Pricing Dynamics
Defense ministries across Indonesia, Malaysia, and Australia anchor procurement volume through multi-year fleet modernization programs, compressing vendor qualification timelines and favoring bundled service contracts that merge platform delivery with operator training and maintenance over pure equipment sales.
Pricing Analysis
Bundled service contracts dominate defense and offshore energy segments while unbundled equipment sales persist in research and educational markets. Three-tier pricing structure across premium, standard, and economy levels separates full ocean depth rated systems with titanium hulls from shallow-water aluminum platforms and refurbished training units. Cost compression in mid-tier survey AUVs is intensifying because Chinese domestic manufacturers exploit GB standards compliance advantages to undercut foreign OEMs on territorial water contracts. Research institutions exhibit highest price sensitivity due to grant-dependent funding cycles, while integrated energy companies prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
Titanium alloy and carbon composite supply rests on Japanese and South Korean specialty metal foundries, with pressure-rated hull fabrication concentrating in Kobe shipyard clusters and Busan hyperbaric welding facilities. Acoustic positioning arrays and inertial navigation units draw from Taiwanese sensor foundries and German engineering centers. Single-source vulnerability in deep-water umbilical manufacturing exposes procurement to input cost volatility when copper and fiber-optic cable supply tightens. Distribution runs through Perth-based offshore service hubs for Australian oil and gas operators and Singaporean logistics nodes for Southeast Asian defense tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific AUV and ROV demand compounds steadily as offshore wind development accelerates across Vietnamese and Australian lease blocks, creating persistent replacement and expansion cycles for inspection-capable platforms.
For Market Incumbents: Anticipate compressed defense tender cycles displacing legacy suppliers unable to adapt proposal workflows to 18-month Indonesian and Malaysian maritime security windows. Prioritize certification reciprocity investments to reduce parallel compliance system costs across fragmented Asia-Pacific maritime zones. Deepen backward integration into pressure vessel welding capabilities to offset skilled technician scarcity extending production lead times.
For New Entrants and Emerging Players: Offshore wind developers in southern Vietnamese lease blocks represent the most penetrable customer segment, with hybrid system demand outpacing established vendor capacity. Marine research programs offer white-space entry through platform flexibility propositions that eliminate duplicate capital expenditure for government and commercial dual-use deployments. Partner with Perth-based service companies controlling proprietary data acquisition workflows to bypass direct competition with integrated energy service incumbents.
For Investors and Strategic Acquirers: Integrated energy service companies are the most active acquirer in this space, seeking navigation technology and survey workflow assets to anchor premium positioning. Target mid-tier AUV assemblers with METI-compliant manufacturing footprints in Japan or PLI scheme qualifications in India. Watch GB standards enforcement intensity as the inflection indicator for domestic manufacturer market share trajectories in Chinese territorial waters.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Platform Architecture Development | Unifies autonomous survey with tethered intervention to eliminate duplicate fleet capital for offshore wind developers. |
| GB Standards Certification Partnership | Accelerates territorial water access for foreign OEMs facing MEE enforcement of domestic emissions and safety mandates. |
| Acoustic Positioning-AI Navigation Fusion | Enables untethered intervention in GPS-denied South China Sea blocks previously reserved for manned submersibles. |
| Domestic Content Assembly Localization | Captures METI-mandated demand in Japan and PLI scheme incentives in India for territorial water robotics programs. |
| Proprietary Data Acquisition Workflow Control | Commands premium pricing from Bass Strait offshore wind developers demanding bathymetric precision for foundation placement. |
Study Parameters
Bottom-up offshore energy operator and defense ministry procurement modeling reconciled against top-down shipyard production capacity tracking forms the analytical core. Primary interviews with fleet managers at integrated energy companies, submarine program officers at Southeast Asian navies, and technical directors at Japanese shipyard clusters combined with secondary validation through customs import records, MEE GB standards filings, and METI domestic content program disclosures. Triangulation across these sources isolates platform deployment rates from inventory accounting distortions common in multi-year defense contracts.
Input-output matrices map pressure-rated hull fabrication capacity in Japanese and South Korean foundries against projected demand from offshore wind site surveys and subsea infrastructure inspection programs. Segmentation dimensions span product architecture, application vertical, end-user procurement sophistication, and propulsion technology type across the modeling period. CAGRs derive from installed base replacement cycles, fleet expansion ratios in emerging lease blocks, and technology substitution rates from tethered ROVs toward hybrid systems.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to GB standards reciprocity negotiations, titanium alloy supply disruptions, and defense budget reallocation following maritime security priority shifts. A small set of triggers—MEE enforcement intensity, Indonesian tender cycle compression, and hybrid system adoption rates in Vietnamese offshore wind—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Waste Sorting Robots Market
Robotics and Automation
Surgical Robots Market
Robotics and Automation
Exoskeleton Systems Market
Robotics and Automation
Mobile Robotics Software Market
Robotics and Automation
Robotics for NDT Market
Robotics and Automation
Europe Automated Guided Vehicle (AGV) Market
Robotics and Automation
Global Autonomous Mobile Robot Market
Robotics and Automation
Robot Market
Robotics and Automation
Piece Picking Robots Market
Robotics and Automation
Bot Services Market
Robotics and Automation
Firefighting Robots Market
Robotics and Automation
Agricultural Robots and Mechatronics Market
Robotics and Automation
Smart Curtain Robot Market
Robotics and Automation
Handheld Robotics Market
Robotics and Automation
Aerospace Service Robotics Market
Robotics and Automation
Top Robotics Market