
 GCC AUV Market | 2026-2036
GCC AUV Market Size, Share, and Industry Trends Forecast 2026-2036
GCC AUV Market Foresight
Saudi Arabia's Eastern Province is reconfiguring demand patterns across the GCC AUV landscape as energy majors expand subsea robotics programs. Kongsberg Gruppen ASA leverages its acoustic sensor heritage to anchor long-term service contracts with regional oil and gas operators. Fugro NV sustains competitive positioning through its specialized focus on geophysical survey and seabed mapping capabilities. Teledyne Technologies Incorporated differentiates via integrated communication systems that extend operational range in deep-water Gulf environments.
An autonomous underwater vehicle (AUV) is a self-propelled, untethered robotic system operating below the water surface, typically rated for depths from 100 to 6,000 meters depending on pressure hull construction and battery configuration, designed to execute pre-programmed missions without real-time human piloting for commercial, scientific, or military data acquisition. Underwater drones dominate current procurement volumes across GCC defense and energy channels, reflecting proven reliability in pipeline inspection and hydrographic survey missions. Hybrid AUVs represent the fastest-expanding technology segment as operators seek dual-mode platforms capable of both autonomous transit and remotely operated intervention tasks, with margin pools concentrating in AI-integrated navigation packages that reduce surface support vessel dependency.
The UAE's Telecommunications and Digital Government Regulatory Authority and Saudi Arabia's Communications, Space and Technology Commission both influence AUV market access through spectrum allocation rules governing underwater acoustic and satellite communication links. Saudi Aramco's internal technical standards for subsea inspection equipment create de facto product certification requirements that shape vendor qualification processes across the Gulf. Stakeholders must monitor how evolving national content requirements and localization mandates in Saudi Arabia and the UAE reshape supply chain structures and partnership obligations for foreign AUV manufacturers.
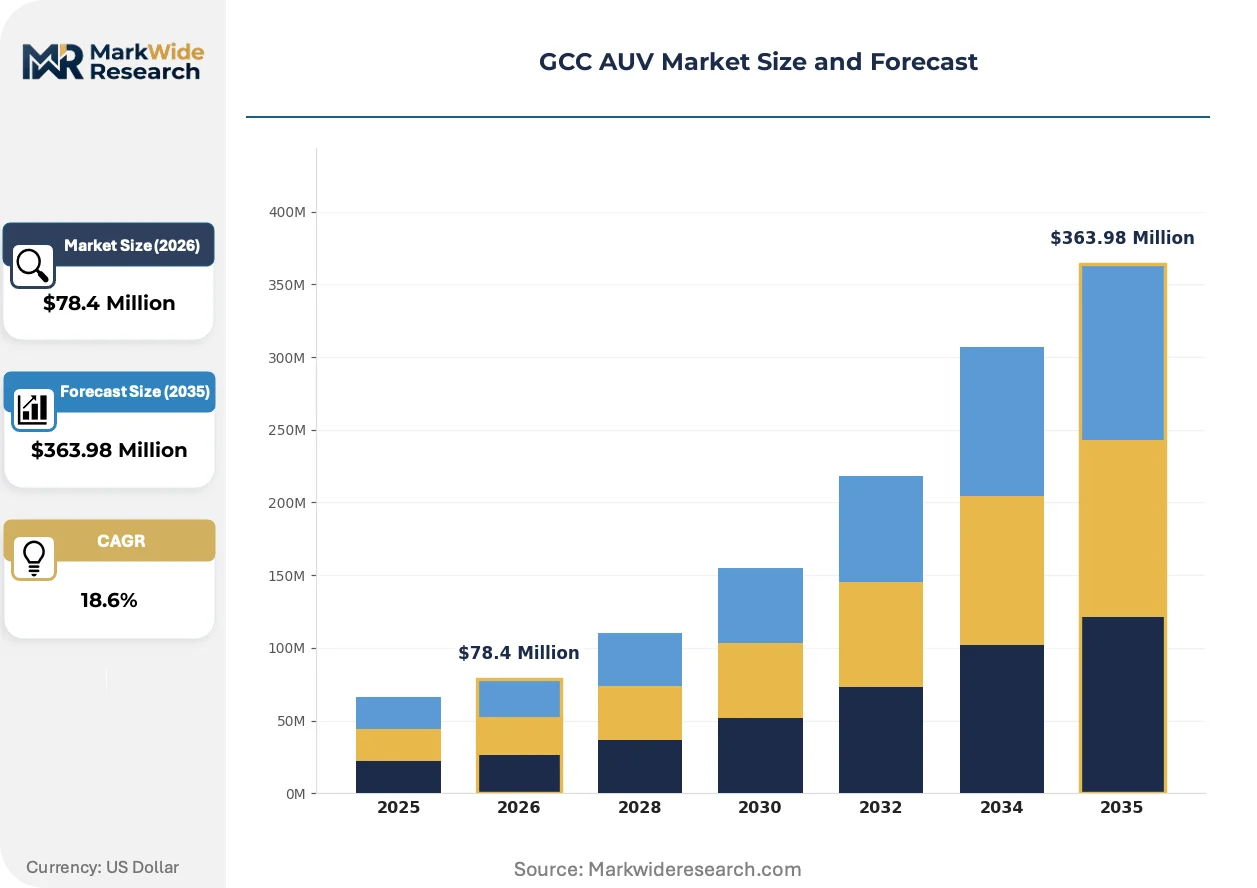
Market Dynamics
Aramco's seabed mapping mandates are compressing deployment timelines and forcing foreign AUV manufacturers into accelerated localization partnerships across Saudi Arabia's Eastern Province.
Growth Catalysts
- Subsea Pipeline Integrity Mandates:Saudi Aramco's technical standards for asset inspection are creating captive demand for autonomous survey platforms in the Persian Gulf's offshore fields.
- SFDA Spectrum Allocation:Saudi Arabia's Communications, Space and Technology Commission has cleared dedicated acoustic frequency bands for underwater telemetry, reducing interference risk in congested Gulf waters.
- Hybrid Platform Convergence:The integration of autonomous transit with remotely operated intervention modes is expanding mission flexibility for deep-water operators.
Market Restraints
- Lithium-Ion Supply Concentration:Pressure-rated battery packs depend on East Asian cell manufacturers, exposing GCC operators to shipping delays through the Strait of Hormuz.
- Pressure Hull Fabrication Bottlenecks:Only three certified suppliers globally produce titanium alloy hulls rated beyond 4,000 meters, creating queue times exceeding 14 months.
- MOHAP Certification Friction:The UAE's maritime regulator requires redundant safety systems for territorial water operations, adding 20-30% to platform integration costs.
Strategic Opportunities
- Qatar's North Field Expansion:Uncontracted demand for seabed preparation and pipeline route surveys ahead of LNG train commissioning creates first-mover positioning for qualified vendors.
- AI-Integrated Navigation Packages:Machine learning-based obstacle avoidance and path optimization are reducing surface support vessel dependency by 40-60% in pilot deployments.
- Oman's Duqm Port Cluster:The special economic zone's shipyard modernization program offers co-location advantages for AUV maintenance and battery swap infrastructure.
Industry Challenges
- Subsea Robotics Technician Scarcity:GCC universities produce fewer than 200 qualified mechatronics graduates annually, forcing operators to import talent from Norway and Singapore.
- Aramco Vendor Qualification Timelines:Foreign manufacturers face 18-24 month approval cycles for subsea equipment certification, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC AUV Market |
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $363.98 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Surface Vehicles, Underwater Drones, Hybrid AUVs, UAVs End User: Defense, Oil & Gas, Environmental Monitoring, Research Institutions Technology: GPS Navigation, Acoustic Sensors, AI Integration, Communication Systems Application: Surveillance, Data Collection, Mapping, Inspection |
| Companies Covered | Forum Energy Technologies Inc., Saab AB, Oceaneering International Inc., Fugro NV, Kongsberg Gruppen ASA, General Dynamics Corporation, Lockheed Martin Corporation, Teledyne Technologies Incorporated, BAE Systems plc, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC AUV Market Shifts & Advancements
Acoustic positioning systems are migrating from short-baseline to ultra-short-baseline architectures, compressing operational envelopes and enabling tighter station-keeping in cluttered seabed environments.
Synthetic aperture sonar is migrating from research-grade deployments to commercial pipeline inspection contracts. Saudi Aramco's surveying divisions are specifying SAS payloads for all new AUV procurements above $2 million unit value. This capability is migrating from specialty geophysical contractors to integrated service companies, collapsing the historical segmentation between hardware vendors and survey operators.
MOHAP's 2024 technical circular on autonomous maritime systems mandates encrypted command links for all sub-500 meter operations in UAE territorial waters. The regulation forces retrofit of legacy acoustic modems or complete platform replacement for operators holding pre-2023 certifications. Dubai-based offshore contractors are absorbing compliance costs through extended lease terms rather than capital write-downs.
Service contracting is fragmenting from integrated vessel-charter packages toward unbundled AUV-day rates with separate charges for data processing and interpretation. Abu Dhabi National Oil Company's marine division now sources autonomous survey platforms from specialized lessors while retaining in-house geophysicists for final deliverable preparation. This unbundling is most advanced in the UAE, where port infrastructure supports rapid equipment rotation between campaigns.
GCC AUV Market Segmentation
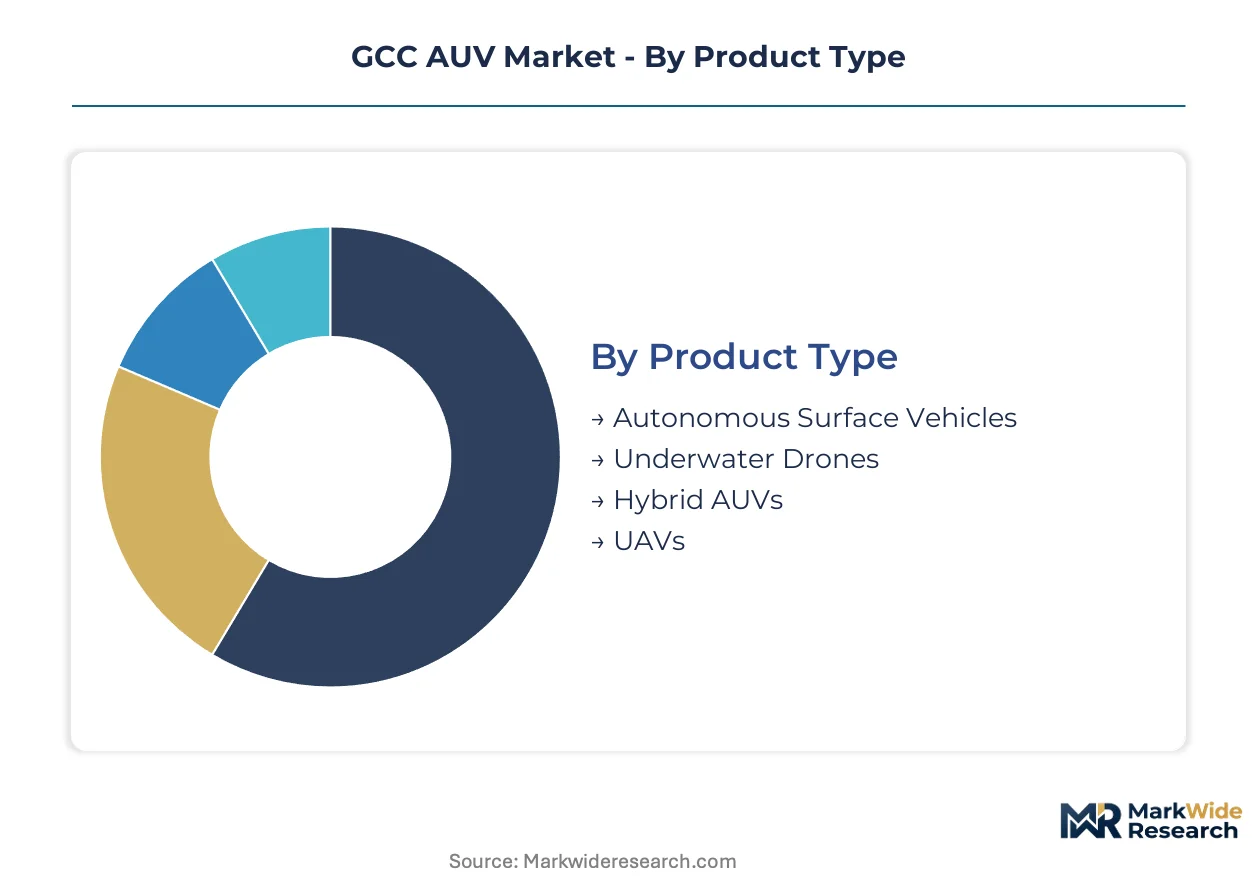
AUV segmentation in the GCC reflects the tension between proven reliability and emerging capability. Procurement patterns diver sharply across defense channels demanding encrypted command links and energy operators prioritizing seabed survey precision.
Product Type:
The use-case spectrum stretches from surface-tethered reconnaissance to fully autonomous deep-water intervention, with battery chemistry and pressure hull rating determining mission envelope boundaries.
- Underwater Drones:Self-propelled untethered platforms rated for 100-6,000 meter depths depending on titanium hull construction and lithium-ion pack configuration. Saudi Aramco's Eastern Province procurement concentrates here for pipeline inspection missions where proven reliability outweighs cutting-edge specifications.
- Hybrid AUVs:Dual-mode systems switching between autonomous transit and remotely operated intervention via acoustic command link. UAE's MOHAP certification requirements for territorial water operations are accelerating fleet upgrades toward this architecture as operators seek to reduce surface support vessel dependency.
- Autonomous Surface Vehicles:Wave or solar-powered platforms for persistent maritime domain awareness patrols above the thermocline.
- UAVs:Aerial coordination platforms extending communication relay range for over-the-horizon AUV operations.
The dominant share belongs to Underwater Drones, while Hybrid AUVs are closing the gap fastest.
End User:
Customer concentration tracks hydrocarbon infrastructure density and defense modernization budgets across the Gulf.
- Oil & Gas:Offshore operators in Saudi Arabia's Eastern Province and Qatar's North Field dominate current procurement volumes. Aramco's technical standards for subsea inspection equipment create de facto certification requirements that shape vendor qualification timelines.
- Defense:Naval forces prioritizing mine countermeasures and seabed warfare capabilities. The UAE's maritime regulator has tightened encrypted command link mandates for all sub-500 meter autonomous operations in territorial waters.
- Environmental Monitoring:Marine protected area managers and fisheries regulators tracking ecosystem health indicators.
- Research Institutions:Universities and oceanographic centers conducting baseline seabed mapping for climate impact assessment.
Energy sector procurement maintains volume leadership, though defense budgets are expanding most quickly.
Technology:
Capability differentiation clusters around navigation precision, sensor fusion, and operational autonomy in GPS-denied environments.
- Acoustic Sensors:Ultra-short-baseline positioning architectures enabling tighter station-keeping in cluttered seabed environments. Saudi Aramco's surveying divisions now specify synthetic aperture sonar payloads for all new procurements above $2 million unit value.
- AI Integration:Machine learning-based obstacle avoidance and path optimization reducing surface support vessel dependency by 40-60% in pilot deployments across Abu Dhabi National Oil Company marine operations.
- GPS Navigation:Surface-bound positioning for shallow-water survey coordination and mission planning.
- Communication Systems:Encrypted acoustic modems and satellite uplinks for command-and-control in deep-water Gulf environments.
Acoustic sensor packages command the largest technology spend, with AI-integrated navigation gaining share fastest.
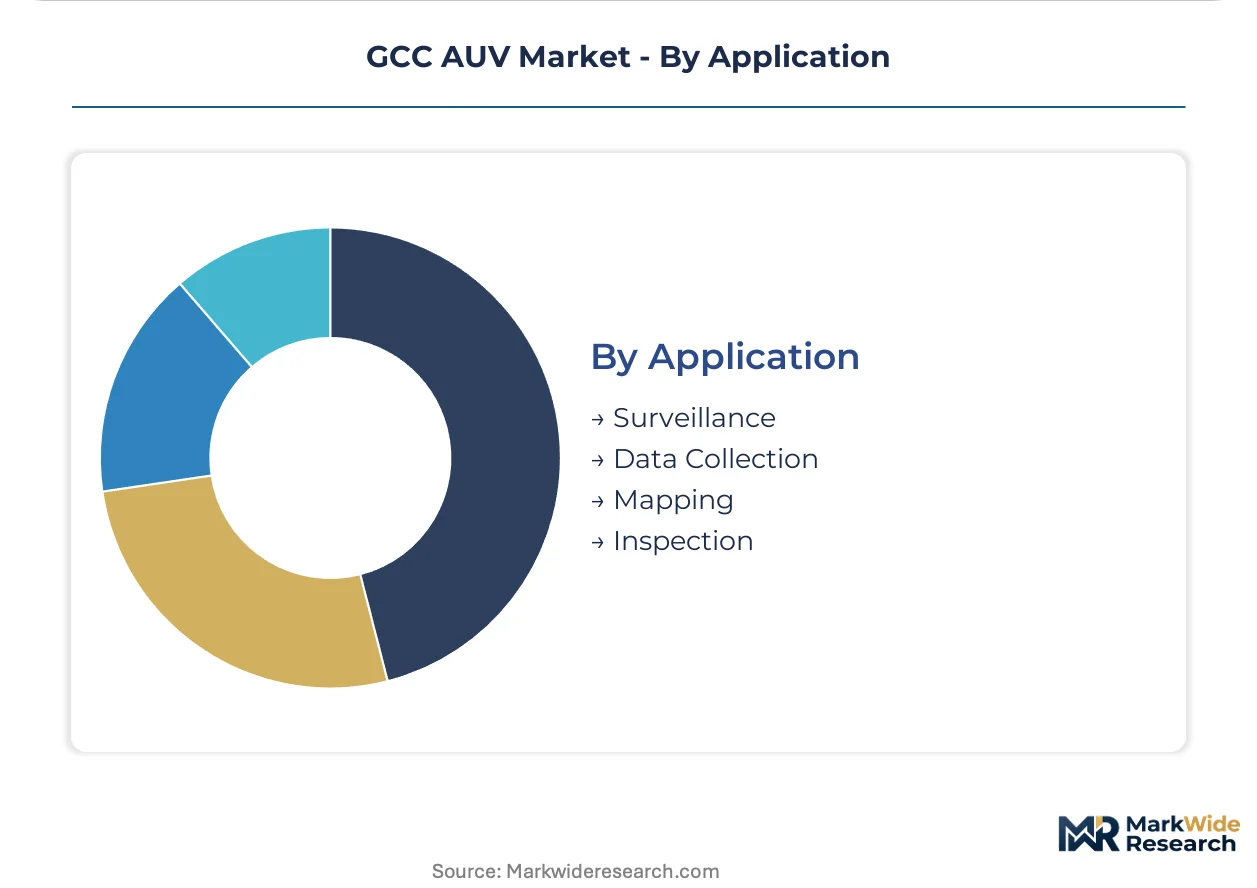
Application:
Mission profiles range from defensive seabed warfare to commercial asset integrity verification.
- Inspection:Pipeline integrity surveys and subsea infrastructure condition assessment. Service contracting is fragmenting from integrated vessel-charter packages toward unbundled AUV-day rates with separate charges for data processing.
- Mapping:High-resolution seabed terrain modeling for route planning and hazard identification. Qatar's North Field expansion creates uncontracted demand for seabed preparation surveys ahead of LNG train commissioning.
- Surveillance:Maritime domain awareness and critical infrastructure protection patrols.
- Data Collection:Oceanographic parameter logging for environmental baseline establishment.
Inspection applications generate the dominant revenue share, while mapping contracts are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's Communications, Space and Technology Commission anchors the regulatory framework governing autonomous underwater operations across the Gulf, with spectrum allocation decisions rippling through procurement timelines in neighboring maritime jurisdictions.
Saudi Arabia
Aramco's seabed mapping mandates and pipeline integrity programs concentrate demand in the Eastern Province, where energy infrastructure investments are accelerating AUV deployment. The Communications, Space and Technology Commission has cleared dedicated acoustic frequency bands for underwater telemetry, reducing interference risk in congested Gulf waters. Dhahran and the surrounding industrial corridor host the densest clustering of subsea robotics procurement activity.
United Arab Emirates
Abu Dhabi National Oil Company's marine division sources autonomous survey platforms through unbundled contracting models, separating equipment lease from data interpretation services. MOHAP's 2024 technical circular mandates encrypted command links for all sub-500 meter operations in territorial waters, forcing retrofit investments across existing fleets. Dubai and Abu Dhabi port infrastructure supports rapid equipment rotation between offshore campaigns.
Qatar
North Field expansion projects generate uncontracted demand for seabed preparation and pipeline route surveys ahead of LNG train commissioning. The country's national maritime regulator has aligned certification requirements with neighboring GCC standards to facilitate cross-border equipment mobility. Ras Laffan Industrial City anchors the concentration of subsea survey contracting activity.
Oman
Duqm Port Cluster's special economic zone offers co-location advantages for AUV maintenance and battery swap infrastructure, attracting regional operators seeking operational cost efficiencies. The Sultanate's central bank has facilitated project finance structures for port modernization programs incorporating autonomous maritime systems. The southeastern coastal development zone is emerging as a maintenance hub for Gulf-based underwater vehicle fleets.
Kuwait
Offshore oil field redevelopment plans are generating preliminary demand for seabed survey capabilities, though procurement volumes remain below Saudi and UAE thresholds. The national oil company's technical standards division is evaluating adoption of Aramco-equivalent certification requirements for subsea inspection equipment. Al Ahmadi's marine logistics cluster is positioning for downstream service contracting as fleet deployment scales.
GCC AUV Market Competitive Landscape
Capability concentration sits with specialized sensor and acoustic technology developers; scale advantage sits with integrated energy service conglomerates with existing vessel fleets and long-term operator relationships. The market structures around three tiers: defense contractors with encrypted command-link expertise, geophysical survey specialists with seabed mapping heritage, and hybrid-platform integrators bridging autonomous and remotely operated modes. Dominant competitive moves include accelerated localization partnerships to satisfy Saudi national content requirements, and technology licensing arrangements to compress Aramco vendor qualification timelines.
Among Norway-based technology groups, Kongsberg Gruppen ASA exemplifies the acoustic sensor heritage archetype, anchoring long-term service relationships through integrated positioning and navigation packages. Netherlands-registered Fugro NV occupies a parallel position in the geophysical survey specialization tier, with seabed mapping capabilities shaping procurement specifications for major Gulf energy operators. Teledyne Technologies Incorporated, a US-incorporated entity, represents the integrated communication systems approach, with underwater telemetry products extending operational range in deep-water Gulf environments.
| Leading Market Players |
|---|
| Forum Energy Technologies Inc. |
| Saab AB |
| Oceaneering International Inc. |
| Fugro NV |
| Kongsberg Gruppen ASA |
| General Dynamics Corporation |
| Lockheed Martin Corporation |
| Teledyne Technologies Incorporated |
| BAE Systems plc |
| Others |
Supply & Pricing Matrix
East Asian lithium-ion cell manufacturers anchor the upstream battery supply for pressure-rated AUV power systems, concentrating margin capture in hull fabrication and AI-integrated navigation software tiers where Gulf operators face extended queue times and limited vendor pools.
Pricing Analysis
Unit pricing spreads $800,000 to $4.5 million across the Gulf depending on pressure hull rating and sensor payload configuration. Three-tier pricing structure across expedition-grade, commercial-survey, and light-inspection levels tracks certification depth rating and acoustic positioning precision. Pricing pressure stems from Aramco's accelerated localization mandates compressing vendor qualification timelines and forcing partnership cost absorption. National oil companies exhibit lowest price sensitivity for seabed mapping contracts, while port-service operators in Oman's Duqm cluster negotiate aggressively on maintenance-day rates.
Supply Chain Analysis
Titanium alloy feedstock for pressure hulls draws from Russian and Chinese sponge producers, with final fabrication concentrated in Norway, the United States, and Japan. Lithium-ion cell supply rests on South Korean and Chinese manufacturers, while synthetic aperture sonar arrays source from specialized acoustic technology groups in Norway and the United Kingdom. Single-source vulnerability concentrates in hulls rated beyond 4,000 meters where only three certified suppliers operate globally. Distribution runs through integrated energy service conglomerates with existing vessel fleets and long-term operator relationships across Saudi Arabia's Eastern Province.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat environment where regulatory entrenchment around Aramco vendor qualification and MOHAP certification creates structural barriers that compound over successive procurement cycles.
For Market Incumbents: Insulate service relationships through accelerated localization partnerships in Saudi Arabia's Eastern Province to satisfy national content requirements. Deepen captive supply of pressure hull fabrication capacity via technology licensing with Norwegian heritage suppliers. Certification investment in encrypted acoustic command links addresses MOHAP's 2024 retrofit mandates before competitors complete approval cycles.
For New Entrants and Emerging Players: Build out white-space positioning in Qatar's North Field expansion seabed preparation contracts where uncontracted demand precedes LNG train commissioning. Target Oman's Duqm Port Cluster maintenance infrastructure as the most penetrable geography given co-location advantages and emerging battery-swap hub status. Go-to-market angle centers on unbundled AUV-day rate contracting with separate data processing charges, mirroring Abu Dhabi National Oil Company's procurement evolution.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed geophysical survey specialists holding Aramco-approved vendor status and synthetic aperture sonar integration capabilities. Long-term viability over the coming decade hinges on AI-integrated navigation package development reducing surface support vessel dependency. Watch for inflection in Saudi national content enforcement intensity as the signal for localization partnership valuation step-ups.
| Strategic Initiative | Industry Significance |
|---|---|
| Localization Partnership Formation | Accelerates Aramco vendor qualification timelines while satisfying Saudi national content mandates. |
| AI-Integrated Navigation Package Development | Reduces surface support vessel dependency by 40-60% in Abu Dhabi National Oil Company pilot deployments. |
| Encrypted Acoustic Modem Retrofit Program | Addresses MOHAP's 2024 technical circular mandates for sub-500 meter UAE territorial water operations. |
| Synthetic Aperture Sonar Payload Integration | Meets Aramco's procurement specifications for all new AUV acquisitions above $2 million unit value. |
| Duqm Port Maintenance Hub Establishment | Captures operational cost efficiencies through co-located battery swap and pressure hull servicing infrastructure. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with subsea robotics program managers at Saudi Aramco, marine division procurement leads at Abu Dhabi National Oil Company, regulatory affairs officers at MOHAP and the Communications, Space and Technology Commission, and technical directors at Kongsberg Gruppen and Fugro. Secondary validation drew from SEC filings of listed energy service conglomerates, customs records tracking titanium alloy and lithium-ion cell imports through Gulf ports, and project development databases for Qatar's North Field expansion. Bottom-up segment sizing triangulated against top-down energy infrastructure investment forecasts.
Calibration against historical AUV deployment data across Saudi Arabia's Eastern Province and UAE offshore fields anchored the projection framework across the analysis window. Segmentation dimensions modeled include product type, end user, technology tier, and application mission profile, with additional granularity on pressure hull depth rating and acoustic positioning architecture. CAGRs were derived from regression analysis of procurement volume trends against hydrocarbon infrastructure investment cycles and regulatory mandate implementation timelines. Industry-specific inputs incorporated Aramco technical standard revision schedules and MOHAP certification throughput capacity.
Stress conditions across lithium-ion supply chain disruption through the Strait of Hormuz, titanium hull fabrication queue extension beyond 18 months, and Saudi national content requirement step-ups were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions around regulatory enforcement intensity and energy operator capital commitment continuity. Cross-checking against subsea robotics technician graduation rates from GCC universities and Norwegian/Singapore talent import volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
United States Agricultural Robots Market
Robotics and Automation
Medical Service Robots Market
Robotics and Automation
Robotic Waste Sorting System Market
Robotics and Automation
High-Precision Truss Robot Market
Robotics and Automation
APAC Robotic Process Automation (RPA) Market
Robotics and Automation
Metal Fabrication Robots Market
Robotics and Automation
Asia-Pacific Cloud Robotics Market
Robotics and Automation
Robotics for NDT Market
Robotics and Automation
Underwater Robot Market
Robotics and Automation
Global Machine Vision and Vision Guided Robotics Market
Robotics and Automation
Global Articulated Robot Market
Robotics and Automation
Global Adaptive Robot Market
Robotics and Automation
Hotel Robot Market
Robotics and Automation
Autonomous Navigation Robots Market
Robotics and Automation
North America Agricultural Robots and Mechatronics Market
Robotics and Automation
Global Enterprise Robotic Process Automation Market