
 Packer Bottle Market | 2026-2036
Packer Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Packer Bottle Market Outlook
The gap between premium pharmaceutical-grade and commodity food-service packer bottles is repositioning procurement criteria across the value chain. Berry Global Group leverages captive resin compounding to sustain margin control in high-barrier segments. Amcor Plc anchors its position through blow-fill-seal technology leadership for sterile applications. Gerresheimer AG dominates glass packer formats for light-sensitive formulations where polymer alternatives face stability limits.
A packer bottle is a wide-mouth cylindrical container engineered for solid dose pharmaceuticals, nutritional supplements, and granular products, typically manufactured through injection blow molding or tubular glass conversion with neck finish tolerances of ±0.25 mm to ensure capping integrity. Plastic packer bottles lead volume due to shatter resistance and lightweight logistics economics, while glass retains premium positioning for moisture-sensitive and oxygen-critical formulations. The pharmaceutical application segment commands the deepest margin pools as child-resistant closure mandates and desiccant integration requirements elevate specification complexity beyond commodity food and beverage standards.
The FDA enforces 21 CFR Part 211 cGMP requirements for pharmaceutical container closure systems, while the EU Falsified Medicines Directive mandates tamper-evident features and unique identifier serialization on all packer bottles entering European distribution. Germany's BfArM and the US FDA both tightened elemental impurity thresholds under ICH Q3D, forcing resin reformulation and supplier qualification cycles that extend new product development timelines. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York, as these jurisdictions test deposit-return frameworks that could restructure post-consumer collection economics for plastic packer formats.
Market Dynamics
Serialization mandates under the EU Falsified Medicines Directive are forcing pharmaceutical packers to retrofit filling lines with integrated track-and-trace hardware, compressing equipment replacement cycles and elevating specification complexity for container closure systems.
Growth Catalysts
- EU Falsified Medicines Directive:Tamper-evident and unique identifier requirements on all pharmaceutical packer bottles entering European distribution are mandating hardware upgrades across contract packaging facilities.
- Sterile filling operations:Germany's Rhine-Main pharmaceutical cluster drives demand for high-barrier packer formats with validated microbial ingress protection and automated blow-fill-seal integration.
- Child-resistant closure mandates:Pediatric safety regulations in multiple jurisdictions require specialized neck finishes and torque testing protocols that elevate technical barriers for commodity suppliers.
Market Restraints
- Resin formulation costs:ICH Q3D elemental impurity thresholds force reformulation of pharmaceutical-grade polymers, extending supplier qualification timelines and compressing margin pools for mid-tier converters.
- Glass supply concentration:Borosilicate and Type III glass packer production concentrates in Central European furnace operations, creating geographic vulnerability for light-sensitive formulation packaging.
- Biologic stability limits:Protein-based therapeutics require oxygen transmission rates below 0.1 cc/pkg/day, a threshold that standard polyethylene and polypropylene packer bottles cannot achieve without metallized barrier layers.
Strategic Opportunities
- India's CDSCO serialization rollout:The phased implementation of track-and-trace requirements for domestic pharmaceutical distribution creates first-mover advantage for packer suppliers with pre-validated coding systems.
- Desiccant-integrated formats:Embedded silica canister designs that eliminate separate sachet insertion steps are gaining traction in moisture-critical nutritional supplement applications.
- California EPR frameworks:Extended producer responsibility legislation testing deposit-return mechanics for plastic packaging could restructure post-consumer collection economics and favor recyclable mono-material packer designs.
Industry Challenges
- Blow-fill-seal technician scarcity:Sterile aseptic processing certification requires 18-24 month training pipelines that outpace workforce development in key pharmaceutical manufacturing clusters.
- Legacy capping line retrofit complexity:Pharmaceutical packers with ±0.25 mm neck finish tolerances often fail validation on older crimping equipment designed for ±0.5 mm commodity specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packer Bottle Market |
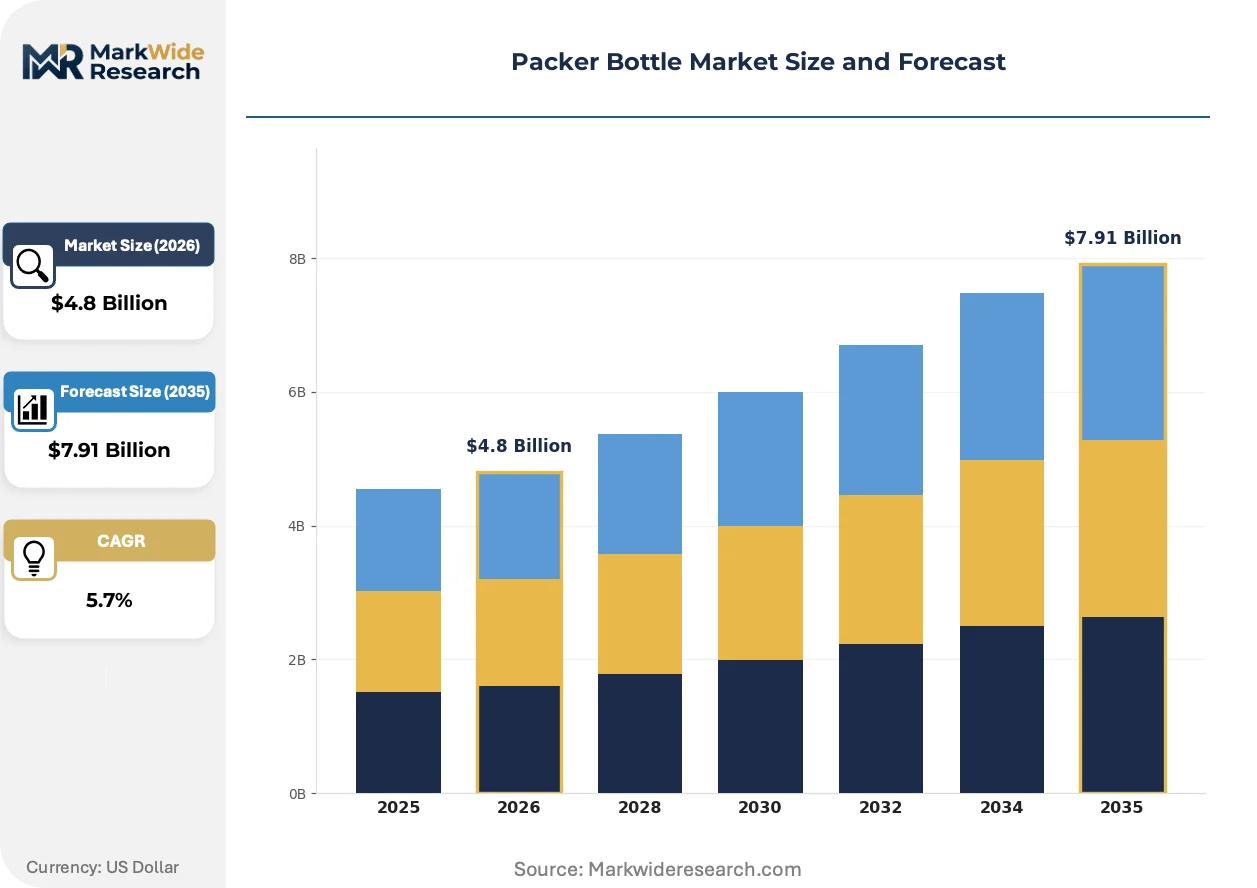
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Aluminum, Biodegradable Closure Type: Screw, Pump, Cork, Snap-On Application: Pharmaceutical, Food & Beverage, Cosmetics, Chemicals Size: Small, Medium, Large, Extra Large |
| Companies Covered | Berry Global Group, Inc., Amcor Plc, Gerresheimer AG, Alpha Packaging, Comar LLC, ALPLA Group, Silgan Holdings Inc., AptarGroup, Inc., Berlin Packaging LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packer Bottle Market Strategic Shifts
Material science convergence with digital manufacturing is collapsing the traditional trade-off between barrier performance and processing efficiency. Three developments are compressing product development timelines and redrawing competitive boundaries.
Multi-layer co-injection blow molding is unifying oxygen barrier and moisture protection in single-cycle production, eliminating secondary lamination steps. Pharmaceutical contract packers in high-humidity climates are adopting these structures for effervescent tablet formats. The technology is unifying what previously required separate equipment investments into integrated filling-line configurations.
REACH Annex XVII restrictions on phthalate plasticizers are accelerating migration to bio-based polyester alternatives for pharmaceutical-grade packer resins. Compounders must reformulate entire product families to maintain EU market access. Blow molding operations serving pediatric and geriatric dosage formats face the steepest requalification burdens.
Direct-to-pharmacy distribution models are compressing traditional wholesale channel dependencies for generic solid-dose manufacturers. Packer bottle procurement is consolidating under central pharmacy buying groups that demand lot-level serialization data and 48-hour replenishment guarantees. This pattern is most visible in Germany's Apothekenverbund networks and comparable purchasing cooperatives in the Netherlands.
Packer Bottle Market Segmentation
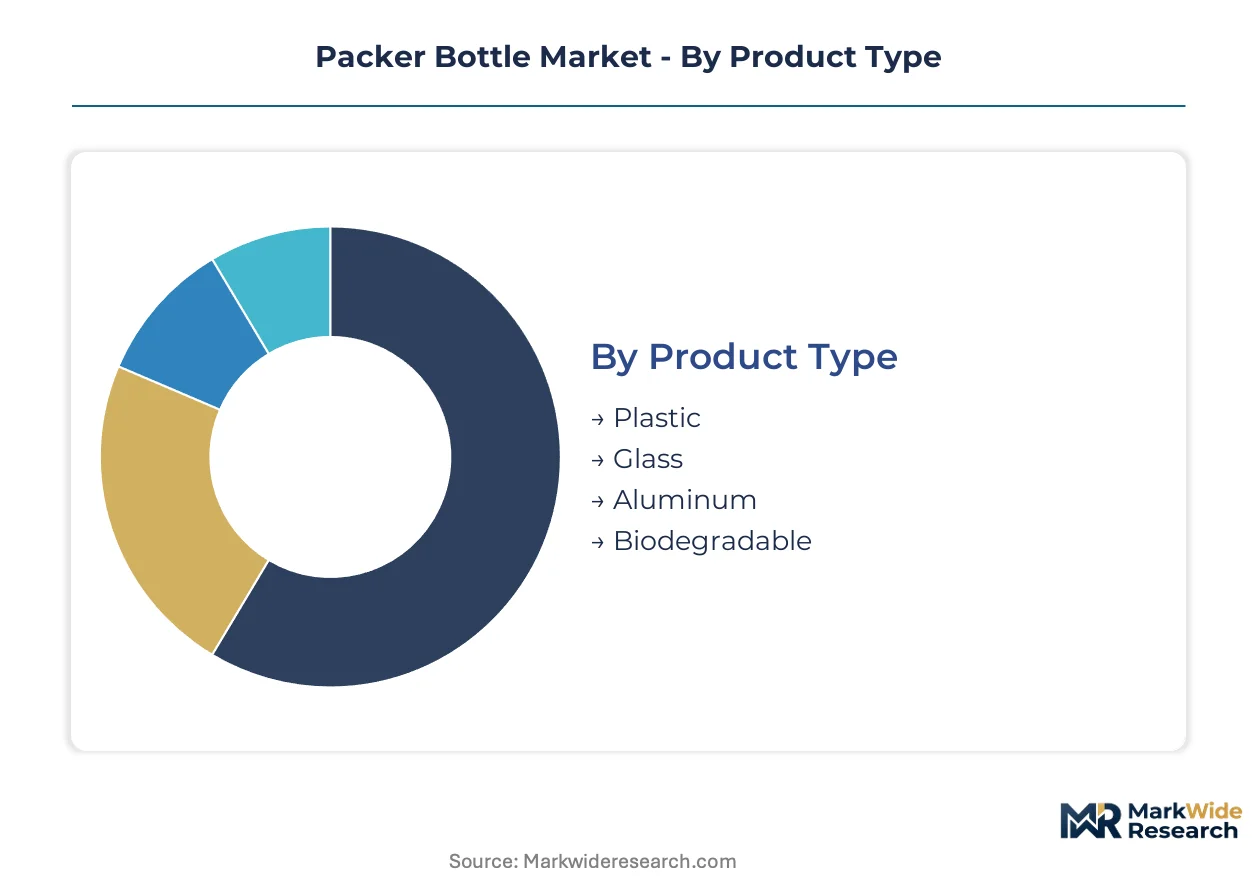
Packer bottle procurement divides sharply between regulated pharmaceutical specifications and commodity food-service tolerances. Material selection and closure engineering determine which suppliers qualify for high-margin sterile filling contracts versus bulk generic packaging.
Product Type:
Barrier performance and sterilization compatibility separate premium pharmaceutical grades from logistics-driven commodity formats.
- Plastic:High-density polyethylene and polypropylene dominate volume through injection blow molding efficiency. Demand clusters in Germany's Rhine-Main pharmaceutical corridor where blow-fill-seal integration requires validated resin lots with ICH Q3D elemental impurity documentation.
- Glass:Type III borosilicate formats retain mandatory status for light-sensitive and oxygen-critical formulations. Central European furnace concentration creates supply vulnerability for moisture-barrier applications requiring validated hydrolytic resistance.
- Aluminum:Collapsible and rigid aluminum formats serve effervescent tablet and diagnostic reagent segments requiring absolute light and moisture exclusion.
- Biodegradable:Polylactic acid and starch-based alternatives face qualification barriers in pharmaceutical applications due to moisture sensitivity and microbial degradation risks during shelf life.
Plastic leads on scale; biodegradable climbs the fastest as California and New York EPR frameworks restructure post-consumer collection economics.
Closure Type:
Child-resistant and tamper-evident mandates elevate engineering complexity beyond commodity capping economics.
- Screw:Continuous thread designs with torque-controlled application dominate pharmaceutical serialization lines. Germany's Apothekenverbund networks demand 48-hour replenishment guarantees on standardized neck finishes.
- Pump:Metered-dose and lotion pump formats serve topical pharmaceutical and cosmetic applications with viscosity-specific dip tube engineering.
- Cork:Natural and synthetic cork closures retain niche positioning for premium nutraceutical and wine-derived supplement formats requiring oxidative permeability control.
- Snap-On:Press-fit designs with audible engagement feedback serve high-speed food and chemical filling lines where capping speed exceeds screw closure throughput.
Screw closures command the deepest specification pools; pump formats gain share fastest in dermatological contract manufacturing.
Application:
Regulatory burden intensity creates four distinct procurement ecosystems with incompatible qualification timelines.
- Pharmaceutical:Solid-dose oral medications drive specification complexity through FDA 21 CFR Part 211 cGMP requirements and EU Falsified Medicines Directive serialization mandates. Child-resistant closure integration and desiccant compatibility testing extend supplier qualification cycles.
- Food & Beverage:Nutraceutical powders and granular ingredients require moisture barriers without pharmaceutical-grade documentation burdens. FDA food contact notification compliance suffices for most formats.
- Cosmetics:Skincare and personal care applications prioritize aesthetic differentiation and pump dispenser compatibility over barrier performance validation.
- Chemicals:Industrial and agricultural chemical packaging emphasizes chemical resistance and UN-certified transport durability rather than consumer safety mechanisms.
Pharmaceutical commands margin concentration; food and beverage offers volume scale with faster qualification pathways.
Size:
Filling line automation and distribution economics determine optimal format selection across dosage quantities.
- Small:Sub-50ml formats serve clinical trial supplies and pediatric dosage packaging with precision-counting automation requirements.
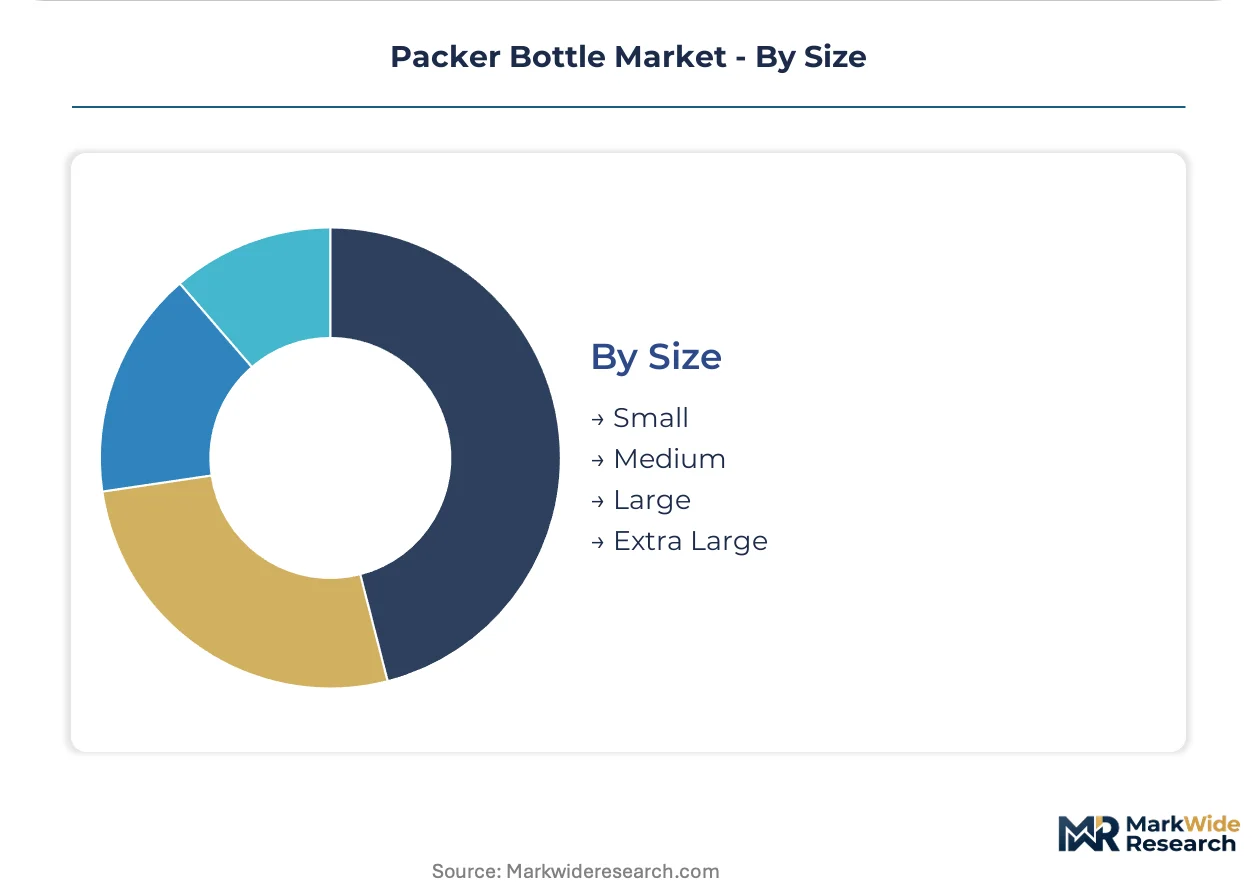
- Medium:100-250ml capacities dominate retail pharmaceutical and supplement segments with shelf-ready case pack configurations.
- Large:500ml and above formats serve institutional dispensing and bulk chemical applications with palletization efficiency priorities.
- Extra Large:Multi-liter formats address industrial chemical and food ingredient bulk distribution with drum-handling logistics integration.
Medium formats anchor volume; small formats expand most quickly in precision-dose generic launches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized blow-fill-seal technicians cluster in Germany's Rhine-Main corridor, anchoring sterile pharmaceutical packaging capacity. India's CDSCO serialization rollout and California's extended producer responsibility frameworks are redrawing qualification timelines across three continents.
United States
FDA 21 CFR Part 211 cGMP enforcement drives specification complexity for domestic pharmaceutical contract packers. California's SB 54 extended producer responsibility legislation tests deposit-return frameworks that favor recyclable mono-material designs. New Jersey's pharmaceutical corridor concentrates blow-fill-seal operations serving generic solid-dose manufacturers with 48-hour replenishment guarantees.
Germany
The Rhine-Main pharmaceutical cluster demands high-barrier packer formats with validated microbial ingress protection for sterile filling lines. BfArM's tightened ICH Q3D elemental impurity thresholds force resin reformulation and extended supplier qualification cycles. Hesse's contract packaging facilities retrofit serialization hardware to meet EU Falsified Medicines Directive mandates.
India
CDSCO's phased track-and-trace implementation for domestic pharmaceutical distribution creates first-mover advantage for suppliers with pre-validated coding systems. Maharashtra's pharmaceutical manufacturing belt concentrates oral solid-dose production requiring child-resistant closure integration. Gujarat's resin compounding sector supplies pharmaceutical-grade polymers with elemental impurity documentation.
China
NMPA serialization requirements for vaccine distribution elevate specification complexity for domestic packer bottle converters. Yangtze River Delta pharmaceutical clusters drive demand for desiccant-integrated formats in moisture-critical applications. Guangdong's injection blow molding sector scales production of high-density polyethylene formats for nutritional supplement exports.
Packer Bottle Market Competitive Environment
Top-tier vendors anchor sterile pharmaceutical-grade supply, while mid-tier converters compete on food-service and nutritional supplement volumes. The market structure stratifies across three capability tiers: integrated resin compounders with captive barrier technology, specialized glass converters serving light-sensitive formulations, and regional injection molders competing on logistics proximity. Two dominant competitive moves define positioning: backward integration into resin compounding to control ICH Q3D compliance costs, and strategic partnerships with blow-fill-seal equipment manufacturers to secure technician training pipelines.
Within the integrated polymer systems tier, Berry Global Group and Amcor Plc exemplify scale-driven positioning through captive resin operations and blow-fill-seal technology leadership. Gerresheimer AG occupies a distinct archetype as a specialized glass converter serving oxygen-critical and light-sensitive pharmaceutical applications where polymer alternatives face stability limits. These three anchors represent divergent competitive vectors: polymer barrier innovation, sterile processing integration, and premium glass stability validation.
| Leading Market Players |
|---|
| Berry Global Group, Inc. |
| Amcor Plc |
| Gerresheimer AG |
| Alpha Packaging |
| Comar LLC |
| ALPLA Group |
| Silgan Holdings Inc. |
| AptarGroup, Inc. |
| Berlin Packaging LLC |
| Others |
Value Chain & Pricing Dynamics
Polypropylene resin indices in the US Gulf Coast and Northwest Europe cascade through pharmaceutical-grade packer bottle supply chains, compressing margin pools for converters without captive compounding while amplifying pricing power for integrated resin compounders serving serialization-mandated European markets.
Pricing Analysis
Pharmaceutical contract packers face unbundled pricing for resin, closure systems, and serialization hardware versus bundled turnkey formats from integrated suppliers. Three-tier pricing structure across premium, standard, and economy levels separates ICH Q3D-validated pharmaceutical grades from food-contact commodity formats. Price differentiation hinges on elemental impurity documentation depth and blow-fill-seal line compatibility. Cost compression in mid-tier polyethylene formats is intensifying because resin reformulation cycles extend supplier qualification timelines. Generic solid-dose manufacturers in India exhibit highest price sensitivity; sterile filling operations in Germany's Rhine-Main corridor show lowest sensitivity due to specification lock-in.
Supply Chain Analysis
Single-source vulnerability sits with Central European borosilicate glass furnace operations serving light-sensitive pharmaceutical formulations. Manufacturing gravity centers on Germany, China, and India for injection blow molding capacity, with resin compounding concentrated in the US Gulf Coast and Gujarat. Pharmaceutical-grade polymer supply draws from high-density polyethylene and polypropylene feedstocks with ICH Q3D elemental certification. Tariff exposure on Chinese-molded components threatens cost structures for North American nutritional supplement packers. Distribution runs through pharmaceutical wholesale networks in Europe and direct-to-pharmacy buying groups in Germany's Apothekenverbund.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The packer bottle market functions as a stable compounder, with regulatory serialization mandates across European and Indian pharmaceutical distribution creating durable specification upgrades and recurring equipment refresh cycles.
For Market Incumbents: To counter margin compression from ICH Q3D resin reformulation costs, backward integration into pharmaceutical-grade compounding secures supply security and documentation control. Capacity addition in India's Maharashtra pharmaceutical belt captures CDSCO serialization rollout demand. Certification investment in desiccant-integrated format patents defends premium positioning against commodity converters. For New Entrants and Emerging Players: Enter via biodegradable mono-material formats targeting California's SB 54 extended producer responsibility frameworks, where deposit-return mechanics favor recyclable designs over multi-layer barrier structures. White-space concentrates in moisture-critical nutritional supplements requiring embedded silica canister integration rather than separate sachet insertion. Go-to-market through direct partnerships with blow-fill-seal equipment manufacturers accelerates sterile line validation. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized glass converters serving oxygen-critical biologic formulations where polymer alternatives face stability limits. Long-term viability rests on five-to-ten year pharmaceutical pipeline shifts toward protein-based therapeutics requiring sub-0.1 cc/pkg/day oxygen transmission rates. Acquisition targets include Central European furnace operators with validated hydrolytic resistance certification. Signal to monitor: India's phased track-and-trace implementation timeline acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply of ICH Q3D-validated polymers reduces qualification burden for European pharmaceutical clients. |
| Blow-Fill-Seal Equipment Partnership | Secured technician training pipelines address 18-24 month certification scarcity in Germany's Rhine-Main cluster. |
| Desiccant-Integrated Format Patenting | Embedded silica canister designs eliminate sachet insertion steps for moisture-critical supplement applications. |
| Serialization Hardware Pre-Validation | Pre-configured track-and-trace systems capture first-mover advantage in India's CDSCO rollout phases. |
| Mono-Material Recyclable Design Transition | California SB 54 compliance positions converters for deposit-return framework economics restructuring. |
Study Parameters
Coverage spans Germany, the United States, India, and China, with primary inputs from each market's pharmaceutical manufacturing clusters. Interviews with contract packaging operations managers, resin compounding technical directors, blow-fill-seal equipment specialists, and pharmacy buying group procurement leads combined with secondary validation from FDA 21 CFR Part 211 guidance documents, EMA Falsified Medicines Directive implementation reports, CDSCO track-and-trace circulars, and SEC filings from listed packaging converters. Bottom-up volume modeling triangulated against top-down pharmaceutical production value estimates.
Rate-of-change decomposition anchored the analytical framework across the analysis window, with volume and value outputs reflecting segmented modeling across material type, closure system, application regulatory tier, and geographic production cluster. CAGRs derived from regression against pharmaceutical output growth, serialization mandate implementation phases, and sterile filling capacity expansion. Industry-specific inputs included ICH Q3D elemental impurity threshold adoption timelines and extended producer responsibility legislative progression in California and New York.
Inputs from pharmaceutical contract packers and resin compounders were available through the study window; gaps in blow-fill-seal technician workforce development data introduce uncertainty bands around sterile capacity expansion forecasts. Forecasts reflect documented assumptions regarding regulatory implementation pacing and resin price index trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Roll Containers Market
Containers
Car Lube Container Market
Containers
Disposable Lids Market
Containers
Square Pails Market
Containers
Takeout Containers Market
Containers
2 Piece Cans Market
Containers
Packaging Bins Market
Containers
EPS Shippers Market
Containers
Clear Hinged Container Market
Containers
PVC Container Market
Containers
Acrylic Container Market
Containers
Hinged Lid Tins Market
Containers
Two Compartment Bottles Market
Containers
Container Fixed Fittings Market
Containers
Foldable Container Market
Containers
Bulk Containers Market