
 EPS Shippers Market | 2026-2036
EPS Shippers Market Size, Share, and Industry Trends Forecast 2026-2036
EPS Shippers Market Foresight
Polyurethane foam is decoupling from premium cold-chain applications as bio-based expanded polystyrene formulations close the thermal-performance gap. Sonoco leverages captive resin compounding to sustain margin control across North American pharmaceutical lanes. Cold Chain Technologies anchors its position through proprietary phase-change material integration that extends temperature-hold duration for cell-and-gene therapies. ACH Foam Technologies dominates custom-mold production for laboratory sample transport, occupying a defensible niche against commodity imports.
EPS shippers are rigid, closed-cell foam containers fabricated from expanded polystyrene beads fused under steam pressure, typically achieving thermal conductivity values between 0.030 and 0.040 W/m·K and density grades from 15 to 30 kg/m³, engineered to maintain stable internal temperatures for 24–120 hours depending on wall thickness and gel-pack configuration. Their primary purpose is protecting temperature-sensitive cargo through last-mile and mid-haul distribution where mechanical refrigeration proves uneconomical. Reusable EPS shippers lead value capture in biotechnology firm procurement programs where reverse logistics infrastructure justifies amortization across fifty-plus rotation cycles, while disposable EPS containers compete on upfront cost for single-use pharmaceutical exports from emerging manufacturing clusters. Custom EPS crates concentrate margin pools in clinical-trial logistics, where lot-specific dimensional requirements and validated qualification protocols command price premiums over standard insulated boxes.
The US FDA enforces 21 CFR 211 distribution-temperature documentation that compels pharmaceutical shippers to demonstrate container qualification, while the EU GDP guidelines and REACH chemical-registration requirements shape material-selection decisions for European-market entrants. EPA regulations on styrene monomer emissions influence domestic manufacturing siting and capital-expenditure timelines for US-based molders. Stakeholders must monitor emerging state-level extended-producer-responsibility frameworks for packaging waste, as these rules will determine whether reusable or recyclable EPS formats capture preference in next-generation procurement specifications.
Market Dynamics
Biologics cold-chain validation requirements are forcing pharmaceutical logistics operators to abandon commodity insulation in favor of performance-qualified EPS configurations with documented thermal hold-time certification.
Growth Catalysts
- Biologics shipment proliferation:Cell-and-gene therapy commercialization is expanding validated shipper procurement across clinical-trial and commercial distribution lanes.
- FDA 21 CFR 211 enforcement:Temperature-documentation mandates compel container qualification investments that favor engineered EPS over generic alternatives.
- Germany's pharmaceutical corridor:Concentrated manufacturing around Frankfurt and Mannheim generates sustained demand for custom-mold laboratory transport solutions.
Market Restraints
- Styrene monomer volatility:Petrochemical feedstock price swings compress molding margins and destabilize long-term contract pricing.
- Polyurethane foam substitution:Premium cold-chain applications increasingly specify vacuum-insulated panels for sub-zero hold requirements.
- REACH chemical-registration burden:European-market entrants face extended material-approval timelines that delay product launches.
Strategic Opportunities
- Extended-producer-responsibility frameworks:State-level packaging-waste regulations in the US will favor reusable EPS formats with reverse-logistics infrastructure.
- Phase-change material convergence:Integration of proprietary PCM layers extends temperature-hold duration for ultra-sensitive cell therapies.
- India biologics manufacturing:Emerging pharmaceutical export clusters require validated single-use shippers for temperature-sensitive API shipments.
Industry Challenges
- Thermal-validation expertise scarcity:Qualified engineers capable of executing ISTA 7E qualification protocols command premium compensation and extended recruitment cycles.
- Qualification-timeline compression:Accelerated clinical-trial startup schedules compress container-validation windows from months to weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EPS Shippers Market |
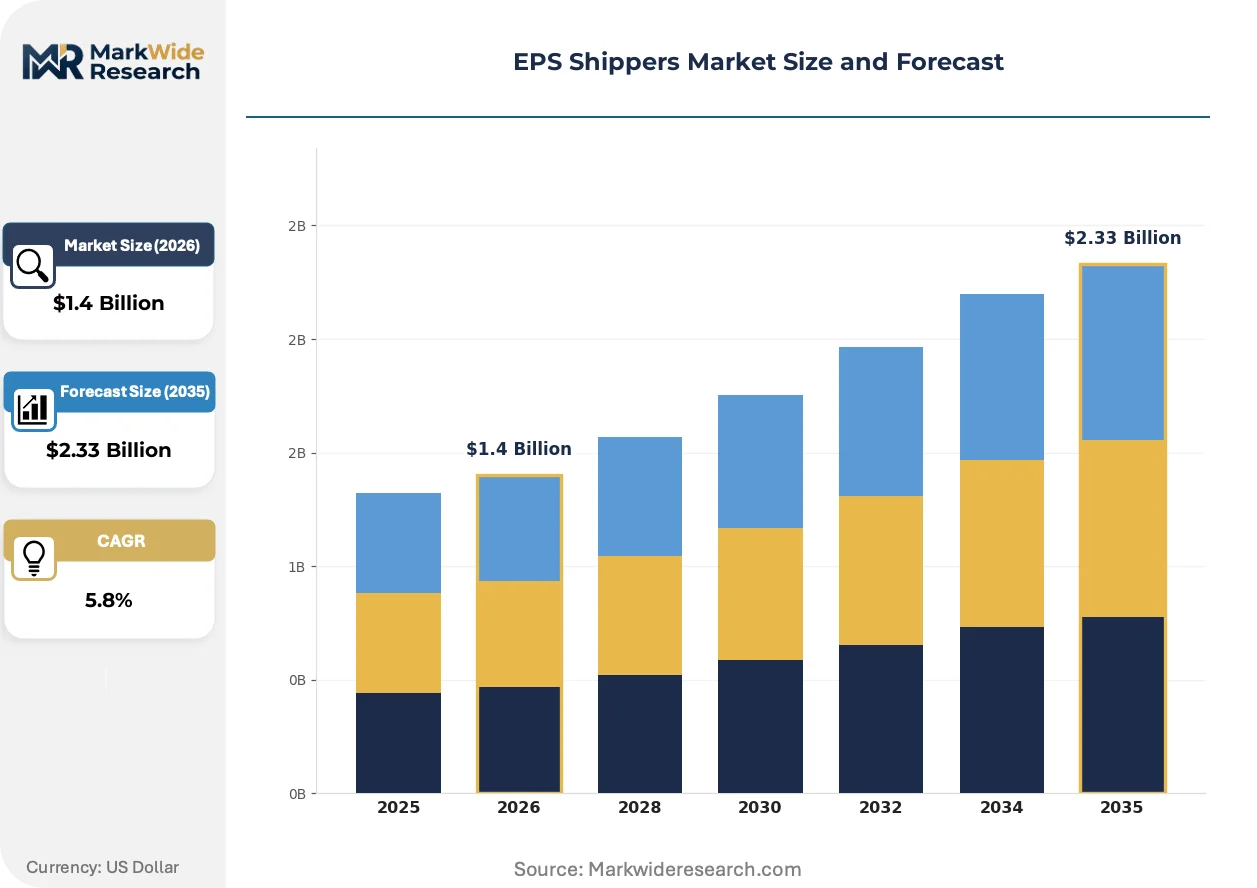
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable EPS Shippers, Disposable EPS Containers, Insulated EPS Boxes, Custom EPS Crates, Refrigerated EPS Cases Application: Pharmaceuticals, Frozen Foods, Electronics Packaging, Laboratory Samples, Perishable Goods End User: Biotechnology Firms, Food Processing Units, Medical Laboratories, Electronics Manufacturers, Chemical Plants Distribution Channel: Direct Sales, E-commerce, Wholesale Distributors, Third-Party Logistics, Retailers |
| Companies Covered | Sonoco, Cold Chain Technologies, ACH Foam Technologies, Snyder Industries, Pelican Products, Cryopak Industries, Tempack Packaging Solutions, EcoCool, American Aerogel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EPS Shippers Market Shifts & Advancements
Bio-based material formulations and smart tracking integration are redefining performance benchmarks for temperature-controlled packaging, collapsing the historical trade-off between thermal efficiency and environmental compliance.
Expanded polystyrene bead chemistry incorporating plant-derived feedstocks is decentralizing premium cold-chain applications away from petroleum-dependent insulation. Pharmaceutical contract manufacturers in the Netherlands and Denmark are adopting these formulations for validated shipper production. The technology is decentralizing supply-chain risk by reducing exposure to fossil-fuel price volatility while maintaining thermal conductivity performance.
REACH chemical-registration requirements are tightening material-traceability obligations across European pharmaceutical logistics. Molders must now document styrene monomer sourcing through full supply-chain tiers. Custom-mold clinical-trial shippers face the steepest compliance burden, driving consolidation toward vertically integrated compounders with captive resin operations.
Reverse-logistics infrastructure investment is reshaping procurement economics for biotechnology firms with recurring sample flows. Genomics laboratories in Massachusetts and California are deploying track-and-trace-enabled reusable shippers across fifty-plus rotation cycles. The model is displacing single-use procurement in high-frequency therapeutic areas where patient enrollment justifies capital deployment.
EPS Shippers Market Segmentation
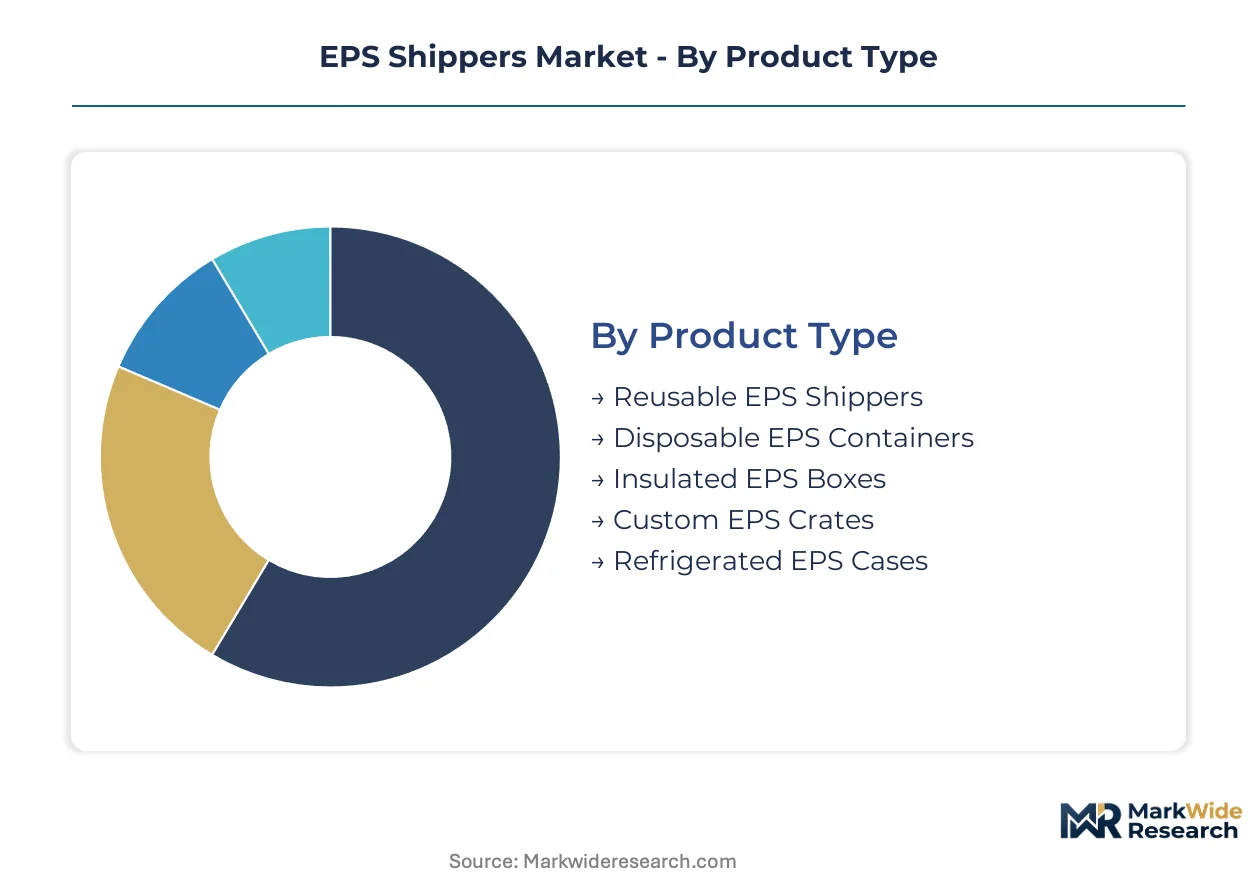
EPS shipper procurement hinges on rotation-cycle economics and validation requirements that vary sharply across temperature-sensitive cargo categories. Segmentation reveals where bio-based formulations command premiums versus where commodity disposables dominate.
Product Type:
Buyers weigh amortization math against qualification burden when selecting between rotation-ready and single-use formats.
- Reusable EPS Shippers:Engineered for fifty-plus rotation cycles with integrated track-and-trace hardware. Massachusetts genomics laboratories and California cell-therapy developers anchor procurement volume through captive reverse-logistics networks.
- Disposable EPS Containers:Single-use molded containers optimized for emerging-market pharmaceutical exports where return infrastructure remains uneconomical. India's biologics manufacturing clusters drive demand acceleration as API shipment volumes multiply.
- Insulated EPS Boxes:Standardized wall-thickness configurations for 24–72 hour thermal hold.
- Custom EPS Crates:Lot-specific dimensional engineering for clinical-trial protocols with ISTA 7E qualification documentation.
- Refrigerated EPS Cases:Hybrid designs incorporating mechanical cooling for extended-route pharmaceutical distribution.
Volume sits with disposable formats; growth tilts toward reusable systems as biotechnology firms deploy reverse-logistics infrastructure.
Application:
Cargo temperature sensitivity and regulatory exposure determine specification intensity across use cases.
- Pharmaceuticals:FDA 21 CFR 211 mandates drive container qualification investments for commercial biologics distribution. Cell-and-gene therapy commercialization is expanding validated shipper procurement across clinical-trial and commercial lanes.
- Laboratory Samples:Custom-mold configurations with documented thermal hold-time certification for diagnostic specimen integrity. Germany's pharmaceutical corridor around Frankfurt and Mannheim concentrates demand for precision-mold transport solutions.
- Frozen Foods:Commodity-grade insulation for last-mile grocery delivery with shorter hold-time requirements.
- Electronics Packaging:Static-dissipative formulations for semiconductor component shipment.
- Perishable Goods:Agricultural export applications with moderate temperature-control demands.
Pharmaceutical applications capture margin concentration; laboratory diagnostics are expanding most quickly as precision medicine sample flows multiply.
End User:
Procurement sophistication correlates with regulatory compliance burden and shipment frequency.
- Biotechnology Firms:High-frequency therapeutic areas with patient enrollment justifying capital deployment into reusable shipper fleets and PCM-integrated configurations.
- Medical Laboratories:Custom-mold clinical-trial shippers with lot-specific dimensional requirements and validated qualification protocols commanding price premiums.
- Food Processing Units:Cost-driven procurement for temperature-sensitive ingredient distribution.
- Electronics Manufacturers:Cleanroom-compatible formulations for microelectronic component protection.
- Chemical Plants:Hazardous-material transport configurations with secondary containment features.
Biotechnology firms dominate premium-tier procurement; medical laboratories are gaining share fastest as diagnostic decentralization accelerates specimen transport volumes.
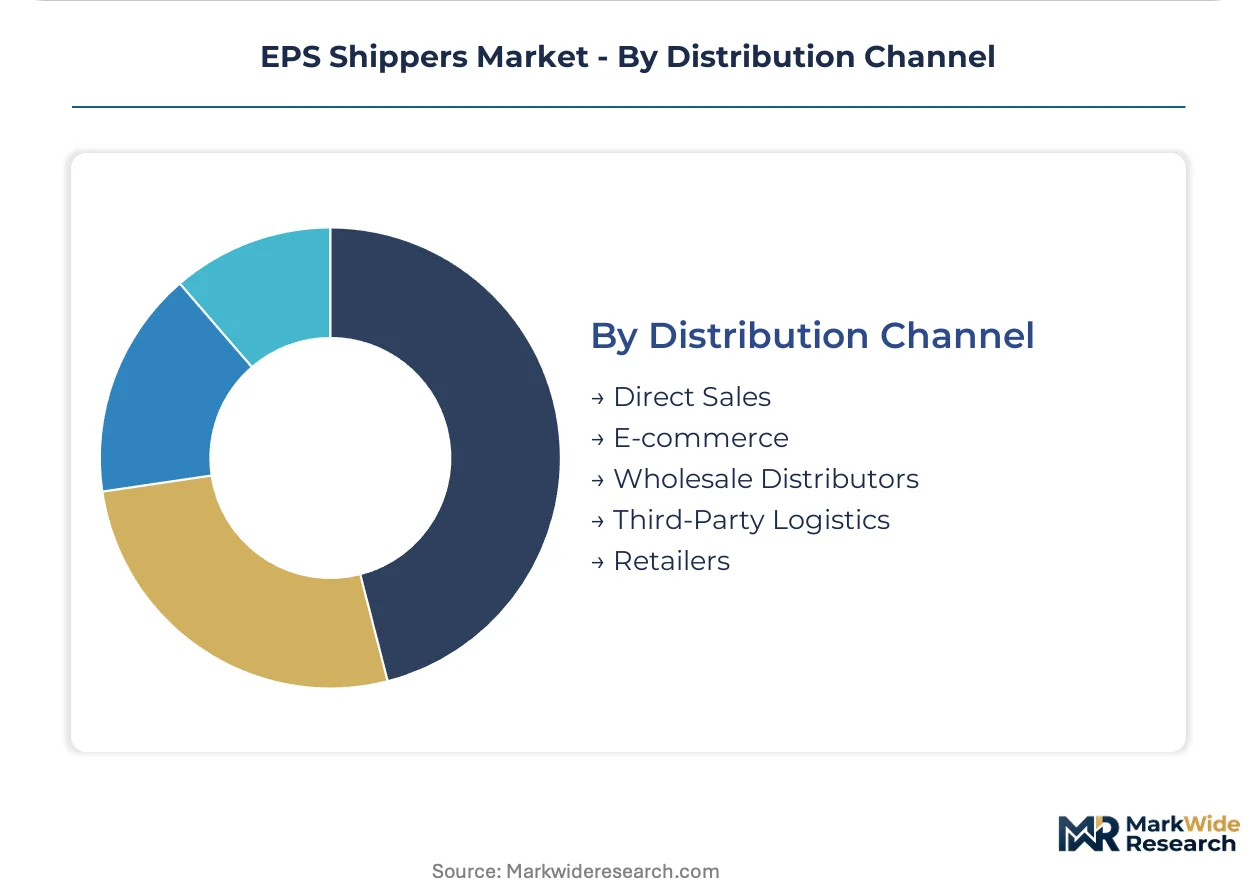
Distribution Channel:
Channel selection reflects buyer scale and qualification-timeline pressure.
- Direct Sales:Large-account relationships with pharmaceutical contract manufacturers requiring accelerated validation timelines and custom engineering support.
- Third-Party Logistics:Integrated cold-chain providers bundling container procurement with lane-management services for mid-scale biotechnology shippers.
- E-commerce:Small-lot procurement for research institutions and startup therapeutic developers.
- Wholesale Distributors:Inventory-positioned stock for standard-format pharmaceutical shippers.
- Retailers:Consumer-facing insulated packaging for specialty food and wine applications.
Direct sales anchor value capture; third-party logistics channels are climbing the fastest as outsourcing consolidates procurement decision-making.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Pharmaceutical Export Zones and China's Free Trade Zones are concentrating biologics manufacturing investment, reshaping where validated EPS shippers deploy across temperature-controlled logistics corridors.
United States
Massachusetts genomics laboratories and California cell-therapy developers anchor reusable shipper procurement through captive reverse-logistics networks. FDA 21 CFR 211 enforcement compels container qualification investments that favor engineered EPS configurations over generic alternatives. The Greater Boston biotechnology cluster sustains demand for track-and-trace-enabled rotation systems.
Germany
Frankfurt and Mannheim concentrate pharmaceutical manufacturing corridors generating sustained demand for custom-mold laboratory transport solutions. ECHA REACH chemical-registration requirements tighten material-traceability obligations across European pharmaceutical logistics. Bavarian molders with captive resin compounding operations capture margin control through vertically integrated supply chains.
India
Hyderabad and Bengaluru biologics manufacturing clusters drive demand acceleration for validated single-use shippers as API shipment volumes multiply. CDSCO temperature-validation guidelines align with international GDP standards for pharmaceutical exports. Pharmaceutical Export Zones in Telangana and Karnataka subsidize cold-chain infrastructure investment.
China
Yangtze River Delta pharmaceutical contract manufacturers expand validated shipper procurement for cell-and-gene therapy commercialization. NMPA distribution-temperature documentation rules tighten compliance requirements for insulated container imports. Shanghai Free Trade Zone logistics hubs concentrate cross-border biologics distribution infrastructure.
Netherlands
Rotterdam and Amsterdam anchor European pharmaceutical distribution with GDP-compliant cold-chain consolidation facilities. EMA guidelines on temperature-controlled transport shape material-selection decisions for continental market entrants. Randstad logistics providers bundle container procurement with lane-management services for mid-scale biotechnology shippers.
EPS Shippers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with qualification-intensive pharmaceutical applications favoring established players while commodity food logistics fragment toward regional molders. The vendor base organizes around three strategic archetypes: resin-integrated compounders controlling feedstock costs, PCM-integrated system houses extending thermal performance, and custom-mold specialists capturing clinical-trial premiums. Capacity expansion and proprietary phase-change material licensing represent the dominant competitive moves reshaping positioning.
Among North American fabricators, Sonoco Products Company and Cold Chain Technologies exemplify divergent strategic paths within the temperature-controlled packaging archetype. ACH Foam Technologies occupies a position in the custom-mold specialist tier alongside Snyder Industries. Pelican Products represents the diversified industrial conglomerate archetype competing across multiple protective packaging verticals.
| Leading Market Players |
|---|
| Sonoco |
| Cold Chain Technologies |
| ACH Foam Technologies |
| Snyder Industries |
| Pelican Products |
| Cryopak Industries |
| Tempack Packaging Solutions |
| EcoCool |
| American Aerogel |
| Others |
Supply & Pricing Matrix
Styrene monomer futures volatility cascades through EPS shipper manufacturing into three distinct pricing tiers that separate validated pharmaceutical configurations from commodity food-logistics formats. Contract manufacturers with captive resin compounding operations capture margin insulation unavailable to molders exposed to spot feedstock markets.
Pricing Analysis
Lead-time compression commands premium pricing for custom-mold clinical-trial shippers requiring ISTA 7E qualification documentation within compressed validation windows. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with biotechnology procurement programs showing lowest price sensitivity due to patient-enrollment-driven urgency. Cost compression in disposable formats is intensifying as Indian biologics exporters scale API shipment volumes. Spot inventory of standardized insulated boxes trades at discount to contracted rotation-ready systems with integrated track-and-trace hardware.
Supply Chain Analysis
Expandable polystyrene bead supply rests on petrochemical producers in Germany, the United States, and China with integrated styrene monomer production. Raw material dependencies span styrene monomer, pentane blowing agents, and nucleating additives with documented REACH traceability. Single-source vulnerability concentrates in specialty-grade beads for pharmaceutical-validated applications requiring lot-level pedigree documentation. Distribution runs through regional molding clusters proximate to Frankfurt, Massachusetts, and Hyderabad pharmaceutical corridors to minimize finished-goods freight exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bio-based expanded polystyrene formulations are displacing petroleum-dependent insulation across premium cold-chain applications, compressing the window for legacy feedstock-dependent producers to reposition.
For Market Incumbents: Lock in backward integration into captive resin compounding to insulate margin structures from styrene monomer volatility, while accelerating PCM-integrated system development to defend against vacuum-insulated panel substitution in cell-and-gene therapy lanes. Sonoco's North American pharmaceutical lane dominance demonstrates the defensive value of upstream control over bead chemistry. For New Entrants and Emerging Players: Launch via third-party logistics channel partnerships targeting mid-scale biotechnology shippers in India's Telangana and Karnataka Pharmaceutical Export Zones, where validated single-use shipper demand outpaces domestic molding capacity. White-space concentration sits with custom-mold clinical-trial formats for decentralized precision-medicine specimen flows. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated compounders with captive resin operations in Germany's Bavarian molding corridor, where REACH compliance burdens are accelerating consolidation toward integrated players. The inflection signal to watch is state-level extended-producer-responsibility framework adoption in Massachusetts and California, which will determine reusable format preference in next-generation procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Resin Compounding Investment | Insulates margin control from styrene monomer volatility across pharmaceutical lanes. |
| Proprietary PCM Integration | Extends temperature-hold duration for ultra-sensitive cell-and-gene therapy shipments. |
| Reverse-Logistics Infrastructure Buildout | Enables fifty-plus rotation-cycle economics for Massachusetts genomics laboratories. |
| REACH-Compliant Material Traceability | Mandatory for European pharmaceutical corridor market access under ECHA guidelines. |
| Clinical-Trial Custom-Mold Capacity | Captures lot-specific dimensional premiums from decentralized diagnostic specimen flows. |
Research Methodology
FDA 21 CFR 211 guidance documents, EMA GDP guidelines, and customs trade data formed the secondary backbone for regulatory and volume validation. Primary interviews with pharmaceutical logistics operators, cold-chain packaging engineers, and biotechnology procurement directors combined with secondary sources through bottom-up and top-down triangulation. Stakeholder conversations captured rotation-cycle economics, validation-timeline compression effects, and procurement specification evolution across clinical-trial and commercial distribution lanes.
Historical trendline analysis of validated shipper procurement volumes anchored the forecast framework across the analysis window. Segmentation dimensions modeled include product type, application, end user, and distribution channel, with additional granularity on temperature-hold duration tiers and qualification protocol intensity. CAGRs derived from curve-fitting procedures applied to disclosed pharmaceutical shipment volumes and biologics manufacturing capacity expansion announcements. Forecast inputs incorporated CDSCO alignment with international GDP standards and NMPA distribution-temperature documentation rules.
Styrene monomer price spikes, accelerated state-level extended-producer-responsibility adoption, and vacuum-insulated panel cost reductions are the dominant revision risks to modeled outcomes. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
HDPE Containers Market
Containers
Wooden Crates Market
Containers
Light Density Polyethylene (LDPE) Bottles Market
Containers
Snap Secure Containers Market
Containers
Single Wall Jars Market
Containers
Metal Crates Market
Containers
Trays Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
Mini Spray Bottles Market
Containers
Oblong Container Market
Containers
Container Liner Market
Containers
Concentrate Containers Market
Containers
Stackable Container Market
Containers
Screw Top Pails Market
Containers
In-Mold Labelled Containers Market
Containers
Spout Containers Market