
 Container Fixed Fittings Market | 2026-2036
Container Fixed Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
Container Fixed Fittings Market Insights
ISO 1496 and CSC certification cycles is reorganizing supplier hierarchies in container fixed fittings, elevating manufacturers with in-house testing laboratories. China International Marine Containers leverages captive steel forging capacity to control corner casting supply chains. Singamas Container Holdings sustains cost leadership through integrated stamping and galvanizing lines in Guangdong. Maersk Container Industry differentiates via proprietary sealing systems engineered for reefer container door assemblies.
Container fixed fittings comprise mechanically fastened hardware permanently affixed to steel box structures, including corner castings rated to 86,000 kg stacking loads and locking bars fabricated from Q345 low-alloy steel with zinc-nickel plating. These components secure structural integrity during intermodal handling and ocean transit. Corner castings dominate value pools due to forging complexity and metallurgical certification requirements, while stainless steel hinges for reefer applications command premium positioning amid corrosion resistance specifications. Aluminum side rails gain traction in weight-sensitive modular structures where payload optimization overrides material cost.
The International Maritime Organization's CSC convention and China's SAMR enforcement of GB/T 1835 govern corner casting dimensional tolerances and load-bearing certifications, directly filtering factory eligibility. The EU F-Gas Regulation and REACH compliance on zinc alloy surface treatments reshape material selection for European-bound container fleets. Stakeholders must monitor divergence between Asian GB standards and European EN 12079 certification paths as dual-compliance costs reshape competitive economics.
Market Dynamics
Freight carriers expanding refrigerated and specialized fleets are tightening material specifications for corner castings and door assemblies, forcing foundries to upgrade metallurgical testing capabilities to meet stacked certification requirements under ISO 1496 and China's GB/T 1835.
Growth Catalysts
- Reefer fleet expansion:Cold chain logistics operators in Brazil and Southeast Asia are retrofitting dry containers with stainless steel hinges and proprietary sealing systems to capture pharmaceutical and fresh produce volumes.
- F-Gas Regulation:The EU's tightening requirements on fluorinated gases are accelerating demand for corrosion-resistant door hardware that maintains thermal integrity without high-global-warming-potential refrigerants.
- East Asian manufacturing concentration:Steel forging clusters around Shanghai and Ningbo provide captive corner casting supply to domestic container builders, compressing lead times for ISO-certified components.
Market Restraints
- Aluminum price volatility:Weight-sensitive modular structures depend on aluminum side rails, exposing fabricators to London Metal Exchange fluctuations that compress margin on premium lightweight fittings.
- Forging capacity concentration:Corner casting production concentrates in Chinese integrated steel mills, creating single-source vulnerability for European and North American container assemblers.
- Zinc-nickel plating limitations:Q345 low-alloy steel locking bars face coating adhesion challenges in high-salinity routes, restricting deployment on Asia-Australia and Asia-Middle East lanes.
Strategic Opportunities
- Indian port infrastructure:Jawaharlal Nehru Port and Mundra Port expansion projects create demand for high-stacking-load corner castings as domestic container manufacturing scales under PLI scheme incentives.
- Modular data center containers:Edge computing deployments are repurposing container structures with aluminum side rails and custom hinge assemblies for rapid field deployment.
- Dual carbon goals:China's MEE enforcement of carbon intensity benchmarks is favoring electric-arc-furnace foundries with lower-emission corner casting output for export-bound fleets.
Industry Challenges
- Metallurgical certification timelines:CSC and GB/T 1835 testing cycles extend 14-18 weeks, delaying new supplier qualification and freezing procurement flexibility during demand spikes.
- Sealing system integration:Proprietary reefer door designs from incumbent manufacturers create interoperability barriers for aftermarket hardware providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Container Fixed Fittings Market |
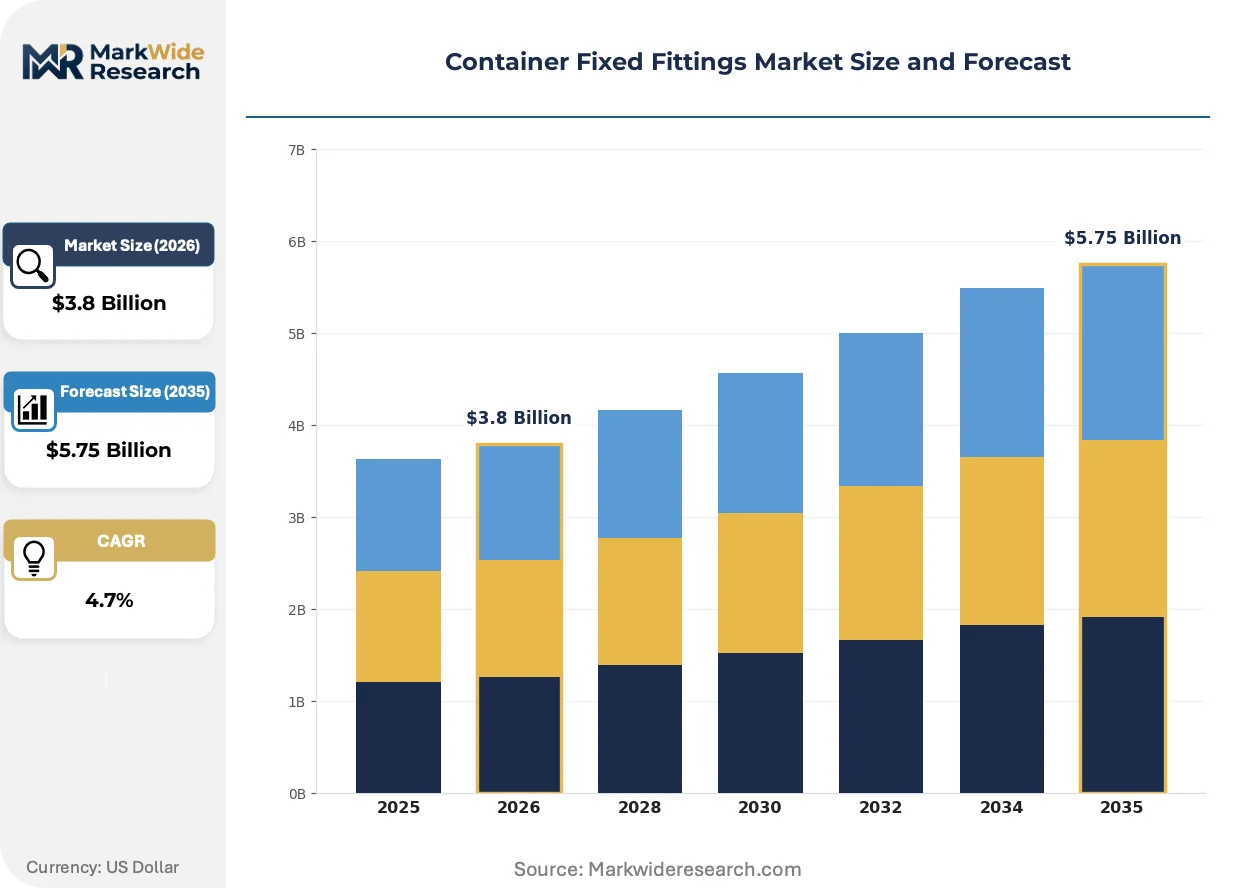
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corner Castings, Locking Bars, Side Rails, Door Handles, Hinges Material: Stainless Steel, Aluminum, Nylon, Zinc Alloy, Brass Application: Shipping Containers, Storage Units, Mobile Homes, Modular Structures, Equipment Cases Customer Type: Freight Carriers, Leasing Companies, Logistics Providers, Construction Firms, Equipment Manufacturers |
| Companies Covered | China International Marine Containers, Singamas Container Holdings, CXIC Group Containers Company Limited, Dong Fang International Container (Hong Kong), Maersk Container Industry, W&K Container, Sea Box, CARU Containers, Stoughton Trailers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Container Fixed Fittings Market Trends and Innovations
Digital traceability requirements and lightweighting pressures are splitting the supplier base between integrated foundries with captive testing labs and specialized coating houses serving niche corrosion specifications.
Aluminum-magnesium alloy side rails are fragmenting the traditional steel-dominated market for weight-sensitive container structures. Pharmaceutical logistics operators and military modular deployers are specifying these alloys for payload optimization. The technology is fragmenting procurement patterns as buyers separate structural from non-structural fitting categories to manage cost-performance trade-offs.
REACH enforcement on hexavalent chromium surface treatments is eliminating traditional zinc chromate plating for European-bound container fleets. Coating houses in Guangdong and Zhejiang are converting to trivalent chromium and zinc-nickel systems to maintain market access. Stainless steel hinge assemblies for reefer applications are capturing premium positioning as compliant alternatives to plated carbon steel.
Carrier procurement departments are consolidating supplier panels around vertically integrated foundries with in-house ISO 1496 testing. Maersk Line and CMA CGM are reducing approved corner casting vendors from twelve to four across their respective fleets. This concentration is most visible on Asia-Europe routes where dual GB and EN 12079 compliance requirements filter out smaller regional suppliers.
Container Fixed Fittings Market Segmentation
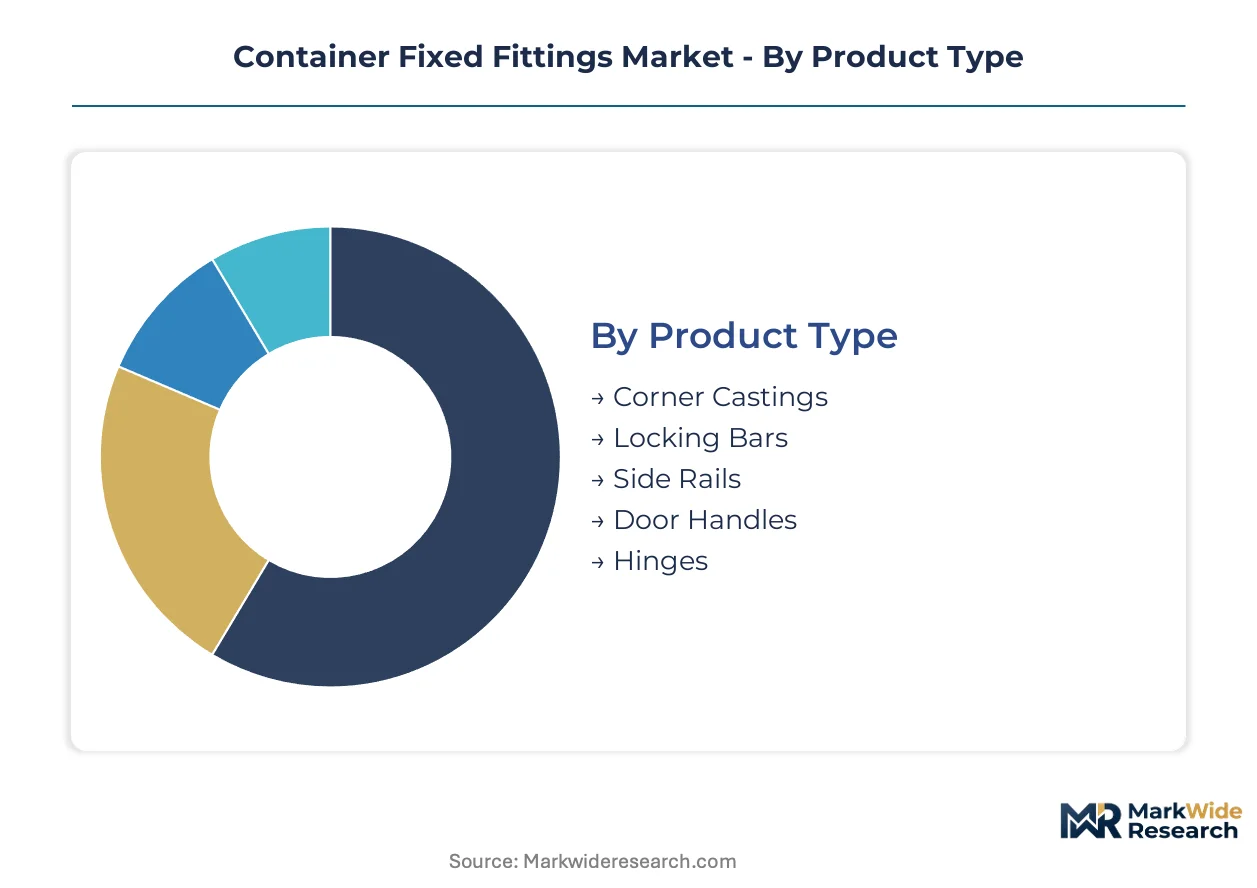
Product differentiation in container fixed fittings hinges on metallurgical certification thresholds and weight-performance trade-offs. Procurement patterns diverge sharply between freight carriers prioritizing stacking-load ratings and modular builders optimizing for payload efficiency.
Product Type:
Aluminum-magnesium alloys and composite door hardware are displacing traditional steel configurations in weight-sensitive applications, pressuring established forging categories.
- Corner Castings:Forged steel components rated to 86,000 kg stacking loads require GB/T 1835 and ISO 1496 metallurgical certification. Demand concentrates at Shanghai and Ningbo steel clusters serving CIMC and Singamas production lines, with electric-arc-furnace foundries gaining preference under China's MEE carbon intensity enforcement.
- Locking Bars:Q345 low-alloy steel bars with zinc-nickel plating secure container doors during intermodal handling. Pharmaceutical reefer fleets in Brazil and Southeast Asia are retrofitting dry boxes with corrosion-resistant variants to meet EU F-Gas thermal integrity requirements without high-GWP refrigerants.
- Side Rails:Structural aluminum extrusions for modular data center containers.
- Door Handles:Stainless steel and zinc alloy hardware for standard and reefer door assemblies.
- Hinges:Stainless steel assemblies capturing premium positioning amid REACH hexavalent chromium restrictions on plated carbon steel.
Corner castings retain volume leadership; hinges hold the steepest expansion curve.
Material:
Cost tiers stratify sharply between commodity steel forgings and certified corrosion-resistant alloys required for refrigerated and pharmaceutical logistics.
- Stainless Steel:Austenitic grades for reefer hinges and door hardware deliver salt-spray resistance exceeding 1,000 hours. Maersk Line and CMA CGM procurement panels are consolidating approved vendors around foundries with captive ISO 1496 testing laboratories, filtering out regional suppliers lacking dual GB and EN 12079 compliance.
- Aluminum:6061 and 5083 alloys for side rails in military modular deployers and edge computing containers. Jawaharlal Nehru Port and Mundra Port expansion under India's PLI scheme is scaling domestic demand for lightweight structural fittings.
- Nylon:Glass-reinforced polymer handles and non-structural hardware.
- Zinc Alloy:Die-cast door hardware facing REACH-driven conversion to trivalent chromium surface treatments.
- Brass:Marine-grade hardware for high-salinity Asia-Australia routes.
Stainless steel dominates revenue contribution; aluminum is climbing the fastest on payload optimization demand.
Application:
Volume concentration tracks container manufacturing geography, while emerging applications fragment procurement specifications across unrelated end-use industries.
- Shipping Containers:Standard dry and refrigerated boxes drive corner casting and locking bar procurement. Freight carrier fleet expansion in Southeast Asia and Brazil is tightening material specifications, forcing foundry upgrades to meet stacked certification requirements.
- Storage Units:Modular self-storage containers for urban logistics.
- Mobile Homes:Residential container structures with custom hinge and rail specifications.
- Modular Structures:Edge computing and telecommunications containers specify aluminum side rails for rapid field deployment. Dual carbon goals in China's steel sector are favoring lower-emission foundry output for export-bound modular fleets.
- Equipment Cases:Military and aerospace protective containers with corrosion-resistant hardware.
Shipping containers retain volume leadership; modular structures hold the steepest expansion curve.
Customer Type:
Procurement consolidation by major carriers is reducing supplier panels and elevating vertically integrated foundries over specialized coating houses.
- Freight Carriers:Maersk Line and CMA CGM have reduced approved corner casting vendors from twelve to four, concentrating procurement around manufacturers with in-house testing capabilities. CSC and GB/T 1835 certification cycles extending 14-18 weeks are freezing procurement flexibility during demand spikes.
- Leasing Companies:Triton International and Textainer specify standardized hardware for fleet interoperability.
- Logistics Providers:Cold chain operators retrofitting dry containers with stainless steel hinges and proprietary sealing systems.
- Construction Firms:Modular builders sourcing aluminum side rails for weight-sensitive structures exposed to London Metal Exchange price volatility.
- Equipment Manufacturers:Military and telecommunications container assemblers with custom hinge specifications.
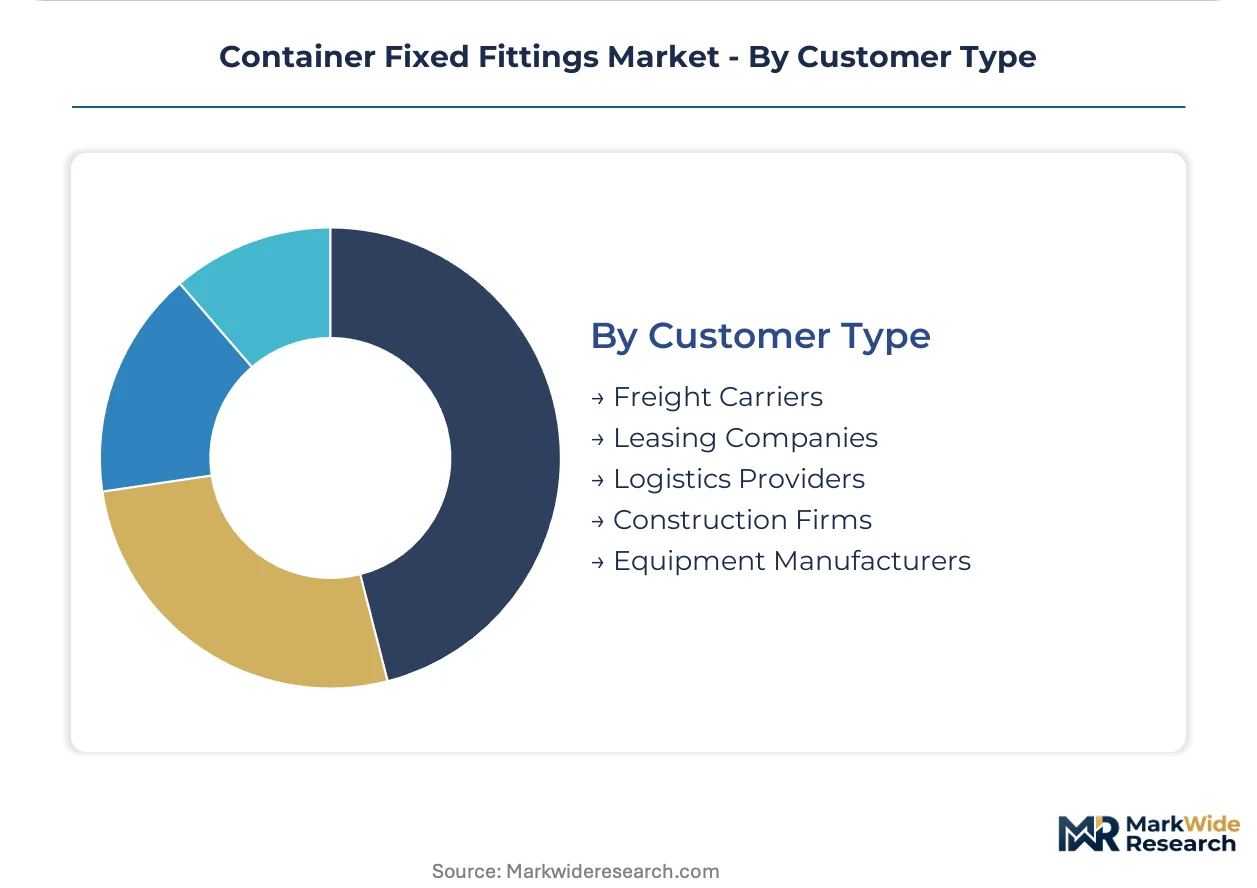
Freight carriers retain volume leadership; logistics providers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangshan Deep Water Port underwrites China's dominance in container fixed fittings procurement, with its automated terminals handling over 47 million TEU annually and demanding ISO 1496-certified corner castings at scale.
China
Shanghai and Ningbo steel forging clusters supply captive corner casting capacity to domestic container builders. SAMR enforcement of GB/T 1835 dimensional tolerances filters factory eligibility, while MEE carbon intensity benchmarks favor electric-arc-furnace foundries for export-bound fleets. The Pearl River Delta hosts integrated stamping and galvanizing lines serving Guangdong-based assembly plants.
Germany
The Port of Hamburg's intermodal terminals drive demand for corrosion-resistant locking bars on Asia-Europe routes. ECHA REACH restrictions on hexavalent chromium surface treatments eliminate traditional zinc chromate plating, forcing conversion to trivalent chromium and zinc-nickel systems. The Ruhr industrial region concentrates coating houses serving European-bound container fleets.
United States
The Port of Los Angeles-Long Beach complex sustains procurement of high-stacking-load corner castings for trans-Pacific trade lanes. EPA oversight of surface coating emissions shapes material selection for domestic container manufacturing. The Gulf Coast petrochemical corridor generates demand for specialized reefer hardware serving chemical and pharmaceutical cold chains.
India
Jawaharlal Nehru Port and Mundra Port expansion projects create demand for certified corner castings as domestic container manufacturing scales. BIS standards alignment with ISO 1496 governs metallurgical certification for local foundries. The Gujarat industrial corridor hosts emerging steel forging capacity under PLI scheme incentives.
Brazil
Santos Port's pharmaceutical cold chain infrastructure drives retrofit demand for stainless steel hinges and proprietary sealing systems. ANVISA regulations on temperature-controlled logistics tighten hardware specifications for reefer conversions. The São Paulo industrial belt concentrates logistics providers retrofitting dry containers for fresh produce exports.
Container Fixed Fittings Market Competitive Landscape
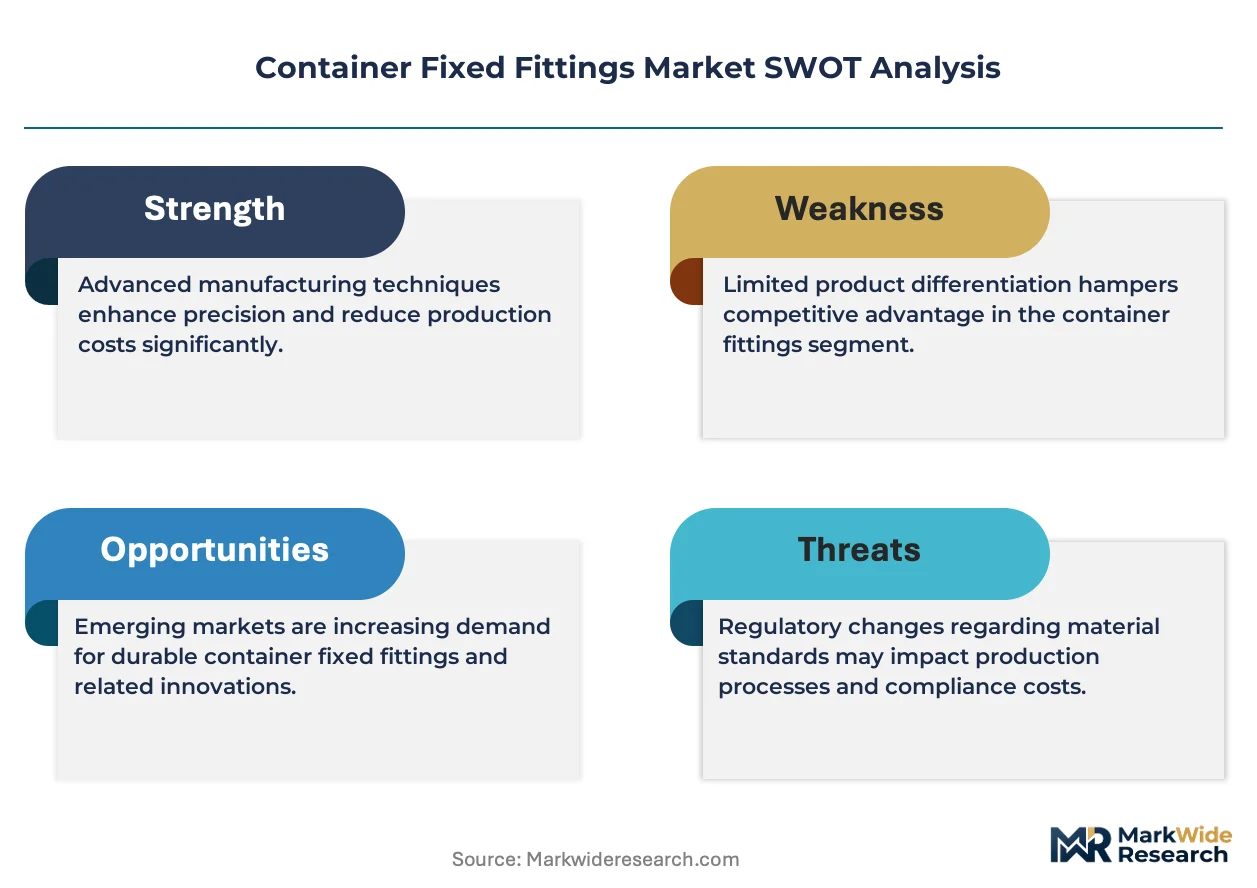
Listed leaders compete with private specialists across certification capabilities, with publicly traded container builders leveraging captive steel forging capacity while independent foundries compete on coating specialization and regional compliance expertise. The supplier base organizes around three archetypes: integrated steel mills with in-house testing laboratories, specialized coating houses serving niche corrosion specifications, and modular hardware assemblers sourcing certified castings. Consolidation pressures favor backward integration into metallurgical testing, while REACH and F-Gas regulatory divergence rewards coating houses with dual-compliance capabilities.
Among Asia-Pacific-based fabricators, China International Marine Containers and Singamas Container Holdings occupy positions reflecting scale-driven foundry integration, while Maersk Container Industry exemplifies the premium-tier vector through proprietary sealing system development. These three entities represent distinct competitive postures: captive supply chain control, cost-optimized integrated production, and differentiated reefer hardware engineering.
| Leading Market Players |
|---|
| China International Marine Containers |
| Singamas Container Holdings |
| CXIC Group Containers Company Limited |
| Dong Fang International Container (Hong Kong) |
| Maersk Container Industry |
| W&K Container |
| Sea Box |
| CARU Containers |
| Stoughton Trailers |
| Others |
Pricing and Supply Chain Analysis
Aluminum-magnesium alloy substitution for traditional steel side rails simultaneously redistributes forging demand toward Guangdong and Zhejiang coating houses while compressing margin pools on commodity corner castings. This material shift rewards suppliers with dual GB and EN 12079 compliance capabilities while penalizing single-certification foundries.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement panels. Premium stainless steel hinges for reefer applications command spreads over zinc-nickel plated Q345 bars due to REACH hexavalent chromium restrictions. Price differentiation hinges on ISO 1496 certification status and captive testing laboratory access. Pricing pressure stems from Maersk Line and CMA CGM vendor consolidation reducing approved corner casting suppliers. Leasing companies exhibit highest price sensitivity; pharmaceutical cold chain operators show lowest.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Ningbo ports shape procurement economics for European and North American container assemblers. Supply concentrates in China, India, and Germany. Raw material flows draw from Q345 low-alloy steel billets, aluminum 6061 extrusions, and zinc-nickel plating chemistries. Single-source vulnerability concentrates in Chinese integrated steel mills controlling corner casting forging. Distribution runs through captive supply chains at CIMC and Singamas, with modular hardware assemblers sourcing certified castings from approved vendor panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as aluminum-magnesium alloys fragment traditional steel-dominated structural categories and modular data center containers reroute demand toward lightweight rail specifications.
For Market Incumbents: Compound metallurgical certification advantages by upgrading in-house ISO 1496 testing capabilities before CSC and GB/T 1835 cycles extend further. Secure electric-arc-furnace foundry partnerships under China's MEE carbon intensity enforcement to defend position against lower-emission entrants. Backward integration into zinc-nickel plating lines insulates margin from Guangdong coating house volatility. For New Entrants and Emerging Players: Anchor in India's Jawaharlal Nehru Port and Mundra Port expansion corridors where PLI scheme incentives scale domestic container manufacturing without entrenched supplier relationships. Target modular data center container specifications for edge computing deployments requiring aluminum side rails and custom hinge assemblies. Pursue dual GB and EN 12079 compliance as entry credential for European-bound fleet procurement panels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed coating houses in the Pearl River Delta possessing REACH-compliant trivalent chromium conversion capabilities. Long-term viability favors foundries with captive testing laboratories serving consolidated carrier procurement panels. Watch aluminum-magnesium alloy adoption curves in military modular deployer specifications as inflection signal for structural material displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Metallurgical Testing Laboratory Investment | ISO 1496 certification access filters supplier eligibility for Maersk and CMA CGM panels. |
| Electric-Arc-Furnace Foundry Partnership | China's MEE carbon intensity benchmarks favor lower-emission corner casting output. |
| Dual Compliance Certification Path | GB and EN 12079 alignment opens European-bound fleet procurement to Asian suppliers. |
| Aluminum-Magnesium Alloy Production Scale-Up | Modular data center containers specify lightweight side rails for rapid field deployment. |
| Reefer Sealing System Development | Proprietary door hardware captures premium positioning amid F-Gas thermal integrity requirements. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in documented compliance requirements. Foundry operations managers, freight carrier procurement directors, container leasing fleet managers, and coating house technical directors provided operational data. Secondary sources include SAMR GB/T 1835 enforcement records, ECHA REACH restriction updates, IMO CSC convention amendments, and customs trade flow databases. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Sensitivity analysis around aluminum price volatility and certification timeline extensions tests forecast robustness across the projection horizon. Segmentation dimensions encompass product type, material grade, application category, and customer archetype. CAGRs derive from regression against container manufacturing output and fleet expansion patterns. Industry-specific inputs include reefer fleet retrofit rates and modular data center container deployment schedules.
Decision-makers should treat outputs as directional under base assumptions of sustained East Asian manufacturing concentration and stable regulatory divergence between GB and EN certification paths; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as India's PLI scheme incentives and China's dual carbon goals evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
PS Containers Market
Containers
EMEA Container Technology Market
Containers
ISO Ocean Containers Market
Containers
Acrylic Container Market
Containers
Flexible Water Tanks Market
Containers
Dual-Ovenable Trays and Containers Market
Containers
Container Stacking Machine Market
Containers
EPS Shippers Market
Containers
Club Store Packaging Tray Market
Containers
Containerboard Market
Containers
Jerry Cans Market
Containers
Grab and Go Containers Market
Containers
Safety Bottle Tote Carriers Packaging Market
Containers
HDPE Blow Molding and Injection Molding Containers Market
Containers
Foldable Steel Containers Market
Containers
Popcorn Containers Market