
 Clear Hinged Container Market | 2026-2036
Clear Hinged Container Market Size, Share, and Industry Trends Forecast 2026-2036
Clear Hinged Container Market Outlook
Asset-light leasing models for thermoforming equipment is narrowing the capital barrier for mid-tier converters entering the clear hinged container space. Berry Global leverages its North American resin compounding network to sustain cost-advantaged supply positions across multiple states. Amcor anchors its competitiveness through integrated PET sheet extrusion and downstream thermoforming operations in key food packaging corridors. Pactiv Evergreen differentiates by controlling distribution into broadline foodservice channels, occupying shelf-stable positions with large institutional buyers.
Clear hinged containers are injection-molded or thermoformed single-piece enclosures with integral flexible hinges, typically manufactured from polypropylene, PET, or polystyrene in gauges ranging from 12 to 30 mil, designed to secure prepared foods through retail and foodservice distribution. Polypropylene formulations dominate current volume due to microwave tolerance and broad recycling acceptance, while PET grades capture premium deli and bakery segments where optical clarity commands price separation. Food packaging applications absorb the majority of unit demand, though catering formats are expanding fastest as event-service operators standardize on leak-resistant hinged designs for transport efficiency.
FDA food-contact notification requirements govern resin selection and additive packages for domestic manufacturers, while EPA guidelines on recycled content thresholds increasingly influence procurement specifications from major foodservice distributors. State-level extended producer responsibility frameworks in California and Oregon are forcing converters to document post-consumer feedstock percentages, reshaping material sourcing strategies. Stakeholders must monitor how FDA modernization initiatives and emerging state bans on expanded polystyrene converge to determine which resin platforms retain long-term viability.
Market Dynamics
State-level single-use plastic bans in California and New York are compressing polystyrene demand while accelerating converter migration toward polypropylene and PET platforms, reshaping material sourcing strategies across North American thermoforming networks.
Growth Catalysts
- Quick-service restaurant operational speed mandates:Foodservice operators are standardizing on hinged formats to reduce packaging assembly labor and accelerate drive-thru throughput during peak hours.
- California SB 54 extended producer responsibility framework:The state's recycled content mandates are forcing converters to document post-consumer feedstock percentages, creating certified supply advantages for early adopters.
- Polypropylene microwave tolerance:Resin formulations supporting hot-fill and reheat applications are capturing deli and prepared-food segments where consumer convenience commands premium positioning.
Market Restraints
- Petrochemical feedstock volatility:Propylene and ethylene price swings directly compress thermoformer margins, particularly for converters without captive resin compounding or long-term supply agreements.
- Polystyrene substitution timeline friction:Existing tooling investments and established recycling streams create inertia for operators serving price-sensitive institutional cafeterias.
- Thin-gauge thermoforming equipment concentration:German and Italian machinery suppliers dominate high-speed forming press manufacturing, exposing mid-tier converters to euro-denominated capex exposure and extended lead times.
Strategic Opportunities
- Catering format standardization:Event-service operators are consolidating around leak-resistant hinged designs for transport efficiency, creating volume pull for specialized large-format containers.
- Post-consumer PET sheet extrusion:FDA food-contact notification pathways for recycled content are opening certified supply positions for converters with integrated extrusion-thermoforming operations.
- Oregon extended producer responsibility implementation:The state's packaging reduction targets are creating first-mover advantages for converters documenting circular feedstock chains.
Industry Challenges
- Thermoforming die design specialization:Shortage of engineers capable of optimizing multi-cavity hinge geometry for high-speed forming is extending new product development cycles.
- FDA food-contact notification timeline compression:Additive package approvals for novel barrier coatings are creating regulatory bottlenecks for converters targeting extended shelf-life applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clear Hinged Container Market |
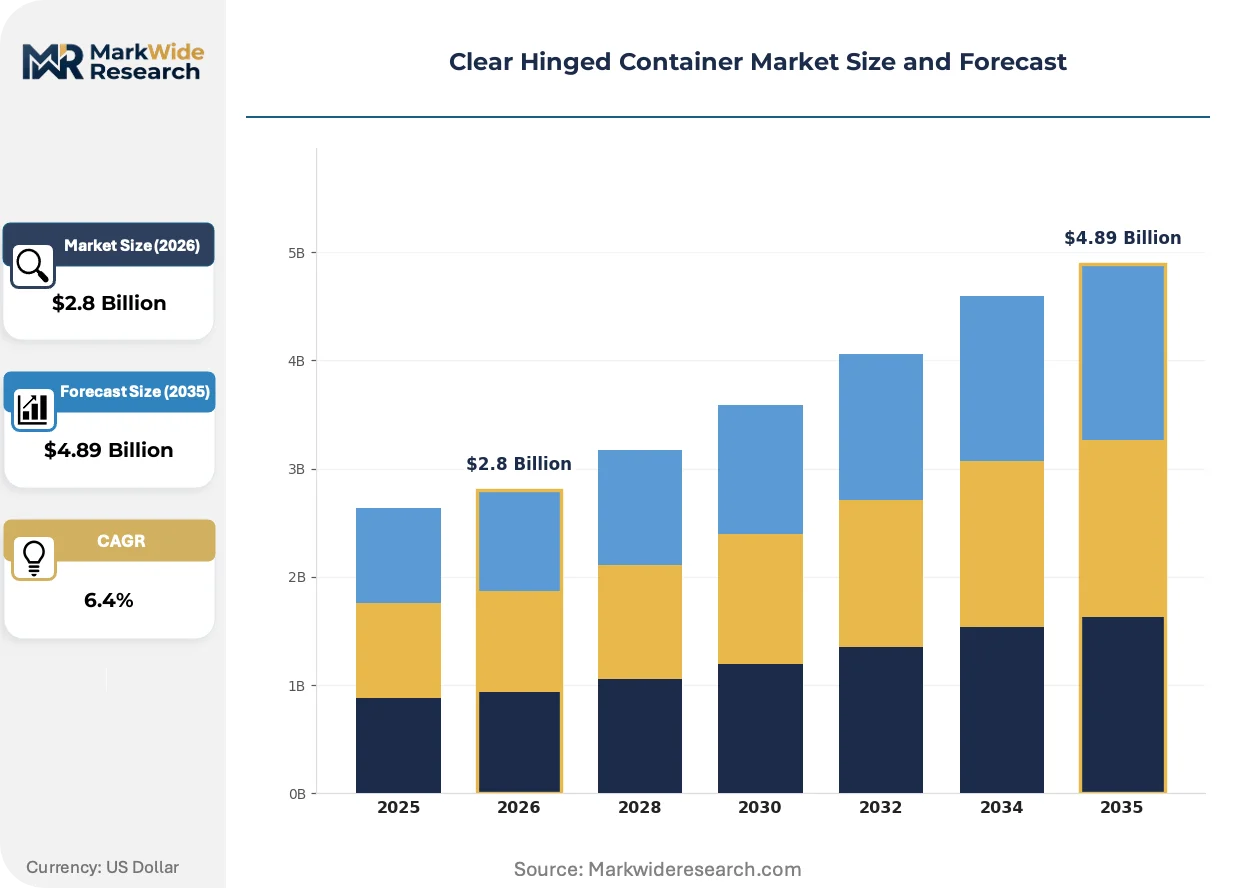
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Polypropylene, Polyethylene, PET, PS Size: Small, Medium, Large, Extra Large Application: Food Packaging, Bakery, Deli, Catering Closure Type: Snap, Lock, Hinged, Others |
| Companies Covered | Berry Global, Amcor, Pactiv Evergreen, Dart Container, Placon, Genpak, Sabert, Huhtamaki, Anchor Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clear Hinged Container Market Strategic Shifts
Material science advances and regulatory compliance automation are compressing traditional product development cycles while enabling certified recycled content claims that previously required multi-year qualification timelines.
Mono-material PET barrier structures with integrated oxygen scavenging are collapsing the performance gap between rigid hinged containers and multi-layer alternatives. Premium deli and bakery buyers are specifying these formats for proteins and prepared salads requiring seven-day refrigerated shelf life. The technology is collapsing the need for separate lidding films and enabling full-container recycling through existing PET streams.
REACH restrictions on per- and polyfluoroalkyl substances are accelerating migration toward silicone-based and bio-derived barrier coatings for grease-resistant applications. European converters are qualifying these alternatives ahead of anticipated restriction expansions. The regulation is forcing reformulation investments that favor integrated resin compounders with in-house additive development capabilities.
Direct procurement relationships between national foodservice distributors and thermoforming converters are displacing traditional packaging distributor intermediaries. Broadline operators are consolidating vendor bases to capture volume pricing and simplify ESG reporting. This pattern concentrates most visibly in the United States, where Sysco and US Foods procurement rationalization programs are certifying preferred converter panels.
Clear Hinged Container Market Segmentation
Clear hinged container purchasing decisions cascade from material specifications through operational constraints. Each segmentation dimension carries distinct margin implications and regulatory exposure for converters and foodservice operators.
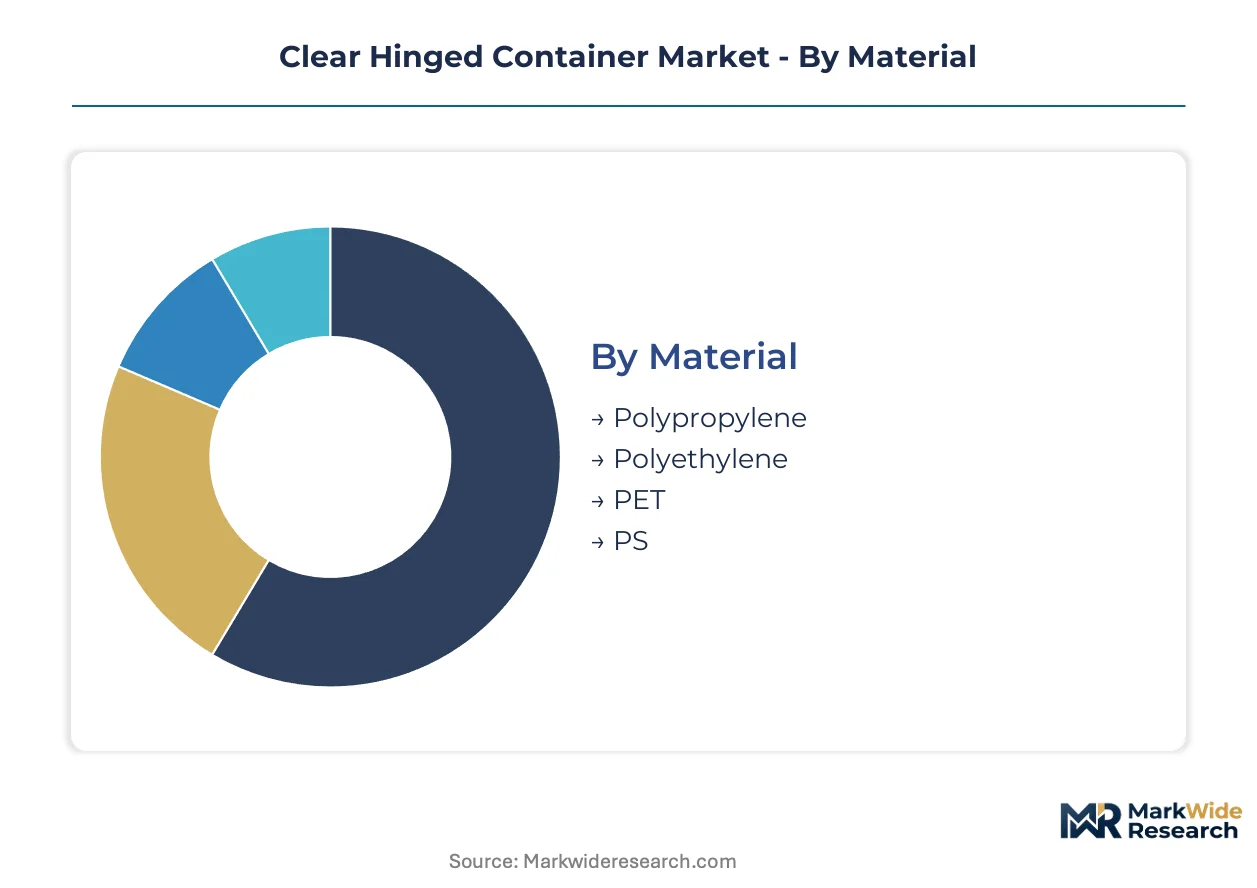
Material:
Mature resin platforms dominate current volume while emerging alternatives reshape compliance positioning across thermoforming networks.
- Polypropylene:Microwave-tolerant formulations withstand hot-fill and reheat cycles without deformation. Deli and prepared-food segments in the United States specify this resin for consumer convenience, though propylene feedstock volatility compresses converter margins.
- PET:Optical clarity grades command premium positioning in bakery and protein applications requiring seven-day refrigerated shelf life. FDA food-contact notification pathways for recycled-content sheet are opening certified supply positions for integrated extrusion-thermoforming operations.
- Polyethylene:Cost-advantaged formulations serve price-sensitive institutional cafeteria contracts with limited heat-resistance requirements.
- PS:California and New York state-level single-use plastic bans are compressing demand, creating substitution timeline friction for operators with existing tooling investments.
Polypropylene handles the majority of throughput; PET is expanding most quickly on share as recycled-content certifications gain procurement weight.
Size:
Cost tier alignment separates commodity volume from specialized formats requiring custom die investments.
- Small:Single-serve condiment and sauce containers for quick-service restaurant drive-thru operations. Operational speed mandates are standardizing hinged formats to reduce assembly labor during peak hours.
- Medium:Sandwich and individual meal formats absorb the highest unit volumes across retail deli cases.
- Large:Family-size prepared food and bulk protein packaging for club store channels.
- Extra Large:Catering trays and event-service formats where leak-resistant hinged designs enable transport efficiency for consolidated vendor bases.
Medium formats carry the volume base; Extra Large formats are climbing the fastest as event-service operators standardize procurement.
Application:
Customer type concentration determines margin structure and regulatory scrutiny intensity.
- Food Packaging:Broadline foodservice distribution absorbs the majority of unit demand. Sysco and US Foods procurement rationalization programs are certifying preferred converter panels, displacing traditional packaging distributor intermediaries.
- Bakery:Premium visual presentation requirements specify PET clarity grades for decorated cakes and pastries. Mono-material barrier structures with integrated oxygen scavenging are collapsing the need for separate lidding films.
- Deli:Prepared salads and sliced proteins require extended shelf-life performance. REACH restrictions on per- and polyfluoroalkyl substances are accelerating migration toward silicone-based barrier coatings.
- Catering:Event-service operators are consolidating around specialized large-format containers. Oregon extended producer responsibility implementation is creating first-mover advantages for converters documenting circular feedstock chains.
Food Packaging anchors procurement volume; Catering is gaining share fastest as post-pandemic takeaway culture solidifies.
Closure Type:
Supply concentration in thermoforming die design capability shapes competitive access to differentiated formats.
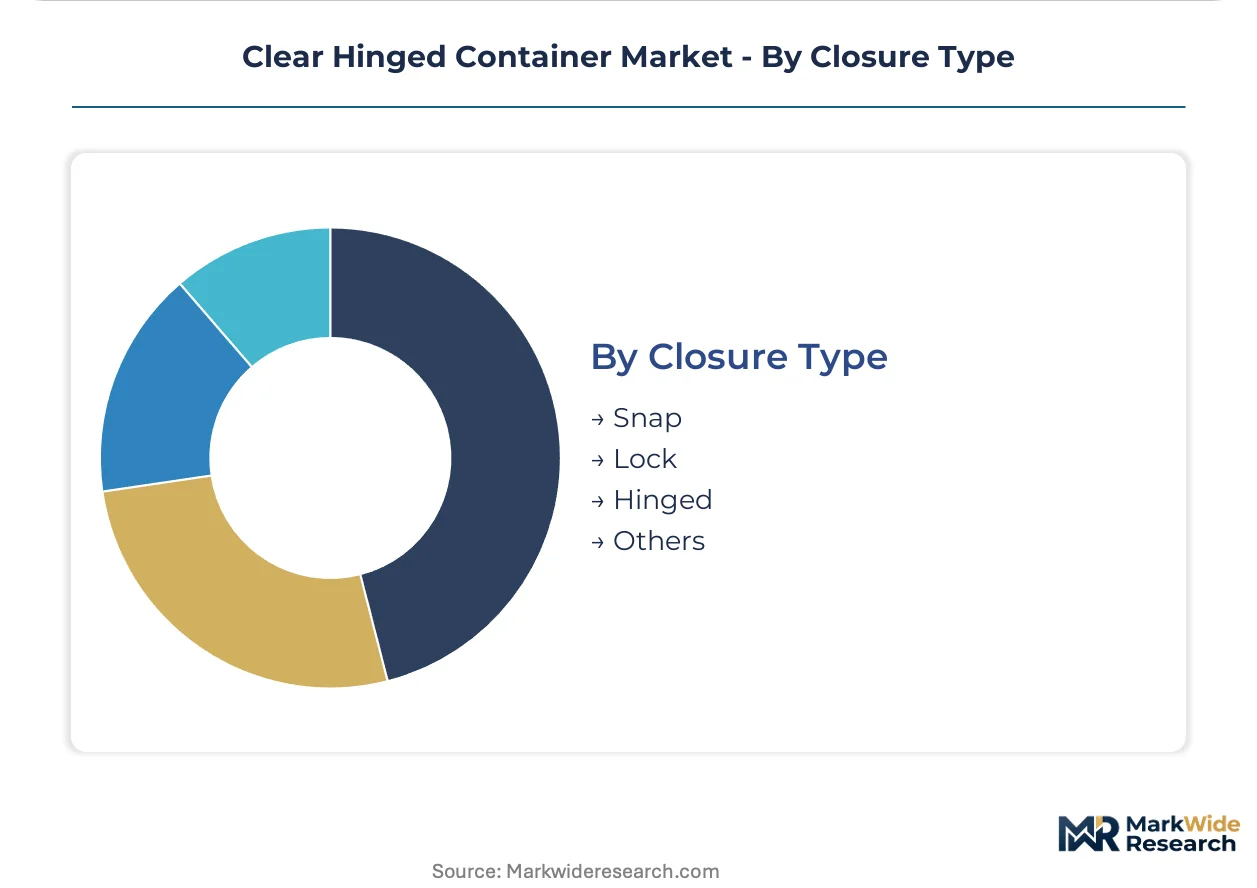
- Hinged:Single-piece enclosures with integral flexible hinges eliminate separate lid inventory and assembly steps. Quick-service restaurant operational speed mandates are driving standardization on this format for drive-thru throughput.
- Snap:Separate lid-and-base configurations retain position in price-sensitive institutional segments with established recycling streams.
- Lock:Tamper-evident mechanisms serve retail channels requiring shelf-life security assurance.
- Others:Specialized mechanisms for medical and pharmaceutical adjacent applications with distinct FDA validation requirements.
Hinged configurations dominate new specification activity; Lock formats show steepest expansion trajectory in retail deli channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in clear hinged containers tilt heavily toward import-dependent regions lacking domestic thermoforming infrastructure. Export competitiveness clusters where resin compounding and sheet extrusion capabilities co-locate with food packaging demand centers.
United States
Deli and prepared-food segments drive volume concentration, with quick-service restaurant chains standardizing on hinged formats for drive-thru throughput. FDA food-contact notification requirements govern resin selection and additive packages for domestic manufacturers. Chicago and Dallas-Fort Worth anchor thermoforming clusters where converters serve broadline foodservice distributors.
Germany
Takeaway culture solidification post-pandemic is accelerating demand for leak-resistant catering formats. REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation investments toward silicone-based barrier coatings. The Rhine-Ruhr and Stuttgart regions concentrate converters with integrated extrusion-thermoforming operations serving premium bakery and deli segments.
Japan
Convenience store chains and bento box culture sustain demand for optical clarity in small-format hinged containers. METI circular economy guidelines are pressuring converters to document recycled content percentages. Osaka and Nagoya industrial corridors host thermoforming networks supplying retail food packaging channels.
China
Urban food delivery expansion is pulling hinged container imports while domestic thermoforming capacity scales. GB standards for food-contact plastics govern resin selection and migration limits. The Yangtze River Delta and Pearl River Delta clusters concentrate converters serving quick-service restaurant chains and fresh-food e-commerce platforms.
India
Organized retail and cloud kitchen expansion is creating pull for standardized food packaging formats. FSSAI food safety regulations mandate compliance testing for plastic food-contact materials. Maharashtra and Gujarat industrial belts are emerging as thermoforming hubs for domestic foodservice and export-oriented catering segments.
Clear Hinged Container Market Competitive Environment
On the supply side, the industry is consolidating around integrated resin compounders with captive thermoforming operations and broadline distribution access. Three strategic archetypes dominate: global packaging conglomerates with multi-material portfolios, regional thermoforming specialists with die design capabilities, and resin-integrated players with cost-advantaged feedstock positions. Competitive moves center on vertical integration into sheet extrusion and strategic partnerships with national foodservice distributors for preferred supplier status.
Among North American packaging conglomerates, Berry Global, Amcor, and Pactiv Evergreen occupy positions exemplifying distinct competitive vectors. Berry Global represents the resin-integrated archetype with compounding network advantages. Amcor anchors the integrated extrusion-thermoforming model. Pactiv Evergreen exemplifies distribution channel control through broadline foodservice relationships. These three sit within a tier where scale and supply chain integration separate market participants.
| Leading Market Players |
|---|
| Berry Global |
| Amcor |
| Pactiv Evergreen |
| Dart Container |
| Placon |
| Genpak |
| Sabert |
| Huhtamaki |
| Anchor Packaging |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European thermoforming press manufacturing is compressing converter margins and extending equipment lead times, forcing mid-tier operators to absorb euro-denominated capex exposure or defer capacity additions. This utilization squeeze propagates downstream through resin procurement negotiations and contract pricing postures across North American foodservice packaging networks.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium, standard, and economy tiers. Price differentiation separates FDA-certified recycled-content PET from virgin polypropylene commodity grades, with volume scale and geographic delivery cost as secondary tiering factors. Cost compression in standard-grade polypropylene is intensifying because propylene feedstock volatility compresses thermoformer margins. Price-sensitive institutional cafeteria operators resist tier upgrades, while premium deli and bakery segments absorb clarity-grade PET premiums.
Supply Chain Analysis
Extended payment terms from German and Italian machinery suppliers are straining converter working capital, accelerating supply-chain finance facility adoption among mid-tier operators. Geographic supply concentration centers on the United States, Germany, and China for thermoforming equipment and resin compounding. Raw material dependencies draw from propylene monomer, PET chip, and calcium carbonate filler streams. Single-source vulnerability in high-speed forming press manufacturing exposes converters to euro-denominated capex exposure. Distribution runs through broadline foodservice distributors consolidating vendor bases for volume pricing capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in thermoforming equipment leasing and die design engineering are expanding faster than container hardware sales, as converters prioritize asset-light capacity scaling over ownership. This recurring-revenue layer offers margin stability distinct from commodity resin exposure.
For Market Incumbents: Build regulatory certification moats through early FDA food-contact notification filings for recycled-content PET sheet extrusion. Secure backward integration into resin compounding to defend against propylene feedstock volatility. Capture preferred supplier status with Sysco and US Foods procurement rationalization programs before channel consolidation hardens. For New Entrants and Emerging Players: Pursue catering format specialization where event-service operators standardize procurement around leak-resistant large-format containers. Target Oregon and California extended producer responsibility implementation timelines for first-mover certified supply positioning. Enter through direct procurement relationships with national foodservice distributors displacing traditional packaging intermediaries. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated extrusion-thermoforming operators with captive die design capabilities. Long-term viability over a multi-year horizon favors converters documenting circular feedstock chains ahead of state-level recycled content mandates. Watch FDA modernization initiatives on food-contact notification timelines as inflection signals for barrier coating technology substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Berry Global's North American network demonstrates cost-advantaged supply positions across multiple states. |
| Integrated Extrusion-Thermoforming Operations | Amcor anchors competitiveness through PET sheet extrusion co-located with downstream forming in food packaging corridors. |
| Broadline Distribution Channel Control | Pactiv Evergreen occupies shelf-stable positions with large institutional buyers through direct procurement relationships. |
| Post-Consumer PET Sheet Certification | FDA food-contact notification pathways open certified supply positions for converters with integrated operations. |
| Catering Format Standardization | Event-service operators consolidate around leak-resistant hinged designs for transport efficiency and vendor base consolidation. |
Study Parameters
Cross-validation between primary interviews with thermoforming plant managers, resin procurement leads at downstream converters, distribution channel partners, and technical R&D directors anchors the qualitative findings. Secondary validation draws from FDA food-contact notification databases, EPA recycled content guidelines, SEC 10-K filings of packaging conglomerates, and customs/trade data on thermoforming equipment imports. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates across the analysis window.
Calibration against historical capacity utilization rates and resin price elasticity informs the analytical framework across the projection horizon. Segmentation dimensions modeled include material resin platform, container size tier, end-use application, closure mechanism type, and regional regulatory cluster. CAGRs derive from compound growth trajectory analysis applied to baseline volume and value estimates. Industry-specific forecast inputs incorporate state-level extended producer responsibility implementation schedules and quick-service restaurant chain expansion pipelines.
Sensitivities concentrate around propylene feedstock volatility, FDA food-contact notification timeline compression, and state-level single-use plastic ban enforcement pace. Forecasts reflect documented assumptions on regulatory implementation schedules, resin substitution timelines, and foodservice operator format standardization rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Pinch Grip Jars Market
Containers
Gable Top Container Market
Containers
High Density Polyethylene (HDPE) Bottles Market
Containers
Insert Trays Market
Containers
Slip Lid Can Market
Containers
Thin Wall Containers Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
PUR Containers Packaging Market
Containers
Lever Lid Cans Market
Containers
Thermoformed Containers Market
Containers
Spout Containers Market
Containers
Collapsible Sleeve Containers Market
Containers
Injection Molding Containers Market
Containers
Wet Wipes Canister Market
Containers
Stock Clamshell Packaging Market
Containers
Grab and Go Containers Market