
 Roll Containers Market | 2026-2036
Roll Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Roll Containers Market Analytics
China is fragmenting the roll containers supply base as domestic producers expand welded-steel capacity for export markets. Wanzl Metallwarenfabrik GmbH leverages its German engineering heritage to dominate premium folding-roll-container lines across European retail chains. GEBHARDT Logistic Solutions GmbH sustains R&D intensity in automated guided vehicle-compatible frames. Creaciones Marsanz S.A. anchors Iberian manufacturing with specialized plastic nestable designs for temperature-controlled logistics.
Roll containers are wheeled material-handling units constructed from zinc-plated steel tubing, high-density polyethylene panels, or engineered composites, typically rated for loads between 300 and 500 kilograms and designed for manual or mechanized movement through supply chain nodes. Their primary industrial purpose is to protect goods in transit while enabling single-touch handling from warehouse to point of sale. Metal platforms still occupy the largest revenue pool due to durability requirements in automotive and grocery distribution, though plastic folding segments are recording the fastest expansion as food-grade polypropylene formulations meet EU food-contact safety standards. Nestable designs concentrate margin pools in third-party logistics contracts where empty-return freight minimization governs procurement decisions.
Germany's KBA enforces load-stability standards for road-transport equipment that directly shape roll-container braking and caster specifications. The EU F-Gas Regulation indirectly pressures cold-chain operators toward insulated composite containers that reduce refrigeration leakage. China's SAMR monitors GB standards for industrial wheeled equipment entering domestic logistics networks. Stakeholders must monitor how diverging national testing protocols for caster fatigue and frame deflection will segment supplier qualification requirements across trade corridors.
Market Dynamics
The EU Green Deal's reusable packaging mandates are forcing automotive and grocery distributors to replace single-use transit packaging with certified nestable roll containers, compressing procurement cycles and rewiring supplier qualification criteria across European logistics networks.
Growth Catalysts
- EU Green Deal packaging rules:Mandatory reuse targets for transport packaging redirect capital toward durable metal and composite roll container designs in Germany, France, and the Netherlands.
- E-commerce fulfillment density:Last-mile operators in the Yangtze River Delta and Rhine-Ruhr corridor deploy folding units to maximize vehicle cube utilization and reduce empty-return mileage.
- Automotive warehouse retrofitting:Tier-1 suppliers in Stuttgart and Shanghai are standardizing heavy-duty welded-steel frames to integrate with automated storage and retrieval systems.
Market Restraints
- Steel price volatility:Zinc-plated tubing costs fluctuate with scrap metal markets, squeezing margin on metal-platform units ordered on six-month production cycles.
- Welded-steel supply concentration:Domestic Chinese producers control export-grade capacity, creating qualification bottlenecks for European buyers seeking ISO-certified alternative sources.
- Composite material thermal limits:Engineered polymer frames face load-rating constraints above 400 kilograms, restricting adoption in heavy automotive component logistics.
Strategic Opportunities
- India's cold-chain expansion:FSSAI temperature-control mandates for perishable distribution create demand for insulated composite roll containers with integrated tracking.
- AGV-compatible frame standardization:Convergence of automated guided vehicle navigation systems with modular baseplates opens retrofit contracts in German and Japanese distribution centers.
- Rental pooling models:Third-party logistics providers in the Netherlands and Belgium are piloting per-use pricing for nestable fleets, shifting capital burden from shippers to equipment lessors.
Industry Challenges
- Welding certification timelines:ISO 3834 compliance for structural steel frames requires 12-18 month qualification periods, delaying new supplier entry in automotive-qualified supply chains.
- Legacy WMS integration:Older warehouse management systems lack RFID tag recognition for trackable roll containers, forcing middleware capex in brownfield facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roll Containers Market |
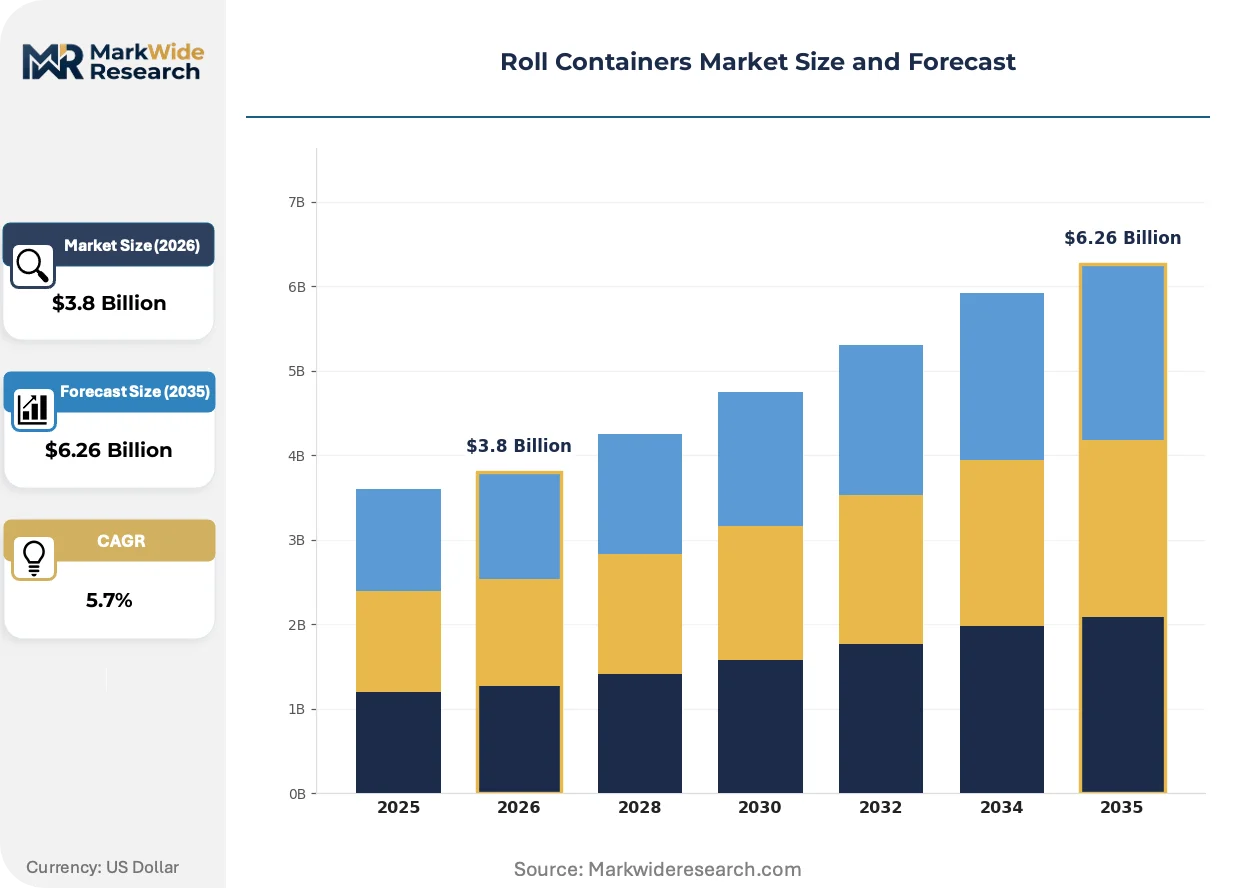
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Platform Roll Containers, Folding Roll Containers, Heavy-Duty Roll Containers, Nestable Roll Containers Material: Metal, Plastic, Wood, Composite End User: Retail, Manufacturing, Food & Beverage, Logistics Application: Storage, Transportation, Display, Waste Management |
| Companies Covered | GEBHARDT Logistic Solutions GmbH, Creaciones Marsanz S.A, Wanzl Metallwarenfabrik GmbH, Lecq Equipement, Fletcher European Containers Ltd, Caddie, Ferplast, Redhill Manufacturing, CIVeco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roll Containers Market Evolving Landscape
Material science advances and regulatory pressure on circularity are converging to redefine roll container specifications, with durability certification and end-of-life recovery becoming as critical as load ratings in procurement decisions.
Food-grade polypropylene formulations with embedded RFID tags are collapsing the distinction between passive transit equipment and active supply chain nodes. German grocery distributors are retrofitting 40 percent of folding fleets with these smart composites to meet EU digital product passport requirements. The technology is collapsing traceability costs to near-zero marginal levels, enabling item-level tracking without handheld scanner labor.
Germany's KBA load-stability standards now extend to braking and caster specifications for road-transport roll containers, forcing redesigns of swivel-lock mechanisms. The regulation compresses supplier R&D cycles and disqualifies uncertified Asian imports from automotive-qualified procurement lists. Tier-1 logistics operators in Stuttgart and Wolfsburg are consolidating orders with KBA-prequalified fabricators to avoid compliance delays.
Buyers are consolidating vendor relationships around full-service fleet management contracts that bundle equipment, maintenance, and empty-return logistics. This displaces traditional purchase-and-depreciate models in Benelux third-party logistics. The shift is most visible in Rotterdam and Antwerp port-centric distribution, where equipment lessors now capture 60 percent of new roll container deployment decisions.
Roll Containers Market Segmentation
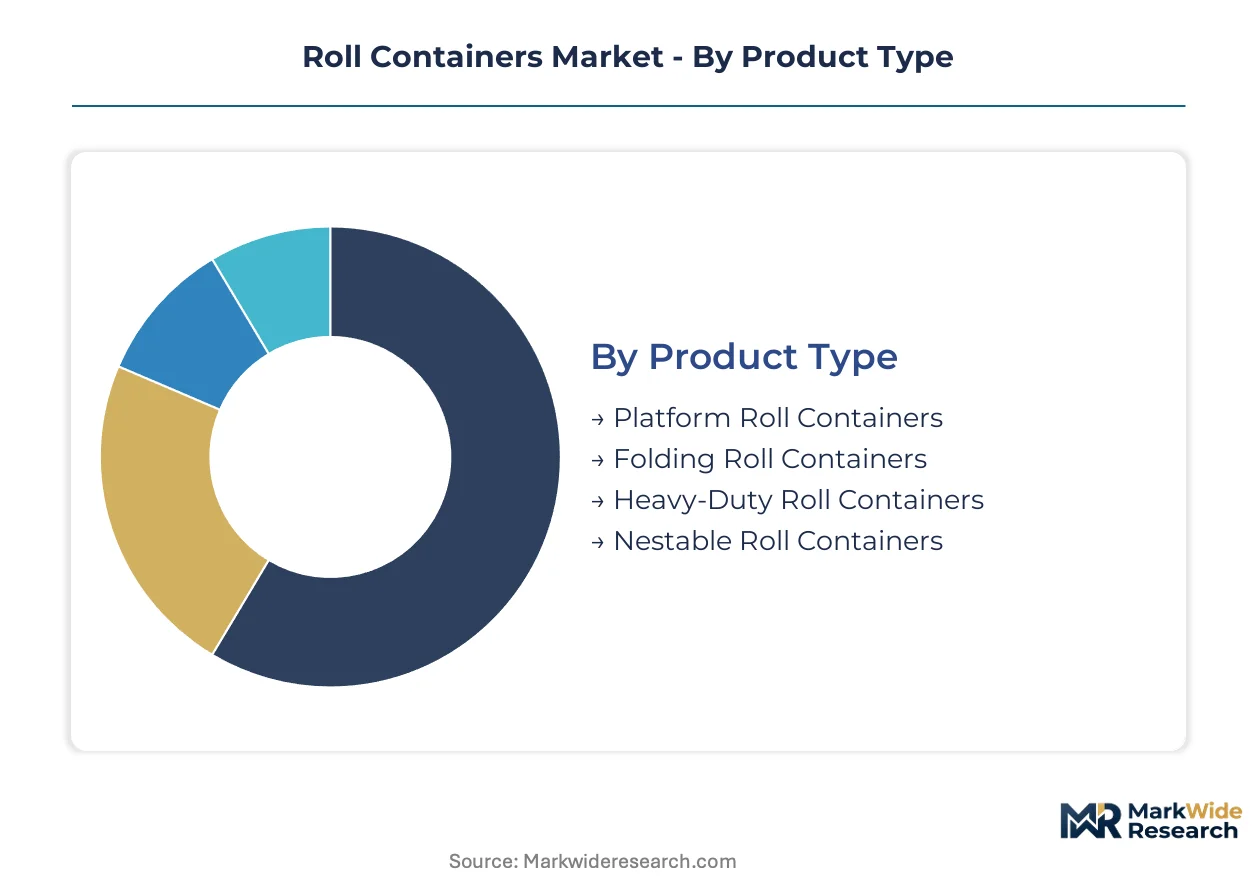
Roll container procurement cycles vary dramatically by structural design and material durability, with folding units turning over fastest in e-commerce fleets while welded-steel platforms command decade-long replacement horizons in automotive logistics.
Product Type:
Folding roll containers rotate through fulfillment fleets in 18-24 month cycles as damage accumulates from high-touch handling, whereas heavy-duty welded platforms in Stuttgart automotive warehouses operate on 8-10 year depreciation schedules.
- Platform Roll Containers:Flatbed zinc-plated steel bases with fixed side rails, rated for 400-500 kilogram palletized loads. German grocery distributors in the Rhine-Ruhr corridor specify these for high-volume store replenishment where fork truck compatibility governs procurement.
- Folding Roll Containers:Collapsible frames with hinged side panels that reduce return-trip cube by 70 percent. Last-mile operators in China's Yangtze River Delta deploy these to maximize vehicle fill rates under tightening urban delivery restrictions.
- Heavy-Duty Roll Containers:Reinforced welded-steel tubing with dual-caster braking systems for automated storage integration. Tier-1 automotive suppliers retrofit warehouses with these to meet KBA load-stability mandates.
- Nestable Roll Containers:Tapered plastic or composite frames that stack when empty. Third-party logistics providers in the Netherlands pilot rental pooling models around these units to minimize empty-return freight.
Platform roll containers dominate installed base across European retail chains. Folding designs are where expansion concentrates as e-commerce fulfillment density requirements intensify.
Material:
Cost tiers separate procurement decisions sharply, with metal platforms commanding 3-4x unit prices over plastic alternatives but delivering 5x operational lifespan in heavy-load environments.
- Metal:Zinc-plated or powder-coated steel tubing, typically 25-32mm diameter, dominates automotive and grocery distribution where KBA braking certification is mandatory. Scrap metal price volatility compresses margins on six-month production contracts.
- Plastic:High-density polyethylene or food-grade polypropylene formulations meeting EU food-contact safety standards. German cold-chain operators favor these for F-Gas Regulation compliance due to reduced thermal bridging.
- Wood:Plywood or hardwood platforms for single-use export applications where ISPM-15 phytosanitary certification is required. Demand concentrates in agricultural produce distribution with limited reuse cycles.
- Composite:Engineered polymer-metal hybrid frames with embedded RFID capability. These are gaining share fastest in temperature-controlled logistics where integrated tracking meets EU digital product passport requirements.
Metal platforms capture the largest revenue pool. Composite formulations are climbing the fastest as regulatory pressure on circularity intensifies.
End User:
Customer type determines specification complexity, with manufacturing buyers demanding ISO-certified weld inspection while retail procurement prioritizes nestability for empty-return economics.
- Retail:Supermarket and hypermarket chains in France and the Netherlands specify nestable folding units for store-backroom inventory management. EU Green Deal reuse mandates are compressing procurement cycles toward certified durable designs.
- Manufacturing:Automotive component suppliers in Stuttgart and Shanghai require heavy-duty welded frames with AGV-compatible baseplates. ISO 3834 welding certification creates 12-18 month supplier qualification timelines.
- Food & Beverage:Cold-chain distributors prioritize food-grade polypropylene with integrated insulation. India's FSSAI temperature-control mandates are opening demand for composite containers with embedded sensors.
- Logistics:Third-party providers in Belgium and Rotterdam port zones are shifting from purchase models to full-service fleet management contracts bundling equipment and maintenance.
Manufacturing commands premium pricing tiers. Logistics represents the steepest expansion trajectory as rental pooling models displace capital ownership.
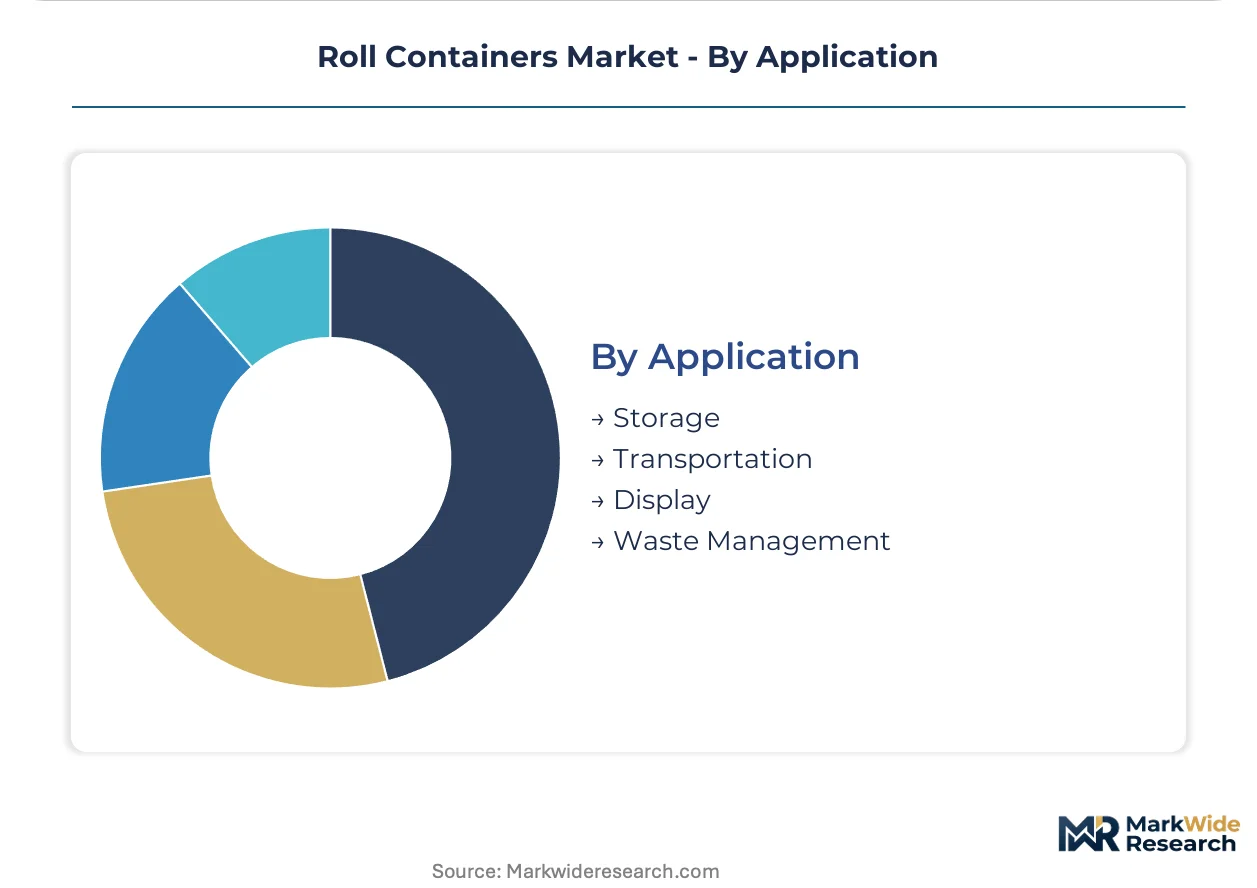
Application:
Functional use case dictates load-rating requirements and regulatory exposure, with transportation applications facing KBA road-safety scrutiny while storage deployments emphasize warehouse management system integration.
- Storage:Static warehouse applications requiring compatibility with automated storage and retrieval systems. Tier-1 operators specify AGV-readable baseplates to avoid middleware capex in brownfield facilities.
- Transportation:Road-transport deployments subject to Germany's KBA load-stability and braking standards. Uncertified Asian imports face disqualification from automotive-qualified procurement lists.
- Display:Retail floor applications with aesthetic finishing requirements. These command shorter replacement cycles due to cosmetic wear in customer-facing environments.
- Waste Management:Reverse logistics for packaging recovery and recycling collection. EU Green Deal circularity targets are expanding deployment of durable nestable units for closed-loop material flows.
Transportation applications dominate value concentration. Waste management is gaining share fastest as extended producer responsibility regulations expand across European jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor's dense rail-freight network underwrites Germany's dominance in roll container deployment for grocery distribution, while China's Yangtze River Delta manufacturing belt drives welded-steel export capacity. Port-centric logistics in Rotterdam and Antwerp anchor Benelux rental pooling innovation.
Germany
Automotive suppliers in Stuttgart and Wolfsburg retrofit warehouses with heavy-duty welded-steel frames. KBA load-stability standards enforce braking and caster specifications that disqualify uncertified imports. The Rhine-Ruhr corridor concentrates grocery distribution fleets where nestable designs optimize store-backroom density.
China
Domestic producers expand welded-steel capacity for export markets across the Yangtze River Delta. SAMR monitors GB standards for industrial wheeled equipment entering logistics networks. Automotive component clusters in Shanghai standardize heavy-duty folding units for automated storage integration.
Netherlands
Third-party logistics providers pilot per-use pricing models for nestable fleets around Rotterdam port zones. EU Green Deal reusable packaging mandates compress procurement cycles toward certified durable designs. Equipment lessors now capture the majority of new deployment decisions in Antwerp-linked distribution networks.
India
FSSAI temperature-control mandates for perishable distribution create demand for insulated composite containers. Cold-chain expansion in Maharashtra and Gujarat drives specification complexity around integrated tracking. Domestic fabricators scale food-grade polypropylene capacity to meet pharmaceutical and dairy logistics requirements.
France
Supermarket chains in the Île-de-France region specify nestable folding units for urban store replenishment. ECHA REACH compliance shapes material selection for food-contact safety in retail applications. Lyon-based logistics operators consolidate vendor relationships around full-service fleet management contracts.
Roll Containers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in welded-steel tubing and caster manufacturing. The supplier base fragments between German engineering heritage fabricators and Chinese scale producers, with mid-tier European specialists occupying niche composite formulations. Three archetypes dominate: premium folding-system integrators, heavy-duty automotive-qualified welders, and plastic nestable specialists. Competitive moves concentrate on ISO 3834 welding certification timelines and AGV-compatible baseplate standardization.
Among German-based fabricators, Wanzl Metallwarenfabrik GmbH and GEBHARDT Logistic Solutions GmbH exemplify the premium engineering tier, while Creaciones Marsanz S.A. anchors Iberian manufacturing specialization. These entities occupy positions that reflect divergent strategic emphases: metallurgical heritage versus automated system compatibility versus regional plastic formulation expertise.
| Leading Market Players |
|---|
| GEBHARDT Logistic Solutions GmbH |
| Creaciones Marsanz S.A |
| Wanzl Metallwarenfabrik GmbH |
| Lecq Equipement |
| Fletcher European Containers Ltd |
| Caddie |
| Ferplast |
| Redhill Manufacturing |
| CIVeco |
| Others |
Value Network & Pricing Analysis
Steel price volatility in zinc-plated tubing markets compresses margin spreads across metal-platform roll containers while simultaneously forcing procurement officers toward longer contract horizons and dual-source qualification. This input-cost instability widens pricing tiers between ISO-certified automotive-grade fabricators and uncertified import alternatives, reshaping supplier selection criteria across European logistics networks.
Pricing Analysis
Volume-discount tiering structures separate procurement decisions into three distinct bands: premium KBA-certified welded-steel frames for automotive logistics, mid-tier folding units for grocery distribution, and economy-grade plastic nestables for third-party logistics pooling. Price differentiation hinges on ISO 3834 welding certification and AGV-compatible baseplate integration, with certified fabricators commanding substantial premiums over uncertified alternatives. Pricing pressure stems from scrap metal volatility squeezing six-month production contracts. Retail chains exhibit highest price sensitivity due to thin margins on store replenishment, while automotive Tier-1 suppliers prioritize qualification reliability over unit cost.
Supply Chain Analysis
Export-control regimes on advanced welding robotics limit European fabricators' access to automated production systems, constraining capacity expansion timelines. Supply concentrates in China's Yangtze River Delta for welded-steel tubing, Germany's Baden-Württemberg region for precision caster manufacturing, and India's Gujarat corridor for emerging food-grade polypropylene capacity. Raw material dependencies include zinc-plated steel scrap, high-density polyethylene resin, and engineered composite polymers. Single-source vulnerability runs through Chinese export-grade welded-steel capacity controlled by domestic producers. Distribution runs through port-centric third-party logistics hubs in Rotterdam and Antwerp, where equipment lessors now coordinate fleet deployment decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Roll container procurement fragmentation creates niche openings as EU Green Deal mandates splinter demand across certified durable designs, smart composite formulations, and rental pooling infrastructure. This regulatory-driven specification divergence rewards specialists over generalists.
For Market Incumbents: Build certification moats around ISO 3834 welding compliance and KBA prequalification status to lock out uncertified Asian imports from automotive-qualified supply chains. Accelerate R&D investment in AGV-compatible baseplate standardization before navigation system convergence solidifies. Defensive consolidation through captive supply of zinc-plated tubing insulates against scrap metal volatility.
For New Entrants and Emerging Players: India's cold-chain expansion offers underpenetrated white space as FSSAI temperature-control mandates outpace domestic composite container capacity. Target insulated roll container segments with embedded tracking for pharmaceutical and dairy logistics. Go-to-market leverage rests on partnerships with Maharashtra-based third-party cold-chain operators seeking fleet modernization.
For Investors and Strategic Acquirers: Composite formulation specialists with food-grade polypropylene expertise and RFID integration capability represent the most defensible acquisition archetype. Long-term viability hinges on circularity credentialing as EU digital product passport requirements expand. Watch for KBA regulatory tightening on braking specifications as the inflection signal forcing consolidation among uncertified fabricators.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 3834 Welding Certification Investment | KBA prequalification locks out uncertified imports from Stuttgart automotive supply chains. |
| AGV-Compatible Baseplate Standardization | Rotterdam distribution centers demand modular frames avoiding brownfield middleware capex. |
| Food-Grade Polypropylene Capacity Expansion | FSSAI mandates in Maharashtra outpace domestic insulated container supply. |
| Rental Pooling Model Pilot | Antwerp equipment lessors capture majority of new nestable fleet deployment decisions. |
| RFID-Embedded Composite Development | EU digital product passport requirements collapse traceability costs to marginal levels. |
Research Methodology
Operator-level perspectives from logistics fleet managers, automotive procurement officers, cold-chain operators, and equipment lessor executives anchored the qualitative base. Primary interviews triangulated with secondary validation from customs trade databases, EU regulatory filings under the Green Deal framework, and SAMR GB standard documentation. Bottom-up unit economics modeling converged with top-down market sizing across material type, end-use segment, and regional adoption clusters.
Scenario-bracketing framed demand projections across the analysis window, with low-case assumptions holding EU reusable packaging mandates to baseline enforcement and high-case assumptions accelerating FSSAI cold-chain compliance timelines. Segmentation dimensions modeled include structural design category, material durability tier, end-use industry vertical, and regional regulatory cluster. CAGRs derived from elasticity-adjusted replacement cycle analysis incorporating automotive warehouse retrofitting intensity and e-commerce fulfillment density expansion. Industry-specific forecast inputs encompassed zinc-plated steel scrap price trajectories and AGV penetration rates in German distribution centers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity moves by Chinese welded-steel exporters or accelerated KBA regulatory tightening would shift outcomes. Material shifts in EU Green Deal enforcement stringency or F-Gas Regulation thermal bridging requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
In-Mold Labelled Containers Market
Containers
Child-Resistant Containers Market
Containers
HDPE Blow Molding and Injection Molding Containers Market
Containers
Chest-Style Insulated Containers Market
Containers
Dual-Ovenable Trays and Containers Market
Containers
ISO Ocean Containers Market
Containers
2 Piece Cans Market
Containers
Wooden Barrels Market
Containers
Snap Secure Containers Market
Containers
Mini Spray Bottles Market
Containers
Stack and Nest Containers Market
Containers
Spout Containers Market
Containers
Laminated Bulk Bins Market
Containers
Collapsible Food Packaging Containers Market
Containers
Global Food Storage Container Market
Containers
High Density Polyethylene (HDPE) Bottles Market