
 Packer Market | 2026-2036
Packer Market Size, Share, and Industry Trends Forecast 2026-2036
Packer Market Outlook
Composite elastomer compounds are displacing conventional nitrile rubber in high-pressure packer elements, and this material transition is realigning product economics across the sector. Schlumberger Limited leverages its integrated manufacturing of proprietary elastomer formulations to sustain margin advantages in deepwater applications. Halliburton Company anchors its competitive stance through geographic dominance in Middle Eastern well completion markets. Baker Hughes Company differentiates via technology leadership in expandable packer systems for unconventional reservoirs.
A packer is a downhole mechanical device engineered to isolate annular spaces between tubing and casing or open hole, typically rated for differential pressures exceeding 10,000 psi and temperatures above 300°F depending on elastomer and metal seal configuration. Its primary industrial purpose is to enable zonal isolation, pressure containment, and selective production or injection in oil and gas wells. Automatic packers command the dominant share of value as operators prioritize rig-time reduction and remote actuation capabilities in offshore environments. Robotic packers represent the fastest-expanding category, driven by integration with intelligent well systems that adjust seal geometry in response to real-time downhole telemetry. Manual packer configurations persist in mature onshore basins where capital constraints outweigh automation returns.
The EPA enforces stringent material disclosure requirements for downhole elastomers used in federally managed lands, compelling manufacturers to reformulate packer elements with reduced aromatic content. API Specification 11D1 governs qualification testing for inflatable and compression-set packers, creating a certification barrier that shapes market access for regional suppliers. The Bureau of Land Management's methane waste prevention rules further condition packer selection by mandating tighter annular seal integrity in gas-bearing formations. Stakeholders must monitor evolving sustainability-linked procurement criteria from major operators and decide whether to invest in recyclable elastomer technologies or defend conventional compound positions through performance guarantees.
Market Dynamics
Automation investments in well completion operations are compressing rig-time economics and forcing packer suppliers to integrate servo-driven actuation and telemetry interfaces into standard product lines. This structural shift favors vendors with captive motion control capabilities over pure-play elastomer specialists.
Growth Catalysts
- Deepwater zonal isolation requirements:Offshore operators in the Gulf of Mexico and Brazil's pre-salt basins mandate redundant seal systems for high-pressure formations, driving specification upgrades for dual-element packer configurations.
- EPA methane waste prevention rules:The Bureau of Land Management's tightened annular seal integrity standards for gas-bearing formations on federal lands compel replacement of legacy compression-set designs with inflatable alternatives.
- Composite elastomer compounds:Fluorocarbon and hydrogenated nitrile formulations rated above 350°F are displacing conventional nitrile in thermal recovery applications, opening premium pricing tiers for material innovators.
Market Restraints
- Specialty polymer supply concentration:Capacities for high-temperature elastomer base stocks concentrate among three German and Japanese chemical suppliers, exposing packer manufacturers to feedstock allocation volatility.
- API 11D1 certification timelines:Qualification testing for inflatable packers requires 18-24 months of sustained pressure and temperature cycling, creating a barrier to rapid product iteration for regional entrants.
- Geothermal energy substitution:Closed-loop geothermal systems eliminate downhole zonal isolation entirely in certain configurations, threatening long-term demand in district heating applications.
Strategic Opportunities
- Intelligent well convergence:Integration of fiber-optic pressure sensing with self-adjusting seal geometry creates a white space for packer vendors to capture recurring software and service revenue.
- US contract packaging expansion:Pharmaceutical serialization mandates under the FDA's Drug Supply Chain Security Act are accelerating automation investments among mid-size packer operations seeking remote actuation capabilities.
- Recyclable elastomer technologies:Sustainability-linked procurement criteria from major European operators favor packer elements with reduced aromatic content and end-of-life reclaim pathways.
Industry Challenges
- Mechatronics talent scarcity:The convergence of mechanical seal engineering with embedded controls and telemetry requires skill sets concentrated among aerospace and automotive sectors, not traditional oilfield services.
- Legacy system integration friction:Retrofitting intelligent packer actuation onto existing wellhead architectures demands custom engineering that erodes margin on brownfield installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packer Market |
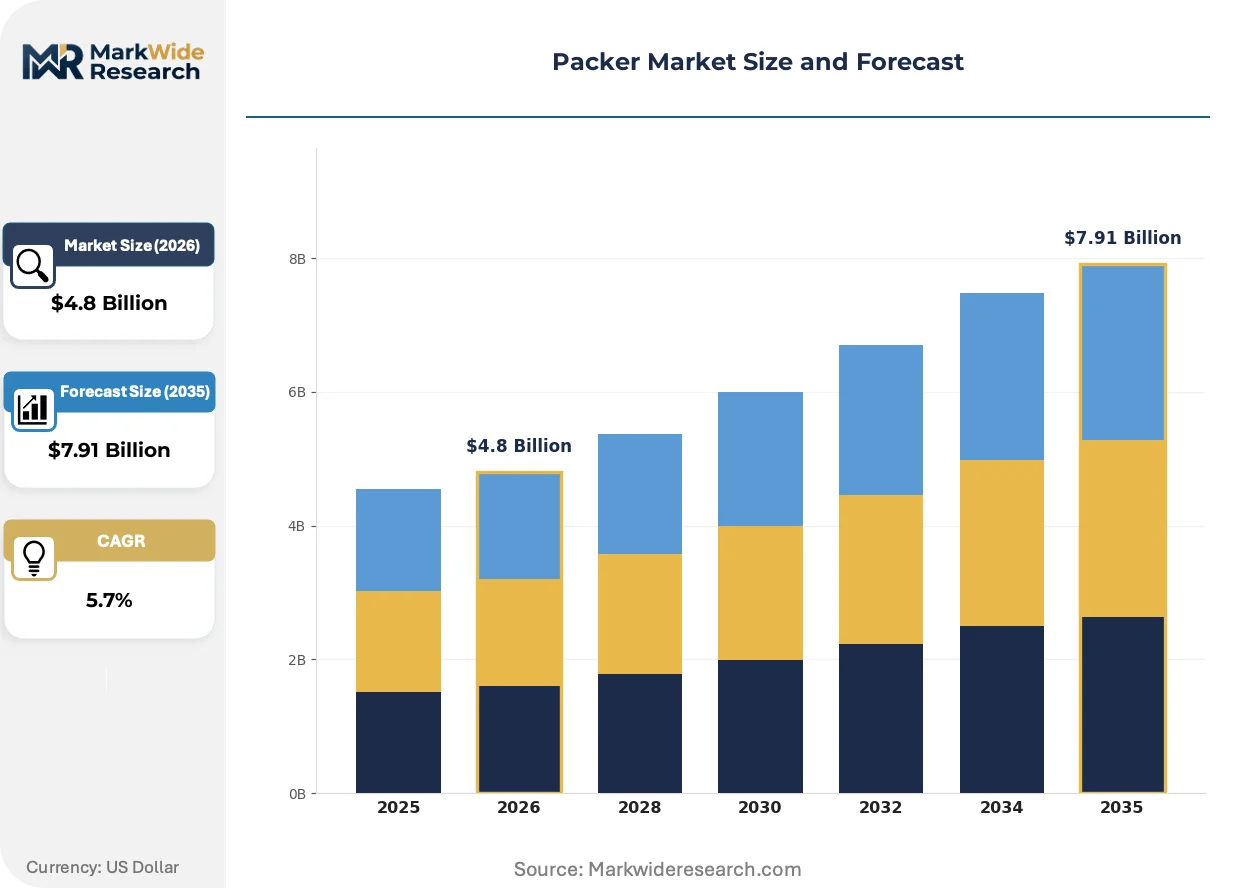
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Packers, Semi-Automatic Packers, Manual Packers, Robotic Packers Packaging Material: Plastic, Glass, Metal, Paper Industry Vertical: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Application: Unit Packing, Bulk Packing, Labeling, Sealing |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, Weatherford International plc, National Oilwell Varco, Packers Plus Energy Services, Logan Completion Systems, TIW, TAM International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packer Market Strategic Shifts
Digitalization of downhole equipment is collapsing the boundary between mechanical isolation devices and real-time reservoir management systems. Vendors must now deliver telemetry-ready hardware or exit premium contract tiers entirely.
Robotic packer systems with adaptive seal geometry are expanding into intelligent well completions across the North Sea and Gulf of Mexico. Subsea operators at Equinor and Shell deploy these units to eliminate intervention vessel calls during pressure regime shifts. The technology is expanding into mid-water depths previously served by manual configurations, compressing addressable market boundaries between automation tiers.
REACH regulation amendments on persistent organic pollutants are forcing reformulation of perfluoroelastomer packer elements used in high-temperature gas wells. European manufacturers face 2026 deadlines to certify replacement compounds or surrender North Sea platform maintenance contracts. German suppliers are accelerating bio-based fluoropolymer development to defend positions in E&P procurement frameworks.
Buying committees at integrated operators now unbundle packer procurement from full-service drilling contracts, creating direct vendor relationships previously mediated by rig contractors. This channel disintermediation concentrates specification authority with reservoir engineers rather than procurement generalists. The shift is most visible in US onshore shale plays where pad drilling standardization enables component-level sourcing at scale.
Packer Market Segmentation
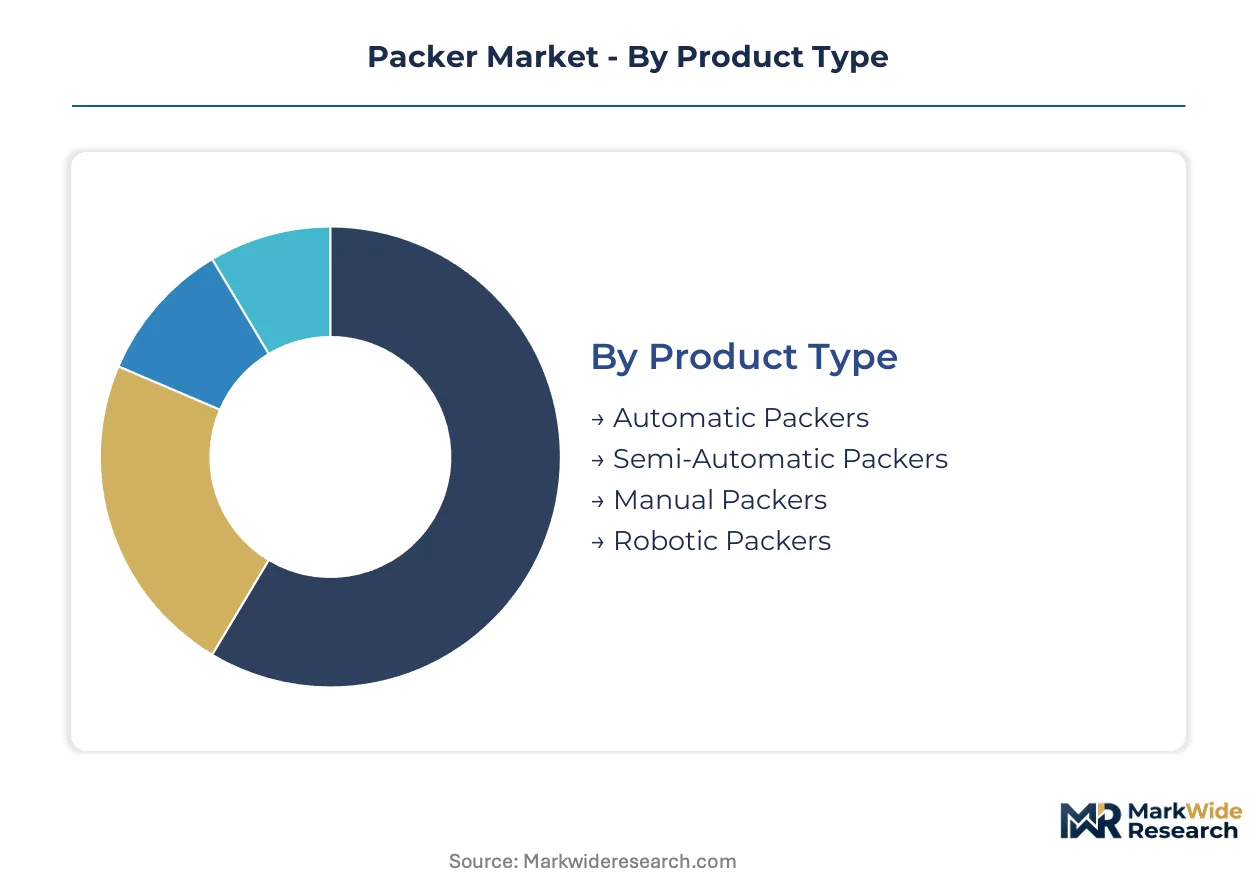
Packer market segmentation reveals divergent capital requirements and technology maturity across automation tiers, material platforms, and end-use specifications. Understanding these structural divisions enables vendors to align R&D spending with segments offering defensible margin positions.
Product Type:
Capital intensity escalates sharply across the automation spectrum, with servo-driven actuation and telemetry integration demanding the heaviest upfront engineering investment.
- Automatic Packers:These systems integrate programmable logic controllers with pneumatic or electric actuation for high-throughput lines. Pharmaceutical manufacturers in the United States deploy these units to satisfy FDA serialization mandates under the Drug Supply Chain Security Act.
- Robotic Packers:Collaborative robotics with vision-guided pick-and-place capabilities enable format changeovers without mechanical retooling. Demand concentrates among contract packaging operations seeking remote actuation to compress labor costs per unit.
- Semi-Automatic Packers:Hybrid configurations blend operator-fed loading with automated sealing cycles, serving mid-size food processors balancing throughput against capital constraints.
- Manual Packers:Benchtop or floor-mounted units rely entirely on operator pacing, persisting in artisanal cosmetics and specialty chemical niches where batch sizes resist automation economics.
Automatic packers absorb the bulk of installed capacity; robotic packers are expanding most quickly.
Packaging Material:
Material selection dictates seal integrity specifications, sterilization compatibility, and regulatory compliance pathways across end-use verticals.
- Plastic:Polyethylene terephthalate and high-density polyethylene formats dominate unit-dose pharmaceutical and beverage applications. Recyclable mono-material structures are gaining specification share as European operators adopt sustainability-linked procurement criteria.
- Metal:Aluminum and tinplate configurations provide barrier protection for aggressive chemical formulations and carbonated beverages. Aseptic filling lines in dairy and ready-to-drink coffee segments specify metal for oxygen exclusion.
- Glass:Borosilicate and soda-lime formats serve parenteral pharmaceuticals and premium cosmetics where inertness and visual clarity command priority over fragility costs.
- Paper:Fiber-based formats with barrier coatings address dry goods and e-commerce secondary packaging, though moisture sensitivity limits penetration in wet-food segments.
Plastic commands the greatest installed base; paper formats are climbing the fastest amid sustainability-driven substitution.
Industry Vertical:
End-use concentration determines batch size distribution, cleanroom requirements, and validation documentation intensity.
- Pharmaceuticals:Serialization, aggregation, and tamper-evidence mandates under FDA and EMA frameworks drive specification for track-and-trace-ready packer configurations with integrated vision systems.
- Food & Beverage:High-volume lines for carbonated soft drinks and shelf-stable dairy demand rotary filling and capping at speeds exceeding 1,000 units per minute.
- Cosmetics:SKU proliferation and premium positioning favor flexible format changeover and decorative finishing capabilities over raw throughput metrics.
- Chemicals:Corrosive resistance and hazardous area electrical classification dominate specification for agrochemical and industrial solvent packaging.
Food and beverage holds the largest equipment population; pharmaceuticals show the steepest expansion trajectory on serialization investment cycles.
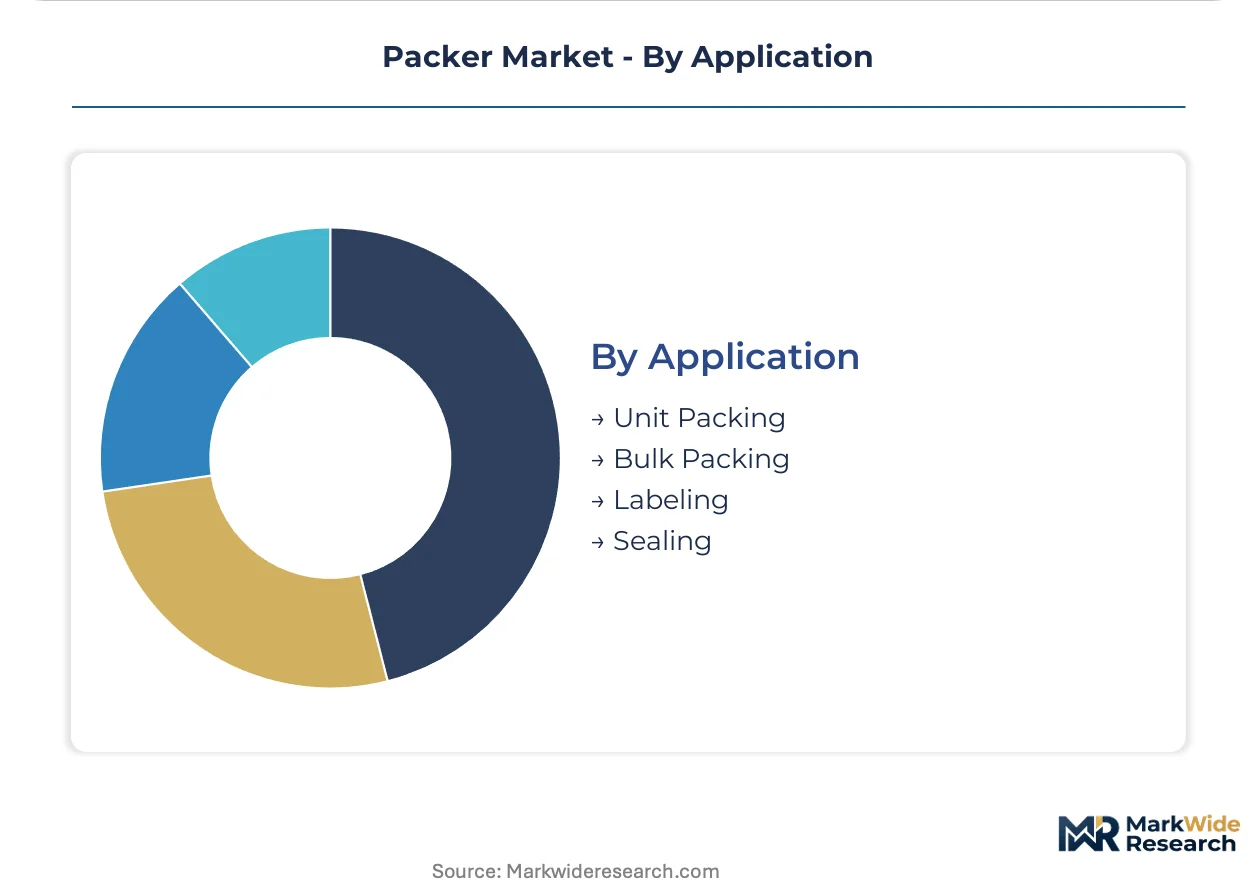
Application:
Functional specialization within packaging lines creates distinct equipment categories with divergent motion control and sensor integration requirements.
- Unit Packing:Individual product containment into primary packages—bottles, blisters, pouches—demands precise dosing and seal integrity verification.
- Bulk Packing:Case packing and palletizing of aggregated units emphasizes robotic depalletizing and layer-forming speed over micron-level tolerances.
- Labeling:Pressure-sensitive, shrink-sleeve, and in-mold labeling systems integrate print verification and rejection mechanisms for regulatory compliance.
- Sealing:Induction, ultrasonic, and heat-seal technologies ensure hermetic closure with validation documentation for sterile barrier maintenance.
Unit packing represents the most saturated equipment category; bulk packing is gaining share fastest on e-commerce fulfillment automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for packer systems concentrates in petroleum-producing economies with active well completion programs and stringent downhole integrity regulations. The United States anchors volume requirements through shale basin redevelopment and offshore Gulf of Mexico activity. Regulatory frameworks in Brazil, Norway, Saudi Arabia, and China are reshaping specification standards for zonal isolation equipment.
United States
The Permian Basin and Gulf of Mexico drive specification upgrades for high-pressure inflatable packers. The EPA enforces methane waste prevention rules mandating tighter annular seal integrity on federal lands. Houston hosts the densest cluster of packer engineering and manufacturing facilities serving domestic shale operators.
Brazil
Pre-salt basin development requires redundant dual-element packer configurations for ultra-deepwater completions. The national petroleum regulator ANP mandates well integrity documentation for all subsea installations. Rio de Janeiro anchors engineering centers supplying floating production systems across the Santos Basin.
Norway
North Sea platform maintenance and decommissioning sustain replacement demand for intelligent well packers. REACH regulation amendments force reformulation of perfluoroelastomer elements by 2026. Stavanger concentrates subsea technology vendors serving Equinor and Aker BP completion programs.
Saudi Arabia
Gas reservoir development and unconventional tight gas programs expand requirements for high-temperature packer systems. The national oil company prioritizes local manufacturing content under in-country value initiatives. Dhahran hosts research centers developing proprietary elastomer formulations for desert well conditions.
China
Sichuan shale gas and Xinjiang tight oil development accelerate domestic packer production capacity expansion. NMPA-aligned standards govern pressure equipment certification for onshore drilling campaigns. Chengdu and Karamay host manufacturing clusters supplying western basin operators with cost-optimized compression-set designs.
Packer Market Competitive Environment
Capacity expansion dominates the current landscape as suppliers retrofit facilities for servo-driven actuation and telemetry integration. The vendor base stratifies across three tiers: integrated oilfield service conglomerates with captive elastomer formulation, specialized packer engineering houses focused on subsea applications, and regional fabricators serving onshore conventional markets. M&A activity concentrates on acquiring intelligent well software capabilities, while strategic partnerships with motion control specialists address mechatronics talent scarcity.
Within the integrated services tier, Schlumberger Limited, Halliburton Company, and Baker Hughes Company exemplify archetypes of vertical scope. Schlumberger occupies a position defined by proprietary material science integration. Halliburton anchors geographic presence in Middle Eastern well completion markets. Baker Hughes sits within the technology leadership vector for expandable systems. These three entities represent the structural concentration against which mid-cap specialists and regional entrants define competitive differentiation strategies.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International plc |
| National Oilwell Varco |
| Packers Plus Energy Services |
| Logan Completion Systems |
| TIW |
| TAM International |
| Others |
Value Chain & Pricing Dynamics
Mechatronics engineering talent concentration in Houston and Stavanger widens pricing spreads between servo-driven intelligent packers and conventional compression-set units, as labor-cost differentials compound with material-grade premiums to stratify procurement tiers.
Pricing Analysis
Volume concentrates in standard compression-set configurations serving mature onshore basins, while margin pools in intelligent packers with fiber-optic telemetry integration for subsea applications. Price differentiation hinges on API 11D1 certification tier and elastomer temperature rating, with fluorocarbon-compound systems commanding substantial premiums over nitrile alternatives. Pricing pressure stems from contract packaging operations in the United States seeking remote actuation capabilities at reduced per-unit labor costs. Mid-size pharmaceutical manufacturers exhibit highest price sensitivity, whereas deepwater operators in Brazil and Norway prioritize seal redundancy over procurement expenditure.
Supply Chain Analysis
Saudi Arabia's in-country value initiatives and Brazil's ANP local-content mandates are forcing packer manufacturers to establish regional fabrication facilities or surrender platform maintenance contracts to domestic suppliers. Specialty elastomer base stocks concentrate in Germany and Japan, with fluoropolymer feedstocks drawing from three chemical suppliers. Single-source vulnerability in high-temperature hydrogenated nitrile exposes packer producers to allocation volatility during upstream polymer plant turnarounds. Distribution runs through integrated oilfield service conglomerates, though direct vendor relationships are expanding as operators unbundle packer procurement from full-service drilling contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with captive elastomer formulation and intelligent well software capabilities, as API 11D1 certification timelines and mechatronics talent scarcity force weaker regional fabricators toward exit or acquisition.
For Market Incumbents: Anticipate margin compression from contract packaging automation demands by securing backward integration into servo-driven actuation components. Prioritize acquisition targets with intelligent well software stacks to capture recurring service revenue streams beyond hardware shipment. For New Entrants and Emerging Players: Launch via direct vendor relationships with reservoir engineers at US shale operators, bypassing rig contractor intermediation. Target mid-water depth intelligent packer retrofits in the Gulf of Mexico, where legacy manual configurations face replacement pressure from subsea intervention cost reduction mandates. For Investors and Strategic Acquirers: Re-rating potential sits with specialized packer engineering houses possessing subsea telemetry integration given Equinor and Shell procurement shifts toward adaptive seal geometry systems. Five-to-ten year viability favors vendors with demonstrated REACH-compliant fluoropolymer reformulation pathways. Watch for EPA methane waste prevention rule enforcement intensity as inflection indicator for inflatable packer specification share.| Strategic Initiative | Industry Significance |
|---|---|
| Intelligent Well Software Acquisition | Captures recurring revenue from Equinor and Shell subsea deployments with adaptive seal geometry. |
| Regional Manufacturing Footprint Expansion | Satisfies Saudi in-country value mandates and Brazil ANP local-content requirements for platform contracts. |
| REACH-Compliant Fluoropolymer Development | Defends North Sea maintenance positions against 2026 persistent organic pollutant deadlines. |
| Servo-Driven Actuation Integration | Compresses rig-time economics for US contract packaging operations under FDA serialization mandates. |
| Direct Reservoir Engineer Channel Development | Exploits operator procurement unbundling from rig contractors in Permian Basin pad drilling. |
Study Parameters
SEC 10-K filings, customs and trade data, and API certification registries formed the secondary backbone, cross-referenced with primary interviews involving completion engineers at integrated operators, procurement leads at national oil companies, elastomer R&D directors at chemical suppliers, and aftermarket service heads at regional packer fabricators. Bottom-up equipment shipment tallies were reconciled with top-down E&P capital expenditure allocations across the analysis window.
Historical trendline analysis of zonal isolation equipment spending informed projection modeling across automation tier, elastomer material platform, well type classification, and regional regulatory cluster dimensions. CAGRs were derived from segment-level growth rate reconciliation with upstream drilling activity forecasts and thermal recovery application expansion trajectories. Intelligent well adoption curves and geothermal energy substitution threats were incorporated as scenario-weighted inputs.
EPA enforcement intensity variability, specialty polymer supply allocation disruptions, and REACH amendment implementation delays are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding sustained shale basin redevelopment and pre-salt basin activity levels. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Strapping Equipment Market
Packaging Equipment
Bagging Equipment Market
Packaging Equipment
Strapping Devices Market
Packaging Equipment
Beverage Packaging Equipment Market
Packaging Equipment
Airless Pumps Market
Packaging Equipment
Powder Dispenser Market
Packaging Equipment
Shrink Wrap Equipment Market
Packaging Equipment
Die-Cutter Market
Packaging Equipment
Vacuum Fillers Market
Packaging Equipment
Clip Applicator Market
Packaging Equipment
Hand Sealers Market
Packaging Equipment
Label Converting Equipment Market
Packaging Equipment
Bottle-Capping Equipment Market
Packaging Equipment
Table Top Band Sealer Market
Packaging Equipment
PIR Blow Molding Market
Packaging Equipment
Industrial Heat Sealers Market