
 Square Pails Market | 2026-2036
Square Pails Market Size, Share, and Industry Trends Forecast 2026-2036
Square Pails Market Analytics
The square pails category is consolidating around two distinct supply tiers. Premium-grade pails with airtight seals and FDA-compliant resins command pricing power in food and pharmaceutical channels. Berry Global Inc. leverages vertical integration across resin sourcing and blow-molding operations to sustain cost advantages. Jokey Plastik Wipperfürth GmbH differentiates through precision-engineered tamper-evident closures that dominate European food-export specifications.
Square pails are rigid, four-sided containers typically manufactured through injection molding or blow molding of high-density polyethylene, steel, or fiber-composite materials, designed for stackable storage and efficient pallet utilization in industrial and commercial logistics. Plastic pails lead volume due to chemical resistance and lightweight handling economics, while metal pails retain margin pools in solvent and flammable liquid applications where UN-certified containment is mandatory. Closure type segmentation shows snap-on lids saturating commodity paint and household segments, whereas screw-on and airtight formats capture growth in food packaging and specialty chemical end uses where evacuation integrity determines shelf stability.
FDA food-contact regulations, EPA hazardous material containment standards, and EU REACH restrictions on phthalate plasticizers collectively elevate compliance costs and disqualify non-certified suppliers from branded food and chemical channels. These frameworks push converters toward documented resin traceability and third-party migration testing. Stakeholders must weigh capital allocation between closure-innovation differentiation and geographic expansion into markets where local certification requirements remain unsettled.
Market Dynamics
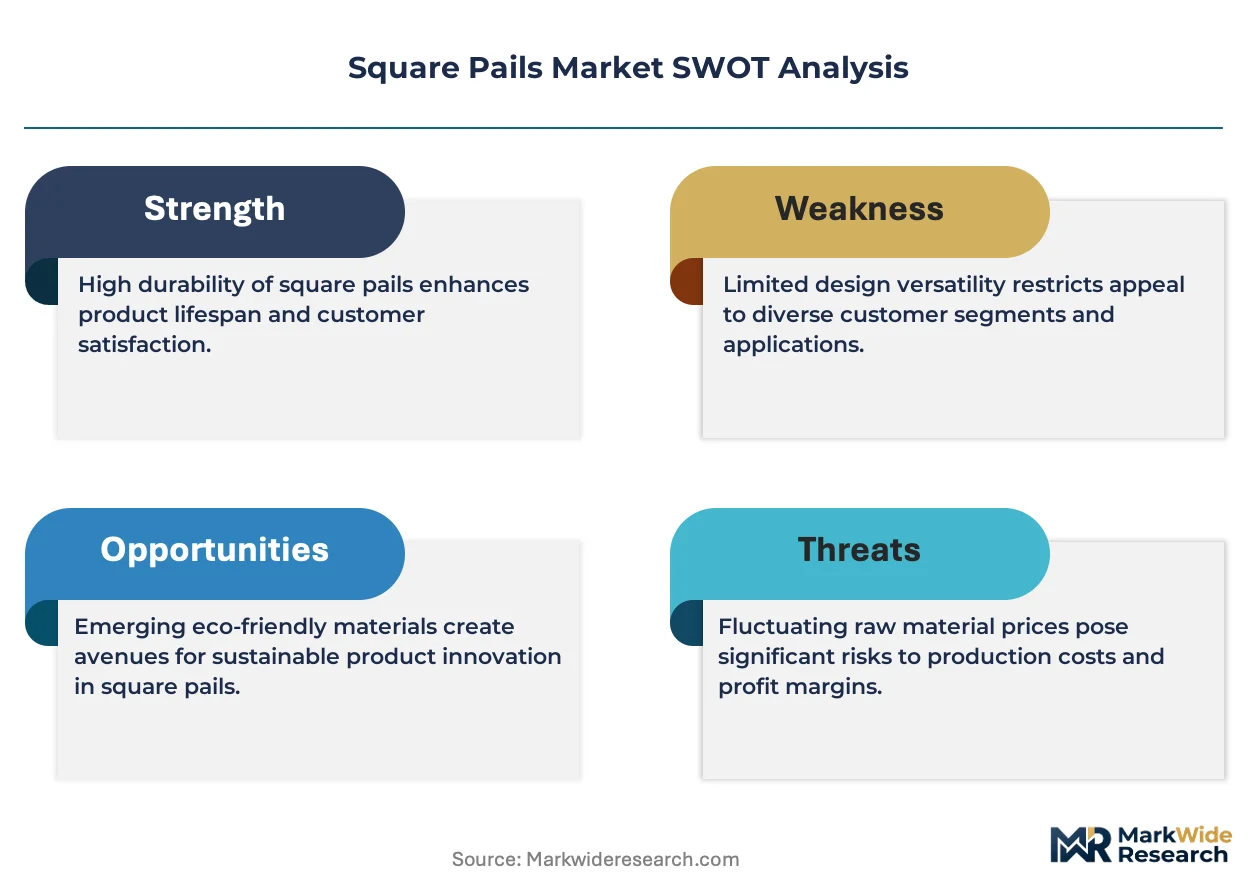
Closure innovation is fragmenting the square pails competitive map, as tamper-evident and airtight sealing technologies separate premium food-grade suppliers from commodity resin molders serving paint and construction channels.
Growth Catalysts
- FDA Food-Contact Modernization:Updated migration testing protocols for polyethylene resins are disqualifying uncertified converters and concentrating volume with documented supply-chain traceability.
- Pharmaceutical Cold-Chain Expansion:Biologics distribution networks in Germany and Switzerland are specifying UN-certified square pails with thermal insulation layers for temperature-sensitive APIs.
- Stackable HDPE Economics:High-density polyethylene formulations achieving 15% weight reduction without dimensional tolerance loss are capturing share from steel pails in non-flammable chemical logistics.
Market Restraints
- Propylene Feedstock Volatility:North American resin converters face margin compression from ethylene and propylene price swings tied to Gulf Coast petrochemical capacity utilization.
- EU REACH Phthalate Restrictions:Plasticizer compliance documentation requirements for food-contact applications extend certification timelines by 8-14 months for non-integrated compounders.
- Fiber-Composite Substitution:Molded pulp containers with biodegradable coatings are capturing shelf-stable dry food segments where moisture barrier requirements are moderate.
Strategic Opportunities
- Indian FSSAI Cold-Chain Mandate:India's 2022 food safety infrastructure rules are creating first-mover advantages for pail suppliers with integrated aseptic filling partnerships.
- Closed-Loop Rental Systems:Industrial pooling models for automotive parts washing and chemical reclamation are shifting ownership economics from purchase to per-use fees.
- RFID-Enabled Smart Closures:Convergence of NFC tags with tamper-evident lids is enabling real-time supply-chain visibility for high-value pharmaceutical and food exports.
Industry Challenges
- Multi-Site Certification Harmonization:Converters operating across US FDA, EU EFSA, and Health Canada jurisdictions face divergent migration testing protocols that complicate SKU rationalization.
- Blow-Molding Tooling Lead Times:Custom multi-cavity molds for precision closure interfaces require 22-28 week procurement cycles that constrain rapid product iteration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Square Pails Market |
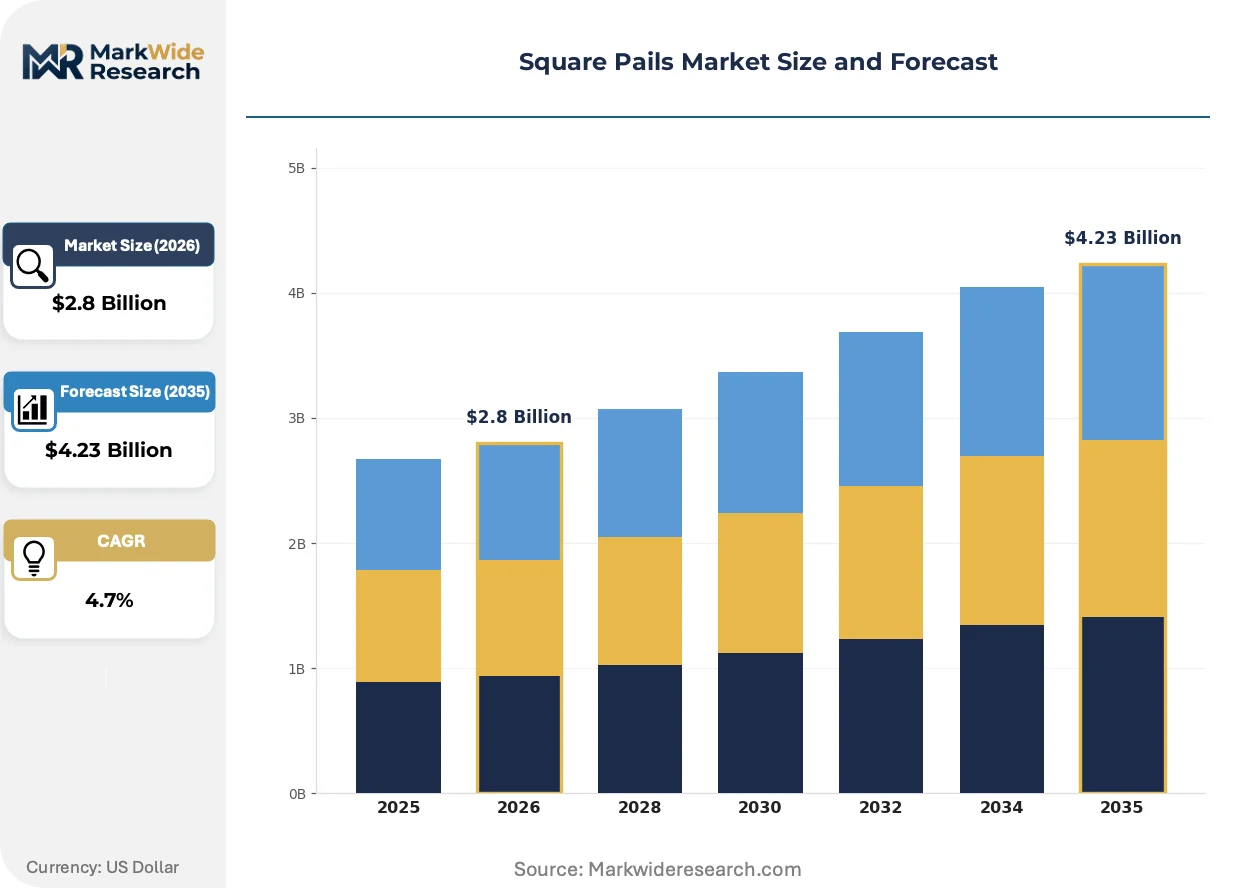
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Metal, Wood, Composite Capacity: 1 Gallon, 5 Gallon, 10 Gallon, 20 Gallon Closure Type: Snap-On Lid, Screw-On Lid, Airtight Seal, Tamper-Evident End Use: Food Packaging, Chemical Storage, Paint, Household Items |
| Companies Covered | M&M Industries Inc., IPL Plastics Inc., Jokey Plastik Wipperfürth GmbH, Pro-Western Plastics Ltd., Berry Global Inc., BWAY Corporation, Greif Inc., Mauser Packaging Solutions, Fox Valley Containers Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Square Pails Market Evolving Landscape
Digital traceability and material science advances are redefining value capture in square pails, shifting competitive advantage from scale economies to verified performance documentation and circular material flows.
Post-consumer recycled HDPE with food-contact clearance is decentralizing resin sourcing strategies for premium pail manufacturers. European dairy and edible oil packers in the Netherlands and Denmark are specifying 30-50% recycled content thresholds in procurement tenders. This material transition is compressing virgin resin offtake volumes while elevating testing and certification costs for converters without in-house recycling capabilities.
EU REACH restrictions on intentionally added microplastics are tightening discharge standards for pail manufacturing facilities by 2027. Wet-processing operations using aqueous cooling systems face capital-intensive filtration upgrades or site relocation. German and Belgian converters with integrated closed-loop water systems are absorbing compliance costs more efficiently than toll processors dependent on municipal treatment infrastructure.
Direct procurement from compounders is displacing distributor intermediaries in North American chemical and food manufacturing accounts. Large volume buyers in Ohio and Texas are negotiating resin-indexed pricing with captive molding operations, bypassing traditional packaging distributors. This channel compression is most visible in specialty chemical verticals where lot traceability and custom color matching justify dedicated supply relationships.
Square Pails Market Segmentation
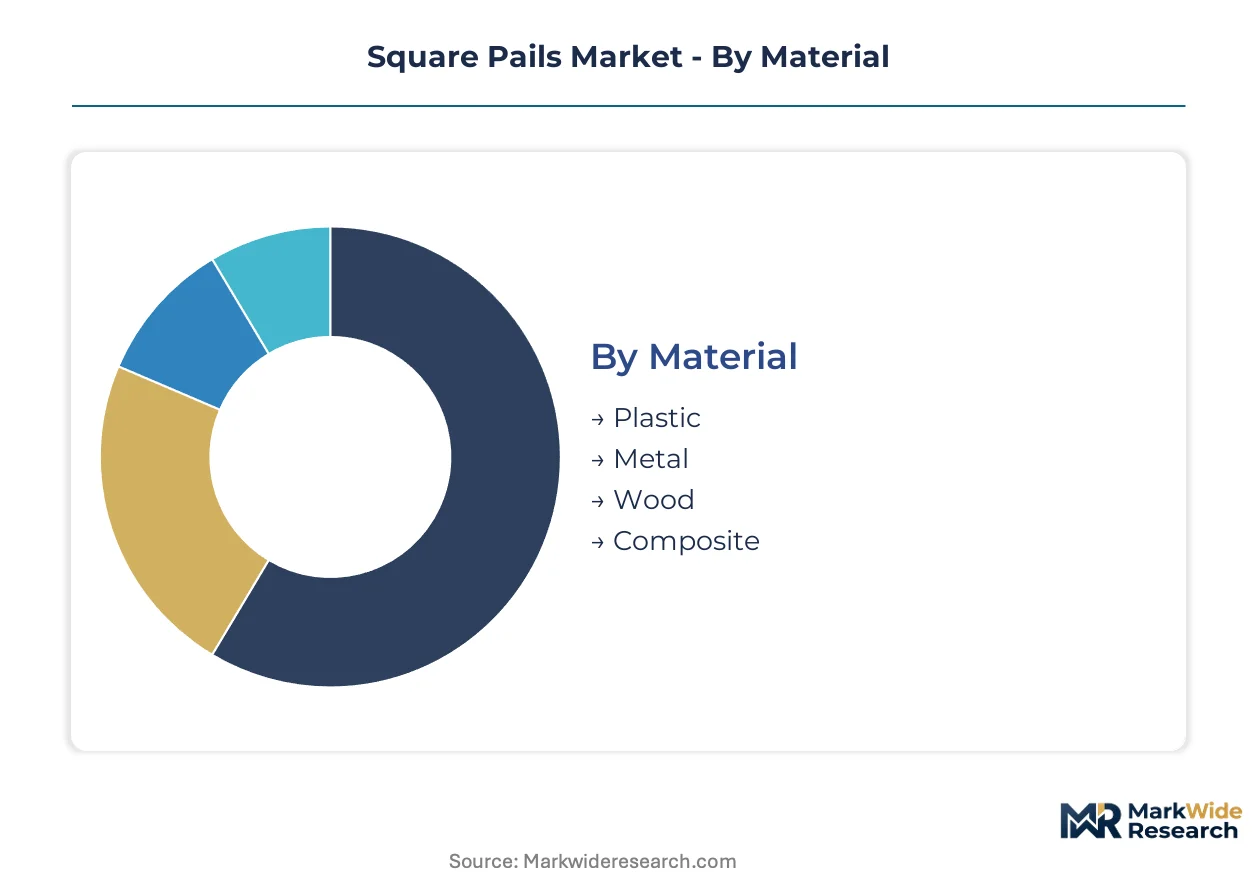
Square pails serve divergent performance requirements across food safety, chemical containment, and logistics efficiency. Material selection and closure engineering determine compliance eligibility and pricing power in each vertical.
Material:
Standardization dominates commodity applications while customization unlocks premium channels requiring certified traceability and specialized barrier properties.
- Plastic:High-density polyethylene formulations deliver chemical resistance and lightweight handling economics. Demand concentrates in United States industrial chemical corridors and European dairy export operations where FDA and EFSA migration testing documentation is mandatory.
- Metal:Cold-rolled steel pails with UN-certified seam welding retain margin pools in solvent and flammable liquid logistics. German automotive parts washers and Texas petrochemical processors specify metal construction where thermal stability and spark resistance override weight considerations.
- Wood:Traditional cooperage formats persist in specialty food fermentation and artisanal packaging niches. Limited volume flows through French wine cooperatives and Scandinavian cured fish exporters.
- Composite:Fiber-reinforced hybrid constructions blend structural rigidity with reduced tare weight. Emerging specifications in Swiss pharmaceutical cold-chain networks favor composite thermal insulation layers.
Most installed capacity flows through Plastic. Expansion is steepest in Composite.
Capacity:
Volume economics and handling ergonomics segment the market across manual, semi-automated, and fully automated filling operations.
- 5 Gallon:The workhorse specification balances cubic utilization with single-person handling limits. Dominates United States paint and coating distribution through Home Depot and Sherwin-Williams supply chains.
- 1 Gallon:Compact footprint serves retail-ready food packaging and specialty chemical sampling. Netherlands-based edible oil packers and Ohio lubricant blenders drive specification refinement for shelf-display compatibility.
- 10 Gallon:Intermediate bulk positioning captures commercial food service and institutional chemical procurement. Danish industrial bakeries and Belgian cleaning compound manufacturers specify this tier for production-floor replenishment cycles.
- 20 Gallon:Maximum manual handling threshold serves bulk ingredient staging and waste collection workflows. German automotive assembly plants and Texas oilfield service operators deploy for parts washing fluid management.
5 Gallon holds the largest installed base. 1 Gallon is gaining share fastest in premium food packaging.
Closure Type:
Security requirements and evacuation integrity standards differentiate commodity supply from certified food and pharmaceutical channels.
- Tamper-Evident:Break-ring or shrink-band mechanisms provide visible breach indication for high-value contents. Swiss biologics distributors and Indian FSSAI-regulated cold-chain operators mandate this format for API and temperature-sensitive food exports.
- Airtight Seal:Gasketed compression closures maintain oxygen and moisture barriers. Concentrated demand from Netherlands dairy powder exporters and Ohio specialty chemical manufacturers where shelf stability determines product integrity.
- Screw-On Lid:Threaded engagement enables resealable access for multi-use applications. Saturates United States household and institutional cleaning product segments.
- Snap-On Lid:Friction-fit engagement minimizes unit cost for single-use or short-cycle applications. Dominates construction and paint segments where resealability is secondary to initial containment.
Snap-On Lid commands the broadest installed base. Tamper-Evident shows the steepest expansion trajectory in regulated food and pharmaceutical channels.
End Use:
Regulatory intensity and performance certification requirements stratify end-use segments by margin potential and supplier qualification barriers.
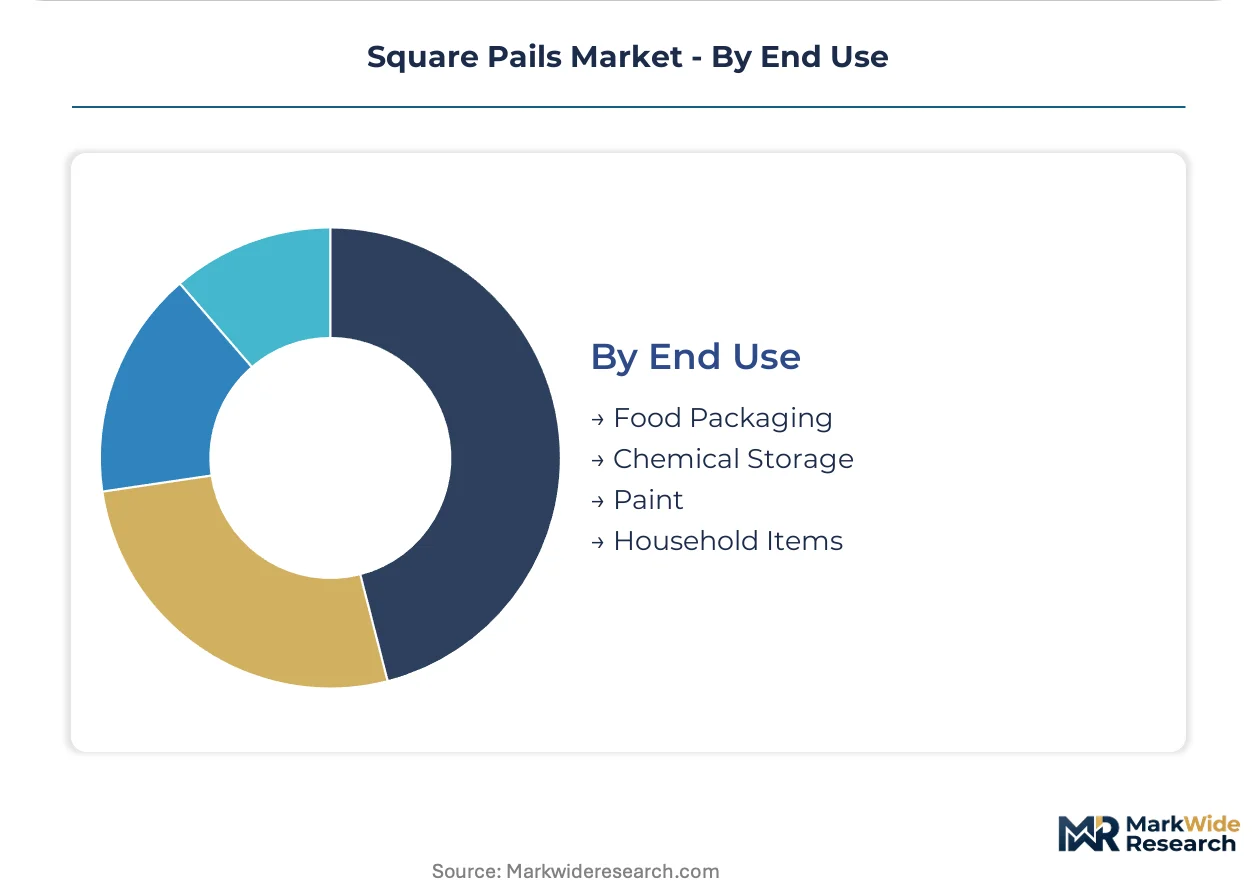
- Food Packaging:FDA food-contact and EU REACH compliance documentation elevates supplier qualification thresholds. Concentrated volume from Netherlands dairy processors, Danish edible oil packers, and Indian FSSAI-mandated cold-chain infrastructure buildouts.
- Chemical Storage:EPA hazardous material containment and UN certification requirements govern specification. Texas petrochemical clusters and German industrial chemical distributors drive demand for documented lot traceability.
- Paint:Color-matching consistency and viscosity compatibility determine supplier relationships. United States architectural coating manufacturers in Ohio and California specify custom-molded pails with integrated pour spouts.
- Household Items:Cost-optimized specifications prioritize shelf presence and retail cube efficiency. Mass merchant procurement in United States and European discount channels dominates volume.
Chemical Storage represents the largest installed capacity segment. Food Packaging is expanding most quickly as regulatory compliance concentrates volume with certified suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium-tier specification authority while the United States anchors volume throughput in industrial chemical corridors. Regulatory divergence between FDA migration protocols and EU REACH phthalate restrictions is fragmenting supplier qualification pathways across Atlantic trade lanes.
United States
Texas and Ohio petrochemical clusters drive HDPE pail consumption for solvent logistics and specialty chemical containment. EPA hazardous material containment standards mandate UN-certified documentation for flammable liquid transport. The Gulf Coast resin corridor faces margin pressure from propylene feedstock volatility tied to regional cracker utilization rates.
Germany
Automotive parts washers and industrial chemical distributors specify metal pail construction where thermal stability overrides weight economics. ECHA REACH restrictions on intentionally added microplastics tighten discharge standards for manufacturing facilities by 2027. Bavarian and North Rhine-Westphalian converters with closed-loop water systems absorb compliance costs more efficiently than toll processors.
India
FSSAI cold-chain infrastructure buildouts are creating first-mover advantages for suppliers with integrated aseptic filling partnerships. The 2022 food safety infrastructure rules mandate tamper-evident formats for temperature-sensitive food exports. Maharashtra and Gujarat dairy processors are scaling procurement of documented supply-chain traceability systems.
Netherlands
Edible oil packers and dairy powder exporters specify 30-50% post-consumer recycled HDPE content thresholds in procurement tenders. EFSA migration testing documentation is mandatory for food-contact polyethylene resins. Rotterdam-area converters are compressing virgin resin offtake volumes while elevating certification costs for non-integrated compounders.
Switzerland
Biologics distribution networks specify UN-certified square pails with thermal insulation layers for temperature-sensitive APIs. Swissmedic pharmaceutical packaging regulations govern cold-chain integrity documentation. Basel and Zurich logistics hubs are driving specification refinement for high-value pharmaceutical exports.
Square Pails Market Competitive Landscape
Top-tier vendors anchor premium food-grade and pharmaceutical channels, while commodity resin molders serve paint and construction segments with cost-optimized specifications. The competitive map fragments across three strategic archetypes: integrated resin-to-pail converters, precision closure specialists, and regional toll molders. M&A activity concentrates among mid-cap European fabricators seeking FDA-compliant US assets. Capacity expansion focuses on multi-cavity blow-molding lines for precision closure interfaces.
Among North American industrial packaging groups, Berry Global Inc. and Greif Inc. represent scale-driven archetypes with captive supply chain control. Jokey Plastik Wipperfürth GmbH anchors the European precision-engineered closure tier. These three entities exemplify divergent competitive positioning: backward integration into resin sourcing, metal-steel hybrid fabrication, and tamper-evident lid specialization respectively.
| Leading Market Players |
|---|
| M&M Industries Inc. |
| IPL Plastics Inc. |
| Jokey Plastik Wipperfürth GmbH |
| Pro-Western Plastics Ltd. |
| Berry Global Inc. |
| BWAY Corporation |
| Greif Inc. |
| Mauser Packaging Solutions |
| Fox Valley Containers Inc. |
| Others |
Value Network & Pricing Analysis
Ethylene and propylene price indices on the Gulf Coast cascade through HDPE resin contracts into three-tier pricing structures across premium, standard, and economy levels. Converters with backward integration into resin sourcing capture margin insulation unavailable to toll molders exposed to spot market volatility.
Pricing Analysis
Capacity additions in Texas and Louisiana are reshaping price floors for commodity-grade square pails while premium food-contact specifications sustain pricing power. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified pails with documented traceability from uncertified construction-grade alternatives. Cost compression in standard-grade segments is intensifying because fiber-composite substitutes are capturing shelf-stable dry food applications. Paint and household buyers exhibit highest price sensitivity, whereas pharmaceutical cold-chain operators accept premium pricing for UN-certified thermal insulation.
Supply Chain Analysis
Single-source vulnerability sits with Gulf Coast petrochemical complexes supplying virgin HDPE resin to North American converters. Manufacturing concentrates in the United States, Germany, and India, with each hub serving distinct regulatory certification requirements. Raw material inputs draw from ethylene crackers, colorant compounders, and closure injection molders. Tariff exposure on Chinese-manufactured closure components presents structural risk for non-integrated assemblers. Distribution runs through direct procurement relationships with large chemical and food manufacturers, bypassing traditional packaging distributors in North American accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The square pails market represents a late-cycle quality story as food packaging buyers shift procurement toward tamper-evident and airtight specifications with full supply-chain documentation.
For Market Incumbents: Deepen backward integration into post-consumer recycled HDPE sourcing to meet Netherlands and Denmark procurement thresholds. Invest in multi-cavity blow-molding tooling for precision closure interfaces before EU REACH microplastic discharge standards tighten in 2027. Fiber-composite substitution in dry food segments threatens commodity resin volumes. For New Entrants and Emerging Players: Begin with Indian FSSAI cold-chain infrastructure buildouts where integrated aseptic filling partnerships create first-mover advantages. Target Maharashtra and Gujarat dairy processors seeking documented traceability systems. License tamper-evident closure designs from European precision engineers rather than developing proprietary molds. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap European fabricators possessing FDA-compliant US assets and closed-loop water systems for REACH compliance. Five-to-ten year viability hinges on certification moats rather than scale economies. Watch for propylene feedstock volatility triggering distressed consolidation among non-integrated Gulf Coast converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Resin Sourcing | Post-consumer HDPE clearance from FDA enables participation in Netherlands dairy procurement tenders. |
| Multi-Cavity Blow-Molding Capacity Expansion | Precision closure interfaces capture pharmaceutical cold-chain specifications from Swiss biologics distributors. |
| Closed-Loop Water System Installation | German and Belgian converters absorb EU REACH microplastic discharge costs more efficiently than toll processors. |
| Aseptic Filling Partnership Development | Indian FSSAI cold-chain mandates require integrated solutions beyond standalone pail manufacturing. |
| RFID-Enabled Smart Closure Launch | NFC tag convergence with tamper-evident lids enables real-time visibility for high-value pharmaceutical exports. |
Research Methodology
Coverage spans the United States, Germany, India, Netherlands, and Switzerland, with primary inputs from each market. Conversations with blow-molding plant managers, procurement leads at chemical and food manufacturers, distribution channel partners, and technical R&D directors combined with customs and trade data, SEC filings, ECHA REACH registration databases, and FSSAI compliance records. Bottom-up volume estimates triangulated against top-down resin consumption figures.
Rate-of-change decomposition across material grade, closure type, capacity tier, end-use vertical, and regional regulatory cluster informed the analytical framework. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Migration testing protocol evolution and feedstock price volatility served as industry-specific forecast sensitivity inputs across the analysis window.
Caveats apply where FDA food-contact modernization timelines or EU REACH enforcement intensity could materially shift the outlook. Forecasts reflect assumptions about certification documentation requirements and propylene cracker utilization rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Global Multi Pack Carriers Market
Containers
Wet Wipes Canister Market
Containers
Containerboard Market
Containers
Old Corrugated Containers (OCC) Market
Containers
Conipack Pails Market
Containers
EMEA Container Technology Market
Containers
Corrugated Open-Head Drums Market
Containers
Slip Lid Can Market
Containers
Kuwait Container Glass Market
Containers
Jars Market
Containers
Cubitainer Market
Containers
Disposable Cups and Lids Market
Containers
Dispensing Jug Market
Containers
High Density Polyethylene (HDPE) Bottles Market
Containers
Wire Containers Market
Containers
Compartment Trays Market