
 Two Compartment Bottles Market | 2026-2036
Two Compartment Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Two Compartment Bottles Market Analytics
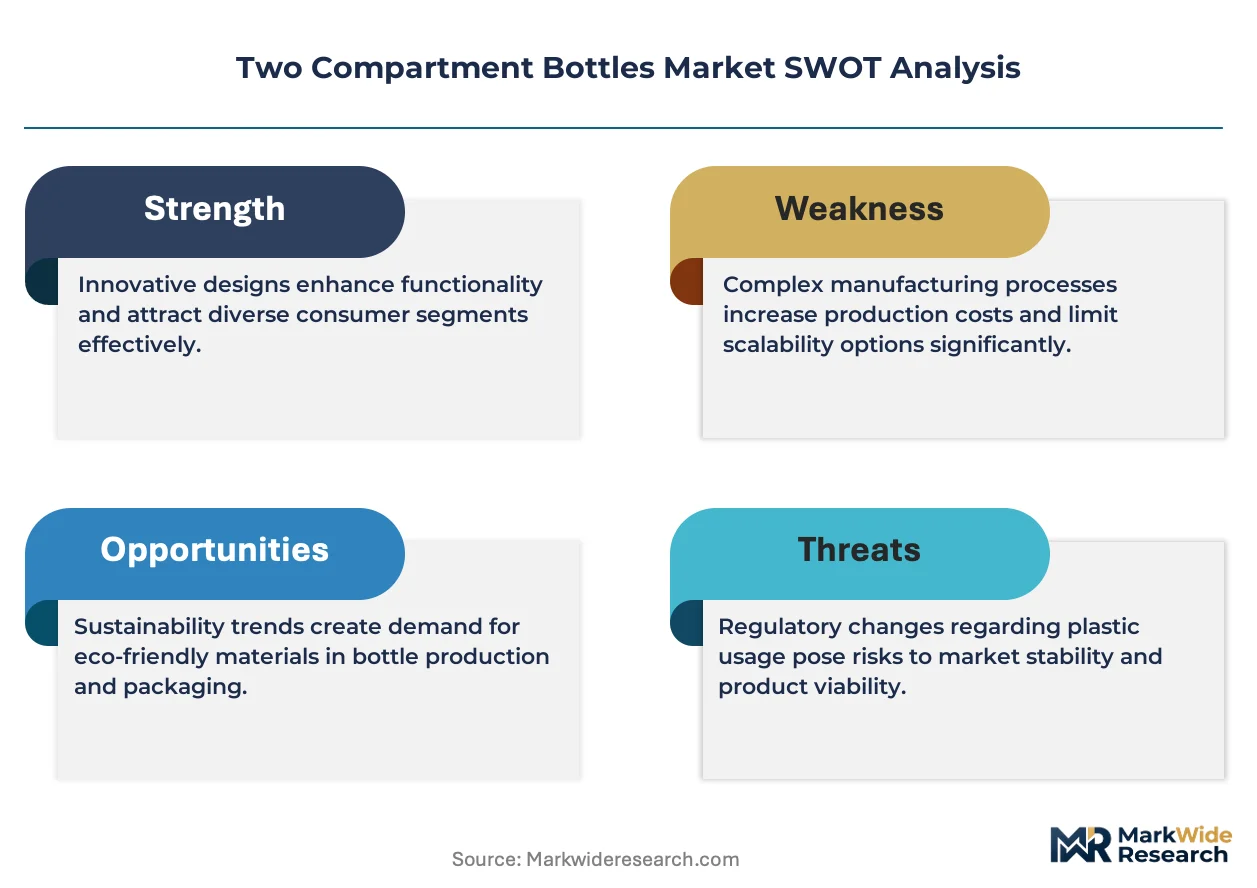
ISO 9001 quality management certification is unwinding the competitive field, filtering out regional molders lacking documented process controls. Plastic Technologies Inc. leverages deep preform engineering expertise to dominate complex barrier designs. Silgan Holdings Inc. sustains manufacturing scale across North American blow-molding facilities. AptarGroup Inc. differentiates through precision dispensing closures integrated with dual-chamber bodies.
Two compartment bottles are rigid or semi-rigid containers featuring an internal partition that isolates two distinct substances—liquids, powders, or gels—until user activation, typically manufactured through extrusion blow molding or injection stretch blow molding with secondary welding or overmolding of the divider. The design serves pharmaceutical titration, cosmetic serum mixing, and on-the-go nutritional supplement preparation where stability and shelf life depend on ingredient separation until consumption. Plastic variants lead volume due to cost-efficient polyethylene terephthalate and polypropylene processing, though glass commands premium positioning in pharmaceutical and cosmetic applications where inertness and recyclability drive selection. Leak-proof design features attract food delivery and beverage brand procurement as spillage liability shapes purchasing criteria.
FDA food-contact substance notifications govern polymer selection and additive migration limits for nutritional supplement and beverage applications in the United States. The EU REACH regulation and F-Gas Regulation constrain fluorinated barrier treatments and propellant systems used in some dual-chamber cosmetic and pharmaceutical formats. China's GB standards and NMPA packaging guidelines impose additional material testing protocols for imported pharmaceutical containers. Stakeholders must monitor evolving extended producer responsibility frameworks across these jurisdictions, as compliance documentation increasingly determines supplier qualification and contract renewal outcomes.
Market Dynamics
ISO 9001 certification requirements are filtering the supplier base, eliminating regional molders lacking documented process controls and documented quality management systems. This structural force is concentrating procurement among certified manufacturers capable of meeting pharmaceutical and nutritional supplement brand standards.
Growth Catalysts
- Nutritional Supplement Format Innovation:Powder-plus-liquid dual-chamber designs address on-the-go consumption patterns. Brands accelerate procurement to capture convenience-seeking consumers.
- REACH and F-Gas Regulation:EU constraints on fluorinated barrier treatments create demand for compliant alternative materials. Packagers invest in non-fluorinated barrier technologies to maintain market access.
- Injection Stretch Blow Molding:Advanced ISBM processes enable thinner-wall designs with maintained barrier performance. Equipment upgrades at tier-one molders expand production capacity for complex geometries.
Market Restraints
- Polymer Price Volatility:PET and polypropylene feedstock costs fluctuate with crude oil indices. Margin compression limits pricing flexibility for standardized container formats.
- Specialized Welding Equipment Concentration:Divider-sealing machinery suppliers cluster in Germany and Japan. Equipment lead times extend to 8-14 months, constraining capacity expansion.
- Glass Substitution in Premium Pharma:Inertness requirements for high-value biologics favor borosilicate vials. Plastic dual-chamber designs face adoption ceilings in parenteral applications.
Strategic Opportunities
- China NMPA Compliance Services:Imported pharmaceutical container testing protocols create advisory revenue streams. Local certification partnerships unlock domestic pharma brand procurement.
- Extended Producer Responsibility Frameworks:EU packaging waste directives mandate design-for-recycling standards. Early compliance positions suppliers for preferred vendor status under evolving EPR schemes.
- Smart Closure Integration:NFC-enabled caps converging with dual-chamber bodies enable dose-tracking and authentication. Cosmetic and pharma brands pilot connected packaging for adherence monitoring.
Industry Challenges
- Multi-Material Separation Expertise:Barrier-layer coextrusion and welding process engineering requires specialized technicians. Talent scarcity extends R&D timelines for new format development.
- ISO 15378 Certification Timelines:Pharmaceutical packaging quality management audits consume 12-18 months. Delayed certification gates contract renewals with GMP-compliant buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two Compartment Bottles Market |
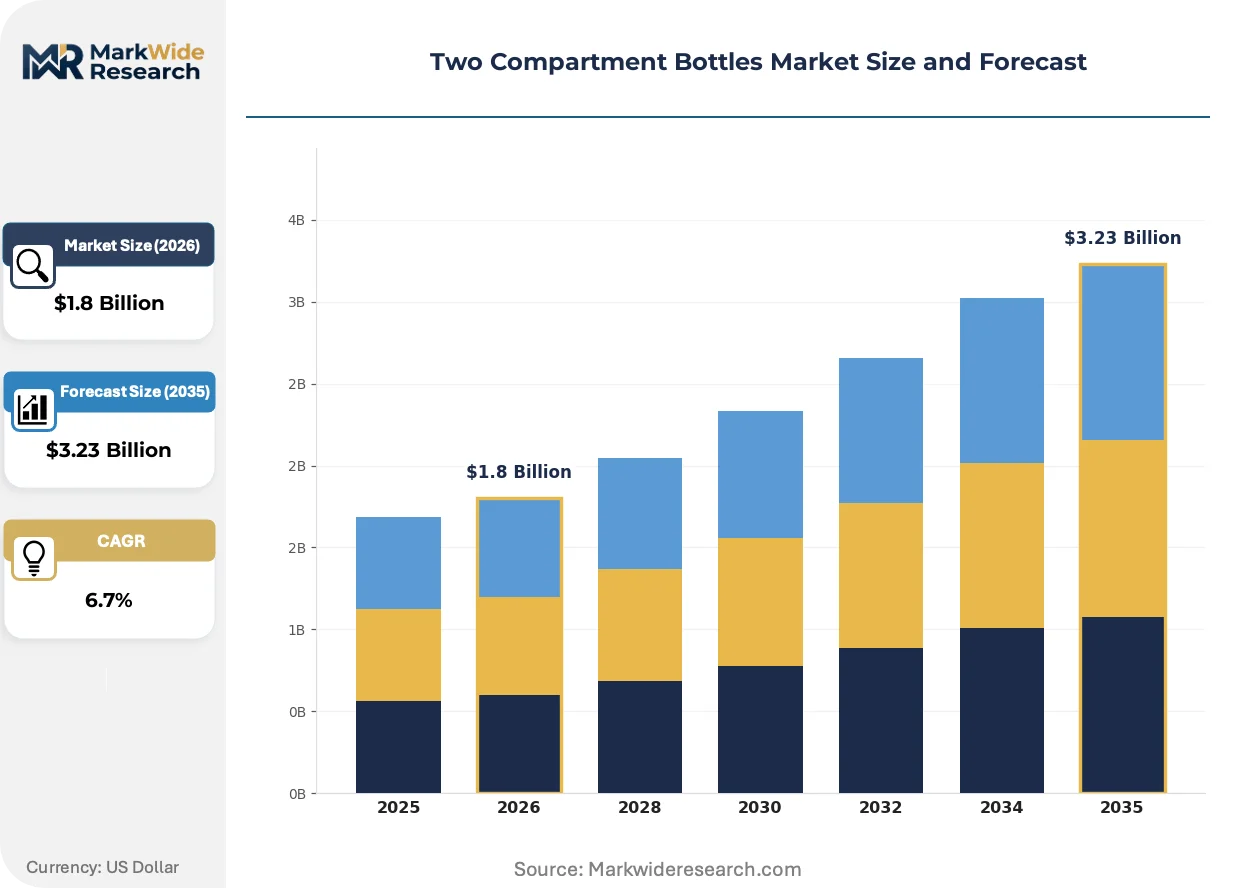
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Metal, Silicone End User: Consumers, Restaurants, Food Delivery, Beverage Brands Application: Cosmetics, Pharmaceuticals, Food & Beverage, Nutritional Supplements Design Feature: Child-Resistant, Leak-Proof, Insulated, Customizable |
| Companies Covered | Plastic Technologies Inc., Golchi LLC, Duothirst, HydraCup, BlenderBottle Company, SmartShake, AptarGroup Inc., Silgan Holdings Inc., Raepak Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two Compartment Bottles Market Evolving Landscape
Barrier material engineering and regulatory compliance automation are restructuring competitive capabilities. Manufacturers differentiate through specialized welding processes and integrated quality documentation systems rather than commodity volume.
Coextruded EVOH barrier layers are bifurcating the standard PET dual-chamber segment. Nutritional supplement brands with 18-24 month shelf-life requirements specify oxygen transmission rates below 0.5 cc/pkg/day. This specification tier is compressing margins for single-layer PET molders while expanding premium positioning for barrier specialists.
FDA food-contact substance notification requirements are tightening additive migration documentation. Polymer suppliers must submit comprehensive extraction studies for new resin grades. Nutritional supplement and beverage packagers in the United States are consolidating supplier lists to pre-qualified FCN holders to avoid regulatory delays.
Brand procurement teams are compressing supplier qualification cycles from 24 months to 14 months. Pharmaceutical and cosmetic packagers demand integrated quality documentation portals with real-time batch traceability. Germany and the United States show the fastest adoption of digital supplier scorecards linking ISO 9001, ISO 15378, and customer-specific audit results.
Two Compartment Bottles Market Segmentation
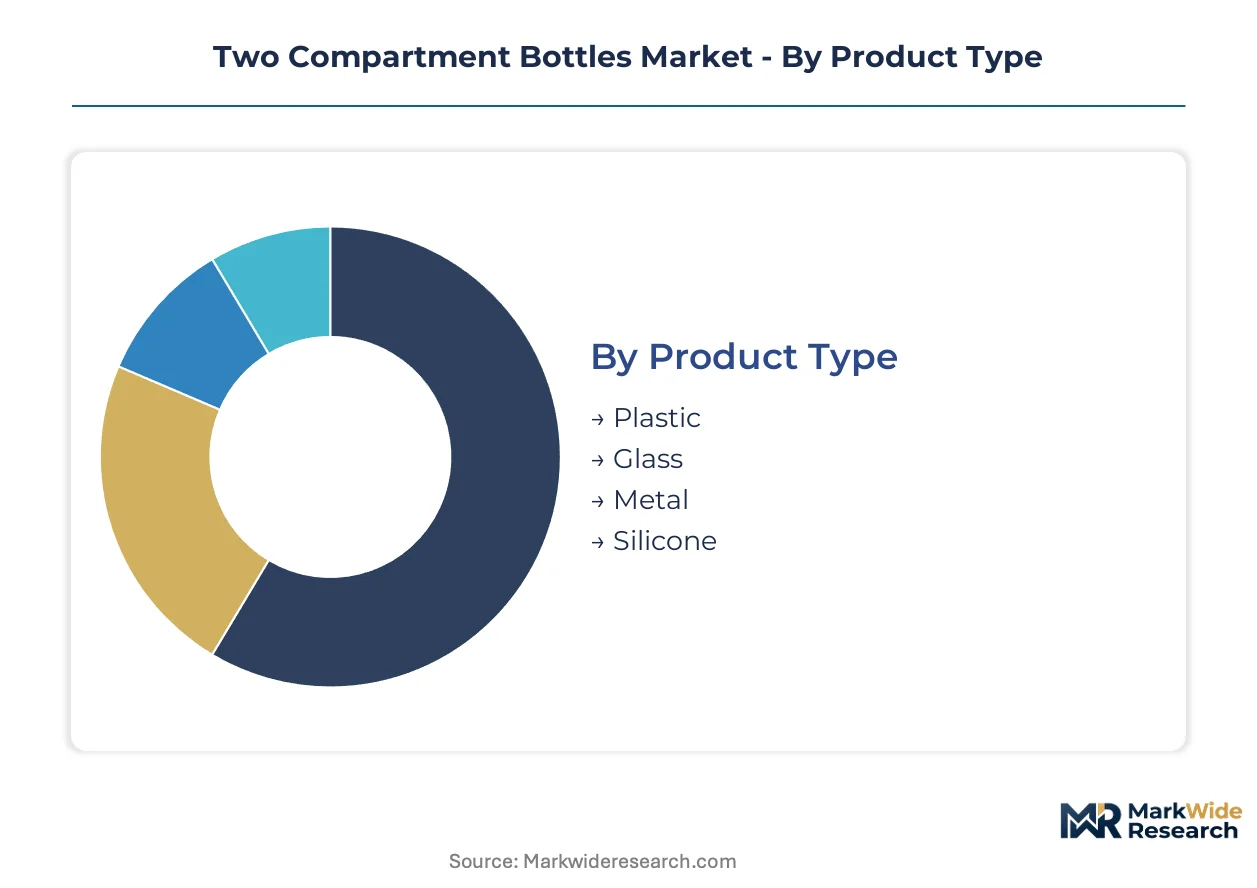
Two compartment bottles serve divergent performance requirements across pharmaceutical stability, beverage convenience, and cosmetic premiumization. Segment boundaries blur as multi-functional designs penetrate adjacent end-use categories. Procurement teams prioritize specification tiers that align with regulatory exposure and brand positioning.
Product Type:
Domestic production concentrates on plastic formats in China, Germany, and the United States, while glass and metal variants flow through specialized import channels serving premium pharma and cosmetic brands.
- Plastic:Polyethylene terephthalate and polypropylene dominate through cost-efficient extrusion blow molding. Beverage brands and nutritional supplement packagers in the United States specify oxygen barrier coextrusions for extended shelf-life formats.
- Glass:Borosilicate and soda-lime constructions command pharmaceutical and cosmetic applications where inertness and recyclability outweigh unit cost. European Union REACH compliance documentation drives supplier consolidation among pre-qualified molders.
- Metal:Aluminum dual-chamber designs serve insulated beverage applications with thermal retention requirements. Niche penetration in premium food delivery formats.
- Silicone:Flexible partition designs enable collapsible travel formats. Limited volume through specialty consumer goods distributors.
Plastic holds the largest share; momentum sits with glass as EPR frameworks elevate recyclability premiums.
End User:
Volume scales inversely with customization complexity, with institutional buyers demanding standardized specifications and consumer channels accepting format experimentation.
- Consumers:On-the-go nutritional supplement preparation and cosmetic serum mixing drive direct-to-retail procurement. Convenience-seeking demographics in Germany and China accelerate dual-chamber adoption for powder-plus-liquid formats.
- Restaurants:Sauce-plus-dressing and beverage concentrate applications require food-grade compliance with rapid throughput. Leak-proof specifications dominate purchasing criteria to eliminate spillage liability.
- Food Delivery:Hot-and-cold separation designs address meal kit temperature integrity. Insulated variants gain traction among platform logistics providers.
- Beverage Brands:Mix-to-activate formats for functional drinks and probiotic shots. FDA food-contact substance notification requirements filter supplier qualification to pre-certified polymer sources.
Consumers represent the deepest volume base; beverage brands are climbing the fastest as activation formats proliferate.
Application:
Regulatory stringency stratifies material selection, with pharmaceutical and nutritional supplement applications imposing the most demanding barrier and documentation requirements.
- Cosmetics:Serum-plus-activator designs preserve ingredient potency through separated storage. Premium positioning in South Korean and French beauty markets demands precision dispensing closure integration.
- Pharmaceuticals:Titration and reconstitution formats for parenteral and oral applications. ISO 15378 certification gates contract eligibility with GMP-compliant buyers.
- Food & Beverage:Dual-chamber condiment and beverage concentrate packaging. Leak-proof and child-resistant specifications shape procurement scoring.
- Nutritional Supplements:Powder-plus-liquid formats address on-the-go consumption patterns. Brands specify EVOH barrier layers for 18-24 month shelf-life requirements.
Pharmaceuticals command the highest unit margins; nutritional supplements are gaining share fastest as format innovation accelerates.
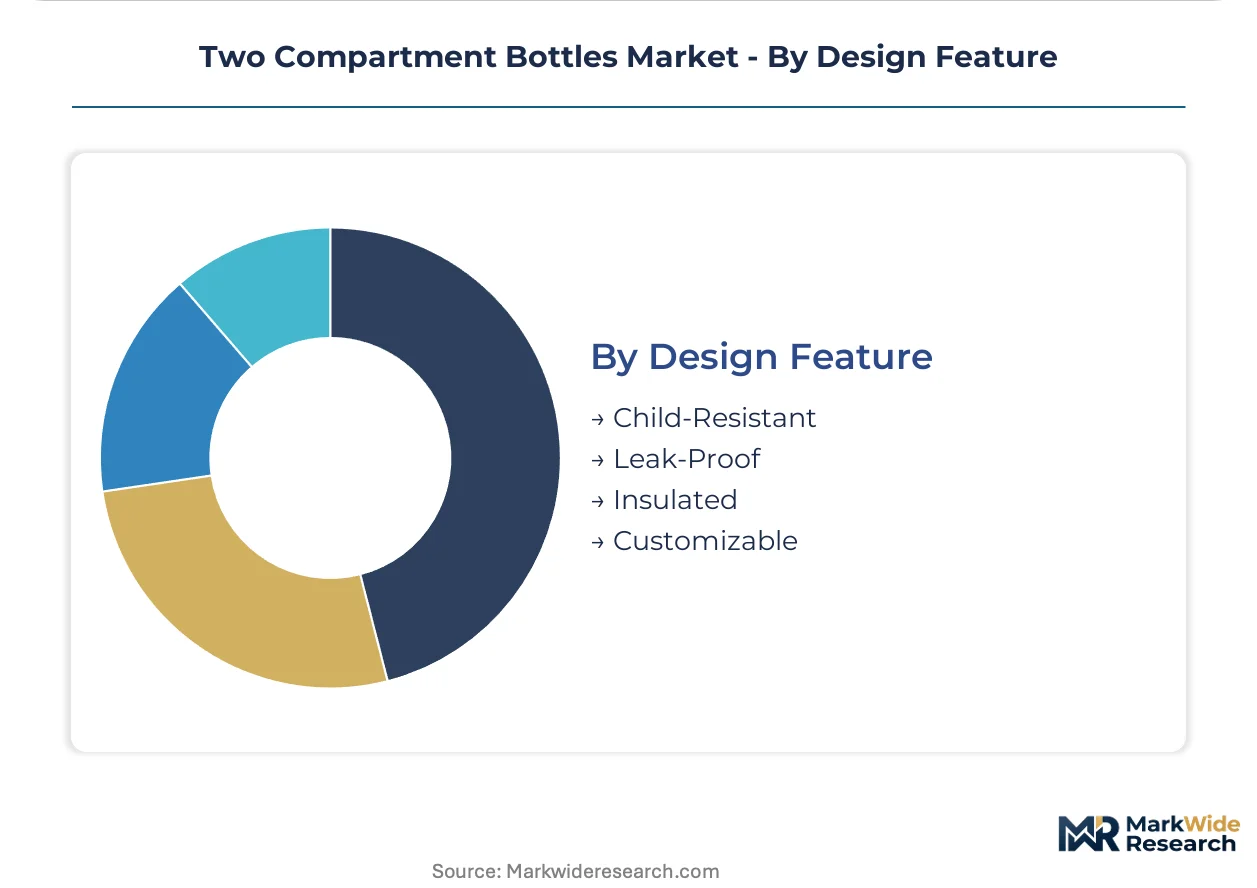
Design Feature:
Functional specifications increasingly bundle multiple attributes, with child-resistant and leak-proof combinations becoming baseline for food and pharmaceutical applications.
- Child-Resistant:Push-and-turn or squeeze-and-lift mechanisms integrated with dual-chamber bodies. Mandatory for pharmaceutical and certain nutritional supplement formats under FDA and EU safety directives.
- Leak-Proof:Precision welding and gasket engineering prevent cross-chamber contamination. Food delivery and beverage brand procurement teams weight spillage liability heavily in vendor scoring.
- Insulated:Double-wall vacuum or foam-in-place constructions for thermal retention. Metal and specialized plastic variants serve food delivery and outdoor beverage applications.
- Customizable:Brand-owned mold investments and digital printing compatibility. Cosmetic and premium beverage segments drive decoration complexity.
Leak-proof specifications hold the largest share; insulated designs are expanding most quickly as food delivery platforms scale cold-chain requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage brands and pharmaceutical packagers concentrate procurement in Germany, China, and the United States, with nutritional supplement format innovation accelerating dual-chamber adoption across these demand clusters.
United States
FDA food-contact substance notifications govern polymer selection for nutritional supplement and beverage applications. Domestic packagers consolidate supplier lists to pre-qualified FCN holders to avoid regulatory delays. Greater Boston and New Jersey pharmaceutical corridors drive ISO 15378-certified dual-chamber procurement for titration formats.
Germany
EU REACH and F-Gas Regulation constraints on fluorinated barrier treatments create demand for compliant alternative materials. Bavarian and North Rhine-Westphalian molding clusters invest in non-fluorinated barrier technologies. Divider-sealing machinery suppliers in southern Germany extend equipment lead times to 8-14 months.
China
NMPA packaging guidelines impose material testing protocols for imported pharmaceutical containers. Yangtze River Delta and Pearl River Delta molders scale domestic production of PET dual-chamber formats. Local certification partnerships unlock procurement from domestic pharma brands seeking compliant container sources.
Japan
METI industrial standards and PMDA pharmaceutical packaging guidelines shape material qualification requirements. Osaka-Kobe and Nagoya manufacturing belts specialize in precision welding processes for cosmetic serum-plus-activator designs. Japanese cosmetic brands pilot NFC-enabled closure integration for adherence monitoring.
South Korea
MFDS pharmaceutical packaging regulations and K-beauty export requirements drive premium dual-chamber specification. Seoul Capital Area cosmetic packagers demand precision dispensing closure integration for serum mixing formats. Domestic brands specify EVOH barrier layers for 18-24 month shelf-life requirements in nutritional supplement applications.
Two Compartment Bottles Market Competitive Landscape
Player mix skews toward specialized molders with barrier engineering capabilities and diversified packaging conglomerates with integrated closure systems. Tier-one manufacturers with ISO 9001 and ISO 15378 certifications capture pharmaceutical and nutritional supplement procurement. Two strategic archetypes dominate: barrier specialists leveraging coextrusion expertise and integrated packaging providers combining dual-chamber bodies with precision dispensing closures. Competitive moves concentrate on capacity expansion for injection stretch blow molding equipment and strategic partnerships for smart closure integration.
Among North American packaging conglomerates, AptarGroup Inc. and Silgan Holdings Inc. occupy positions within the integrated systems tier, exemplifying the convergence of dual-chamber body manufacturing with precision dispensing closure engineering. Plastic Technologies Inc. anchors the barrier specialist archetype, representing deep preform engineering capabilities for complex oxygen transmission specifications. These three entities illustrate the bifurcation between scale-driven integrated providers and technology-focused specialty molders reshaping supplier qualification criteria.
| Leading Market Players |
|---|
| Plastic Technologies Inc. |
| Golchi LLC |
| Duothirst |
| HydraCup |
| BlenderBottle Company |
| SmartShake |
| AptarGroup Inc. |
| Silgan Holdings Inc. |
| Raepak Ltd. |
| Others |
Value Network & Pricing Analysis
Eight-to-fourteen-month equipment lead times for divider-sealing machinery compress capacity expansion timelines and amplify pricing power for certified molders with installed welding assets. This inventory-to-delivery dynamic concentrates procurement leverage among German and Japanese equipment holders while forcing spot buyers toward premium contract tiers.
Pricing Analysis
Cost-plus contracts indexed to crude oil derivatives govern PET and polypropylene resin procurement for standardized formats. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15378-certified pharmaceutical suppliers from commodity beverage molders and unqualified regional players. Price differentiation hinges on barrier-layer complexity and FDA food-contact substance notification status. Pricing pressure stems from polymer feedstock volatility squeezing margins at single-layer PET molders. Nutritional supplement brands show highest price sensitivity, while pharmaceutical packagers prioritize certification compliance over unit cost.
Supply Chain Analysis
Just-in-time resin procurement dominates tier-one molders in Germany and the United States, while Chinese Yangtze River Delta producers maintain strategic stockpiles of EVOH barrier materials to buffer NMPA testing delays. Supply concentrates in Germany, China, and the United States for injection stretch blow molding capacity. Raw material dependencies rest on Saudi and Korean PET resin, German welding equipment, and Japanese precision dispensing components. Single-source vulnerability in divider-sealing machinery creates bottleneck risk. Distribution runs through direct OEM contracts for pharmaceutical and beverage brands, with spot market access limited to cosmetic and consumer goods channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-chamber flexible pouches with spout-fitment designs threaten rigid dual-chamber bottles in nutritional supplement and beverage convenience segments, forcing incumbents to articulate stability and premium positioning defenses.
For Market Incumbents: Compound barrier engineering capabilities through captive EVOH coextrusion capacity or exclusive polymer supplier partnerships. ISO 15378 certification investments lock out regional molders from pharmaceutical contract renewals. Backward integration into preform manufacturing defends margin position against resin volatility and equipment lead-time compression. For New Entrants and Emerging Players: ISO 9001 fast-track certification programs unlock supplier qualification with mid-tier nutritional supplement brands bypassing 24-month incumbent timelines. White-space sits with domestic Chinese pharma brands seeking NMPA-compliant local container sources. Target South Korean cosmetic packagers demanding precision dispensing closure integration for serum-plus-activator formats. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because tightening FDA, REACH, and NMPA documentation requirements continuously filter supplier bases and concentrate share among certified molders. Acquisition targets cluster at barrier-specialist molders with installed welding assets and FCN-submitted resin portfolios. Watch NMPA approval velocity for imported pharmaceutical containers as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Layer Coextrusion Capacity Expansion | EVOH oxygen transmission specifications below 0.5 cc/pkg/day capture nutritional supplement shelf-life premiums. |
| ISO 15378 Certification Investment | Pharmaceutical packaging quality management gates contract eligibility with GMP-compliant buyers in Greater Boston corridor. |
| Smart Closure Integration Partnership | NFC-enabled caps with dual-chamber bodies enable dose-tracking pilots by Japanese cosmetic brands. |
| Non-Fluorinated Barrier Technology Development | EU F-Gas Regulation compliance maintains market access for Bavarian molding clusters. |
| Extended Producer Responsibility Design Alignment | EU packaging waste directive compliance positions suppliers for preferred vendor status under evolving EPR schemes. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA food-contact substance notifications, EU REACH substance registrations, and NMPA packaging guidelines. Interviews with pharmaceutical packaging procurement managers, nutritional supplement brand supply chain directors, blow-molding equipment engineers, and polymer supplier technical sales leads inform demand-side and supply-side dynamics. Secondary validation draws from customs trade data, ISO certification registries, and equipment manufacturer order backlogs. Bottom-up capacity modeling and top-down end-use consumption estimates triangulate market sizing.
Segmentation dimensions modeled include material type, end-user channel, application category, and design feature complexity across the projection horizon. Pharmaceutical titration formats, nutritional supplement powder-plus-liquid designs, and cosmetic serum mixing applications anchor volume and value outputs. CAGRs derive from installed equipment capacity expansion schedules, brand procurement pipeline visibility, and regulatory compliance timeline assumptions. Forecast inputs incorporate polymer price index trajectories and equipment lead-time observations from German and Japanese machinery suppliers.
Underlying assumptions cover stable FDA enforcement patterns for food-contact substances, sustained EU F-Gas Regulation stringency, and incremental NMPA testing protocol harmonization, with deviation risk concentrated in polymer feedstock volatility and equipment delivery delays. Revision becomes warranted when divider-sealing machinery lead times exceed 18 months or when NMPA accelerates domestic substitution mandates for imported pharmaceutical containers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Thin Wall Containers Market
Containers
Light Density Polyethylene (LDPE) Bottles Market
Containers
Square Pails Market
Containers
Lab Storage Container Market
Containers
Durable Insulated Containers Market
Containers
EMEA Container Technology Market
Containers
Americas Container Technology Market
Containers
Snap-Lock Container Market
Containers
Stackable Container Market
Containers
Trays Market
Containers
Pail Lids Market
Containers
Sanitary Cans Market
Containers
Tottle Containers Market
Containers
Foam Hinged Take-Out Containers Market
Containers
Pails Market
Containers
Jug Shipper Market