
 Plastic Canister Market | 2026-2036
Plastic Canister Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Canister Market Outlook
Food-grade certification tiers is rotating toward the center of competitive strategy as buyers reject regrind-heavy formulations. Berry Global leverages captive resin compounding to sustain margin control across North American dairy packaging accounts. Silgan Holdings anchors its position through metal-to-plastic conversion programs for industrial lubricants. Time Technoplast dominates India’s pharmaceutical canister segment with in-house PTFE lining capabilities.
Plastic canisters are blow-molded or injection-molded containers, typically manufactured from high-density polyethylene or polypropylene, with wall thicknesses engineered for chemical resistance and stack-load stability; they serve as primary packaging for solids, powders, and viscous liquids across regulated industries. Round canisters lead volume in food processing applications due to uniform label adhesion and pallet efficiency, while specialty containers command premium positioning in aerospace solvent handling where UN certification is mandatory. Polyethylene grades absorb the highest material share, though polypropylene is displacing PVC in pharmaceutical applications as extractables testing intensifies.
FDA 21 CFR food-contact notifications and EU REACH substance restrictions constrain resin additive portfolios, pushing converters toward virgin-copolymer formulations with documented supply-chain traceability. BIS certification requirements in India and GB standards enforcement through SAMR in China add parallel compliance layers for exporters. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border fulfillment networks.
Market Dynamics
Material purity mandates across FDA 21 CFR and EU REACH are compressing resin additive portfolios, forcing converters toward virgin-copolymer formulations with documented supply-chain traceability. This regulatory tightening is reshaping competitive positioning as food-grade certification tiers rotate toward the center of buyer evaluation.
Growth Catalysts
- Metal-to-plastic conversion programs:Industrial lubricant packagers are abandoning tinplate containers for polyethylene canisters to reduce corrosion risk and transportation weight. Silgan Holdings anchors this transition through dedicated conversion engineering services.
- EU REACH substance restrictions:The tightening of SVHC thresholds is eliminating regrind-heavy formulations from export-qualified production lines, creating premium positioning for converters with captive virgin resin compounding.
- Pharmaceutical extractables testing:Polypropylene is displacing PVC in parenteral packaging as USP Class VI and ISO 10993 biocompatibility protocols intensify material scrutiny across CDSCO-regulated Indian facilities and FDA-inspected US plants.
Market Restraints
- Feedstock volatility:Naphtha-linked polyethylene resin prices swing with crude differentials, compressing converter margins when long-term supply agreements lock in above-spot conversion economics.
- German industrial cluster concentration:Specialized container demand concentrates around Cologne and Hamburg, creating geographic dependency risk for exporters serving pharmaceutical and aerospace solvent accounts.
- UN certification bottlenecks:Dangerous goods packaging approvals for aerospace and chemical applications require 12-18 month testing cycles, freezing product development pipelines for mid-cap converters.
Strategic Opportunities
- Indian pharmaceutical expansion:CDSCO's alignment with ICH Q3D elemental impurity guidelines is opening demand for PTFE-lined canisters in active pharmaceutical ingredient storage, where Time Technoplast holds in-house capability.
- US dairy packaging consolidation:Berry Global's captive resin compounding model demonstrates margin defense potential as FDA food-contact notification requirements tighten across fluid milk and yogurt segments.
- Post-consumer recycled integration:Advanced decontamination technologies enabling food-grade rHDPE incorporation are creating compliance-aligned sustainability positioning for converters ahead of EU Packaging and Packaging Waste Regulation enforcement.
Industry Challenges
- Blow-molding technician scarcity:Precision parison control for thin-wall pharmaceutical canisters requires specialized operator training that outpaces vocational pipeline output in Midwestern US manufacturing zones.
- Multi-jurisdiction certification stacking:Simultaneous pursuit of FDA 21 CFR, EU REACH, BIS IS 9845, and GB 4806 compliance creates documentation burden and stranded inventory risk in cross-border fulfillment networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Canister Market |
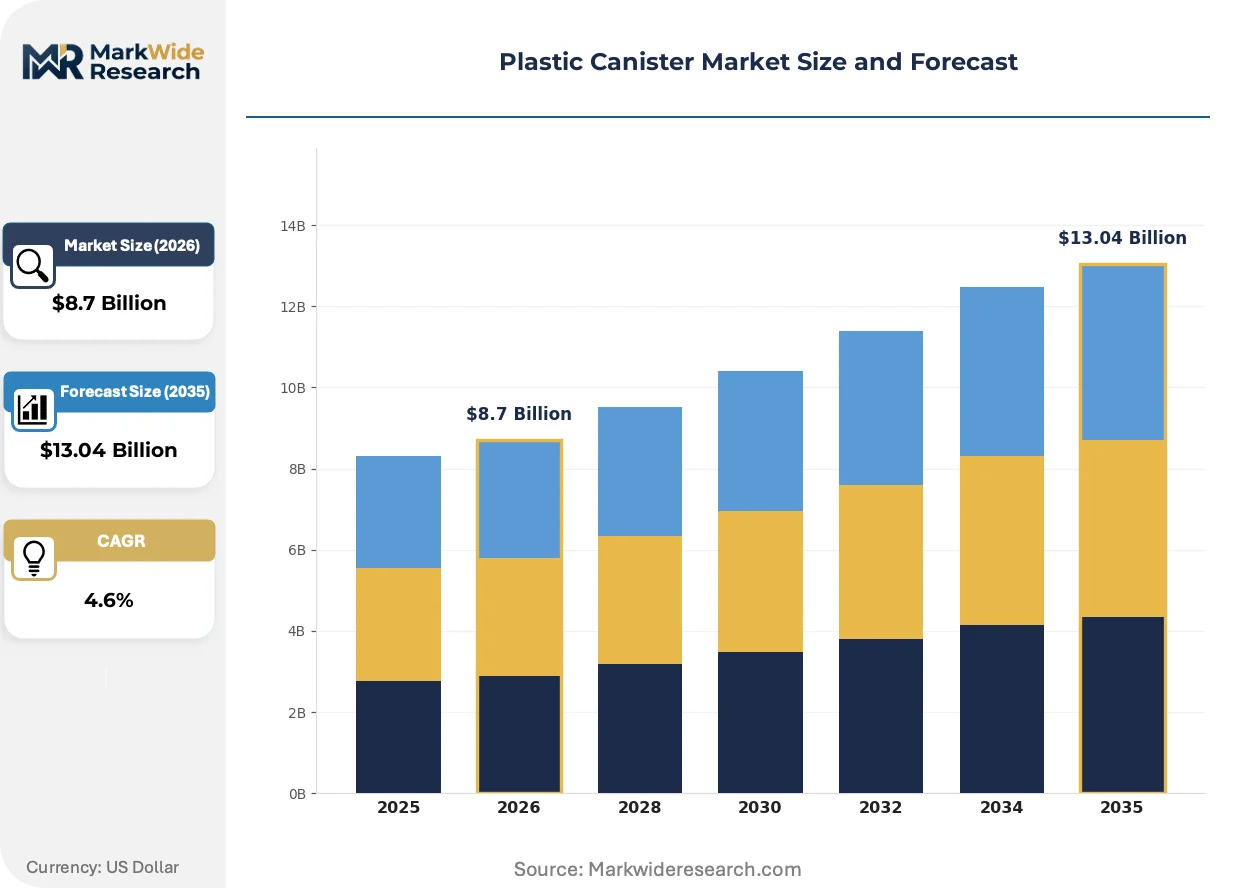
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Canisters, Square Canisters, Cylindrical Canisters, Specialty Container Material: Polyethylene, Polypropylene, PVC, PTFE End User: Aerospace, Food & Beverage, Pharmaceuticals, Industrial Capacity: Small, Medium, Large, Custom Sizes |
| Companies Covered | ALPLA Group, Silgan Holdings, Berry Global, Altium Packaging, Pretium Packaging, Amcor Plc, Graham Packaging Company, Time Technoplast, Plastipak Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Canister Market Strategic Shifts
Active material science advancement and regulatory protocol convergence are compressing development cycles while elevating performance thresholds. Three developments are restructuring competitive capability requirements.
Barrier-enhanced coextrusion technology is displacing monolayer HDPE in oxygen-sensitive food applications. Dairy powder and nutraceutical packagers in Germany and the Netherlands are adopting five-layer EVOH-interrupted structures at accelerated qualification pace. This displacement is compressing addressable volume for conventional blow-molders lacking coextrusion asset bases.
EU REACH Annex XVII restrictions on phthalate plasticizers are eliminating flexible PVC from pharmaceutical closures and gaskets. ECHA's 2023-2024 substance evaluation roadmap is accelerating polypropylene and TPE substitution in parenteral packaging across EMA-regulated manufacturing sites. German converters with documented supply-chain traceability systems are capturing displaced flexible PVC volume.
Direct-to-manufacturer procurement consolidation is eliminating distributor intermediaries in industrial chemical packaging. Large lubricant blenders in Texas and Louisiana are negotiating frame contracts with blow-molders for 24-month supply security with indexed resin pass-through. This channel compression is visible most acutely in US Gulf Coast petrochemical corridors where integrated producers leverage geographic proximity for just-in-time delivery.
Plastic Canister Market Segmentation
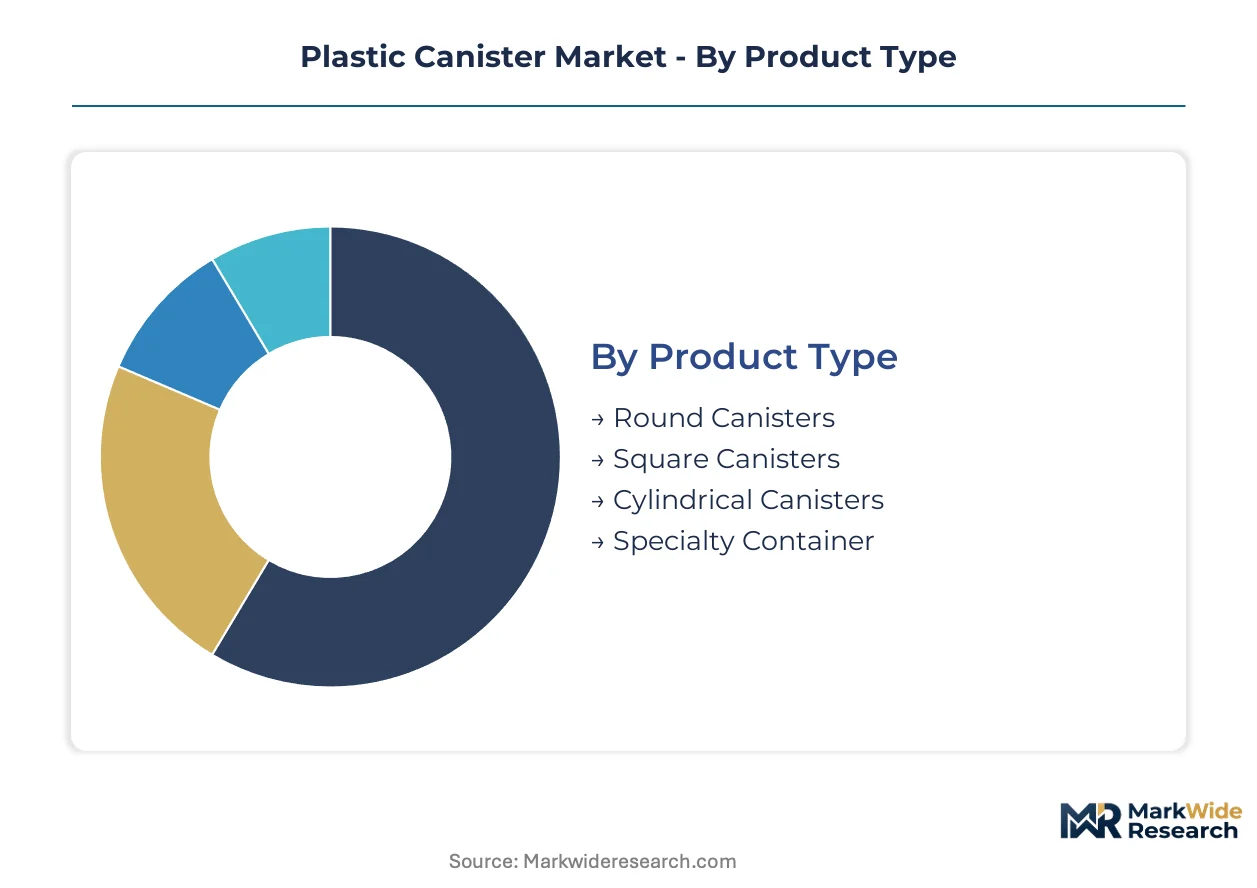
Channel configuration in plastic canister procurement varies sharply across segment boundaries. Industrial lubricant packagers negotiate direct frame contracts with blow-molders, while pharmaceutical buyers route through certified distributors to satisfy multi-jurisdiction documentation requirements.
Product Type:
Round canisters flow through food processing distributors with pallet-optimized logistics, while specialty containers move via engineering-direct channels for UN-certified aerospace applications.
- Round Canisters:Uniform wall thickness enables consistent label adhesion across dairy powder and nutraceutical lines. Demand concentrates in German dairy processing clusters around Cologne, where pallet efficiency drives procurement specifications.
- Specialty Container:Engineered for UN-certified dangerous goods transport with 12-18 month approval cycles. Aerospace solvent handling in Hamburg and Texas Gulf Coast petrochemical corridors absorbs premium-positioned volume.
- Square Canisters:Maximize cubic utilization in warehouse racking systems for industrial chemical storage.
- Cylindrical Canisters:Preferred for viscous liquid dispensing in pharmaceutical compounding operations.
Round canisters dominate installed base. Specialty containers are where expansion concentrates.
Material:
Cost tier stratification separates virgin-copolymer formulations from regrind-heavy alternatives, with regulatory compliance premiums widening spreads between tiers.
- Polyethylene:Blow-molded HDPE grades absorb the highest material share across food and industrial applications. FDA food-contact notification requirements and EU REACH SVHC thresholds are compressing additive portfolios toward documented virgin supply chains.
- Polypropylene:Injection-molded homopolymer and copolymer grades displace PVC in parenteral packaging. USP Class VI and ISO 10993 biocompatibility protocols intensify scrutiny across CDSCO-regulated Indian facilities and FDA-inspected US plants.
- PVC:Flexible formulations face ECHA Annex XVII phthalate restrictions, eliminating closure and gasket applications.
- PTFE:In-house lining capabilities command premium positioning in active pharmaceutical ingredient storage.
Polyethylene holds volume leadership. Polypropylene is climbing the fastest as extractables testing intensifies.
End User:
Customer type determines certification stacking intensity, with pharmaceutical and aerospace accounts demanding parallel FDA, EMA, and BIS documentation.
- Food & Beverage:Dry goods and liquid storage procurement is expanding for polyethylene-based canisters with five-layer EVOH-interrupted coextrusion for oxygen-sensitive applications.
- Pharmaceuticals:Parenteral packaging material scrutiny is intensifying across CDSCO-regulated Indian facilities and FDA-inspected US plants.
- Industrial:Lubricant packagers are abandoning tinplate for polyethylene to reduce corrosion risk and transportation weight.
- Aerospace:Solvent handling mandates UN certification with extended testing cycles freezing mid-cap converter pipelines.
Food & Beverage anchors current volume. Pharmaceuticals is gaining share fastest on regulatory alignment investments.
Capacity:
Volume scale determines blow-molding asset configuration, with small-capacity pharmaceutical lines requiring precision parison control that outpaces technician supply.
- Medium:Standard dairy and industrial chemical formats balance pallet efficiency with manual handling ergonomics.
- Large:Bulk lubricant and solvent containers leverage just-in-time delivery contracts with indexed resin pass-through.
- Small:Pharmaceutical and nutraceutical dosing formats require thin-wall precision that strains Midwestern US vocational pipelines.
- Custom Sizes:Frame-contract industrial accounts specify dimensional tolerances for automated filling line integration.
Medium capacity holds the broadest installed base. Custom sizes are where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Resin compounding capacity clusters in Germany, the United States, India, China, and Brazil, with each jurisdiction layering distinct compliance requirements onto export-bound production. Regulatory divergence across FDA, EU REACH, and national standards is fragmenting supply chain configurations.
Germany
Industrial packaging demand concentrates around Cologne and Hamburg, where pharmaceutical and aerospace solvent accounts drive specialized container orders. ECHA REACH Annex XVII restrictions on phthalate plasticizers are eliminating flexible PVC from closure applications, accelerating polypropylene substitution. Bavaria-based converters with documented supply-chain traceability systems capture displaced volume from reformulation mandates.
United States
Dairy powder and nutraceutical packagers in the Midwest are adopting five-layer EVOH-interrupted coextrusion structures for oxygen-sensitive applications. FDA 21 CFR food-contact notification requirements are compressing additive portfolios toward virgin-copolymer formulations with batch-level documentation. Texas and Louisiana lubricant blenders negotiate direct frame contracts with blow-molders for indexed resin pass-through arrangements.
India
CDSCO alignment with ICH Q3D elemental impurity guidelines is opening demand for PTFE-lined canisters in active pharmaceutical ingredient storage. BIS IS 9845 certification requirements add parallel compliance layers for export-qualified production. Maharashtra-based pharmaceutical manufacturing clusters absorb premium-positioned container volume from domestic and international drug formulators.
China
GB 4806 standards enforcement through SAMR is tightening material purity requirements for food-contact plastics destined for domestic consumption and re-export. Dual carbon policy targets are pressuring converters toward post-consumer recycled integration in non-food applications. Yangtze River Delta blow-molding operations serve both domestic dairy processors and EU-bound specialty chemical accounts.
Brazil
ANVISA pharmaceutical packaging regulations are intensifying extractables testing requirements for parenteral applications, displacing PVC in favor of polypropylene. Industrial lubricant distributors in São Paulo state are converting metal drum inventories to polyethylene canisters for corrosion resistance. Southeast Brazilian chemical corridors leverage Mercosur trade positioning to supply Argentina and Chile with UN-certified dangerous goods containers.
Plastic Canister Market Competitive Environment
Concentration sits with integrated resin compounders and specialized pharmaceutical converters, while mid-cap blow-molders face margin compression from feedstock volatility. The vendor base stratifies across three tiers: captive resin producers with FDA-registered facilities, regional specialists with UN certification capabilities, and commodity converters serving undifferentiated industrial accounts. Dominant competitive moves include backward integration into resin compounding and geographic expansion through distributor acquisition in high-growth pharmaceutical corridors.
Among North American integrated packaging groups, Berry Global and Silgan Holdings exemplify divergent strategic archetypes. Berry Global represents the captive resin compounding model, sustaining margin control through in-house supply chain traceability systems. Silgan Holdings anchors the metal-to-plastic conversion specialist tier, engineering dedicated transition programs for industrial lubricant accounts. Time Technoplast occupies a position within the Asia-Pacific pharmaceutical specialist segment, where in-house PTFE lining capabilities command premium positioning. These three entities illustrate how regulatory compliance investments and material science capabilities are separating premium-tier converters from commodity competitors.
| Leading Market Players |
|---|
| ALPLA Group |
| Silgan Holdings |
| Berry Global |
| Altium Packaging |
| Pretium Packaging |
| Amcor Plc |
| Graham Packaging Company |
| Time Technoplast |
| Plastipak Holdings |
| Others |
Value Chain & Pricing Dynamics
Metal-to-plastic conversion in industrial lubricant packaging is redrawing procurement geography and compressing pricing power for tinplate suppliers while opening margin expansion corridors for polyethylene converters with captive resin capabilities.
Pricing Analysis
FDA 21 CFR food-contact notification requirements dictate the pricing tier structure across dairy and nutraceutical applications. Three-tier pricing separates virgin-copolymer formulations with batch-level documentation from regrind-heavy alternatives and commodity industrial grades. Cost compression in standard polyethylene canisters is intensifying because naphtha-linked resin prices swing with crude differentials. Food-grade certification tiers face the lowest price sensitivity, while undifferentiated industrial accounts negotiate aggressively on volume.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for converters dependent on imported resin additives. Supply concentrates in Germany, the United States, and India, with each jurisdiction layering distinct compliance requirements onto export-bound production. Raw material portfolios draw from high-density polyethylene grades, polypropylene homopolymers, and specialized PTFE lining compounds. Single-source vulnerability sits with German industrial clusters around Cologne and Hamburg, where pharmaceutical and aerospace solvent demand concentrates. Distribution runs through direct frame contracts for lubricant accounts and certified distributors for pharmaceutical buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where FDA and EU REACH compliance investments create switching costs that entrench established converters against commodity entrants.
For Market Incumbents: Shield market position by deepening backward integration into resin compounding to offset feedstock volatility, and expand UN certification capabilities to capture aerospace solvent demand frozen in 12-18 month approval pipelines. Priority investments should target five-layer EVOH coextrusion assets as barrier-enhanced structures displace monolayer HDPE in oxygen-sensitive food applications. For New Entrants and Emerging Players: CDSCO alignment with ICH Q3D guidelines offers a certification fast-track into Indian pharmaceutical canister demand, where PTFE-lined active pharmaceutical ingredient storage commands premium positioning. White-space opportunity concentrates in post-consumer recycled integration for EU Packaging and Packaging Waste Regulation compliance, and in precision parison control for small-capacity pharmaceutical formats where Midwestern US technician scarcity constrains incumbent expansion. Go-to-market execution should anchor on just-in-time delivery contracts with indexed resin pass-through for Gulf Coast petrochemical accounts. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors converters with documented supply-chain traceability systems and captive virgin resin capabilities. Long-term viability over a multi-year horizon rests on regulatory entrenchment rather than volume scale alone. Acquisition targets should display parallel FDA, EU REACH, and BIS certification stacks with minimal stranded inventory exposure. The signal to watch is EU REACH Annex XVII expansion to additional substance categories, which would accelerate displacement of flexible PVC and regrade-heavy formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Berry Global's captive supply model demonstrates margin defense against naphtha price volatility. |
| UN Certification Capability Buildout | Silgan Holdings anchors metal-to-plastic conversion programs through dedicated engineering services. |
| Five-Layer EVOH Coextrusion Investment | German dairy processors adopt barrier-enhanced structures for oxygen-sensitive powder applications. |
| PTFE Lining Technology Acquisition | Time Technoplast dominates Indian pharmaceutical storage through in-house lining capabilities. |
| Post-Consumer Recycled Integration | Advanced decontamination technologies enable food-grade rHDPE ahead of EU Packaging Regulation enforcement. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with blow-molding plant managers, pharmaceutical procurement leads, dairy packaging engineers, and industrial lubricant distributors; and secondary validation through FDA 21 CFR food-contact notification databases, ECHA REACH substance restriction filings, CDSCO regulatory circulars, and customs trade data for polyethylene resin flows. Bottom-up capacity modeling across German, US, and Indian production clusters was triangulated against top-down demand aggregation by end-use segment.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product type, material grade tier, end-use industry, and regional regulatory cluster. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers. Industry-specific forecast inputs included pharmaceutical extractables testing intensity, metal-to-plastic conversion program adoption curves, and UN certification pipeline clearance rates.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA and EU REACH regulatory tightening; material deviation through regulatory harmonization or feedstock price collapse would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
North America Blow Molded Plastics Market
Plastic Packaging
Russia Plastic Packaging Market
Plastic Packaging
Global Returnable Plastic Crates Market
Plastic Packaging
PET Clamshell Market
Plastic Packaging
Disposable Straw Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market
Plastic Packaging
Canada Plastic Packaging Market
Plastic Packaging
Japan Plastic Bottles Market
Plastic Packaging
Blow Molded Bottles Market
Plastic Packaging
CPET Trays Market
Plastic Packaging
Middle East and Africa Plastic Bottles Market
Plastic Packaging
Asia Pacific Plastic Packaging Market
Plastic Packaging
Plastic Vials Market
Plastic Packaging
E-Commerce Plastic Packaging Market
Plastic Packaging
Australia and New Zealand Plastic Bottles Market
Plastic Packaging
Compostable Plastic Packaging Material Market