
 Strap Dispenser Market | 2026-2036
Strap Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Strap Dispenser Market Analytics
Automation integration in packaging lines is narrowing the performance gap between manual and automatic strapping workflows. Signode Industrial Group LLC leverages its steel and plastic strapping ecosystem to sustain captive demand for companion dispensers. Mosca GmbH anchors European market share through precision-engineered automatic dispensers with servo-controlled tensioning. Fromm Packaging Systems Inc. competes across pneumatic and electric technology tiers with modular dispenser architectures.
A strap dispenser is a material handling device that feeds, tensions, and cuts plastic or steel strapping from a wound coil, typically accommodating strap widths from 9 mm to 32 mm and coil weights up to 85 kg for industrial models. The unit integrates with arch-type strapping machines or operates as a standalone workstation for pallet securing and carton closing in logistics hubs. Automatic dispensers lead unit volume in high-throughput manufacturing plants where cycle time dictates equipment selection, while manual dispensers retain margin pools in small-batch retail and specialty packaging applications. E-commerce end users represent the fastest-growing demand segment as same-day fulfillment requirements compress packing station dwell times.
FDA facility standards for pharmaceutical packaging cleanliness and OSHA machine guarding requirements shape dispenser design specifications in the United States, while EU machinery directives and CE marking enforce interlock and emergency-stop compliance across European deployments. The EU Green Deal's packaging waste reduction targets indirectly stimulate dispenser demand by accelerating reusable strapping adoption over single-use alternatives. Stakeholders must monitor how digital tension-control technology and predictive maintenance interfaces redefine equipment replacement cycles and aftermarket service revenue models.
Market Dynamics
Automated packaging line integration is compressing dwell times at fulfillment workstations, forcing dispenser architectures to synchronize with upstream carton erectors and downstream palletizers through unified control protocols.
Growth Catalysts
- E-commerce fulfillment velocity:Same-day delivery mandates from major retailers are eliminating manual strapping stations in favor of automatic dispensers with sub-three-second cycle times.
- OSHA machine guarding standards:Workplace safety inspections in US distribution centers are accelerating replacement of unguarded legacy dispensers with interlock-equipped models.
- Steel coil weight standardization:European logistics hubs are consolidating procurement around 85 kg maximum coil specifications, streamlining dispenser compatibility across multi-site operations.
Market Restraints
- Polypropylene resin price volatility:Strap material input costs fluctuate with crude oil indices, squeezing margin stability for dispenser operators in price-sensitive segments.
- German manufacturing cluster concentration:Precision servo-drive components for automatic tensioning systems source predominantly from Baden-Württemberg suppliers, creating geographic supply risk.
- Steel strap corrosion limitations:High-humidity pharmaceutical and food processing environments restrict steel strapping adoption, capping dispenser deployment in regulated cleanroom applications.
Strategic Opportunities
- India logistics infrastructure expansion:Cold chain modernization under the PLI scheme is creating first-mover advantage for stainless-steel dispenser suppliers targeting pharmaceutical distribution.
- Predictive maintenance interface convergence:Integration of IoT tension sensors with cloud-based analytics platforms is enabling subscription service revenue models alongside equipment sales.
- EU Green Deal packaging waste targets:Reusable strapping mandates are stimulating demand for heavy-duty dispensers compatible with return-loop logistics systems.
Industry Challenges
- Mechatronics technician scarcity:Servo-controlled automatic dispensers require specialized calibration expertise that outpaces vocational training program output in mature manufacturing economies.
- Legacy PLC integration complexity:Brownfield packaging lines running proprietary Allen-Bradley or Siemens protocols demand costly middleware development for dispenser connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strap Dispenser Market |
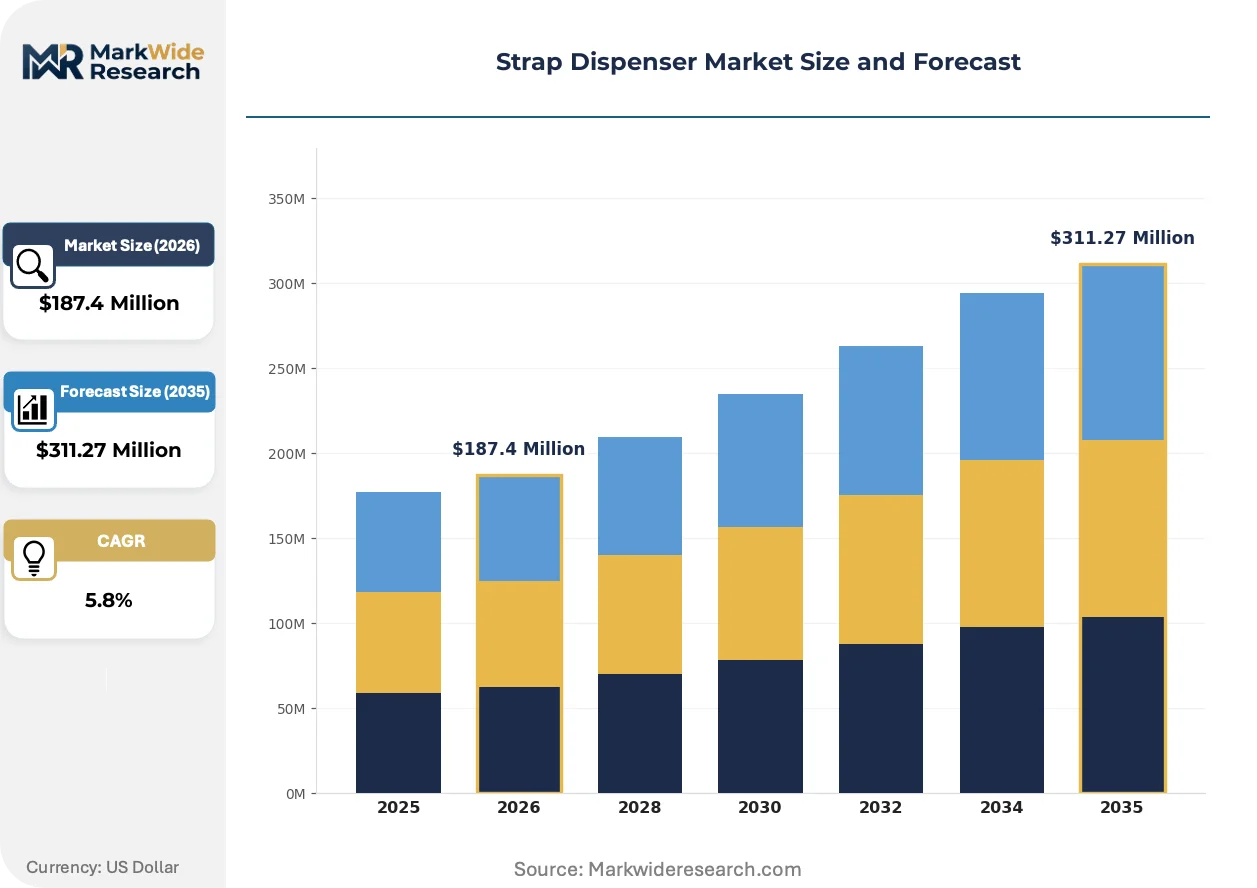
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Dispensers, Automatic Dispensers, Semi-Automatic Dispensers, Electric Dispensers Application: Packaging, Shipping, Manufacturing, Retail End User: Logistics Companies, Manufacturing Plants, Retailers, E-commerce Technology: Mechanical, Pneumatic, Hydraulic, Digital |
| Companies Covered | Signode Industrial Group LLC, Cyklop International, Mosca GmbH, Fromm Packaging Systems Inc., StraPack Corp., Dynaric Inc., Polychem Corporation, Samuel Strapping Systems, Strapex Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strap Dispenser Market Evolving Landscape
Digital thread technologies are redefining how tension control data flows from coil to cloud, compressing maintenance response windows and reshaping aftermarket service economics across installed bases.
Servo-electric tensioning systems are virtualizing the mechanical clutch and brake assemblies that historically dominated automatic dispenser architectures. Pharmaceutical contract packagers in Switzerland and Germany are adopting these platforms fastest, driven by FDA and Swissmedic validation requirements for repeatable strap tension documentation. The technology is virtualizing maintenance schedules by enabling remote diagnostics that anticipate component degradation before field failure.
EU machinery directives and CE marking requirements for emergency-stop functionality and two-hand interlock systems are mandating control system redesigns for dispensers deployed in European manufacturing plants. Industrial consequence includes accelerated obsolescence of pneumatic-only tensioning platforms lacking electronic safety integration. Automatic dispenser product lines serving automotive and appliance manufacturing in Germany, Italy, and Poland are responding with integrated safety PLC modules that streamline third-party conformity assessment.
Buyer consolidation among third-party logistics operators is compressing equipment specification diversity toward standardized dispenser platforms. Regional 3PL networks in the Netherlands and Belgium are consolidating procurement around single-vendor automatic dispenser fleets to simplify spare parts inventory and technician cross-training. Food and beverage contract packaging in the Benelux region exhibits this pattern most visibly, with multi-site operators demanding identical dispenser configurations across facilities to enable labor mobility and reduce downtime risk.
Strap Dispenser Market Segmentation
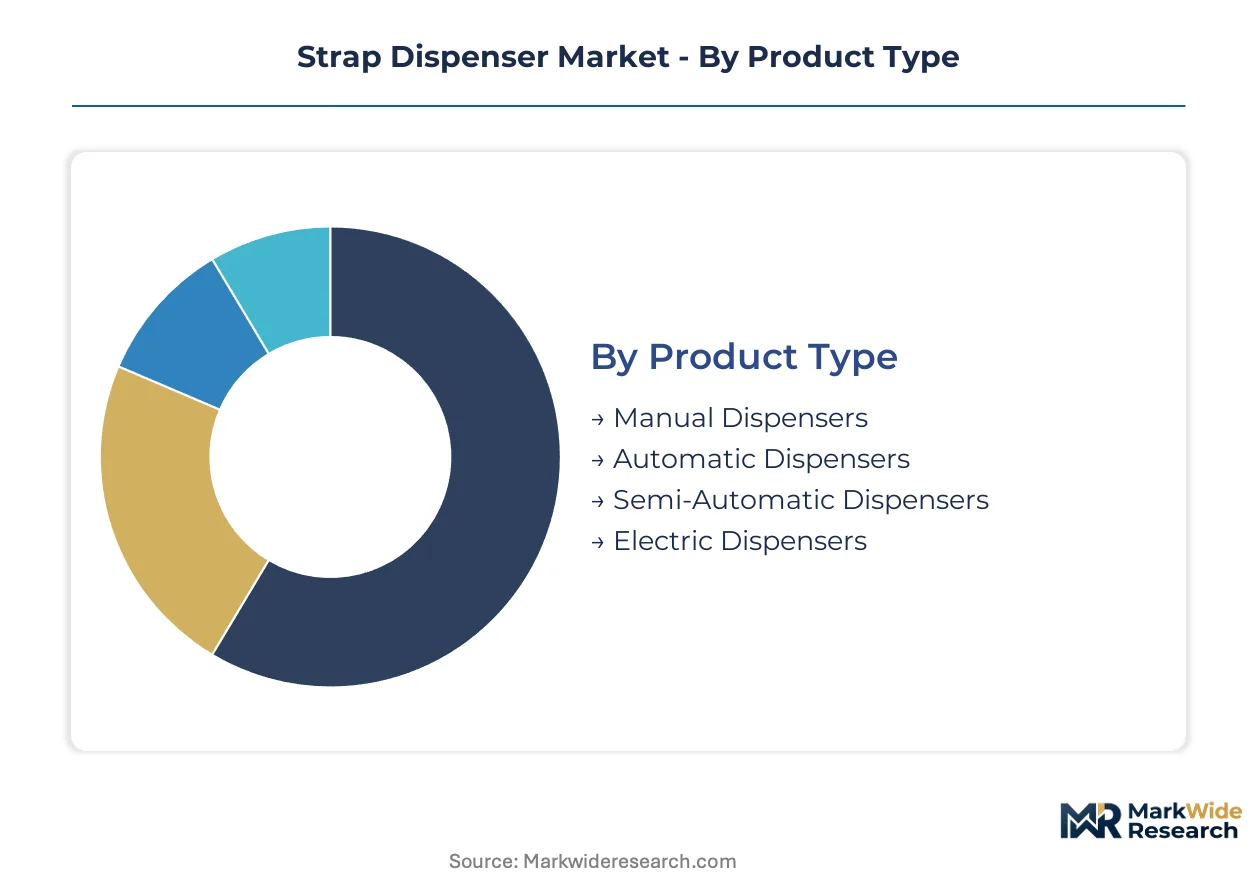
Strap dispenser procurement patterns diverge sharply across operational environments. Cycle-time requirements, labor cost structures, and integration complexity create distinct preference clusters that shape vendor product roadmaps and distribution channel investments.
Product Type:
Automatic dispensers turn over fastest in high-velocity fulfillment networks where sub-three-second cycle mandates dominate capital planning. Manual units rotate slowly through small-batch retail and specialty packaging operations with irregular throughput patterns.
- Manual Dispensers:Portable floor-standing or cart-mounted units feed strap from coils up to 50 kg without powered tensioning. Retail packaging stations in Germany and France retain these for low-volume carton sealing where capital constraints outweigh speed requirements.
- Automatic Dispensers:Servo-electric architectures synchronize with upstream carton erectors through unified control protocols. E-commerce fulfillment centers in the United States and Netherlands deploy these for same-day delivery compliance, with OSHA machine guarding standards accelerating replacement of unguarded legacy models.
- Semi-Automatic Dispensers:Pneumatic or electric tensioning with operator-initiated cycle start. Mid-tier manufacturing plants in Italy and Poland favor these for mixed-SKU pallet securing where full automation cannot be justified.
- Electric Dispensers:Battery-powered mobile units for warehouse floor flexibility. Cold chain logistics operators in India under the PLI scheme are adopting stainless-steel variants for pharmaceutical distribution.
Automatic dispensers dominate installed base in high-throughput manufacturing plants. Electric dispensers are where expansion concentrates for mobile warehouse applications.
Application:
Cost tier stratification separates capital-intensive packaging line integration from low-friction shipping floor deployment. Manufacturing applications command premium pricing for precision tension documentation.
- Packaging:Integration with arch-type strapping machines for carton closing and pallet unitizing. Pharmaceutical contract packagers in Switzerland demand servo-electric tensioning with FDA-validated repeatability documentation.
- Shipping:Standalone workstation deployment for outbound freight consolidation. Third-party logistics networks in Belgium and the Netherlands standardize on single-vendor automatic fleets to simplify spare parts inventory.
- Manufacturing:Inline feeding for appliance and automotive production lines. German automotive plants specify integrated safety PLC modules to satisfy EU machinery directive conformity assessment.
- Retail:Back-of-store carton sealing and promotional display preparation. Small-format retailers in France retain manual dispensers for intermittent use patterns.
Packaging commands the deepest technology integration. Shipping is where standardization pressure concentrates among consolidated 3PL buyers.
End User:
Customer type determines specification complexity and aftermarket service attach rates. Logistics operators prioritize fleet commonality; manufacturers demand predictive maintenance interfaces.
- Logistics Companies:Multi-site operators in the Benelux region demand identical dispenser configurations across facilities to enable labor mobility and reduce downtime risk.
- Manufacturing Plants:Brownfield packaging lines running proprietary Allen-Bradley or Siemens protocols require costly middleware development for dispenser connectivity.
- Retailers:Store-level procurement favors portable manual units with minimal training requirements for seasonal workforce turnover.
- E-commerce:Same-day fulfillment mandates from major retailers are eliminating manual strapping stations in favor of automatic dispensers with sub-three-second cycle times.
Manufacturing plants dominate precision-engineered installed base. E-commerce is where steepest expansion trajectory concentrates as fulfillment velocity requirements intensify.
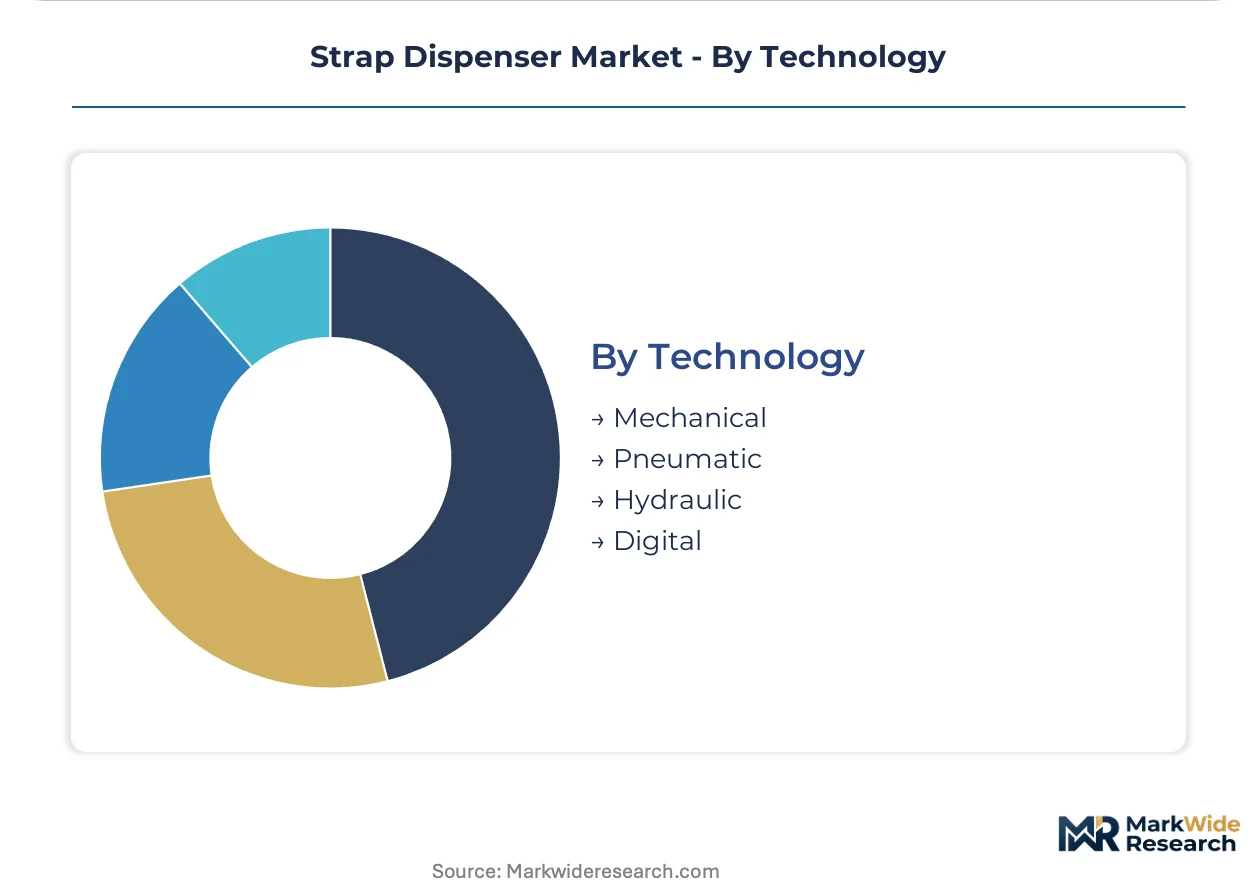
Technology:
Maturity curves separate legacy pneumatic platforms from digitally integrated architectures. Margin pools concentrate where predictive maintenance interfaces enable subscription revenue models.
- Mechanical:Clutch and brake tensioning assemblies with fixed force settings. Legacy installations in mature European manufacturing economies face technician scarcity for specialized calibration.
- Pneumatic:Air-cylinder actuation for mid-speed applications. EU machinery directives are accelerating obsolescence of pneumatic-only platforms lacking electronic safety integration.
- Hydraulic:High-force tensioning for steel strapping in heavy industrial applications. High-humidity pharmaceutical and food processing environments restrict deployment due to corrosion limitations.
- Digital:IoT tension sensors with cloud-based analytics platforms. Pharmaceutical contract packagers in Germany and Switzerland adopt these fastest for remote diagnostics anticipating component degradation.
Mechanical and pneumatic platforms dominate legacy installed base. Digital technology is where vendor R&D investment and aftermarket service revenue expansion concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering exports anchor European dispenser supply chains, while e-commerce fulfillment networks in the United States and Netherlands absorb the highest unit volumes for automatic architectures.
United States
OSHA machine guarding inspections accelerate replacement cycles for legacy unguarded dispensers in distribution centers. FDA facility standards for pharmaceutical packaging cleanliness shape stainless-steel specifications in contract manufacturing. Chicago and Memphis logistics clusters standardize on automatic dispensers with sub-three-second cycle times for same-day delivery compliance.
Germany
EU machinery directives and CE marking requirements enforce emergency-stop functionality and two-hand interlock systems across manufacturing deployments. Baden-Württemberg suppliers concentrate precision servo-drive components for automatic tensioning systems. Stuttgart and Munich automotive plants specify integrated safety PLC modules to satisfy conformity assessment protocols.
Netherlands
Third-party logistics operator consolidation compresses equipment specification diversity toward standardized automatic dispenser fleets. Rotterdam and Venlo distribution hubs demand identical configurations across multi-site operations to enable labor mobility. EU Green Deal packaging waste targets stimulate demand for heavy-duty dispensers compatible with reusable strapping return-loop systems.
India
Cold chain modernization under the PLI scheme creates first-mover opportunities for stainless-steel dispenser suppliers targeting pharmaceutical distribution. BIS standards and CDSCO regulations govern equipment validation in temperature-controlled logistics. Mumbai and Hyderabad logistics corridors adopt battery-powered mobile electric dispensers for warehouse floor flexibility.
Switzerland
Swissmedic validation requirements drive adoption of servo-electric tensioning with repeatable strap tension documentation in pharmaceutical contract packaging. Precision engineering clusters around Basel and Zurich integrate digital thread technologies for predictive maintenance interfaces. ISO standards and national quality protocols exceed baseline EU requirements for equipment certification.
Strap Dispenser Market Competitive Landscape
On the supply side, the industry is structured around precision-engineered automatic systems and modular portable architectures serving distinct operational environments. Three strategic archetypes dominate: integrated packaging system vendors with captive strapping ecosystems, specialized dispenser-only manufacturers with regional service networks, and diversified industrial equipment conglomerates with cross-selling capabilities. Competitive moves concentrate on geographic expansion through distribution partnerships and technology licensing agreements for servo-control integration.
Among German precision engineering specialists, Mosca GmbH and Fromm Packaging Systems Inc. exemplify the integrated-systems archetype through their positioning alongside advanced manufacturing clusters. Signode Industrial Group LLC anchors the diversified-industrial tier with its steel and plastic strapping ecosystem generating companion dispenser demand. These three entities represent the dominant competitive positioning vectors: precision servo-control specialization, modular architecture flexibility, and vertically integrated material-handling portfolios.
| Leading Market Players |
|---|
| Signode Industrial Group LLC |
| Cyklop International |
| Mosca GmbH |
| Fromm Packaging Systems Inc. |
| StraPack Corp. |
| Dynaric Inc. |
| Polychem Corporation |
| Samuel Strapping Systems |
| Strapex Group |
| Others |
Value Network & Pricing Analysis
Overcapacity in pneumatic dispenser manufacturing across Northern Italy is compressing margins for mid-tier suppliers while concentrating pricing power with German servo-drive specialists. This utilization asymmetry forces procurement managers to choose between discounted legacy platforms and premium digital architectures with diverging total-cost-of-ownership profiles.
Pricing Analysis
Current-generation servo-electric dispensers command substantial premiums over prior-generation pneumatic units and emerging next-gen digital-native platforms. Three-tier pricing structure across premium servo systems, standard pneumatic models, and economy mechanical units stratifies the market by certification tier and after-sales service bundling. Pricing pressure stems from polypropylene resin volatility squeezing margin stability in price-sensitive segments. Small-batch retail operations exhibit highest price sensitivity, while pharmaceutical contract packagers prioritize FDA-validated repeatability over unit cost.
Supply Chain Analysis
Contract manufacturing for electronic control modules concentrates with EMS providers in Taiwan and South Korea, while precision mechanical fabrication remains anchored in Baden-Württemberg and Northern Italy. Servo-drive components draw from German automotive supplier networks, steel coils source predominantly from domestic European mills, and battery cells for mobile electric units hinge on South Korean chemistry suppliers. Single-source vulnerability around precision servo motors from Stuttgart-area specialists creates geographic concentration risk. Distribution runs through authorized dealer networks with regional service technicians, supplemented by direct procurement for large 3PL fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance subscription attach rates are expanding faster than hardware unit sales as cloud-based tension analytics reshape vendor economics. This service-layer acceleration repositions dispenser procurement from capital expenditure to operational technology budgets with recurring SaaS components.
For Market Incumbents: Insulate installed-base profitability by deepening aftermarket service penetration through IoT-enabled remote diagnostics. Convert legacy pneumatic customers to servo-electric platforms before EU machinery directive deadlines accelerate obsolescence. Prioritize certification investment for FDA-validated pharmaceutical applications where switching costs anchor multi-year contracts. For New Entrants and Emerging Players: Pursue white-space opportunities in India's cold chain logistics corridors where PLI scheme infrastructure spending outpaces established vendor presence. Target stainless-steel electric dispenser deployment for pharmaceutical distribution in Mumbai and Hyderabad. Differentiate through battery-powered mobility architectures optimized for warehouse floor flexibility rather than competing on established automatic line integration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with predictive maintenance platforms and multi-site 3PL fleet contracts. Long-term viability favors acquisition targets combining digital thread capabilities with established pharmaceutical validation credentials. Monitor servo-drive component lead times from Baden-Württemberg suppliers as an inflection indicator for supply-constrained pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Cloud-based tension analytics from IoT sensors enable subscription revenue alongside equipment sales. |
| Servo-Electric Architecture Migration | EU machinery directives and CE marking accelerate obsolescence of pneumatic-only safety platforms. |
| Pharmaceutical Validation Investment | FDA and Swissmedic repeatability documentation requirements anchor high-margin contract packaging demand. |
| India Cold Chain Market Entry | PLI scheme infrastructure expansion creates first-mover advantage for stainless-steel dispenser suppliers. |
| 3PL Fleet Standardization Partnership | Benelux logistics consolidation demands identical configurations across multi-site operations for labor mobility. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads; and secondary validation through customs trade data, SEC machinery filings, EU machinery directive compliance databases, and packaging equipment association reports. Bottom-up unit deployment estimates triangulated against top-down capital expenditure patterns across e-commerce fulfillment networks.
Forecast inputs considered product type segmentation across manual, semi-automatic, and automatic architectures; application splits between packaging line integration and standalone shipping deployment; and technology tiers from mechanical through digital IoT-enabled platforms. CAGRs derived from modeled replacement cycles, e-commerce fulfillment velocity expansion, and regulatory compliance deadlines across the projection horizon. Industry-specific inputs incorporated OSHA inspection frequency data and EU Green Deal packaging waste target implementation timelines.
Sensitivities concentrate around polypropylene resin price volatility, servo-drive component availability from German suppliers, and e-commerce fulfillment network capital allocation shifts. Forecasts reflect assumptions about regulatory enforcement consistency and technology substitution rates without guarantee of realization. Quarterly review of OSHA citation patterns, EU machinery directive amendment proposals, and 3PL fleet standardization announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Refrigerated Display Cases Market
Packaging Equipment
Diaper Packaging Machines Market
Packaging Equipment
Shrink Wrapper Market
Packaging Equipment
Multihead Weighers Market
Packaging Equipment
Inflatable Void Fill System Market
Packaging Equipment
Blow Molding Tools Market
Packaging Equipment
Flexible End-Load Cartoner Market
Packaging Equipment
Industrial Heat Sealers Market
Packaging Equipment
Burnisher Market
Packaging Equipment
Plastic Waste Sorting Equipment Market
Packaging Equipment
Cannabis Packaging Equipment Market
Packaging Equipment
Tray Loader Market
Packaging Equipment
Loading Spout Market
Packaging Equipment
Global Shrink Sleeve Applicator Market
Packaging Equipment
Bespoke Dispenser Market
Packaging Equipment
Retail Press Dispenser Pump Market