
 2 Piece Cans Market | 2026-2036
2 Piece Cans Market Size, Share, and Industry Trends Forecast 2026-2036
2 Piece Cans Market Outlook
Can tooling engineer availability is bifurcating the competitive landscape, as shallow labor pools constrain new line commissioning while established producers scale output. Ball Corporation leverages backward integration into aluminum sheet production to secure input cost stability across North American beverage contracts. Crown Holdings anchors its position through geographic dominance in European tinplate food packaging, where technical specifications for corrosion resistance remain stringent. Ardagh Group differentiates via R&D intensity in lightweighting technology, competing for contracts with premium sparkling water brands that demand thinner-wall aluminum solutions.
Two-piece cans are cylindrical metal containers formed from a single piece of body metal with a separately attached end, typically manufactured through draw-and-iron or draw-and-redraw processes producing wall thicknesses of 0.10 mm or below for aluminum variants, primarily serving the hermetic preservation and shelf-stable distribution of carbonated beverages, processed foods, and aerosol products. Aluminum product types lead volume due to infinite recyclability and lower transport costs, though tinplate sustains share in acidic food segments where material inertness protects flavor profiles. Food & Beverages applications command the largest revenue pool, while Personal Care represents a faster-growing niche driven by aerosol deodorant and dry shampoo formulations in 100 ml and 250 ml sizes.
The EPA oversees volatile organic compound emissions from can coating operations in the United States, while REACH and the EU Green Deal mandate recycled content thresholds and restrict certain epoxy-based lining chemistries across European supply chains. Brazil's ANVISA imposes sanitary registration requirements on food-contact metal packaging that shape import access rules for foreign producers. Stakeholders must monitor evolving extended producer responsibility frameworks and lining material substitutions that could alter capital allocation between aluminum and tinplate substrate investments.
Market Dynamics
Aluminum sheet cost volatility and EU Green Deal circularity mandates are compressing margins while forcing substrate substitution decisions across beverage and food packaging supply chains.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon propellants accelerates migration to compressed gas aerosol systems in 100 ml and 250 ml personal care formats, expanding two-piece aluminum demand for valve-crimped containers.
- Brazil:ANVISA sanitary registration requirements for food-contact metal packaging create localized production incentives that concentrate Latin American capacity expansion around São Paulo industrial corridors.
- Draw-and-iron process refinement:Wall thickness reduction below 0.10 mm in aluminum beverage cans cuts transport costs per unit and unlocks shelf-stable distribution for ready-to-drink cocktail brands.
Market Restraints
- Primary aluminum ingot price volatility:London Metal Exchange pricing swings directly transmit to can sheet conversion costs, compressing converter margins during energy-intensive smelting disruptions.
- Tinplate supply concentration:European steel mill consolidation leaves food can producers with limited alternative sources for corrosion-resistant tin-coated substrate specified in acidic vegetable and tomato formulations.
- Epoxy-based lining chemistry restrictions:REACH substance evaluations and EU Green Deal substance restrictions constrain bisphenol-A derived coating options, forcing reformulation timelines that delay new product launches.
Strategic Opportunities
- Ready-to-drink cocktails:Premium spirits brands are specifying thinner-wall aluminum solutions for 250 ml and 355 ml formats, creating white space for lightweighting technology suppliers outside traditional beer contracts.
- Extended producer responsibility frameworks:Deposit-return scheme expansion across German and Nordic markets generates guaranteed aluminum scrap flows that reduce recycled content certification costs for compliant producers.
- Aerosol dry shampoo:Personal care brands are adopting 100 ml aluminum cans for travel-format powder formulations, opening faster-growing niche demand outside saturated deodorant segments.
Industry Challenges
- Can tooling engineer scarcity:Shallow labor pools for draw-and-iron line commissioning constrain new capacity ramp rates while established producers accelerate output expansion.
- Coating operation VOC compliance:EPA emission limits for volatile organic compound releases from can lining applications require capital-intensive thermal oxidizer installations at US manufacturing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2 Piece Cans Market |
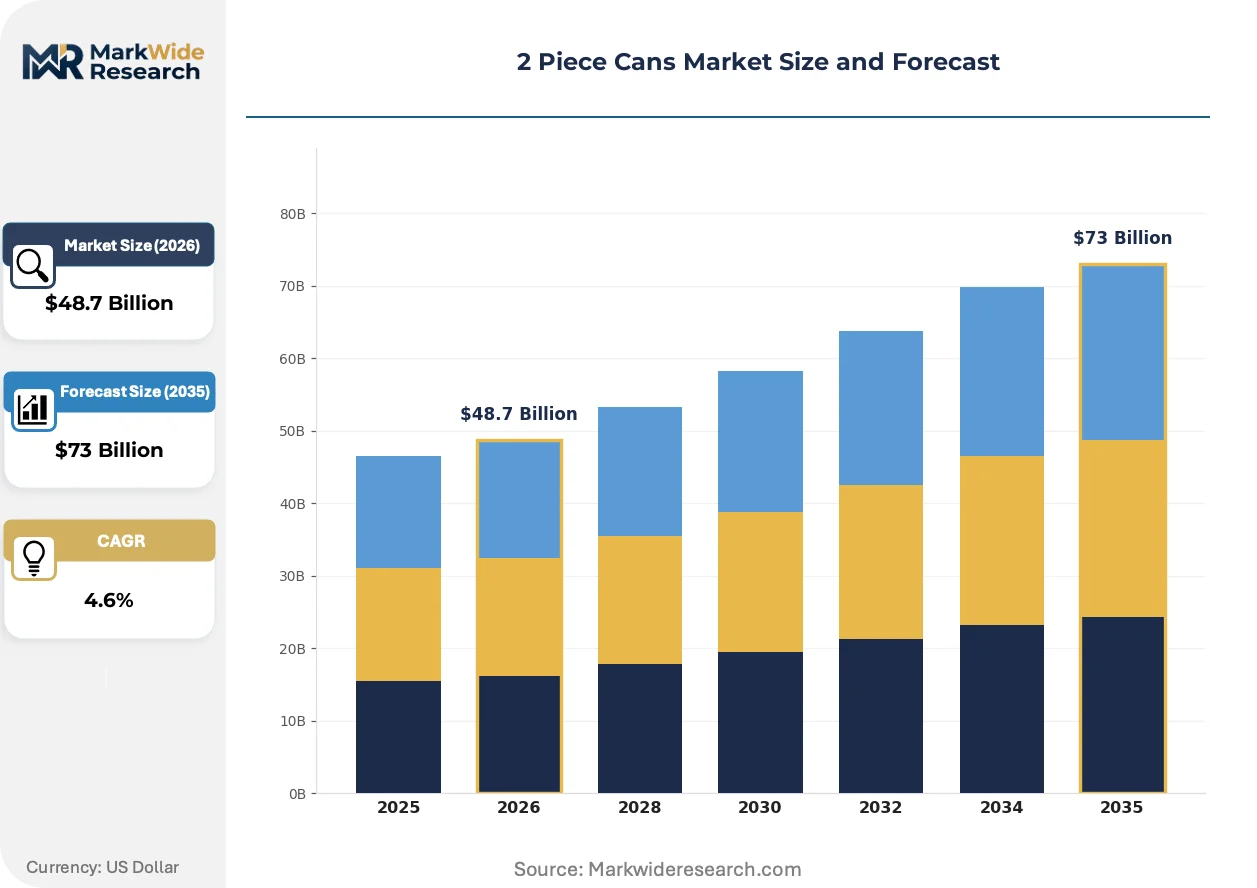
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $73 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Tinplate, Steel, Biodegradable Application: Food & Beverages, Personal Care, Chemical, Household Products Size: 100ml, 250ml, 500ml, 1L End User: Food Manufacturers, Beverage Companies, Retailers, Distributors |
| Companies Covered | Ball Corporation, Crown Holdings, Ardagh Group, Silgan Containers, Can-Pack Group, CPMC Holdings, Toyo Seikan, Envases Group, CCL Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2 Piece Cans Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are simultaneously enabling thinner-wall structures while forcing coating system replacements across aluminum and tinplate substrate categories.
Digital printing on aluminum can exteriors is bifurcating decoration economics, allowing beverage brands to execute short-run seasonal designs without lithographic cylinder changeover delays. Premium sparkling water and craft cocktail producers are adopting this capability for regional market testing. The technology is compressing minimum order quantities and enabling geographic micro-segmentation previously uneconomical at rotary press scale.
REACH substance restrictions and EU Green Deal lining material mandates are forcing epoxy-phenolic coating substitutions across European food can supply chains. Reformulation investments now precede capacity decisions, with converters screening polyester and acrylic alternatives for sulfur-staining resistance in protein-rich foods. Acidic vegetable segments face the tightest compliance timelines, driving qualification partnerships between coating chemical suppliers and steel substrate producers.
Direct-to-retail procurement consolidation among beverage multinationals is compressing supplier negotiation cycles and unbundling technical service from unit pricing. North American carbonated soft drink bottlers now centralize aluminum can sourcing through single-converter frameworks, displacing regional distributor intermediaries. Brazil and Mexico exhibit the most advanced buyer concentration, with multinational beverage headquarters mandating continental contract structures that override local procurement autonomy.
2 Piece Cans Market Segmentation
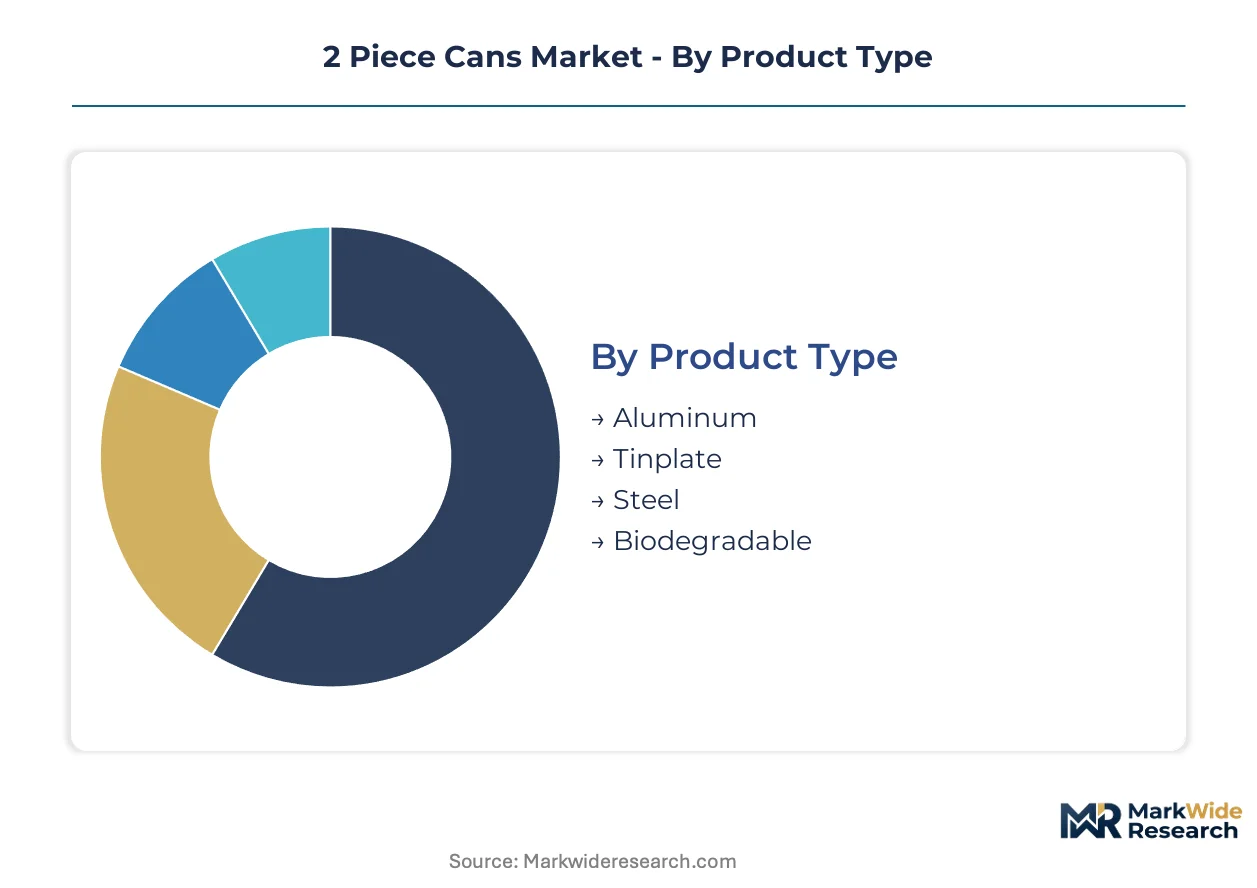
Two-piece can segmentation reveals how substrate chemistry, filling specifications, and distribution channel requirements fragment procurement decisions across beverage, food, and aerosol supply chains. Regulatory thresholds on recycled content and lining material safety create divergent compliance burdens that reshape segment economics.
Product Type:
REACH substance evaluations and EU Green Deal mandates on epoxy-phenolic coatings force divergent reformulation timelines across metallic and emerging substrate categories.
- Aluminum:Draw-and-iron processing achieves wall thickness below 0.10 mm for carbonated beverage and ready-to-drink cocktail applications. Beverage companies in Brazil and Mexico centralize procurement around aluminum for its infinite recyclability and lower transport costs per unit.
- Tinplate:Tin-coated steel substrate delivers corrosion resistance mandatory for acidic vegetable and tomato formulations where flavor inertness protects product integrity. European steel mill consolidation limits alternative sourcing for food can producers facing REACH compliance deadlines.
- Steel:Heavier gauge substrate serves industrial aerosol and chemical packaging where pressure resistance exceeds aluminum capabilities.
- Biodegradable:Emerging polymer-metal hybrid structures target single-use restrictions in select European deposit-return scheme markets.
Aluminum handles the majority of throughput; biodegradable formats are expanding most quickly on share as lining chemistry restrictions accelerate material experimentation.
Application:
Filling process temperature and hermetic sealing requirements create distinct tooling investments across liquid, viscous, and pressurized product categories.
- Food & Beverages:Shelf-stable distribution of carbonated drinks, processed foods, and ready-to-drink cocktails commands the largest revenue pool. EPA volatile organic compound emission limits from coating operations constrain US manufacturing capacity expansion.
- Personal Care:Aerosol deodorant and dry shampoo formulations in 100 ml and 250 ml sizes represent a faster-growing niche. EU F-Gas Regulation phasedown of hydrofluorocarbon propellants accelerates migration to compressed gas valve-crimped aluminum containers.
- Chemical:Industrial solvents and coatings require corrosion-resistant linings and thicker wall specifications than consumer applications.
- Household Products:Cleaning sprays and air fresheners occupy mid-volume demand with seasonal promotional cycles.
Food & Beverages dominates absolute volume; Personal Care climbs the fastest as travel-format powder formulations gain shelf space.
Size:
Transport cube efficiency and retail shelf modularization drive standardization around discrete capacity points despite brand differentiation efforts.
- 100ml:Travel-format personal care aerosols and premium spirit samples. ANVISA sanitary registration requirements in Brazil shape import access rules for foreign producers targeting Latin American airline and hospitality channels.
- 250ml:Ready-to-drink cocktails and sparkling water premium positioning. Thinner-wall aluminum solutions unlock distribution economics for spirits brands outside traditional beer contracts.
- 500ml:Standard beverage multipack configurations and food can family sizes.
- 1L:Bulk food service and institutional catering formats with lower per-unit logistics costs.
250ml and 500ml split mainstream throughput; 100ml gains share fastest as micro-format personal care launches multiply.
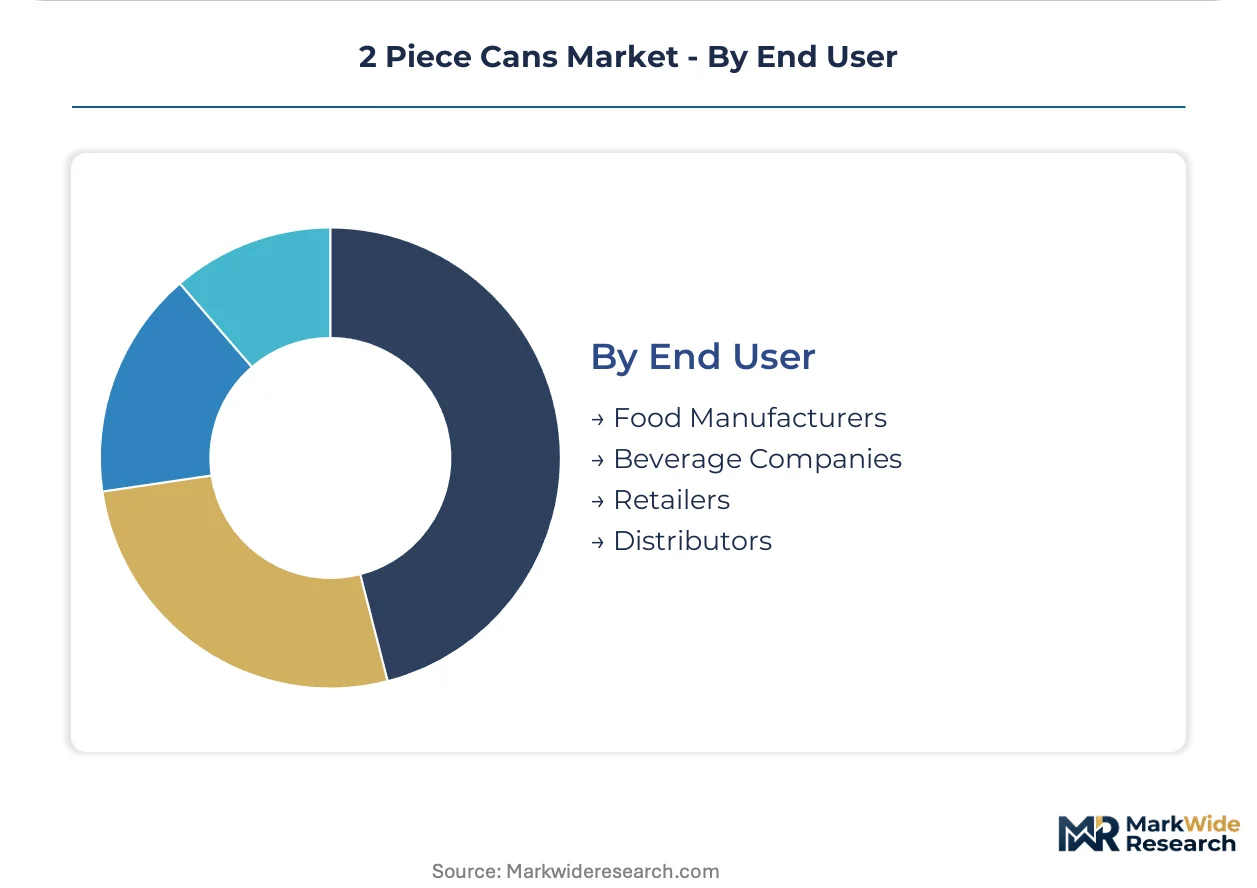
End User:
Procurement centralization versus distributed sourcing separates contract structures and technical service bundling across the value chain.
- Food Manufacturers:Acidic and protein-rich formulation expertise demands corrosion-resistant tinplate partnerships with European steel substrate producers.
- Beverage Companies:North American carbonated soft drink bottlers now consolidate aluminum can sourcing through single-converter frameworks, displacing regional distributor intermediaries.
- Retailers:Private-label sourcing teams negotiate direct converter relationships for seasonal and regional SKU proliferation enabled by digital printing capabilities.
- Distributors:Inventory pooling and logistics coordination services face margin compression as multinational headquarters mandate continental contract structures.
Beverage Companies anchor procurement volume; Retailers are gaining negotiating leverage fastest through digital printing adoption for short-run micro-segmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA oversees volatile organic compound emissions from can coating operations in the United States, while REACH and the EU Green Deal mandate recycled content thresholds across European supply chains. Brazil's ANVISA imposes sanitary registration requirements that shape Latin American production incentives. These regulatory frameworks are compressing margins while forcing substrate substitution decisions across beverage and food packaging supply chains.
United States
Carbonated beverage bottlers centralize aluminum can procurement through single-converter frameworks, displacing regional distributor intermediaries. EPA emission limits for volatile organic compounds from can lining applications require capital-intensive thermal oxidizer installations at manufacturing facilities. Chicago and Milwaukee industrial corridors host concentrated converter capacity serving North American beverage contracts.
Germany
Deposit-return scheme expansion generates guaranteed aluminum scrap flows that reduce recycled content certification costs for compliant producers. EU Green Deal circularity mandates and REACH substance evaluations constrain bisphenol-A derived coating options, forcing reformulation timelines. Düsseldorf and Hamburg anchor European tinplate food packaging capacity where technical specifications for corrosion resistance remain stringent.
Brazil
ANVISA sanitary registration requirements for food-contact metal packaging create localized production incentives that concentrate Latin American capacity expansion. Can-Pack Group and Crown Holdings have expanded production capacity to serve beverage markets across the continent. São Paulo industrial corridors host the densest clustering of two-piece can manufacturing lines in Latin America.
China
Ready-to-drink cocktail brands specify thinner-wall aluminum solutions for premium positioning in 250 ml and 355 ml formats. National standards on food-contact materials and dual carbon goals shape converter investment decisions. Yangtze River Delta manufacturing clusters supply aluminum sheet conversion for domestic beverage and export aerosol applications.
Japan
Personal care brands adopt 100 ml aluminum cans for travel-format dry shampoo powder formulations. METI guidance on resource circulation and packaging waste reduction influences substrate selection for premium cosmetic applications. Kansai industrial zones maintain specialized capacity for high-precision aerosol valve-crimped containers.
2 Piece Cans Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the two-piece cans market. The upper tier commands pricing power through captive aluminum sheet supply and continental contract structures with multinational beverage headquarters. Mid-scale converters compete on lightweighting technology and digital printing capabilities for short-run regional brands. Capacity expansion and backward integration into substrate production represent the dominant competitive moves as converters defend margin positions against primary aluminum ingot volatility.
Within the integrated multinational tier, Ball Corporation and Crown Holdings exemplify scale-driven positioning through geographic diversification and input cost control. Ardagh Group occupies a position defined by R&D intensity in thinner-wall solutions. Among regionally focused specialists, Can-Pack Group anchors Latin American production concentration, while Toyo Seikan represents Japanese precision manufacturing archetypes for aerosol and premium beverage formats.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings |
| Ardagh Group |
| Silgan Containers |
| Can-Pack Group |
| CPMC Holdings |
| Toyo Seikan |
| Envases Group |
| CCL Industries |
| Others |
Value Chain & Pricing Dynamics
Ninety-day aluminum sheet inventory cycles at North American beverage converters compress negotiation windows while amplifying exposure to London Metal Exchange volatility, concentrating pricing power among backward-integrated producers who control captive smelter relationships. This lead-time structure forces mid-scale converters into spot-market vulnerability during energy-intensive primary aluminum disruptions, reshaping contract terms toward indexed pricing clauses that transfer commodity risk downstream.
Pricing Analysis
Transatlantic aluminum can sheet spreads widen during European smelting curtailments, with German beverage contracts commanding premiums over US Midwest pricing due to EU Green Deal recycled-content certification costs. Three-tier pricing structure across premium, standard, and economy levels separates Ball Corporation's captive-supply tier from distributor-served regional brands and import-dependent spot buyers. Pricing pressure stems from primary aluminum ingot volatility transmitting directly to conversion margins. Beverage multinationals exercising single-converter procurement frameworks exhibit lowest price sensitivity, while regional craft cocktail brands face acute cost compression during energy price spikes.
Supply Chain Analysis
Bauxite refining concentration in Guinea and Australia underwrites primary aluminum cost structures that cascade through Chinese and Canadian smelter output into can sheet conversion. Draw-and-iron tooling fabrication draws from German precision engineering clusters and Japanese machine tool specialists, creating single-source vulnerability for new line commissioning. Supply chain risk centers on European steel mill consolidation limiting tinplate alternatives for acidic food formulations. Distribution runs through São Paulo industrial corridors for Latin American beverage markets and Chicago-Milwaukee hubs for North American carbonated soft drink bottlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The two-piece cans market sits in aluminum price-cycle recovery, with smelter restarts and scrap flow normalization from expanded German deposit-return schemes providing cyclical uplift through improved converter margin structures.
For Market Incumbents: Fortify backward integration into aluminum sheet production to insulate beverage contracts from London Metal Exchange volatility, while accelerating digital printing capability investments to capture short-run seasonal demand from craft cocktail brands. Crown Holdings' European tinplate dominance demonstrates how geographic concentration in corrosion-resistant food packaging creates defensive moats against REACH compliance disruptions. Priority lever rests on can tooling engineer retention programs that constrain competitor capacity ramp rates.
For New Entrants and Emerging Players: Technical service unbundling from unit pricing represents the most exploitable gap, as multinational beverage headquarters mandate continental contract structures that displace localized converter support. White-space targets include 100 ml aerosol dry shampoo formats for Japanese personal care brands and 250 ml ready-to-drink cocktail lightweighting contracts outside established beer relationships. Go-to-market angle should emphasize rapid digital printing turnaround for regional brand seasonal launches.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates seeking to divest non-core metal exposure, particularly European tinplate food can assets facing REACH reformulation investment burdens. Long-term viability frames aluminum circularity economics against biodegradable substrate experimentation, with five-to-ten-year windows hinging on extended producer responsibility scheme expansion. Signal to watch: EPA thermal oxidizer enforcement intensity at US coating facilities, which would accelerate consolidation among capital-constrained mid-scale converters.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Sheet Production | Ball Corporation's captive supply secures input cost stability across North American beverage contracts. |
| Digital Printing Capability Expansion | Short-run seasonal design execution captures craft cocktail brand procurement previously uneconomical at rotary press scale. |
| Lightweighting Technology R&D Investment | Ardagh Group's thinner-wall solutions unlock ready-to-drink cocktail distribution outside traditional beer contract structures. |
| Deposit-Return Scheme Compliance Certification | Guaranteed aluminum scrap flows from German and Nordic markets reduce recycled content verification costs for compliant producers. |
| Can Tooling Engineer Training Partnerships | Shallow labor pools for draw-and-iron line commissioning constrain new capacity ramp rates while favoring established producers. |
Study Parameters
The analysis maps aluminum beverage can, tinplate food can, and aerosol personal care sub-sectors, each validated through converter procurement directors, beverage company supply chain executives, and coating chemical formulation specialists. Primary interviews with can tooling engineers and secondary validation through EPA emission filings, REACH substance evaluation databases, and ANVISA sanitary registration records anchored supply-side capacity assessments. Customs data on aluminum sheet trade flows and steel mill output statistics provided demand calibration. Bottom-up segment sizing triangulated against top-down macro aluminum consumption benchmarks.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with aluminum can throughput cross-referenced against beverage industry production data and tinplate food can volumes verified against processed food shipment statistics. Segmentation dimensions modeled include substrate chemistry, filling process temperature requirements, distribution channel configuration, and regional regulatory cluster. CAGRs derived from trend extrapolation moderated by aluminum price cycle phase and coating chemistry substitution timelines. Forecast inputs incorporated EU Green Deal recycled content mandate implementation pace and F-Gas Regulation propellant phasedown schedules.
Forecasts assume regulatory continuity in EPA emission limits, REACH substance restrictions, and ANVISA sanitary registration frameworks; material policy shifts would require re-modeling around thermal oxidizer compliance costs or epoxy-phenolic lining prohibitions. Scenario readiness requires monitoring lining material qualification partnerships between coating suppliers and steel substrate producers. Practitioners should keep alternative scenarios live as EU Green Deal circularity mandates and extended producer responsibility scheme expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Packer Bottle Market
Containers
Thermoformed Containers Market
Containers
Lever Lid Tinplate Containers Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
Lift-Off Lid Box Market
Containers
Shipping Container Liners Market
Containers
Thin Wall Containers Market
Containers
Screw Top Pails Market
Containers
PET Hinged Containers Market
Containers
Foldable Container Market
Containers
Global Cardboard Box and Container Market
Containers
Container Stacking Machine Market
Containers
Laminated Bulk Bins Market
Containers
Pail Lids Market
Containers
Multi Cavity Tray Market
Containers
Belgium Container Glass Market