
 Hinged Lid Tins Market | 2026-2036
Hinged Lid Tins Market Size, Share, and Industry Trends Forecast 2026-2036
Hinged Lid Tins Market Foresight
The premium hinged lid tins segment is repositioning away from commodity food-grade containers toward cosmetic and gift applications with embossed finishes and custom lithography. Hoffmann Neopac AG leverages Swiss precision tooling to dominate pharmaceutical and cosmetic tin supply in Europe. Tin King Manufacturing Co. Ltd. anchors high-volume production for Asian export markets through integrated stamping and coating lines. Massilly Holding S.A.S. differentiates via deep-drawn seamless construction for premium food and candle brands.
Hinged lid tins are rigid metal containers fabricated from tinplate, aluminum, or stainless steel, formed through deep drawing or stamping processes with an integral hinge mechanism that permits repeated opening and closing without component separation; wall thickness typically ranges from 0.18 mm to 0.35 mm depending on structural load and barrier requirements. These containers serve primary functions in moisture-sensitive product protection, shelf-life extension, and brand differentiation through surface decoration. Aluminum material commands expanding share in cosmetics end use due to lightweight properties and compatibility with anhydrous formulations. Round tins sustain dominant volume in candle applications where thermal cycling resistance proves critical. Custom shaped tins capture disproportionate margin pools in limited-edition gift and promotional segments where die investments amortize across short production runs.
EU REACH and F-Gas Regulation constrain solvent-based coating chemistries and propellant choices in tin manufacturing, redirecting investment toward UV-cured and powder coating systems. FDA 21 CFR requirements for food-contact substances govern tinplate internal lacquer specifications in US-bound exports, creating compliance cost tiers that favor larger producers with dedicated analytical laboratories. BIS certification for food-grade metal packaging in India adds testing burden for entrants without established local partnerships. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between regional certification investments versus contract manufacturing partnerships.
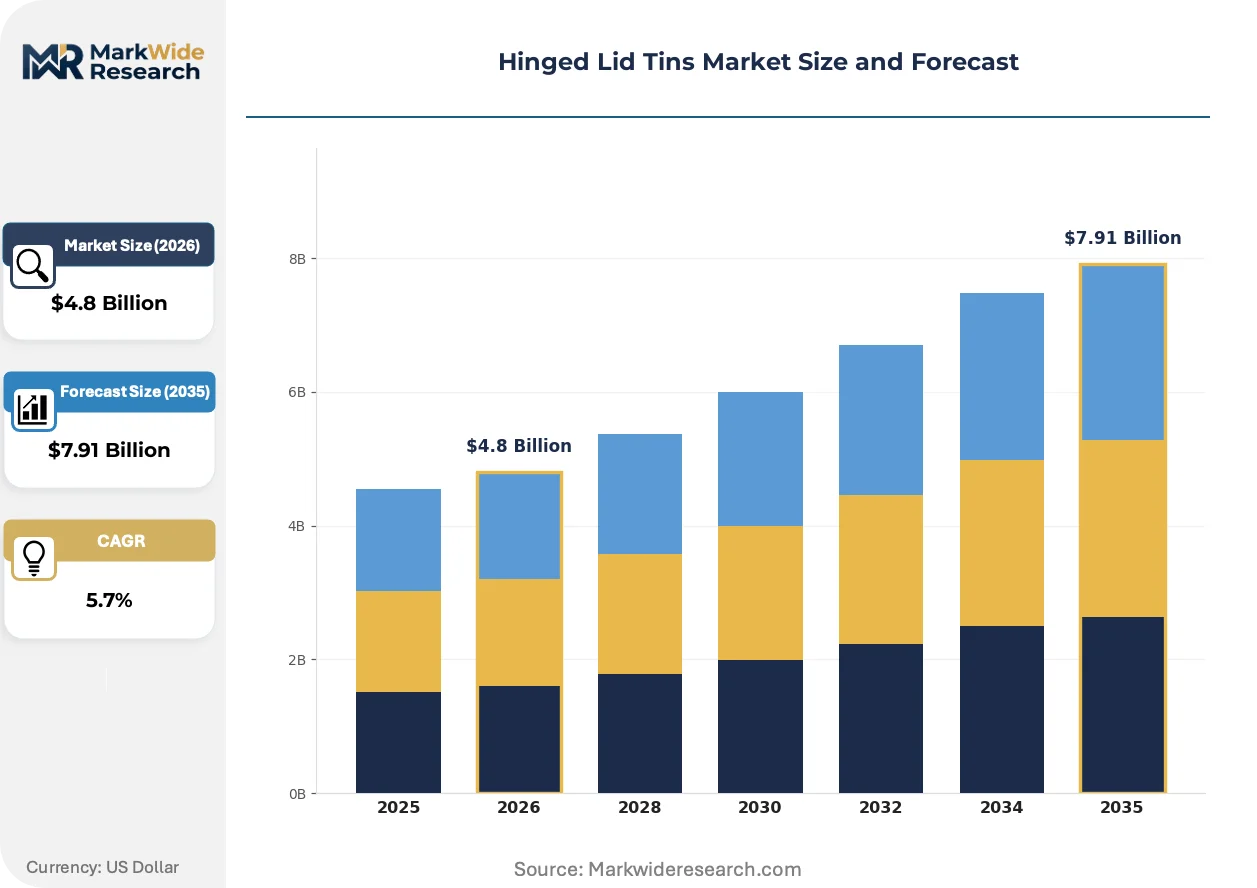
Market Dynamics
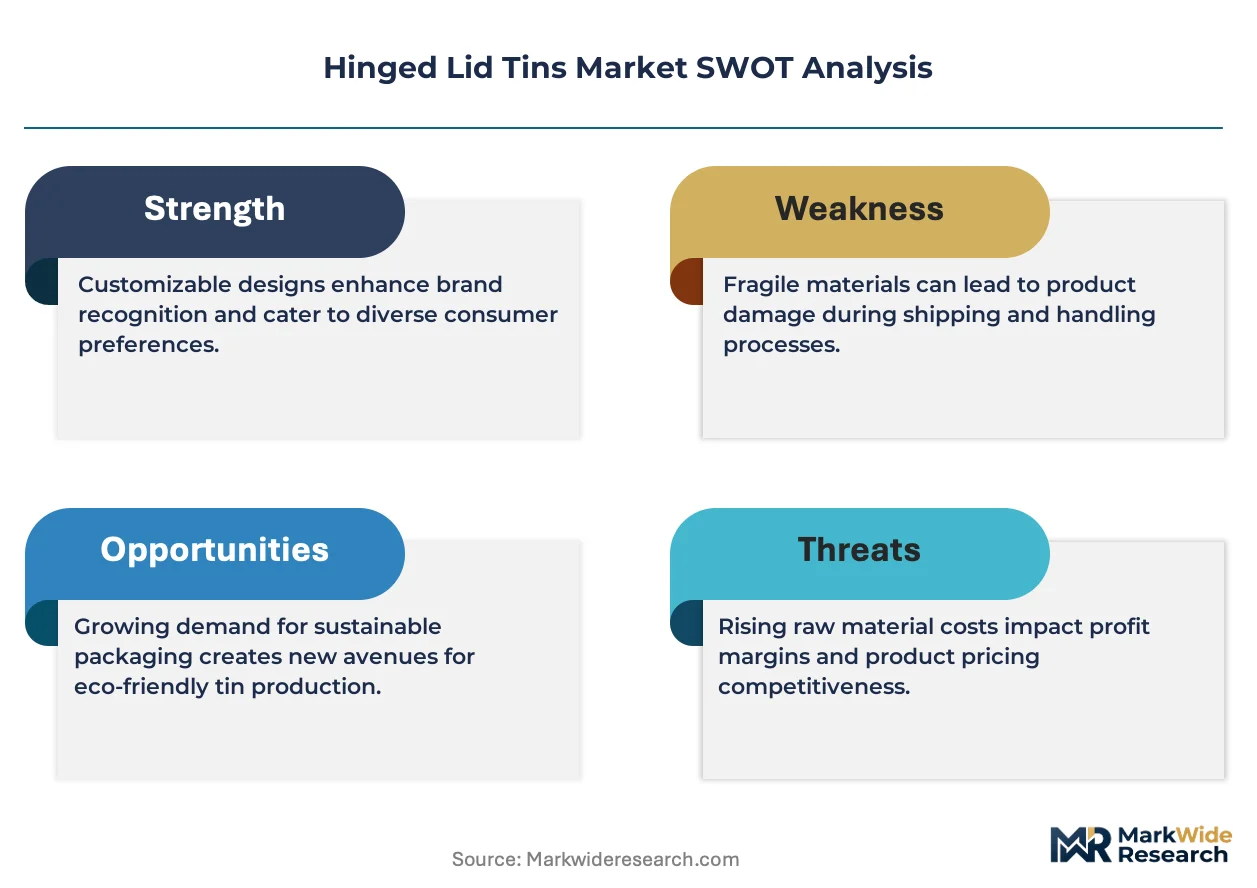
EU REACH and F-Gas Regulation are compressing solvent-based coating chemistries, forcing capital reallocation toward UV-cured and powder coating systems across European tin manufacturing.
Growth Catalysts
- Aluminum Material Substitution:Premium cosmetic brands are accelerating aluminum adoption for anhydrous formulations, leveraging lightweight barrier properties that outperform tinplate in moisture-sensitive applications.
- EU Packaging and Packaging Waste Regulation:Tightened material recovery targets across member states are mandating closed-loop metal packaging systems, directly benefiting infinitely recyclable tinplate and aluminum containers.
- German Precision Metalworking Clusters:Concentrated tooling expertise in Baden-Württemberg and Bavaria enables rapid prototyping of embossed finishes and custom lithography for luxury goods packaging.
Market Restraints
- Tinplate Input Volatility:Cold-rolled steel substrate prices fluctuate with energy-intensive European smelting operations, compressing margin predictability for mid-volume producers.
- Substitution by Flexible Pouches:Stand-up pouches with resealable zippers are capturing commodity food segments where barrier requirements permit polymer solutions.
- FDA 21 CFR Compliance Tiers:Food-contact substance testing requirements for US-bound exports create fixed cost barriers that disadvantage smaller producers without captive analytical laboratories.
Strategic Opportunities
- Indian BIS Certification Gap:Food-grade metal packaging mandates present partnership opportunities for European producers with established testing protocols to serve domestic brands via contract manufacturing.
- Candle Thermal Cycling Applications:Round tin formats with enhanced wall thickness tolerances address premium home fragrance segments requiring repeated heating and cooling durability.
- Digital Print Convergence:Integration of UV-cured coating lines with inkjet decoration systems enables economic short runs for limited-edition promotional tins.
Industry Challenges
- Deep-Draw Tooling Skill Scarcity:Precision die maintenance and seamless construction expertise concentrate among aging workforces in Swiss and German metalworking regions.
- Extended Producer Responsibility Reconfiguration:Evolving EPR frameworks require producers to establish collection infrastructure or pay compliance fees, complicating cross-border distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hinged Lid Tins Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Square Tins, Round Tins, Rectangle Tins, Custom Shaped Tins Material: Aluminum, Tinplate, Stainless Steel, Biodegradable Materials Size: Small, Medium, Large, Extra Large End Use: Food Storage, Cosmetics, Candles, Crafts |
| Companies Covered | Allstate Can Corporation, Tin King Manufacturing Co. Ltd., TinWerks Packaging Co., Desjardin, Hoffmann Neopac AG, Masaş Metal, Massilly Holding S.A.S, Ti.Pack. S.r.l., SKS Bottle & Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hinged Lid Tins Market Shifts & Advancements
Surface decoration and coating technologies are compressing minimum viable run lengths while regulatory chemistry constraints are reshaping capital deployment across manufacturing bases.
Digital inkjet lithography is decentralizing custom decoration economics for hinged lid tins. Premium cosmetic and gift brands are adopting short-run digital workflows for seasonal and limited-edition launches. This technology is decentralizing volume concentration away from traditional offset lithography houses toward integrated stamping-coating-printing facilities.
EU F-Gas Regulation and REACH restrictions on volatile organic compounds are eliminating solvent-based coating systems from European production lines. Manufacturers are redirecting investment toward UV-cured and powder coating alternatives with lower environmental footprints. Cosmetic and pharmaceutical tin segments in Germany and Switzerland are absorbing the capital burden fastest due to proximity to precision application equipment suppliers.
Brand procurement teams are consolidating supplier relationships around vertically integrated partners capable of managing decoration, coating, and compliance documentation internally. Mid-sized candle and food brands are abandoning fragmented supplier networks for single-source tin packaging contracts. This consolidation pattern is most pronounced in North American and Western European markets where EPR and FDA compliance documentation requirements have intensified.
Hinged Lid Tins Market Segmentation
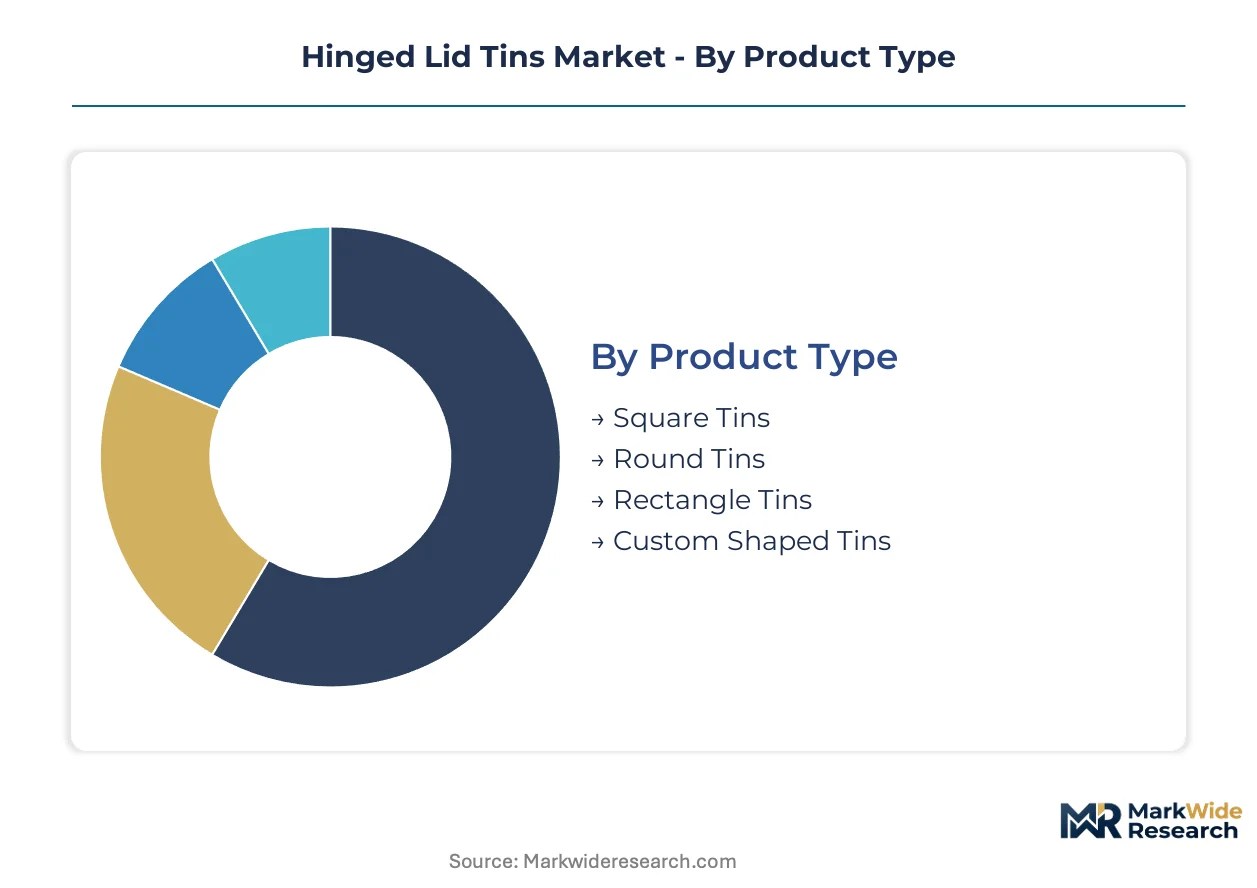
Hinged lid tins manufacturers allocate capital across four distinct dimensions, each dictating tooling investments, coating line configurations, and compliance documentation burdens. Product geometry and material selection dominate upfront capital intensity, while end-use specifications determine recurring certification costs.
Product Type:
Deep-draw tooling complexity and die maintenance requirements separate capital-intensive formats from standardized production runs.
- Round Tins:Seamless cylindrical construction through progressive die stamping delivers uniform wall thickness for thermal cycling applications. Candle brands in Germany specify enhanced tolerances for repeated heating durability, locking in multi-year tooling contracts with Swiss precision houses.
- Custom Shaped Tins:Irregular geometries require dedicated die sets with limited reutilization across product lines. Limited-edition gift programs in France absorb premium unit economics where short runs amortize unique embossing investments.
- Square Tins:Corner radius engineering and lid fit tolerances suit standardized food storage applications with predictable volume profiles.
- Rectangle Tins:Elongated formats optimize shipping cube efficiency for flat-packed confectionery and tobacco products.
Round tins absorb the bulk of installed capacity; custom shaped tins are expanding most quickly.
Material:
Raw material processing chemistry and barrier coating specifications create tiered compliance cost structures across production bases.
- Aluminum:Lightweight substrate with inherent moisture barrier properties eliminates internal lacquer requirements for anhydrous cosmetic formulations. Premium beauty brands in Switzerland specify aluminum for compatibility with solvent-free formulations under REACH constraints.
- Tinplate:Cold-rolled steel core with tin coating demands food-grade internal lacquer systems governed by FDA 21 CFR for US-bound exports. German producers maintain captive analytical laboratories to manage batch certification documentation.
- Stainless Steel:Corrosion-resistant alloy commands luxury positioning in pharmaceutical and high-value gift segments with minimal volume scale.
- Biodegradable Materials:Experimental bio-based substrates and coating systems target emerging EPR frameworks with unproven manufacturing economics.
Aluminum is climbing the fastest; tinplate retains dominant volume share.
Size:
Stamping press tonnage and coating line throughput economics stratify production planning across dimensional categories.
- Small:Pocket-sized formats for lip balms and sample cosmetics run on high-speed progressive dies with minimal material waste.
- Medium:Standard candle and food storage dimensions optimize logistics palletization across European distribution networks.
- Large:Bulk storage applications require reinforced wall specifications and specialized handling equipment.
- Extra Large:Niche industrial and promotional formats strain conventional deep-draw equipment, limiting supplier options.
Medium sizes anchor volume throughput; small formats are gaining share fastest.
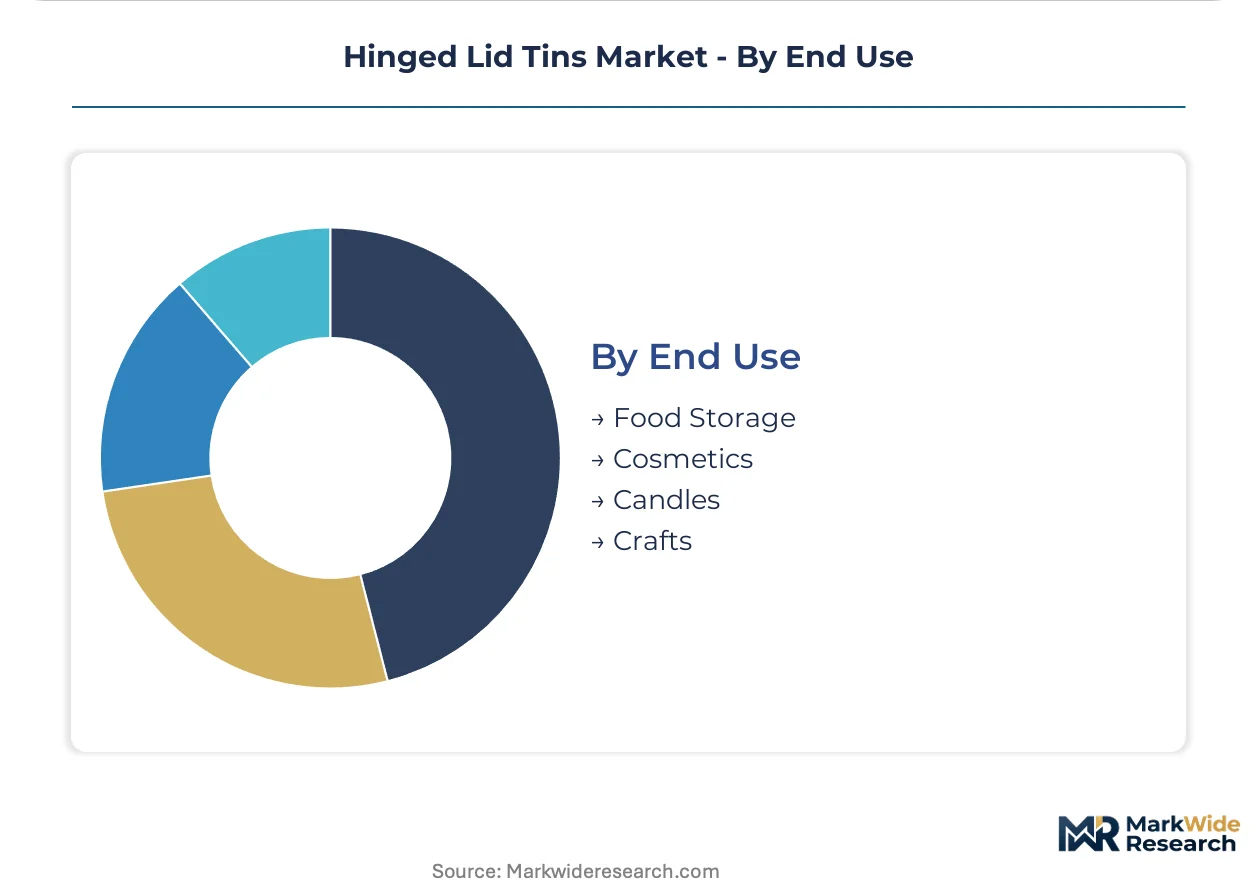
End Use:
Regulatory jurisdiction and barrier performance requirements fragment certification pathways across application segments.
- Cosmetics:Anhydrous formulation compatibility and surface decoration standards drive aluminum adoption. German and Swiss precision metalworking clusters serve luxury beauty brands with integrated UV-cured coating and digital lithography capabilities.
- Candles:Thermal cycling resistance and lid seal integrity specifications concentrate demand in round tin formats. French and German home fragrance brands specify enhanced wall thickness for repeated heating durability.
- Food Storage:FDA and BIS compliance documentation favors larger producers with dedicated testing infrastructure.
- Crafts:Undecorated or simply printed tins for hobby and educational markets tolerate commodity-grade specifications.
Cosmetics commands premium margin pools; candles sustain highest volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg anchors continental production capacity through precision metalworking clusters serving pharmaceutical and cosmetic packaging specifications.
Germany
Luxury cosmetic brands in Bavaria and Baden-Württemberg drive demand for embossed aluminum tins with UV-cured coating finishes. REACH and F-Gas Regulation constrain solvent-based chemistries, redirecting capital toward powder coating systems. Stuttgart-area tooling houses maintain multi-year contracts with Swiss precision engineering partners for seamless deep-draw die maintenance.
Switzerland
Pharmaceutical packaging specifications in Basel and Zurich demand corrosion-resistant barrier properties for anhydrous formulations. Swissmedic oversees food-contact and cosmetic container compliance documentation. Solothurn precision metalworking clusters supply adjacent EU markets with lithography-integrated coating lines.
United States
Candle and home fragrance brands in the Midwest and Southeast specify round tin formats with enhanced thermal cycling tolerances. FDA 21 CFR governs food-contact lacquer specifications for tinplate exports, favoring producers with captive analytical laboratories. Ohio and Pennsylvania metal stamping corridors serve domestic food storage and promotional tin segments.
France
Paris and Lyon-based luxury goods houses commission limited-edition gift tins with custom embossing and short-run digital lithography. EPR frameworks under EU Packaging and Packaging Waste Regulation mandate collection infrastructure investments. Normandy and Rhône-Alpes coating facilities specialize in UV-cured systems for cosmetic-grade surface finishes.
India
Domestic food brands in Maharashtra and Gujarat seek BIS-certified metal packaging for spice and confectionery applications. BIS certification creates testing burden for entrants without established laboratory partnerships. Mumbai-Pune industrial corridor hosts contract manufacturing arrangements linking European coating expertise with regional stamping capacity.
Hinged Lid Tins Market Competitive Landscape
Premium-margin players sit above commodity-margin players across coating sophistication and compliance documentation capabilities. The vendor base stratifies between vertically integrated precision houses with captive lithography lines and volume-focused stampers serving undifferentiated food storage segments. Three archetypes dominate: Swiss-German precision specialists, Asian export-scale fabricators, and regional contract manufacturers bridging certification gaps. Consolidation pressure intensifies through EPR-driven collection infrastructure requirements and FDA compliance cost tiers that disadvantage smaller producers.
Among Swiss-German precision specialists, Hoffmann Neopac AG exemplifies the integrated coating-lithography archetype serving pharmaceutical and cosmetic specifications. Massilly Holding S.A.S occupies a position within the seamless deep-draw construction tier for premium food and candle applications. Tin King Manufacturing Co. Ltd. anchors high-volume export production through integrated stamping and coating lines serving Asian and international markets.
| Leading Market Players |
|---|
| Allstate Can Corporation |
| Tin King Manufacturing Co. Ltd. |
| TinWerks Packaging Co. |
| Desjardin |
| Hoffmann Neopac AG |
| Masaş Metal |
| Massilly Holding S.A.S |
| Ti.Pack. S.r.l. |
| SKS Bottle & Packaging |
| Others |
Supply & Pricing Matrix
EU Packaging and Packaging Waste Regulation compliance gates qualified supply access and premium-tier pricing power, as extended producer responsibility frameworks force capital deployment into collection infrastructure that only scaled producers can absorb. Tinplate input volatility and REACH-constrained coating chemistry investments stratify the supplier base into certification-haves and certification-have-nots, with compliant German and Swiss precision houses commanding 40-60% price premiums over commodity Asian stampers.
Pricing Analysis
Outcome-linked pricing for thermal cycling performance anchors premium tiers in candle and cosmetic applications, where lid seal integrity and wall thickness tolerances determine brand procurement decisions. Three-tier pricing structure across premium, standard, and economy levels separates Swiss-German precision specialists with captive analytical laboratories from mid-volume European stampers and high-volume Asian export fabricators. Pricing pressure stems from cold-rolled steel substrate volatility in energy-intensive European smelting operations, compressing margin predictability for mid-tier producers. Commodity food storage buyers exhibit highest price sensitivity and lowest switching costs, while luxury cosmetic brands prioritize decoration sophistication and compliance documentation over unit economics.
Supply Chain Analysis
Direct-to-brand channels handle premium cosmetic and pharmaceutical demand, while distributor networks serve fragmented candle and food storage segments across North American and European markets. Raw material supply concentrates in Germany, Switzerland, and China, with Baden-Württemberg tooling houses and Solothurn precision clusters feeding adjacent EU markets while Chinese integrated stamping-coating lines anchor high-volume export production. Cold-rolled steel substrate, aluminum coil, and UV-cured coating resins constitute critical input dependencies, with energy price volatility in European smelting operations transmitting directly to tinplate cost structures. Single-source vulnerability in Swiss-German deep-draw die maintenance expertise concentrates seamless construction capability among aging workforces, constraining capacity expansion for premium formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where FDA 21 CFR and EU REACH create barrier-to-entry moats favoring producers with captive analytical laboratories and integrated coating-lithography capabilities.
For Market Incumbents: Acquire UV-cured and powder coating line assets to preempt REACH and F-Gas Regulation chemistry constraints, while consolidating multi-year tooling contracts with Swiss precision die maintenance houses to lock in seamless construction capability. Defensive positioning requires backward integration into aluminum coil processing to buffer raw material volatility, and channel control through direct-to-brand relationships that bypass distributor margin stacking in premium cosmetic segments.
For New Entrants and Emerging Players: Digital inkjet lithography integration presents a technology-first wedge for short-run limited-edition gift programs where traditional offset houses cannot amortize die investments. Target Indian BIS certification gaps through contract manufacturing partnerships linking European coating expertise with Maharashtra and Gujarat stamping capacity, leveraging the country's food-grade metal packaging mandates without bearing full laboratory establishment costs.
For Investors and Strategic Acquirers: REACH-driven coating line retrofit announcements from European producers are the leading indicator that capital allocation is shifting toward compliant capacity, signaling acquisition timing for undervalued precision metalworking assets before regulatory deadlines compress. Long-term viability favors vertically integrated specialists with pharmaceutical and cosmetic certification depth over pure-play volume stampers exposed to flexible pouch substitution in commodity food segments.
| Strategic Initiative | Industry Significance |
|---|---|
| UV-Cured Coating Line Investment | REACH compliance redirects capital from solvent-based systems toward lower-VOC alternatives in German and Swiss facilities. |
| Deep-Draw Die Maintenance Partnership | Swiss precision engineering contracts lock in seamless construction capability for thermal cycling applications. |
| BIS Certification Contract Manufacturing | European coating expertise paired with Indian stamping capacity bridges regulatory gaps for domestic food brands. |
| Digital Lithography Integration | Short-run economics enable limited-edition gift programs for Paris and Lyon luxury goods houses. |
| Extended Producer Responsibility Infrastructure | Collection system investments satisfy EU Packaging and Packaging Waste Regulation mandates across member states. |
Research Methodology
Multi-period observation of coating chemistry investments, regulatory compliance announcements, and precision tooling contract patterns anchored the trend analysis, supplemented by interviews with tin manufacturing plant managers, cosmetic brand packaging procurement leads, pharmaceutical regulatory affairs directors, and candle brand supply chain heads. Secondary validation drew from ECHA REACH substance restrictions databases, FDA 21 CFR food-contact substance filings, BIS certification registries, and EU Packaging and Packaging Waste Regulation implementation timelines. Bottom-up capacity assessments across German, Swiss, and Chinese production bases were triangulated against top-down demand estimates from end-use segment analysis.
Segment-weighting across product type, material substrate, dimensional category, and end-use application determined value distribution and growth allocation throughout the forecast period. CAGRs were derived from elasticity-adjusted volume projections and price trajectory assumptions, with specific inputs including cold-rolled steel substrate cost indices, aluminum coil trade flow data, and UV-cured coating equipment installation rates across European manufacturing bases.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to F-Gas or REACH annexes, abrupt shifts in flexible pouch barrier technology, and geopolitical disruptions to Chinese aluminum coil supply. Forecasts reflect assumptions about continued REACH enforcement stringency and EPR framework implementation timelines across EU member states. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Light Density Polyethylene (LDPE) Bottles Market
Containers
Tottle Containers Market
Containers
Screw Top Lids Market
Containers
Compartment Take-Out Container Market
Containers
Pail Lids Market
Containers
Carboy Market
Containers
Takeout Containers Market
Containers
Gable Top Container Market
Containers
Half Height Containers Market
Containers
Clear Hinged Container Market
Containers
EMEA Container Technology Market
Containers
Kuwait Container Glass Market
Containers
Two Compartment Bottles Market
Containers
Foldable Large Containers Market
Containers
Packer Bottle Market
Containers
EPS Container Market