
 Intratumoral Cancer Therapies Market | 2026-2036
Intratumoral Cancer Therapies Market Size, Share, and Industry Trends Forecast 2026-2036
Intratumoral Cancer Therapies Market Foresight
Oncolytic virology and immuno-oncology talent pools is bifurcating between established pharmaceutical corridors and emerging biotech clusters, constraining pipeline velocity for novel intratumoral platforms. Amgen Inc. leverages its T-VEC heritage to anchor commercial infrastructure in melanoma. Replimune competes through next-generation oncolytic virus candidates engineered for enhanced systemic immune activation. Intensity Therapeutics differentiates via its DfuseRx technology platform, which specializes in intratumoral delivery of chemotherapy payloads.
Intratumoral cancer therapies constitute localized treatment modalities administered directly into tumor tissue, encompassing oncolytic viruses, cytokine injections, and ablative energy systems designed to induce immunogenic cell death while minimizing systemic exposure. The primary commercial purpose centers on converting immunologically "cold" tumor microenvironments into "hot" states susceptible to checkpoint inhibitor synergy. Immunotherapies lead current revenue contribution through established oncolytic virus platforms, while targeted therapies represent the fastest-expanding segment as bispecific and cytokine-armed modalities advance through clinical pipelines. Solid tumors command the dominant therapy area position, though melanoma maintains disproportionate margin concentration due to favorable reimbursement and accessible lesion anatomy.
The FDA's breakthrough therapy and regenerative medicine advanced therapy designations shape clinical development economics by compressing regulatory review timelines for intratumoral candidates. EMA's ATMP framework and the EU Clinical Trials Regulation govern European market access, with notified body oversight of viral vector manufacturing quality. WHO prequalification pathways influence lower-middle-income country procurement for biosimilar cytokine products. Stakeholders must monitor how evolving FDA guidance on combination immuno-oncology trial design reshapes partnership structures between intratumoral developers and checkpoint inhibitor manufacturers.
Market Dynamics
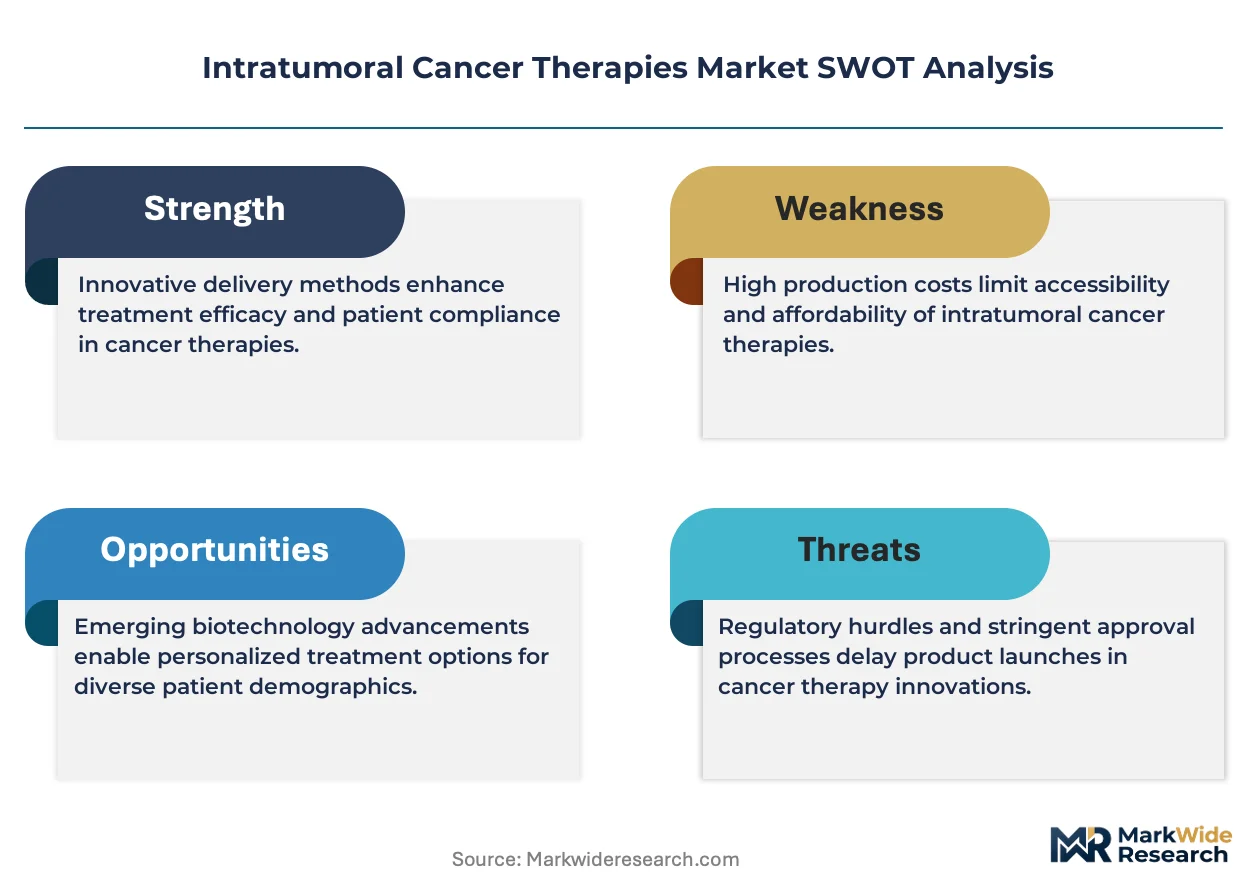
The FDA's breakthrough therapy designation pathway compresses clinical timelines for intratumoral candidates, creating competitive pressure on developers to accelerate from first-in-human to pivotal trials within compressed windows.
Growth Catalysts
- Regulatory Acceleration:The FDA's breakthrough therapy and regenerative medicine advanced therapy designations compress review timelines for intratumoral oncolytic virus candidates, incentivizing sponsor investment in combination immuno-oncology trial designs.
- Melanoma Lesion Accessibility:Cutaneous and subcutaneous tumor anatomy enables direct injection protocols without image guidance, reducing site-of-care infrastructure requirements and expanding addressable patient pools across community oncology settings.
- Cold-to-Hot Tumor Conversion:Intratumoral cytokine engineering platforms demonstrate enhanced systemic immune activation when sequenced with checkpoint inhibitors, creating pharmacologic rationale for combination development partnerships.
Market Restraints
- Viral Vector Manufacturing Concentration:Contract manufacturing capacity for GMP-grade oncolytic viruses concentrates among a limited set of European and North American CDMOs, constraining batch release velocity for multi-cohort expansion studies.
- Reimbursement Uncertainty:CMS and commercial payers apply inconsistent prior authorization criteria for intratumoral administration codes, creating revenue recognition delays for practices adopting novel injection protocols.
- Technical Limitation in Deep Tissue:Current needle delivery systems face anatomical constraints for visceral organ lesions, limiting addressable indications to accessible tumor sites and compressing total market expansion potential.
Strategic Opportunities
- Underpenetrated Non-Melanoma Skin Cancer:Squamous cell carcinoma and basal cell carcinoma patient populations remain underserved by intratumoral modalities, with lesion accessibility comparable to melanoma but limited commercial penetration to date.
- Technology Convergence:Bispecific antibody engineering is converging with oncolytic viral backbone platforms, enabling localized expression of T-cell engagers within tumor microenvironments and reducing systemic cytokine release risk.
- EU ATMP Tailwind:The European Medicines Agency's advanced therapy medicinal product framework provides centralized marketing authorization pathways for gene-modified oncolytic viruses, reducing regulatory fragmentation across member states.
Industry Challenges
- Oncolytic Virology Talent Scarcity:Specialized expertise in viral vector engineering, tumor-selective replication mechanisms, and host immune evasion strategies concentrates among a limited pool of academic and industry researchers, constraining hiring velocity for emerging biotech platforms.
- Combination Trial Complexity:Protocol design for intratumoral-plus-checkpoint inhibitor studies requires coordination across multiple sponsor organizations, creating intellectual property negotiation friction and delaying trial activation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intratumoral Cancer Therapies Market |
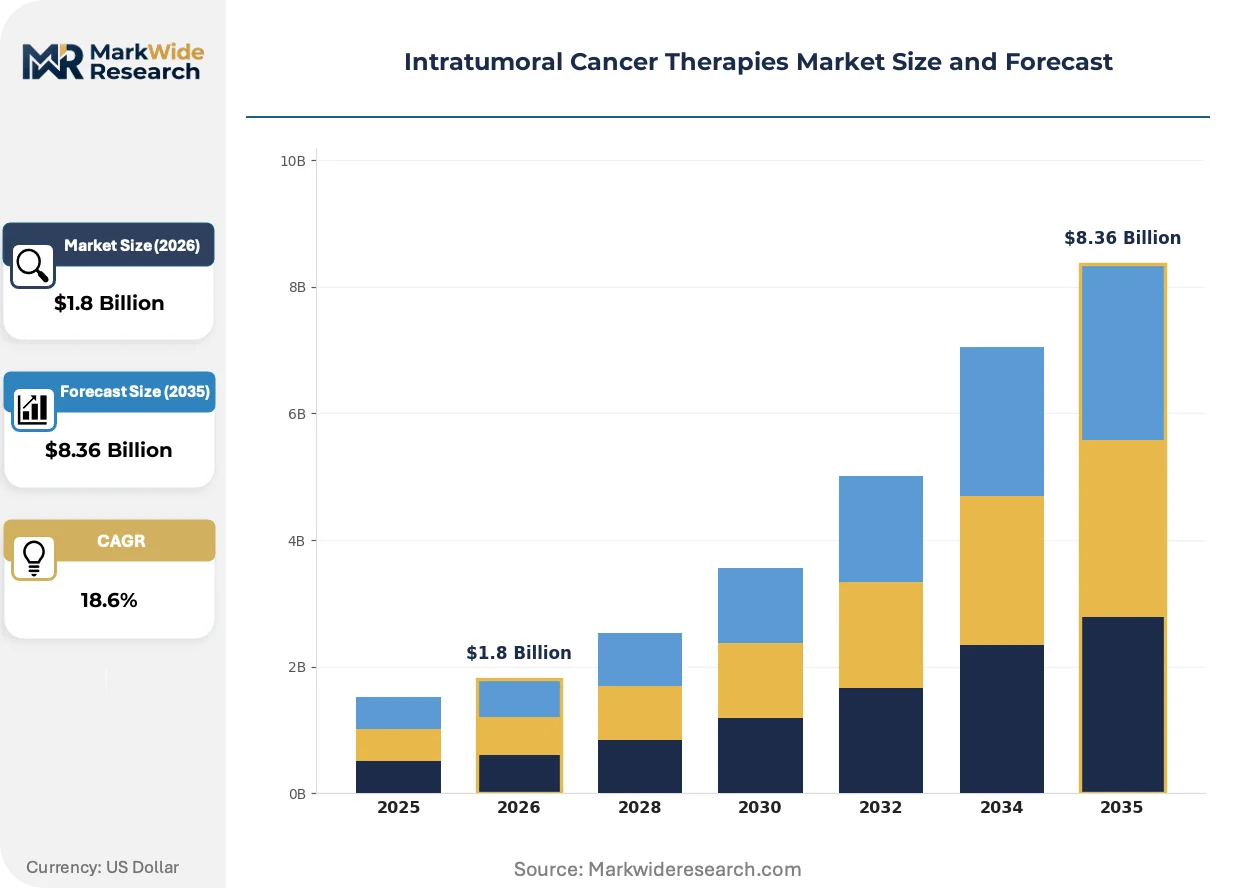
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunotherapies, Radiofrequency Ablation, Chemotherapy Agents, Targeted Therapies Administration Route: Intralesional, Intravenous, Subcutaneous, Topical End User: Hospitals, Cancer Research Centers, Academic Institutions, Private Clinics Therapy Area: Solid Tumors, Lymphomas, Melanoma, Breast Cancer |
| Companies Covered | Amgen Inc., Daiichi Sankyo, Nanobiotix, Replimune, Merck & Co., Novartis AG, AstraZeneca plc, Intensity Therapeutics, OncoSec Medical Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intratumoral Cancer Therapies Market Shifts & Advancements
Engineering platforms for intratumoral delivery are converging with systemic immuno-oncology modalities, reshaping how developers architect combination therapy paradigms and commercial positioning strategies.
Next-generation oncolytic viruses engineered with transgene payloads for localized cytokine expression are supplanting first-generation unarmed viral platforms in clinical development pipelines. Melanoma and non-melanoma skin cancer investigators are adopting these armed constructs at accelerating rates across phase I and II protocols. The shift is compressing development timelines for sponsors pursuing checkpoint inhibitor combination strategies, as transgene-armed candidates demonstrate enhanced objective response rates in early cohorts.
The European Medicines Agency's advanced therapy medicinal product classification framework is reshaping manufacturing quality requirements for viral vector-based intratumoral candidates. Sponsors must now demonstrate extended shelf-life stability and reduced replication-competent virus shedding profiles to maintain centralized marketing authorization eligibility. Small and mid-cap biotech developers with limited quality control infrastructure face disproportionate compliance burden, driving partnership structures with established viral vector manufacturers.
Academic medical centers and community oncology practices are unbundling intratumoral administration from comprehensive cancer center referral networks, establishing localized injection capabilities within satellite facilities. This channel expansion displaces traditional tertiary center concentration for accessible lesion indications. The pattern is most visible across United States Medicare Advantage networks, where capitated reimbursement models incentivize site-of-care migration toward lower-cost community settings.
Intratumoral Cancer Therapies Market Segmentation
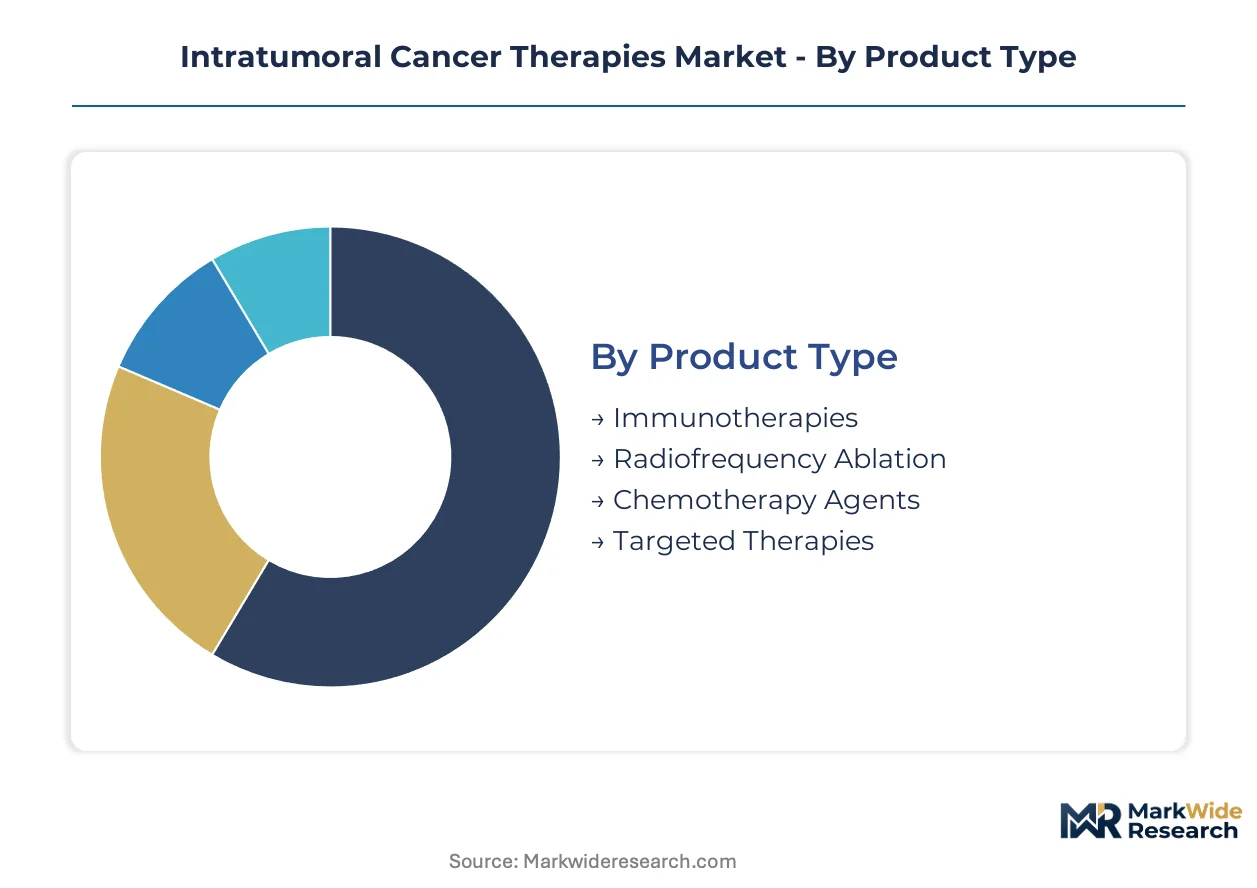
Intratumoral cancer therapies segment across multiple dimensions that determine regulatory pathways, reimbursement codes, and site-of-care economics. Product type and therapy area classifications particularly shape FDA breakthrough therapy eligibility and EMA ATMP framework applicability.
Product Type:
FDA breakthrough therapy and EMA ATMP designations apply differentially across product categories, with gene-modified oncolytic viruses facing distinct manufacturing quality requirements from small-molecule or ablative modalities.
- Immunotherapies:Oncolytic viruses and cytokine-engineered platforms induce immunogenic cell death while minimizing systemic exposure. Demand concentrates in melanoma and non-melanoma skin cancer applications where lesion accessibility enables direct injection without image guidance.
- Targeted Therapies:Bispecific antibodies and cytokine-armed modalities engineered for localized tumor microenvironment expression. Fastest-expanding segment as developers pursue checkpoint inhibitor combination strategies with reduced systemic cytokine release risk.
- Radiofrequency Ablation:Thermal energy systems designed to induce localized tumor destruction and secondary immune activation. Compact description with procedural reimbursement tied to ambulatory surgical center codes.
- Chemotherapy Agents:Intratumoral delivery of cytotoxic payloads via specialized formulation technologies. Intensity Therapeutics' DfuseRx platform exemplifies this approach for enhanced local pharmacologic action.
Immunotherapies handle the majority of throughput; targeted therapies is the fastest mover on share.
Administration Route:
Route selection determines site-of-care infrastructure requirements and prior authorization complexity across Medicare Advantage and commercial payer networks.
- Intralesional:Direct tumor injection protocols requiring minimal imaging support for accessible cutaneous and subcutaneous lesions. Community oncology adoption accelerates as satellite facilities unbundle administration from tertiary centers.
- Intravenous:Systemic delivery of intratumoral-acting agents with modified biodistribution profiles. Demand concentrates in visceral organ indications where needle-based direct injection faces anatomical constraints.
- Subcutaneous:Depot-formulation cytokines and immune modulators administered proximal to tumor sites. Expanding share in breast cancer adjuvant settings.
- Topical:Surface-applied formulations for superficial skin lesions with limited penetration depth. Restricted to early-stage non-melanoma skin cancer applications.
Intralesional administration handles the majority of throughput; subcutaneous delivery is expanding most quickly on procedural volume.
End User:
End user segmentation reflects the unbundling of intratumoral administration from comprehensive cancer center referral networks toward distributed care settings.
- Hospitals:Tertiary centers with integrated interventional radiology and surgical oncology capabilities. Retain complex visceral lesion cases requiring image-guided injection.
- Private Clinics:Community-based practices adopting localized injection capabilities for accessible melanoma and skin cancer indications. Fastest-expanding channel under capitated Medicare Advantage reimbursement.
- Cancer Research Centers:Academic medical centers conducting phase I and II combination immuno-oncology trials. Principal investigators coordinate across multiple sponsor organizations.
- Academic Institutions:University-affiliated hospitals with specialized oncolytic virology expertise. Limited to Boston, Basel, and select biotech cluster geographies.
Hospitals handle the majority of throughput; private clinics are gaining share fastest on site-of-care migration.
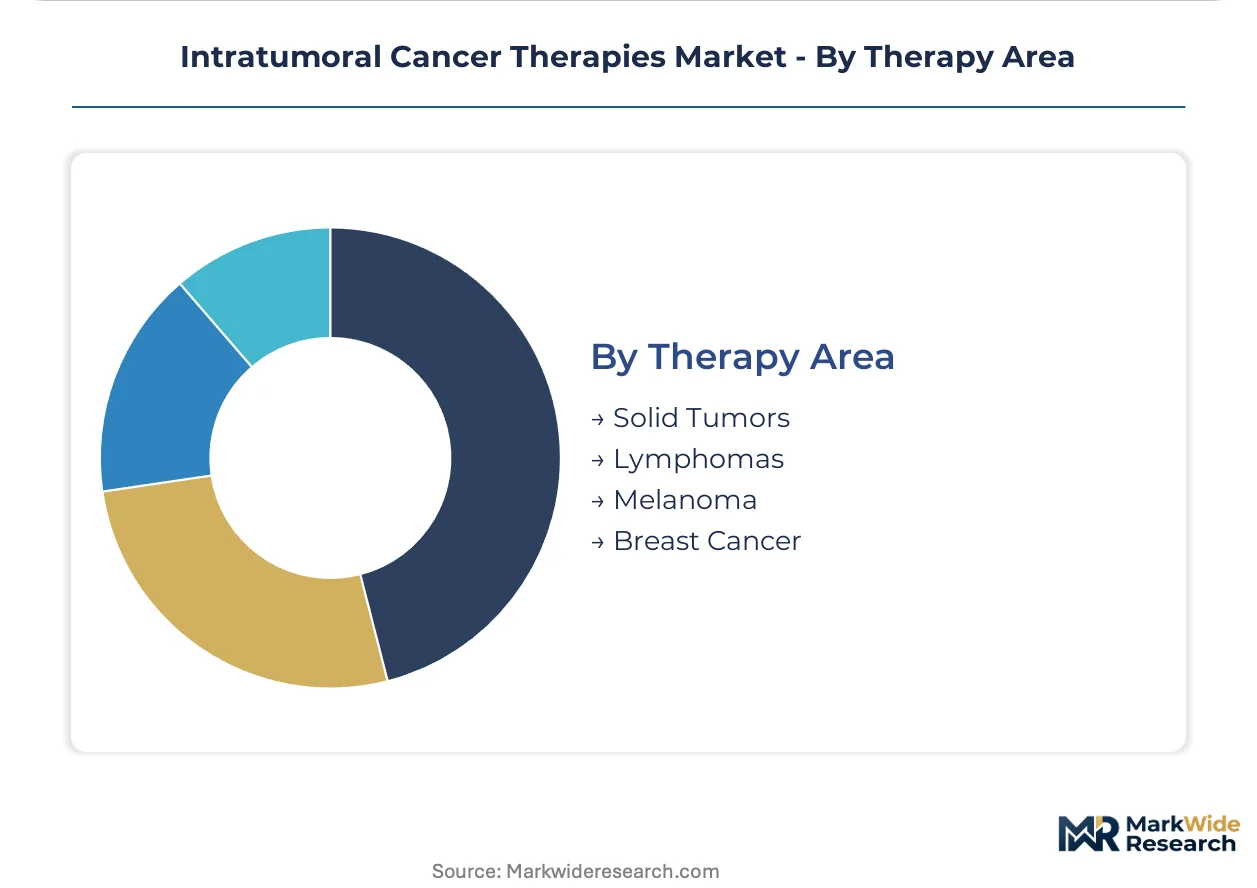
Therapy Area:
Therapy area segmentation aligns with lesion anatomical accessibility and checkpoint inhibitor combination development priorities.
- Solid Tumors:Broad category encompassing cutaneous, subcutaneous, and select visceral malignancies amenable to localized delivery. Dominant position by patient addressability.
- Melanoma:Disproportionate margin concentration due to favorable reimbursement, established T-VEC heritage, and accessible lesion anatomy. Amgen anchors commercial infrastructure here.
- Breast Cancer:Emerging application for intratumoral cytokine priming prior to neoadjuvant checkpoint therapy. Expanding clinical pipeline activity.
- Lymphomas:Limited penetration due to systemic disease biology and circulating tumor cell distribution constraints. Restricted to localized cutaneous lymphoma subtypes.
Solid tumors handle the majority of throughput; breast cancer is climbing the fastest on trial activation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough therapy designations anchor commercial development timelines in the United States, while EMA's ATMP framework governs European market access for gene-modified oncolytic viruses. Manufacturing quality requirements and reimbursement pathways diverge materially across these regulatory jurisdictions, shaping where sponsors prioritize clinical trial activation and partnership structures.
United States
Melanoma lesion accessibility drives community oncology adoption of intralesional administration protocols. Medicare Advantage capitated reimbursement models incentivize site-of-care migration toward satellite facilities outside tertiary centers. Boston and San Francisco biotech clusters concentrate oncolytic virology talent pools, with specialists relocating from traditional pharmaceutical hubs.
Germany
EMA centralized marketing authorization pathways reduce regulatory fragmentation for viral vector-based candidates across member states. Heidelberg and Munich academic medical centers coordinate multi-national combination immuno-oncology trials. CDMO capacity constraints for GMP-grade oncolytic viruses limit batch release velocity for German-sponsored expansion studies.
Switzerland
Swissmedic oversight of advanced therapy medicinal products aligns with EMA quality standards while maintaining distinct pharmacovigilance requirements. Basel anchors European viral vector engineering expertise, drawing talent from both academic institutions and multinational pharmaceutical operations. Local developers face disproportionate compliance burden for extended shelf-life stability demonstrations.
United Kingdom
MHRAs post-Brexit regulatory autonomy enables accelerated access pathways for innovative intratumoral modalities. London and Cambridge biotech clusters pursue checkpoint inhibitor combination partnerships with US-based sponsors. NHS England reimbursement negotiations create prior authorization complexity for novel injection protocols in community settings.
Japan
PMDA sakigake designation system compresses review timelines for oncolytic virus candidates addressing unmet melanoma needs. Tokyo and Osaka academic medical centers retain complex visceral lesion cases requiring image-guided injection capabilities. Domestic developers prioritize localized cytokine expression platforms over unarmed viral backbones in clinical pipelines.
Intratumoral Cancer Therapies Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with commercial infrastructure scale separating melanoma-focused incumbents from emerging platform developers. The upper tier commands established reimbursement codes and interventional oncology relationships, while mid-cap specialists compete on next-generation engineering capabilities. Two strategic archetypes dominate: heritage oncolytic virus developers leveraging T-VEC commercial legacies, and technology-convergence platforms integrating bispecific engineering with localized delivery. Competitive moves concentrate on CDMO partnership structures for viral vector manufacturing capacity and checkpoint inhibitor co-development alliances.
Within the heritage developer tier, Amgen Inc. anchors commercial infrastructure through its T-VEC melanoma positioning, while Replimune occupies a position exemplifying next-generation armed viral platform engineering. Intensity Therapeutics represents the chemotherapy payload specialization archetype through its DfuseRx technology focus. These three entities collectively illustrate how competitive positioning stratifies across viral backbone, transgene engineering, and small-molecule formulation modalities.
| Leading Market Players |
|---|
| Amgen Inc. |
| Daiichi Sankyo |
| Nanobiotix |
| Replimune |
| Merck & Co. |
| Novartis AG |
| AstraZeneca plc |
| Intensity Therapeutics |
| OncoSec Medical Incorporated |
| Others |
Supply & Pricing Matrix
GMP-grade viral vector manufacturing scale economies concentrate among European and North American CDMOs, compressing batch release velocity and anchoring price floors for oncolytic virus developers. This capacity scarcity grants established contract manufacturers asymmetric pricing power while forcing emerging biotech sponsors to accept longer lead times or premium slot reservations.
Pricing Analysis
Price spreads between US and European markets reflect divergent reimbursement coding maturity for intralesional administration procedures. Three-tier pricing structure across premium armed-viral platforms, standard unarmed backbones, and economy ablative modalities tracks with FDA breakthrough therapy designation status and manufacturing complexity. Pricing pressure stems from CMS prior authorization friction for novel injection protocols, compressing margins in community oncology settings. Hospital systems exhibit lowest price sensitivity due to bundled reimbursement, while private clinics face acute cost consciousness under capitated Medicare Advantage models.
Supply Chain Analysis
Belgium, Germany, and the United States anchor GMP-grade oncolytic virus manufacturing, with CDMOs in these jurisdictions controlling critical viral seed stock and fill-finish capacity. Production draws from specialized cell culture media, plasmid DNA templates, and replication-competent virus detection assays as core inputs. Single-source vulnerability concentrates in viral vector plasmid supply, where limited qualified suppliers create bottleneck risk for multi-cohort expansion studies. Distribution runs through cold-chain logistics networks terminating at hospital pharmacy and satellite clinic infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated health systems and Medicare Advantage networks as site-of-care unbundling concentrates procurement decisions among fewer regional purchasing entities.
For Market Incumbents: Fortify CDMO partnership structures through capacity reservations and quality co-investment agreements to defend against viral vector manufacturing scarcity. Secure exclusive checkpoint inhibitor co-development alliances before protocol design friction escalates, leveraging existing regulatory dossiers as negotiation leverage. For New Entrants and Emerging Players: Lead with non-melanoma skin cancer indications where lesion accessibility matches melanoma but commercial penetration remains limited, avoiding direct T-VEC heritage competition. Pursue EMA ATMP centralized pathway eligibility early to reduce European regulatory fragmentation cost. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform developers with validated transgene engineering capabilities and established viral backbone intellectual property. Long-term viability hinges on combination immuno-oncology trial execution rather than monotherapy differentiation. Monitor FDA guidance evolution on combination trial design as the inflection signal for partnership structure repricing.| Strategic Initiative | Industry Significance |
|---|---|
| CDMO Capacity Reservation | Locks GMP-grade viral vector slot access before competitor biotech sponsors exhaust qualified manufacturing pools. |
| Checkpoint Inhibitor Partnership | Structures co-development protocols with Bristol Myers Squibb or Merck to accelerate combination trial activation timelines. |
| EMA ATMP Pathway Filing | Secures centralized European marketing authorization eligibility, reducing notified body fragmentation across member states. |
| Community Oncology Channel Expansion | Deploys intralesional administration training to satellite clinics under Medicare Advantage capitated reimbursement models. |
| Transgene Engineering Patent Estate | Builds localized cytokine expression claims that differentiate armed viral platforms from first-generation unarmed competitors. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA breakthrough therapy designation filings, EMA ATMP classification decisions, ClinicalTrials.gov protocol registrations, and CMS Medicare reimbursement code updates. Bottom-up demand modeling triangulated against top-down epidemiology and treatment rate assumptions.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled segmentation dimensions including product type, administration route, therapy area, and regional regulatory cluster. CAGRs were derived from patient addressability curves, pricing trajectory assumptions, and penetration rate modeling for checkpoint inhibitor combination settings.
The analysis sits within stated boundaries; outcomes outside sustained FDA breakthrough therapy pathway access or EMA ATMP framework stability would require recalibration. Forecasts reflect assumptions regarding viral vector manufacturing capacity expansion, CMS coding clarity for intralesional procedures, and checkpoint inhibitor partnership velocity. Recalibration cycles align with material shifts in regulatory guidance, CDMO capacity announcements, or pivotal trial readouts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Global Metastatic Cancer Treatment Market
Oncology
Pancreatic Cancer Treatment Market
Oncology
Osteosarcoma Market
Oncology
France Radiation Oncology Market
Oncology
Paranasal Sinus Cancer Market
Oncology
Colorectal Cancer Screening Market
Oncology
Global Nasopharyngeal Cancer Market
Oncology
Single-Room Proton Therapy Systems Market
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
Liposarcoma Treatment Market
Oncology
America Cancer Immunotherapy Market
Oncology
Throat Cancer Market
Oncology
Interventional Oncology Ablation Market
Oncology
Germany Radiotherapy Market
Oncology
North America Proton Therapy Market
Oncology
Epithelial Ovarian Cancer Market