
 Precision Oncology Market | 2026-2036
Precision Oncology Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Oncology Market Intelligence
Hospital-based molecular tumor boards is rebalancing the end-user mix as health systems integrate genomic profiling into standard cancer care protocols. Thermo Fisher Scientific sustains broad reagent and instrument dominance across clinical and research channels. Illumina anchors high-throughput sequencing infrastructure in major academic medical centers. Guardant Health differentiates through liquid biopsy platforms that compete directly with tissue-based workflows.
Precision oncology encompasses molecular characterization of individual tumors to guide targeted therapeutic selection, utilizing biomarker analysis, gene sequencing, and companion diagnostic platforms that detect specific mutations, fusions, or expression signatures with clinical-grade analytical sensitivity. Gene sequencing occupies the central revenue pool as NGS panel adoption becomes standard-of-care for solid tumor profiling. Targeted therapies command premium positioning where companion diagnostics mandate specific drug eligibility. Immunotherapies represent the fastest-growing application segment as PD-L1 and tumor mutational burden testing expands into community oncology settings.
FDA companion diagnostic regulations and EMA biomarker qualification pathways shape product development timelines and label expansion strategies for manufacturers seeking market access. China's NMPA has established accelerated review channels for innovative oncology diagnostics, creating parallel regulatory gravity in Asia. Stakeholders must monitor evolving reimbursement frameworks for multi-gene panel tests across Medicare, national health systems, and private payers.
Market Dynamics
Companion diagnostic mandates from FDA and EMA are compressing drug development timelines while forcing diagnostic-therapeutic co-development partnerships that reshape vendor economics across the value chain.
Growth Catalysts
- NMPA Accelerated Review:China's streamlined oncology diagnostic pathway reduces time-to-market for multi-gene panels, pulling manufacturers toward Asia-Pacific regulatory filing strategies.
- Community Oncology Penetration:PD-L1 and TMB testing protocols now extend beyond academic centers into regional hospital networks, expanding addressable specimen volume.
- Liquid Biopsy Workflow Integration:Cell-free DNA platforms enable serial monitoring without tissue re-biopsy, creating new revenue streams in treatment response surveillance.
Market Restraints
- Reimbursement Fragmentation:Medicare coverage determination lags for multi-gene panels, forcing providers to absorb out-of-pocket costs or limit test offerings.
- Reagent Supply Concentration:Critical sequencing chemistries and flow cell manufacturing cluster in single-source suppliers, exposing labs to allocation risk.
- Variant Interpretation Bottleneck:VUS (variant of uncertain significance) rates exceed actionable findings, requiring costly expert review without clinical utility.
Strategic Opportunities
- Germany's Digital Health Act:Fast-track reimbursement for AI-augmented pathology creates entry wedge for computational diagnostic platforms.
- Minimal Residual Disease Tracking:Post-treatment surveillance applications expand testing frequency from diagnosis-only to longitudinal monitoring models.
- CRISPR-Based Companion Assays:Convergence of gene editing diagnostics with synthetic reference materials enables cheaper, faster analytical validation.
Industry Challenges
- Bioinformatics Talent Scarcity:Clinical interpretation of complex genomic datasets requires hybrid pathology-informatics expertise that outpaces training pipeline output.
- LIMS Integration Complexity:Laboratory information systems at hospital networks lack API standardization, forcing custom middleware development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Oncology Market |
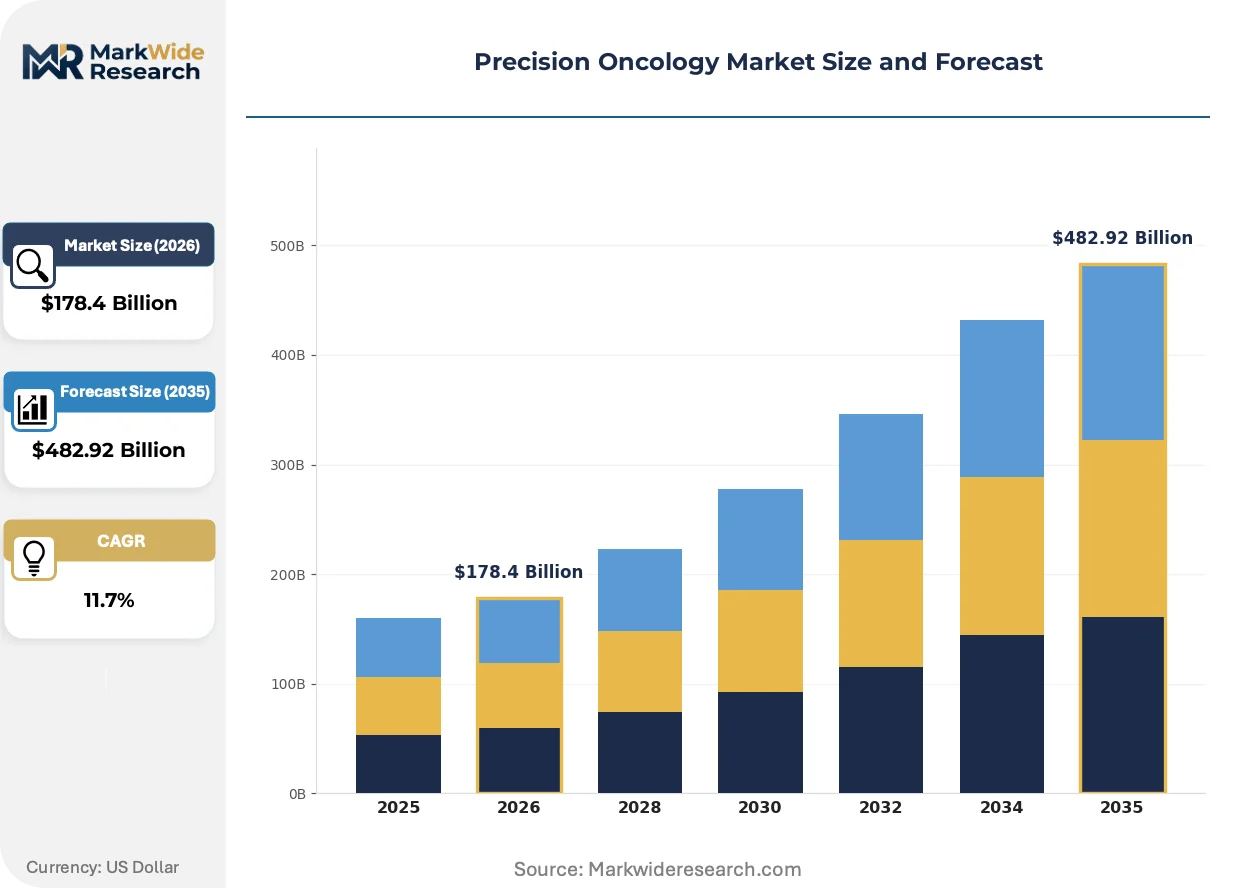
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $482.92 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biomarkers, Gene Sequencing, Targeted Therapies, Immunotherapies End User: Clinics, Research Institutions, Hospitals, Diagnostic Laboratories Technology: Next-Generation Sequencing, Microarray, PCR, CRISPR Application: Cancer Screening, Treatment Selection, Drug Development, Personalized Medicine |
| Companies Covered | Thermo Fisher Scientific Inc., Illumina Inc., F. Hoffmann-La Roche AG, QIAGEN N.V., Guardant Health, Invitae Corporation, Exact Sciences Corporation, Labcorp, Myriad Genetics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Oncology Market Strategic Shifts & Innovations
Artificial intelligence is compressing variant classification timelines while regulatory frameworks race to validate algorithmic diagnostic outputs for clinical decision-making.
Multi-omics integration is rewriting how tumor boards synthesize genomic, transcriptomic, and proteomic data into unified therapeutic recommendations. Major cancer centers in the United States now require simultaneous DNA-RNA profiling for solid tumor cases, compressing the historical sequential testing model. This convergence is enabling biomarker discovery programs that previously required separate vendor contracts and incompatible data formats.
EMA's In Vitro Diagnostic Regulation (IVDR) is recalibrating quality management requirements for CE-marked oncology assays, forcing manufacturers to rebuild clinical evidence packages. The regulation's stricter notified body oversight extends review timelines by 12-18 months for novel companion diagnostics. German and French reference laboratories are consolidating validation studies to share regulatory burden across health system networks.
Hospital procurement committees now mandate total cost-of-ownership analysis rather than capital expenditure alone, unbundling instrument placement from reagent contracts. Community oncology practices in the United States increasingly lease sequencing capacity through service agreements rather than acquiring capital equipment. This shift concentrates purchasing power within integrated delivery networks that negotiate enterprise-wide pricing across multiple sites.
Precision Oncology Market Segmentation
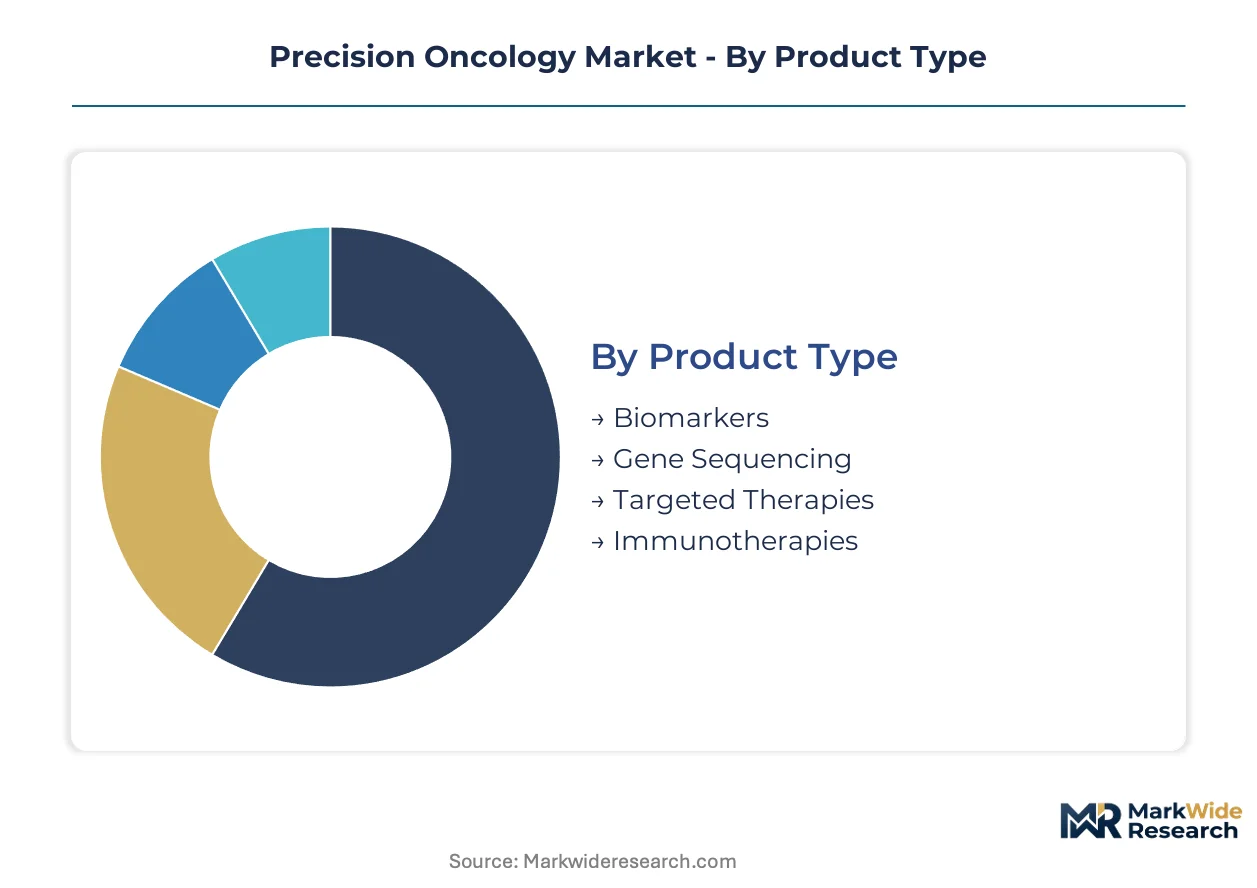
Segmentation in precision oncology reveals how value migrates across technology tiers and care settings. Product architecture, end-user sophistication, and clinical workflow integration determine pricing power and adoption velocity for vendors competing across molecular diagnostics.
Product Type:
Customization intensity spans from commoditized biomarker reagents to fully integrated therapeutic platforms requiring co-development partnerships.
- Gene Sequencing:NGS panels and whole-exome platforms deliver comprehensive mutational profiling with clinical-grade analytical sensitivity. Demand concentrates in academic medical centers across the United States and Germany, where tumor boards mandate broad molecular characterization for treatment-naive patients. Reagent contracts now bundle instrument placement with per-sample pricing, compressing margin transparency for independent laboratories.
- Targeted Therapies:Small-molecule inhibitors and monoclonal antibodies require companion diagnostic linkage for regulatory approval and reimbursement. Companion diagnostic mandates from FDA and EMA force pharmaceutical manufacturers into exclusive or preferred vendor arrangements with diagnostic platforms, reshaping competitive dynamics.
- Biomarkers:Protein expression and metabolic markers provide lower-cost entry points for community oncology settings with limited sequencing infrastructure.
- Immunotherapies:PD-1/PD-L1 inhibitors and CAR-T cell therapies drive demand for predictive biomarker testing including PD-L1 immunohistochemistry and tumor mutational burden scoring.
Leading the category by volume: Gene Sequencing. Growing fastest: Immunotherapies.
End User:
Capital intensity and reimbursement sophistication separate institutional buyers from price-sensitive outpatient operators.
- Hospitals:Integrated delivery networks command enterprise pricing through consolidated procurement of instruments, reagents, and bioinformatics support. Molecular tumor boards at major cancer centers in the United States now require simultaneous DNA-RNA profiling, expanding test menu breadth.
- Diagnostic Laboratories:Reference laboratories scale specimen throughput across health system networks, achieving cost advantages through automation and centralized variant interpretation. Germany's Digital Health Act fast-tracks reimbursement for AI-augmented pathology, creating procurement preference for computational platforms.
- Research Institutions:Academic centers prioritize discovery-oriented panels over clinical-grade assays, accepting higher variant of uncertain significance rates in exchange for broader genomic coverage.
- Clinics:Community oncology practices increasingly lease sequencing capacity through service agreements rather than acquiring capital equipment, concentrating purchasing power within integrated delivery networks.
Hospital systems dominate procurement volume. Diagnostic laboratories are expanding most quickly as health systems outsource molecular pathology.
Technology:
Maturity curves separate established platforms with reimbursement clarity from emerging modalities awaiting clinical validation.
- Next-Generation Sequencing:High-throughput sequencers anchor clinical and research workflows with standardized bioinformatics pipelines and FDA-cleared assays. China's NMPA accelerated review pathway pulls manufacturers toward Asia-Pacific regulatory filing strategies for multi-gene panels.
- PCR:Real-time and digital PCR platforms deliver rapid turnaround for single-gene hotspot testing with lower capital requirements than NGS.
- Microarray:Comparative genomic hybridization and SNP arrays retain niche applications for copy number variation detection in hematologic malignancies.
- CRISPR:Gene editing diagnostics with synthetic reference materials enable cheaper, faster analytical validation for novel companion assays, though clinical deployment remains pre-commercial.
NGS commands the largest installed base. CRISPR-based diagnostics show the steepest expansion trajectory in development pipelines.
Application:
Clinical utility and reimbursement certainty vary sharply across the care continuum from asymptomatic screening to post-treatment surveillance.
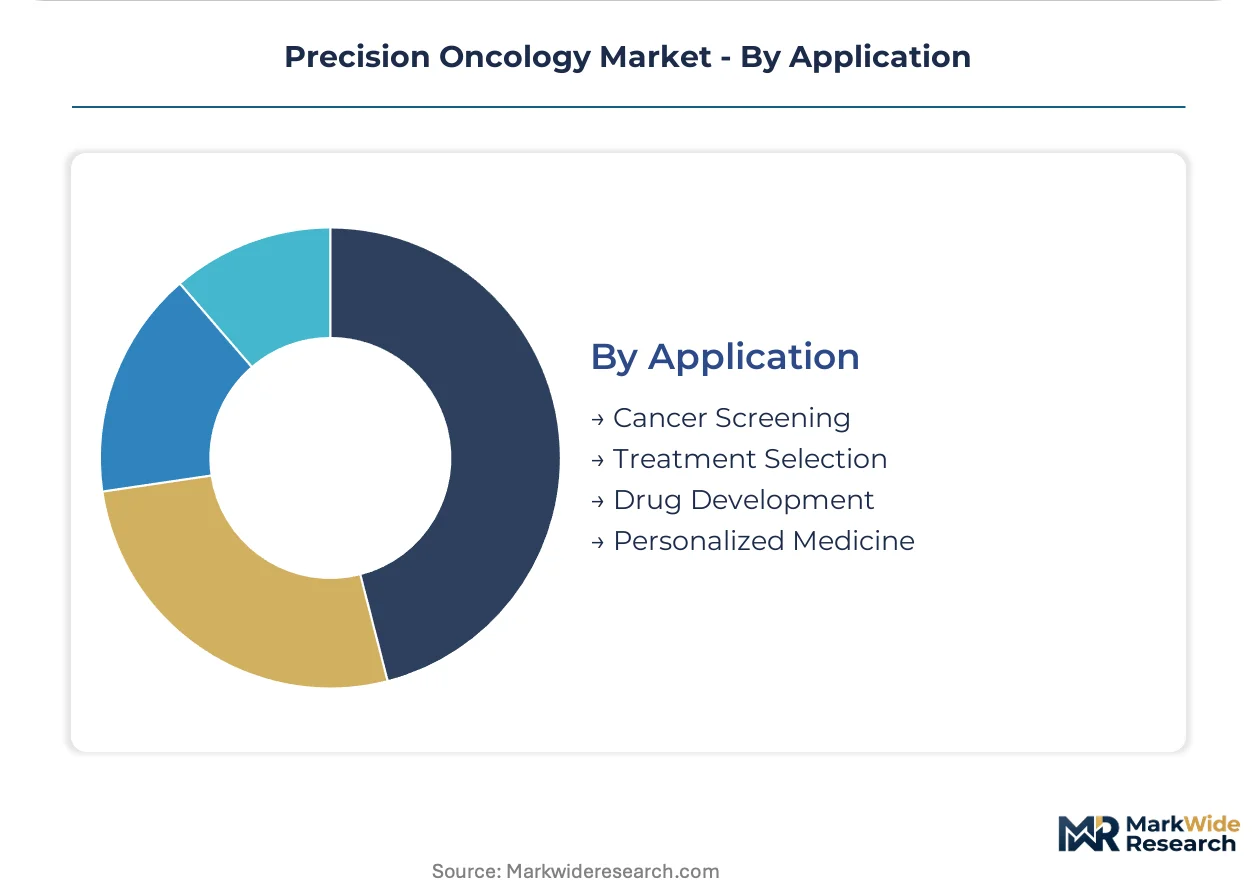
- Treatment Selection:Companion diagnostic testing to match patients with approved targeted therapies represents the most reimbursed application with established clinical utility evidence. Medicare coverage determination processes create geographic variation in access.
- Personalized Medicine:Multi-omics integration synthesizes genomic, transcriptomic, and proteomic data into unified therapeutic recommendations, requiring sophisticated bioinformatics infrastructure concentrated at major academic centers.
- Cancer Screening:Multi-cancer early detection assays using liquid biopsy face reimbursement uncertainty despite technological feasibility.
- Drug Development:Biomarker discovery and patient stratification for clinical trials generate contract research revenue with pharmaceutical sponsors.
Treatment Selection leads by commercial volume. Personalized Medicine is gaining share fastest as tumor boards mandate integrated profiling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biohub special economic zones in the United States concentrate precision oncology infrastructure through tax-advantaged R&D incentives and accelerated FDA review pathways for companion diagnostics.
United States
Hospital-based molecular tumor boards at MD Anderson and Memorial Sloan Kettering mandate simultaneous DNA-RNA profiling for treatment-naive patients. FDA breakthrough device designation compresses commercialization timelines for multi-gene panels. The Boston-Cambridge corridor anchors liquid biopsy development clusters where cell-free DNA platforms achieve analytical validation.
Germany
Integrated delivery networks in Bavaria and North Rhine-Westphalia consolidate procurement of NGS instruments through enterprise-wide reagent contracts. The Digital Health Act fast-tracks reimbursement for AI-augmented pathology diagnostics. Heidelberg and Berlin reference laboratories share validation studies to distribute IVDR compliance costs across health system networks.
China
NMPA accelerated review channels pull manufacturers toward Asia-Pacific regulatory filing strategies for oncology diagnostics. Shanghai and Beijing biotech parks host multi-gene panel developers seeking streamlined approval pathways. Hospital procurement committees in Guangdong province mandate total cost-of-ownership analysis for sequencing infrastructure.
Japan
PMDA biomarker qualification pathways align companion diagnostic development with pharmaceutical co-development timelines. Tokyo and Osaka academic medical centers prioritize clinical-grade NGS panels over discovery-oriented assays. METI funding programs support domestic sequencing chemistry manufacturing to reduce import dependency.
United Kingdom
NHS England's genomic medicine service expands tumor profiling access beyond academic centers into regional hospital networks. The MHRA operates parallel recognition pathways for FDA-cleared oncology diagnostics. London and Cambridge precision medicine clusters attract pharmaceutical diagnostic partnerships for label expansion strategies.
Precision Oncology Market Key Industry Players
Top-tier vendors anchor high-throughput sequencing infrastructure, while mid-tier specialists occupy liquid biopsy and bioinformatics niches. Thermo Fisher Scientific and Illumina command instrument placement and reagent contracts through bundled pricing models. Three strategic archetypes dominate: broad-platform conglomerates, liquid biopsy pure-plays, and reference laboratory networks. Competitive moves concentrate on diagnostic-therapeutic co-development partnerships and AI-augmented variant interpretation capabilities.
Within the broad-platform tier, Thermo Fisher Scientific Inc. and Illumina Inc. exemplify instrument-reagent bundling strategies that compress margin transparency for independent laboratories. Guardant Health occupies a distinct position as a liquid biopsy specialist competing directly with tissue-based workflows. These three entities represent the dominant competitive anchors shaping vendor economics across molecular diagnostics value chains.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Illumina Inc. |
| F. Hoffmann-La Roche AG |
| QIAGEN N.V. |
| Guardant Health |
| Invitae Corporation |
| Exact Sciences Corporation |
| Labcorp |
| Myriad Genetics Inc. |
| Others |
Cost & Logistics Intelligence
Instrument-reagent bundling bifurcation separates integrated delivery networks commanding enterprise discounts from independent laboratories absorbing opaque per-sample pricing. This divergence concentrates procurement leverage within hospital systems while fragmenting cost visibility across community oncology settings in the United States and Germany.
Pricing Analysis
Short lead-time premiums apply to FDA-cleared companion diagnostics with breakthrough device designation, while spot inventory discounts emerge for research-use-only reagents awaiting clinical validation. Subscription-based instrument placement with per-test consumable pricing dominates, with differentiation driven by NGS throughput tier and bioinformatics support bundling. Cost compression in community oncology stems from Medicare coverage determination lags for multi-gene panels. Independent reference laboratories exhibit highest price sensitivity; academic medical centers with molecular tumor boards show lowest.
Supply Chain Analysis
Single-source vulnerability sits with flow cell manufacturing concentrated in the United States and Singapore, with sequencing chemistry production anchored in California and Massachusetts. Critical inputs span semiconductor-grade substrates, fluorophore-labeled nucleotides, and polymerase enzyme preparations. Tariff exposure on Chinese-sourced optical components threatens margin stability at instrument manufacturers. Distribution runs through direct field service organizations for hospital placements and third-party logistics for reagent replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA's In Vitro Diagnostic Regulation has erected a cost-of-compliance moat that favors manufacturers with existing notified body relationships and clinical evidence portfolios, squeezing mid-tier assay developers from European market entry.
For Market Incumbents: Lock in molecular tumor board relationships through simultaneous DNA-RNA profiling contracts that embed bioinformatics interpretation services. Deepen backward integration into sequencing chemistry manufacturing to reduce allocation exposure from single-source suppliers. Threat substitution from CRISPR-based companion assays demands preemptive patent positioning around synthetic reference materials.
For New Entrants and Emerging Players: Launch via liquid biopsy service agreements targeting community oncology practices lacking capital for NGS infrastructure. White-space concentrates in post-treatment minimal residual disease surveillance, where testing frequency expands from diagnosis-only to longitudinal models. Germany's Digital Health Act fast-track reimbursement for AI-augmented pathology offers regulatory arbitrage entry.
For Investors and Strategic Acquirers: Exit pathways concentrate in diagnostic-therapeutic co-development partnerships with pharmaceutical sponsors seeking companion diagnostic platforms. Long-term viability hinges on reimbursement capture for multi-cancer early detection assays. Watch FDA Medicare coverage determination timelines for multi-gene panels as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | FDA and EMA mandates force pharmaceutical manufacturers into exclusive vendor arrangements with diagnostic platforms. |
| AI-Augmented Pathology Platform Launch | Germany's Digital Health Act fast-tracks reimbursement for computational diagnostic platforms in Bavaria and North Rhine-Westphalia. |
| Liquid Biopsy Workflow Integration | Cell-free DNA platforms enable serial monitoring without tissue re-biopsy, creating new revenue streams in treatment response surveillance. |
| Multi-Omics Data Integration Investment | Major cancer centers now require simultaneous DNA-RNA profiling, compressing historical sequential testing models. |
| IVDR Compliance Infrastructure Buildout | EMA's stricter notified body oversight extends review timelines, forcing manufacturers to rebuild clinical evidence packages. |
Research Approach
FDA 510(k) and PMA filings, EMA CE-marking databases, and ClinicalTrials.gov biomarker stratification records formed the secondary backbone. Primary interviews with molecular pathologists, hospital procurement committee chairs, companion diagnostic regulatory affairs leads, and pharmaceutical biomarker strategy executives validated assumptions. Bottom-up and top-down triangulation reconciled instrument placement data with reagent consumption patterns across academic medical centers and reference laboratories.
Bottom-up modeling anchored forecasts to NGS panel adoption curves, immunotherapy biomarker test volumes, and liquid biopsy penetration rates across the projection horizon. Segmentation dimensions spanned product architecture, end-user sophistication, technology maturity, and application clinical utility. CAGRs derived from regression analysis of historical pricing trajectories and reimbursement expansion patterns, with inputs from Medicare coverage determination timelines and NMPA accelerated review throughput.
The model assumes a particular technology adoption path; alternative pathways for CRISPR-based companion assays would alter the outlook if clinical validation timelines compress materially. Forecasts reflect assumptions on reimbursement parity between tissue and liquid biopsy modalities. Deviation in FDA breakthrough device designation velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Musculoskeletal Oncology Therapeutics Market
Oncology
Paranasal Sinus Cancer Market
Oncology
Global Nasopharyngeal Cancer Market
Oncology
Australia Cancer Treatment Market
Oncology
Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Adrenocortical Carcinoma Treatment Market
Oncology
Cancer API Market
Oncology
Paraneoplastic Syndromes Market
Oncology
Breast Cancer Brachytherapy Market
Oncology
Lung Cancer Treatment Market
Oncology
Glioblastoma Market
Oncology
Low-Grade Central Osteosarcoma Treatment Market
Oncology
Global Cancer Profiling Market
Oncology
Tumor Infiltrating Lymphocytes Market
Oncology
Metastatic Melanoma Market
Oncology
Pancreatic Cancer Therapeutics Market