
 Small Cell Lung Cancer (SCLC) Treatment Market | 2026-2036
Small Cell Lung Cancer (SCLC) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Small Cell Lung Cancer (SCLC) Treatment Market Analytics
Immuno-oncology combination protocols is rewriting treatment paradigms for extensive-stage SCLC. Bristol Myers Squibb leverages its checkpoint inhibitor portfolio to anchor first-line combination strategies. AstraZeneca plc competes through durvalumab-based regimens that extend into maintenance settings. Merck & Co., Inc differentiates via pembrolizumab programs targeting platinum-resistant populations.
Small cell lung cancer treatment encompasses systemic therapeutic interventions designed to manage aggressive neuroendocrine malignancies characterized by high proliferation rates, early metastasis, and initial chemosensitivity followed by rapid resistance. Platinum-etoposide chemotherapy remains the cytotoxic backbone, while immunotherapy agents target PD-L1 pathways to extend survival in extensive-stage disease. Immunotherapy now commands the fastest-expanding segment as PD-L1 inhibitors penetrate first-line protocols, though chemotherapy retains volume leadership due to entrenched clinical pathways and lower cost barriers. Intravenous delivery dominates administration logistics, yet subcutaneous formulations are gaining structural attention for their potential to shift care from infusion centers toward outpatient and home settings.
The FDA accelerates SCLC therapy access through breakthrough therapy and priority review designations, while the EMA's adaptive pathways pilot shapes European commercialization timelines for novel agents. Reimbursement negotiations with CMS and national health technology assessment bodies determine real-world uptake velocity across markets. Stakeholders must monitor biomarker-driven patient stratification advances that could fragment the historically homogeneous SCLC population into addressable subgroups with distinct therapeutic vulnerabilities.
Market Dynamics
Checkpoint inhibitor integration into first-line SCLC protocols is restructuring competitive positioning and reimbursement negotiations across oncology networks. The FDA's breakthrough therapy designation for PD-L1 combinations compresses trial-to-commercialization timelines, forcing incumbent chemotherapy franchises to defend volume through price positioning.
Growth Catalysts
- Biomarker stratification:Liquid biopsy platforms enable real-time genomic profiling of circulating tumor DNA, allowing clinicians to identify patients with SLFN11 mutations or other actionable alterations for targeted trial enrollment.
- Medicare reimbursement expansion:CMS coverage determinations for novel immunotherapy agents in the hospital outpatient setting reduce prior authorization friction and accelerate community oncology adoption.
- Platinum resistance protocols:Lurbinectedin and other second-line cytotoxics create salvage therapy demand where immunotherapy progression occurs, extending the treatment continuum.
Market Restraints
- Platinum supply volatility:Cisplatin and carboplatin production concentration in India creates periodic shortages that disrupt chemotherapy scheduling and force substitution to less efficacious regimens.
- Small patient populations:SCLC represents only 13-15% of lung cancer incidence, fragmenting clinical trial recruitment and limiting blockbuster economics for developers.
- Cross-resistance mechanisms:MYC amplification and NOTCH pathway alterations drive rapid relapse after initial response, compressing duration of therapy and per-patient revenue.
Strategic Opportunities
- Subcutaneous formulation development:Atezolizumab and other checkpoint inhibitors transitioning from IV to subcutaneous delivery enable home administration, reducing infusion center burden and capturing pharmacy benefit reimbursement.
- Maintenance therapy positioning:Durvalumab consolidation after chemoradiation in limited-stage disease represents an addressable gap where no immunotherapy currently holds approval.
- Japan's Sakigake designation:Priority review and early reimbursement for innovative oncology products accelerates commercialization timelines in the world's second-largest pharmaceutical market.
Industry Challenges
- Neuroendocrine pathology expertise:Community oncologists lack specialized training in SCLC's aggressive biology, leading to delayed referral patterns and suboptimal sequencing decisions.
- Clinical trial site activation:Contract negotiation and IRB approval timelines stretch 14-18 months, slowing enrollment for combination studies against evolving standard-of-care benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Cell Lung Cancer (SCLC) Treatment Market |
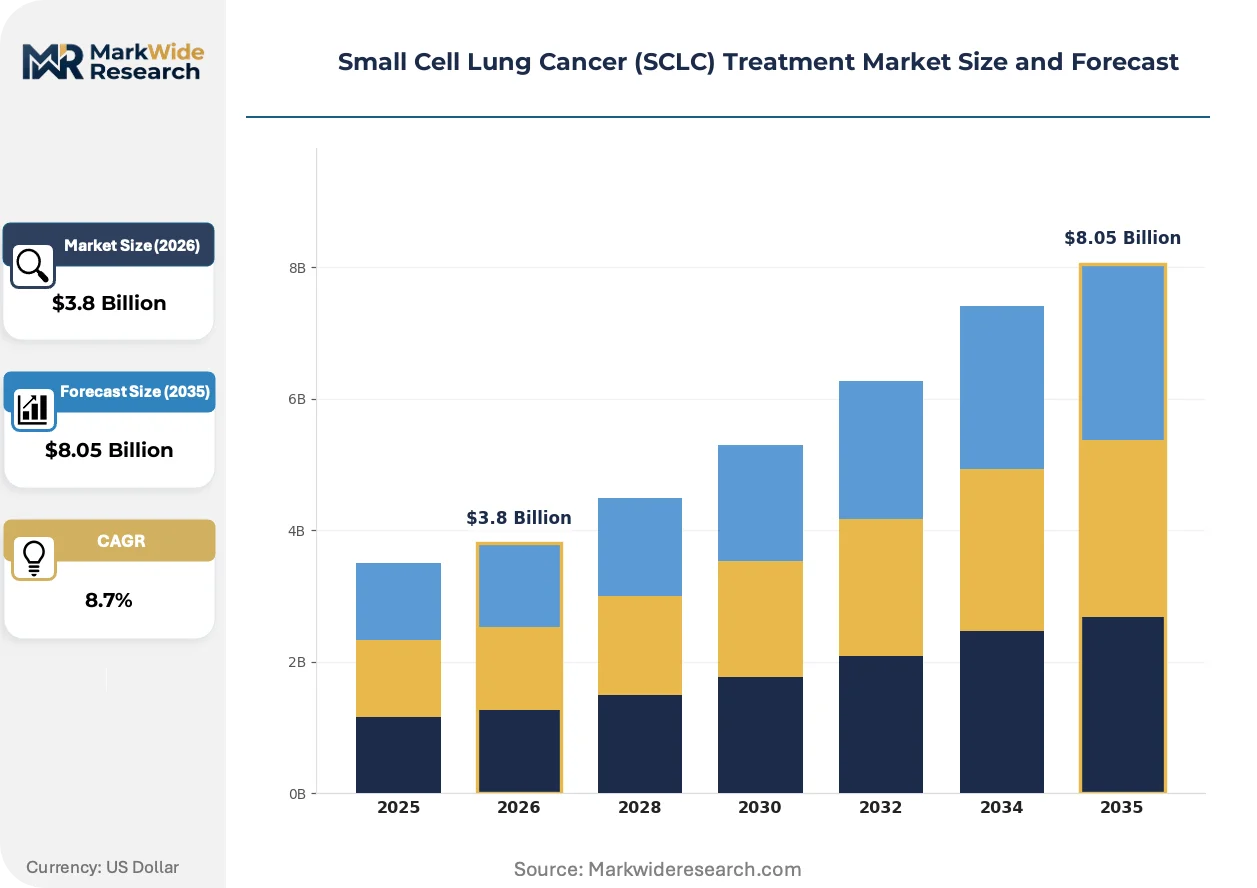
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Chemotherapy, Immunotherapy, Targeted Therapy, Radiation Therapy Therapy Area: First-Line Treatment, Second-Line Treatment, Maintenance Therapy, Palliative Care Delivery Mode: Intravenous, Oral, Subcutaneous, Inhalation End User: Hospitals, Oncology Clinics, Research Institutions, Home Care |
| Companies Covered | F. Hoffmann-La Roche Ltd, AstraZeneca plc, Merck & Co., Inc, Pfizer Inc, GSK plc, Novartis AG, Bristol Myers Squibb, Jazz Pharmaceuticals plc, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Cell Lung Cancer (SCLC) Treatment Market Evolving Landscape
Digital infrastructure is penetrating SCLC care pathways, from decentralized trial execution to algorithmic response assessment. Technology convergence across diagnostics, therapeutics, and care delivery is compressing decision cycles and redrawing competitive boundaries.
Artificial intelligence pathology platforms are digitizing tumor microenvironment characterization, enabling automated PD-L1 scoring and T-cell infiltration quantification. Community pathology labs adopt these tools to reduce inter-observer variability and accelerate biomarker turnaround. The technology is digitizing diagnostic workflows, shifting interpretive capacity from academic medical centers toward distributed networks.
The FDA's Project Optimus mandates dose-optimization studies for oncology drugs, requiring sponsors to evaluate multiple dose levels rather than defaulting to maximum tolerated dose. This regulatory shift extends Phase I timelines but improves probability of successful Phase III execution by identifying optimal efficacy-safety tradeoffs. Combination immunotherapy developers face the greatest adaptation burden, as dose-finding complexity multiplies with each added agent.
Oncology networks are consolidating procurement decisions under centralized pharmacy and therapeutics committees, displacing individual physician prescribing autonomy. Hospital systems negotiate directly with manufacturers for checkpoint inhibitor contracts, bundling SCLC indications with broader lung cancer portfolios. This concentration is most pronounced in United States integrated delivery networks, where formulary placement determines 70-80% of real-world utilization.
Small Cell Lung Cancer (SCLC) Treatment Market Segmentation
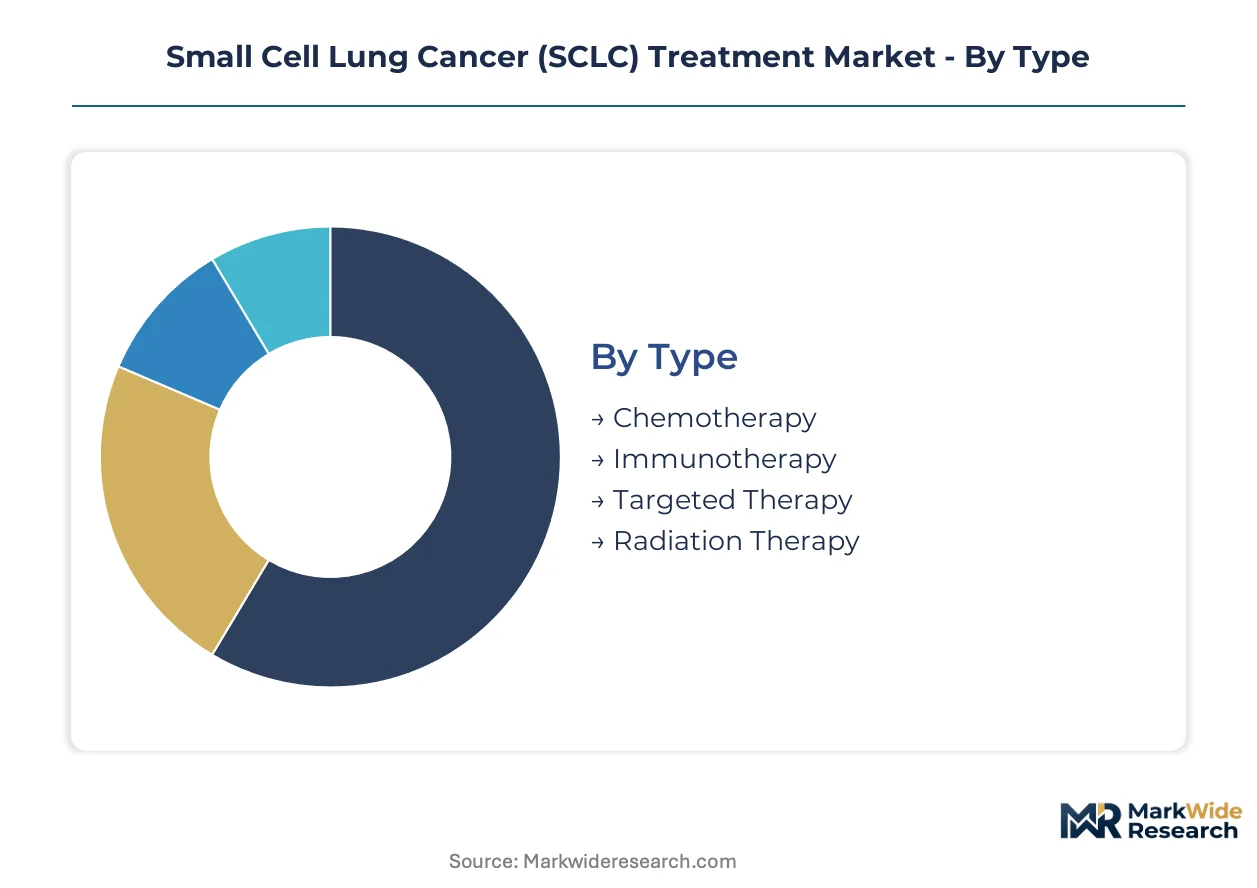
Treatment modality selection in SCLC hinges on disease staging, patient performance status, and reimbursement pathways across care settings. Segmentation reveals how immunotherapy is displacing chemotherapy volume in first-line protocols while delivery innovation reshapes site-of-care economics.
Type:
After-sales service intensity varies sharply across therapeutic categories, with immunotherapy requiring specialized infusion nursing and adverse event management that chemotherapy protocols have standardized over decades.
- Chemotherapy:Platinum-etoposide combinations remain the cytotoxic backbone with established compounding protocols and predictable toxicity profiles. Community oncology networks in the United States concentrate demand here due to entrenched Medicare reimbursement codes and lower prior authorization friction.
- Immunotherapy:PD-L1 checkpoint inhibitors target the tumor microenvironment to restore T-cell mediated cytotoxicity. Academic medical centers and specialized thoracic oncology units drive adoption where clinical trial access and biomarker testing infrastructure concentrate.
- Targeted Therapy:Agents addressing SLFN11 mutations and other actionable alterations serve niche populations in referral-heavy treatment pathways.
- Radiation Therapy:Consolidative thoracic irradiation and prophylactic cranial irradiation anchor limited-stage disease management in hospital-based departments.
Chemotherapy holds the largest share; momentum sits with immunotherapy.
Therapy Area:
Cost tier stratification separates curative-intent protocols from supportive care, with first-line immunotherapy combinations commanding premium pricing against genericized platinum agents.
- First-Line Treatment:Chemo-immunotherapy combinations now define extensive-stage SCLC standards, requiring coordinated scheduling and toxicity monitoring across multidisciplinary teams.
- Second-Line Treatment:Lurbinectedin and topotecan salvage regimens address platinum-resistant progression, with demand concentrating at tertiary referral centers managing complex relapse patterns.
- Maintenance Therapy:Durvalumab consolidation after chemoradiation in limited-stage disease represents an addressable gap where no immunotherapy currently holds regulatory approval.
- Palliative Care:Symptom-focused interventions prioritize quality-of-life endpoints and shorter treatment courses in hospice-eligible populations.
First-line treatment commands revenue concentration; maintenance therapy represents the steepest expansion trajectory.
Delivery Mode:
Volume distribution favors intravenous administration, though subcutaneous formulation development is compressing infusion center dwell times and shifting economic value toward pharmacy benefit managers.
- Intravenous:Infusion center-dependent delivery dominates checkpoint inhibitor administration, with hospital outpatient departments capturing reimbursement under Medicare's 340B program.
- Oral:Limited SCLC-relevant oral agents constrain this segment to temozolomide and selected clinical trial populations.
- Subcutaneous:Atezolizumab and emerging checkpoint inhibitors enable home administration, reducing facility fees and capturing pharmacy benefit reimbursement in United States commercial plans.
- Inhalation:Investigational locoregional delivery approaches target limited-stage disease with reduced systemic exposure.
Intravenous delivery holds the largest share; subcutaneous formulations are gaining share fastest.
End User:
Customer type determines procurement complexity, with integrated delivery networks consolidating purchasing decisions across hospital and clinic sites under centralized pharmacy and therapeutics committees.
- Hospitals:Academic medical centers and community hospital systems anchor SCLC care, managing complex inpatient toxicities and radiation integration.
- Oncology Clinics:Freestanding infusion centers expand immunotherapy capacity to capture community-based volume, competing on scheduling flexibility and parking accessibility.
- Research Institutions:NCI-designated cancer centers concentrate early-phase trial enrollment and biomarker-driven protocol access.
- Home Care:Subcutaneous administration and oral agents enable shifting treatment into home settings, supported by specialty pharmacy nursing networks.
Hospitals hold the largest share; oncology clinics are expanding capacity most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiss pharmaceutical exports supply oncology networks across Germany and France, while United States biotech firms ship immunotherapy compounds to Japanese hospital systems under priority review frameworks.
United States
Medicare reimbursement policies determine real-world uptake velocity for novel SCLC agents, with CMS coverage determinations in hospital outpatient settings reducing prior authorization friction. The FDA's breakthrough therapy designation compresses development timelines for PD-L1 combinations. NCI-designated cancer centers in Boston and Houston concentrate early-phase trial enrollment and biomarker-driven protocol access.
Germany
Hospital outpatient departments anchor SCLC care delivery, with statutory health insurance funds negotiating price-volume agreements for checkpoint inhibitors. The EMA's adaptive pathways pilot shapes commercialization timelines for novel agents entering European markets. Heidelberg and Munich oncology clusters concentrate specialized thoracic units and liquid biopsy infrastructure.
Japan
The world's second-largest pharmaceutical market accelerates commercialization through the Sakigake designation, which grants priority review and early reimbursement for innovative oncology products. PMDA consultations streamline development for combination immunotherapy protocols. Tokyo and Osaka medical centers drive adoption of subcutaneous formulation development for home administration.
United Kingdom
NICE technology appraisals determine National Health Service access to premium-priced immunotherapy combinations, creating reimbursement negotiation complexity for manufacturers. MHRA post-Brexit regulatory pathways diverge from EMA timelines for novel agent approval. London and Manchester integrated care systems consolidate procurement decisions under centralized pharmacy and therapeutics committees.
China
Domestic biopharma firms develop PD-1 inhibitors for SCLC indications, with NMPA priority review channels accelerating local competitor entry against multinational franchises. National reimbursement drug list negotiations determine volume access for imported oncology agents. Beijing and Shanghai hospital systems concentrate radiation oncology capacity and clinical trial site activation.
Small Cell Lung Cancer (SCLC) Treatment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across oncology networks, with hospital systems and integrated delivery networks consolidating procurement decisions that determine 70-80% of real-world utilization. The vendor base organizes around three strategic archetypes: checkpoint inhibitor developers anchoring first-line combination strategies, cytotoxic specialists defending platinum-etoposide volume through price positioning, and emerging subcutaneous formulation developers shifting care from infusion centers toward outpatient settings. Dominant competitive moves include strategic partnerships for biomarker co-development and geographic expansion through Japan's Sakigake and China's NMPA priority review channels.
Among Swiss and UK-based pharmaceutical developers, F. Hoffmann-La Roche Ltd and AstraZeneca plc occupy positions within the immuno-oncology combination tier, while Bristol Myers Squibb represents the checkpoint inhibitor archetype with entrenched first-line positioning. These firms exemplify how regulatory strategy and reimbursement negotiation capabilities determine competitive outcomes in concentrated oncology markets.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| AstraZeneca plc |
| Merck & Co., Inc |
| Pfizer Inc |
| GSK plc |
| Novartis AG |
| Bristol Myers Squibb |
| Jazz Pharmaceuticals plc |
| Johnson & Johnson |
| Others |
Value Network & Pricing Analysis
Infusion center capacity utilization rates in the United States sit at 85-90% across major metropolitan oncology networks, compressing scheduling flexibility for platinum-etoposide regimens and forcing hospitals to prioritize higher-margin immunotherapy slots. This utilization squeeze simultaneously elevates bargaining leverage for checkpoint inhibitor manufacturers while pressuring community oncology practices to consolidate procurement under centralized pharmacy and therapeutics committees.
Pricing Analysis
Cost-plus contracts with platinum price indexation anchor chemotherapy procurement agreements between hospital systems and generic injectable suppliers. Three-tier pricing structure across branded checkpoint inhibitors, biosimilar entrants, and commodity cytotoxics reflects differentiation by FDA breakthrough therapy status and biomarker co-development bundling. Pricing pressure stems from Medicare's hospital outpatient prospective payment system compressing margins on infusion-administered agents. Community oncology clinics exhibit highest price sensitivity due to 340B program eligibility gaps, while academic medical centers prioritize clinical trial access over unit cost.
Supply Chain Analysis
Extended payment terms of 90-120 days and supply-chain finance facilities have become standard between oncology distributors and hospital procurement departments, stretching working capital requirements for checkpoint inhibitor inventory. Active pharmaceutical ingredient production concentrates in India and China for platinum salts, with fill-finish capacity clustering in Switzerland and the United States for biologic immunotherapies. Single-source vulnerability pervades the cisplatin supply base following manufacturing consolidation. Cold chain distribution runs through specialty pharmacy networks with temperature-controlled logistics partners managing checkpoint inhibitor last-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SCLC treatment market constitutes a defensive-moat opportunity anchored by regulatory entrenchment: FDA breakthrough therapy designations and CMS national coverage determinations create multi-year exclusivity windows that compound competitive advantage through real-world evidence generation.
For Market Incumbents: Pre-empt biosimilar erosion by securing exclusive formulary placement through outcomes-based contracts with integrated delivery networks. Deepen vertical integration into companion diagnostic development to capture biomarker-driven patient stratification. Threaten emerging subcutaneous formulation developers through accelerated IV-to-SC transition programs.
For New Entrants and Emerging Players: Pursue maintenance therapy positioning in limited-stage SCLC where durvalumab consolidation lacks regulatory approval, representing the most penetrable white-space segment. Target Japan's Sakigake designation pathway to compress commercialization timelines. Deploy direct-to-oncologist digital education platforms to circumvent entrenched hospital formulary committees.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subcutaneous formulation developers with pharmacy benefit manager contracts, offering superior cash flow predictability versus hospital-dependent IV franchises. Acquisition target archetype: mid-cap biotechs with Phase II checkpoint inhibitor data in platinum-resistant populations. Watch for FDA Project Optimus dose-optimization mandates as inflection indicator for development timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Shifts care from infusion centers to home settings, capturing pharmacy benefit reimbursement under United States commercial plans. |
| Biomarker Co-Development Partnership | Liquid biopsy platforms enable SLFN11 mutation screening, fragmenting the homogeneous SCLC population into addressable subgroups. |
| Japan Sakigake Designation Pursuit | Priority review and early reimbursement accelerate commercialization timelines in the world's second-largest pharmaceutical market. |
| Maintenance Therapy Regulatory Filing | Durvalumab consolidation after chemoradiation addresses an unapproved indication gap in limited-stage disease management. |
| Integrated Delivery Network Contracting | Centralized pharmacy and therapeutics committees determine 70-80% of real-world checkpoint inhibitor utilization across United States oncology networks. |
Research Methodology
The analysis maps chemotherapy backbones, PD-L1 checkpoint inhibitors, targeted therapy agents, and radiation protocols, each validated through formulary directors at NCI-designated cancer centers, hospital procurement managers, payer access specialists, and regulatory affairs leads at immuno-oncology developers. Primary interviews with these stakeholders combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare claims databases. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing across the analysis window.
Assumptions held fixed include current FDA breakthrough therapy designation criteria, existing CMS reimbursement codes for hospital outpatient immunotherapy administration, and stable platinum salt supply from Indian API manufacturers. Variables included immunotherapy penetration rates by disease stage, subcutaneous formulation adoption curves, and biomarker testing infrastructure expansion. Segmentation dimensions encompassed treatment modality, therapy line, delivery mode, and end-user facility type. CAGRs derived from epidemiological incidence projections cross-referenced with label expansion timelines and pricing elasticity estimates for Medicare-covered populations.
Sensitivities concentrate around platinum supply disruption, accelerated biosimilar entry, and biomarker-driven protocol fragmentation that could compress duration of therapy. Forecasts reflect these documented assumptions. Macroeconomic shifts in healthcare reimbursement, regulatory pathway modifications, or technological breakthroughs in targeted therapy would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Metastatic Breast Cancer Market
Oncology
Global Skin Cancer Diagnostics and Therapeutics Market
Oncology
Asia-Pacific Cancer Biomarkers Market
Oncology
Tumor Lysis Syndrome Treatment Market
Oncology
Precision Oncology Market
Oncology
Kinase Inhibitors for Cancer Treatment Market
Oncology
Asia-Pacific Tumor Ablation Market
Oncology
North America Veterinary Oncology Market
Oncology
Glottic Cancer Treatment Market
Oncology
Tumor Embolization Market
Oncology
North America Tumor Ablation Market
Oncology
Lung Cancer Treatment Market
Oncology
Outpatient Oncology Infusion Market
Oncology
Global Particle Therapy Market
Oncology
Cancer Cachexia Market
Oncology
Esophageal Cancer Market