
 Global Nasopharyngeal Cancer Market | 2026-2036
Global Nasopharyngeal Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nasopharyngeal Cancer Market Foresight
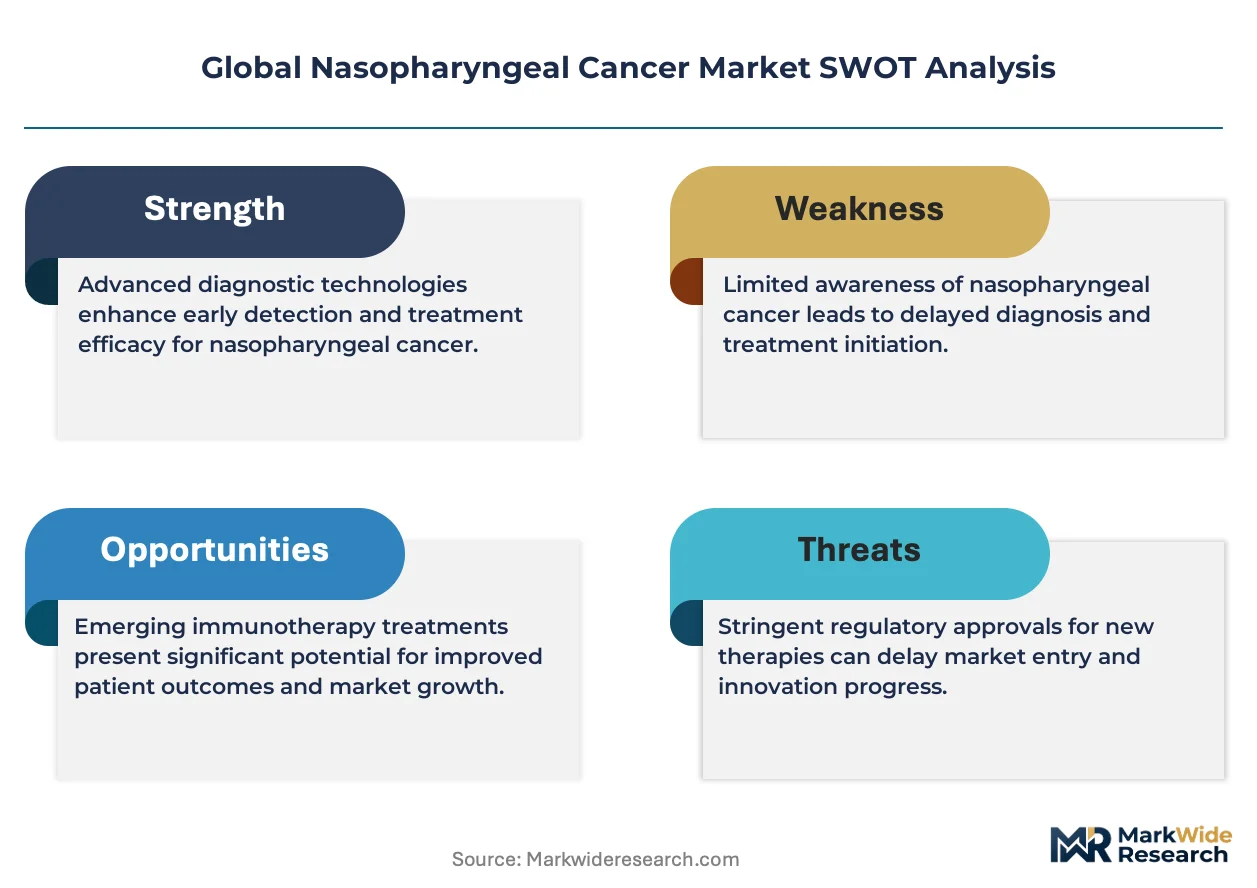
Hospital procurement of nasopharyngeal cancer therapeutics is narrowing toward integrated oncology networks with centralized formulary control. Merck & Co. leverages its pembrolizumab franchise to anchor immunotherapy positioning across major academic medical centers. Bristol Myers Squibb competes through nivolumab combinations in recurrent disease settings, while BeiGene Ltd. specializes in regional access across Chinese-speaking markets with tislelizumab.
Nasopharyngeal carcinoma originates in the epithelial lining of the nasopharynx, typically presenting as non-keratinizing squamous cell carcinoma with strong Epstein-Barr virus association, and requires multimodal treatment combining radiation with systemic therapy due to anatomical constraints and radiosensitivity. Immunotherapy now leads growth trajectories as PD-1 inhibitors displace platinum-based regimens in first-line metastatic settings, while targeted therapy occupies narrower EGFR-driven niches where cetuximab retains relevance. Radiation therapy sustains foundational demand across all therapy areas, though margin pools increasingly concentrate in combination protocols that integrate concurrent chemoradiation with adjuvant immunotherapy.
FDA oncology center standards, EMA's MDR pathway for companion diagnostics, and China's NMPA accelerated approval framework collectively shape trial design requirements and market access timelines for novel agents. These regulatory structures elevate biomarker validation burdens while compressing development cycles for breakthrough-designated therapies. Stakeholders must monitor evolving reimbursement thresholds for combination regimens as health technology assessment bodies in Germany, the United Kingdom, and South Korea recalibrate value frameworks for immuno-oncology integration.
Market Dynamics
PD-1 checkpoint inhibitor approvals are compressing development timelines and redirecting hospital formulary budgets away from platinum-based chemotherapy protocols across major oncology networks.
Growth Catalysts
- Accelerated Approval Pathways:China's NMPA breakthrough therapy designation and FDA's oncology center standards compress trial-to-market cycles for novel immuno-oncology agents.
- Radiotherapy Infrastructure Expansion:Specialty clinics in Guangdong province and Hong Kong SAR are adding linear accelerator capacity to address rising patient volumes from EBV-endemic populations.
- Biomarker Validation:Companion diagnostic requirements under EMA's MDR pathway elevate PD-L1 testing penetration and expand addressable patient pools for targeted immunotherapy.
Market Restraints
- Platinum Supply Concentration:Cisplatin and carboplatin production concentrates in Chinese and Indian API manufacturers, exposing procurement to export restriction volatility.
- Reimbursement Compression:Germany's G-BA and NICE in the United Kingdom impose outcome-based value thresholds that delay combination regimen coverage decisions.
- Technical Limitation:Blood-brain barrier penetration constraints restrict systemic therapy efficacy for patients with base-of-skull recurrence.
Strategic Opportunities
- Underpenetrated Geography:Indonesia and Vietnam present white-space expansion potential where nasopharyngeal carcinoma incidence exceeds 10 per 100,000 but immunotherapy access remains limited to cash-pay segments.
- Technology Convergence:Integration of AI-based radiotherapy planning with concurrent chemoradiation protocols enables margin capture in precision-delivery service contracts.
- Regulatory Tailwind:South Korea's MFDS expanded access program for rare cancers streamlines import pathways for investigational PD-1 inhibitors ahead of formal approval.
Industry Challenges
- Radiation Oncology Talent Gap:Training programs in Malaysia and Thailand cannot match installation rates for new linear accelerators, creating treatment bottlenecks.
- Companion Diagnostic Integration:Multiplex EBV DNA testing and PD-L1 assay standardization delays fragment clinical trial eligibility criteria across academic medical centers.
- Legacy System Interoperability:Electronic health record platforms in Hong Kong public hospitals require custom API development to support real-time biomarker-result routing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nasopharyngeal Cancer Market |
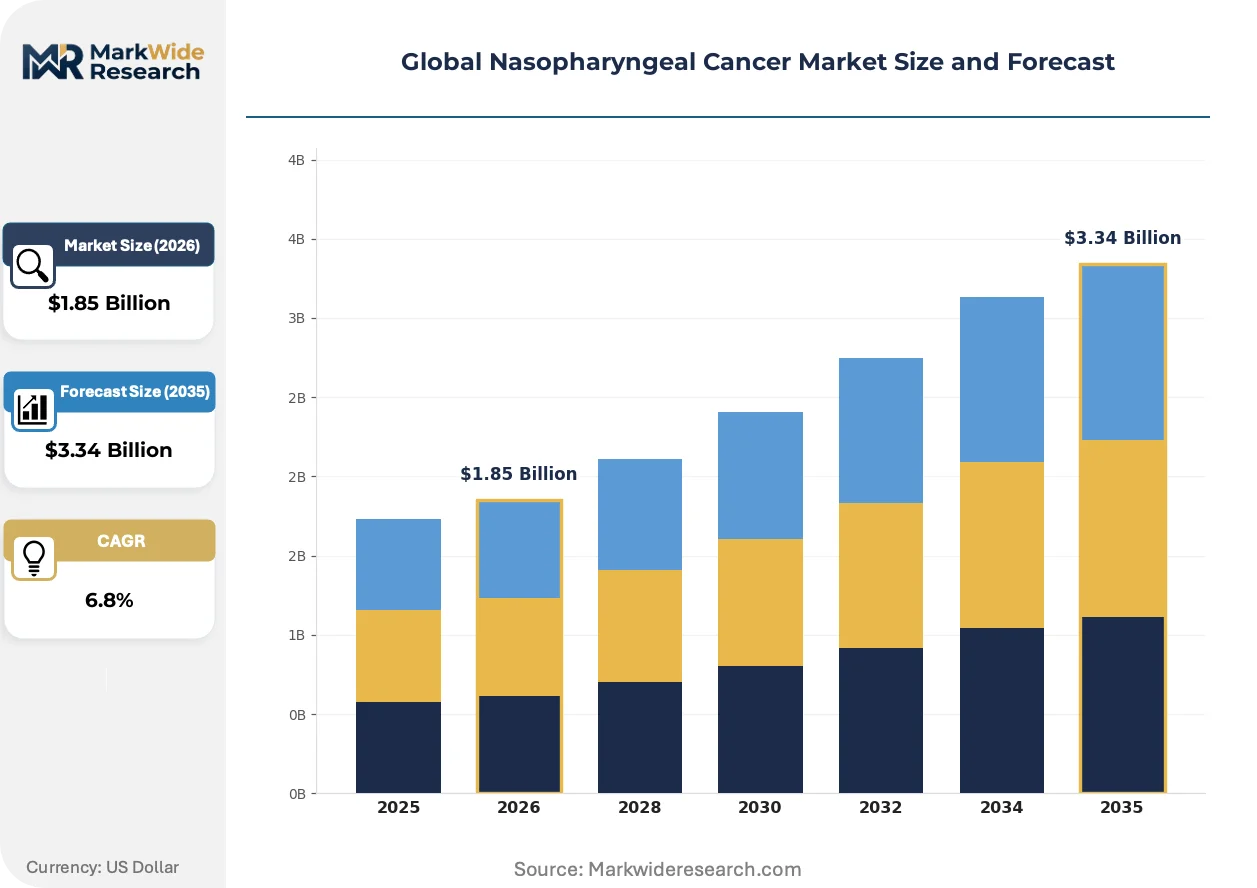
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiation Therapy, Chemotherapy, Immunotherapy, Targeted Therapy, Surgery Therapy Area: Early Stage, Locally Advanced, Metastatic, Recurrent End User: Hospitals, Specialty Clinics, Cancer Research Centers, Outpatient Facilities Delivery Mode: Intravenous, Oral, Inhalation, Subcutaneous, Intramuscular |
| Companies Covered | Merck & Co., Inc., Bristol Myers Squibb, Pfizer Inc., Roche, Novartis AG, Sanofi, Eli Lilly and Company, AstraZeneca, BeiGene Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nasopharyngeal Cancer Market Shifts & Advancements
Immunotherapy protocol standardization is compressing the window between diagnosis and systemic therapy initiation, while radiotherapy precision technologies reshape locoregional control benchmarks.
Proton beam therapy systems are rendering obsolete conventional photon-based approaches for skull-base tumors requiring optic nerve sparing. Academic medical centers in Singapore and the United States are prioritizing proton center investments despite higher capital requirements. This shift is rendering obsolete older cobalt-60 units and compressing reimbursement negotiations around dose-escalation protocols.
EMA's MDR companion diagnostic framework now mandates parallel validation of biomarker assays with novel therapeutic submissions. Manufacturers must submit technical documentation for EBV DNA quantification and PD-L1 scoring algorithms alongside drug applications. European reference laboratories are consolidating validation contracts to meet compressed timelines, favoring integrated diagnostic-therapeutic partnerships over standalone testing vendors.
Hospital procurement committees are consolidating oncology drug purchasing through centralized formulary control at integrated delivery network level. Academic medical centers in southern China now require protocol committee approval for any off-label immunotherapy use, replacing individual physician discretion. This concentration is most visible in Guangzhou and Shenzhen, where three health systems control access for over 60 percent of insured patients.
Global Nasopharyngeal Cancer Market Segmentation
Treatment modality selection in nasopharyngeal carcinoma hinges on EBV biomarker status, disease staging, and radiotherapy access geography. Segmentation reveals how immunotherapy is displacing legacy protocols while infrastructure constraints reshape patient flow across delivery settings.
Product Type:
Mature modalities anchor volume while emerging biologics capture margin expansion in academic medical centers.
- Immunotherapy:PD-1 checkpoint inhibitors demonstrate superior progression-free survival in first-line metastatic settings versus platinum doublets. Demand concentrates at Guangzhou Cancer Center and Hong Kong Queen Mary Hospital where EBV-endemic populations drive trial recruitment and formulary prioritization.
- Radiation Therapy:Intensity-modulated and proton beam systems deliver precision dose escalation to skull-base tumors with optic nerve sparing requirements. Singapore National Cancer Centre and University of Texas MD Anderson are retiring cobalt-60 units in favor of proton center investments despite capital intensity.
- Chemotherapy:Cisplatin-based concurrent chemoradiation maintains foundational role in locally advanced disease despite immunotherapy encroachment.
- Targeted Therapy:EGFR inhibitors occupy narrow niches in cetuximab-responsive subpopulations with biomarker-confirmed overexpression.
- Surgery:Salvage nasopharyngectomy applies strictly to select recurrent cases with localized failure after primary radiotherapy.
Immunotherapy handles the majority of new patient throughput in metastatic settings; radiation therapy remains the fastest mover on infrastructure investment share.
Therapy Area:
Volume distribution follows disease incidence curves while reimbursement complexity escalates with progression stage.
- Locally Advanced:Concurrent chemoradiation with adjuvant immunotherapy represents the standard-of-care evolution across NCCN guidelines. Treatment concentrates at integrated oncology networks in southern China where linear accelerator density exceeds 4 units per million population.
- Metastatic:First-line PD-1 inhibitor combinations are displacing platinum-gemcitabine regimens in FDA and NMPA-approved protocols. Patient flow redirects toward centers with real-time EBV DNA monitoring capability.
- Early Stage:Definitive radiotherapy alone suffices for T1-T2N0 disease with excellent locoregional control rates.
- Recurrent:Re-irradiation and salvage systemic therapy face blood-brain barrier penetration constraints for base-of-skull failures.
Locally advanced disease handles the majority of treatment episodes; metastatic settings are climbing the fastest on protocol innovation share.
End User:
Procurement authority centralization is reshaping access hierarchies across institutional tiers.
- Hospitals:Academic medical centers with centralized formulary control govern immunotherapy access for insured populations exceeding 60 percent in concentrated health systems.
- Specialty Clinics:Radiotherapy-focused facilities in Guangdong province and Hong Kong SAR are expanding linear accelerator capacity to address EBV-endemic patient volumes.
- Cancer Research Centers:Phase I-II trial sites attract investigator-initiated studies for novel PD-1 combinations.
- Outpatient Facilities:Subcutaneous immunotherapy administration enables community-based delivery for stable metastatic patients.
Hospitals handle the majority of complex case throughput; specialty clinics are expanding most quickly on capacity addition share.
Delivery Mode:
Route selection balances pharmacokinetic requirements with patient convenience and reimbursement site-of-care rules.
- Intravenous:Pembrolizumab and nivolumab infusions require oncology-certified nursing infrastructure available primarily at hospital-based infusion centers.
- Oral:Tyrosine kinase inhibitors in targeted therapy enable home-based administration with periodic monitoring.
- Subcutaneous:Emerging formulations reduce infusion chair time and shift administration toward outpatient settings.
- Inhalation:Investigational intranasal delivery routes target locoregional disease with reduced systemic exposure.
- Intramuscular:Supportive care agents including growth factors utilize this route for neutropenia prophylaxis.
Intravenous delivery handles the majority of immunotherapy throughput; subcutaneous formulations are gaining share fastest on convenience-driven protocol adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oncology center standards and China's NMPA breakthrough therapy designation compress trial-to-market cycles for novel immuno-oncology agents, while EMA's MDR pathway elevates biomarker validation burdens across European reference laboratories.
United States
Academic medical centers in Houston and New York anchor proton beam therapy investments despite capital intensity, with MD Anderson retiring cobalt-60 units. FDA's oncology center standards govern PD-1 inhibitor approval timelines. The Texas Medical Center concentrates Phase I-II trial recruitment for novel checkpoint combinations.
China
Guangdong province and Hong Kong SAR drive the world's highest nasopharyngeal carcinoma incidence rates from EBV-endemic populations. NMPA accelerated approval frameworks streamline tislelizumab market access. Guangzhou Cancer Center governs immunotherapy formulary control for over 60 percent of insured patients across three concentrated health systems.
Singapore
National Cancer Centre prioritizes proton center investments for skull-base tumors requiring optic nerve sparing. The national pharmaceutical regulator aligns with EMA MDR standards for companion diagnostic validation. Biomedical research clusters in one-north attract investigator-initiated studies for PD-1 combinations.
South Korea
MFDS expanded access programs for rare cancers streamline import pathways for investigational checkpoint inhibitors. Seoul National University Hospital anchors real-time EBV DNA monitoring capability for metastatic patient triage. The capital region concentrates linear accelerator density exceeding national averages.
Germany
G-BA outcome-based value thresholds delay combination regimen coverage decisions for immuno-oncology integration. Heidelberg University Hospital anchors radiotherapy precision research. The country's national pharmaceutical regulator enforces parallel biomarker assay validation with novel therapeutic submissions.
Global Nasopharyngeal Cancer Market Competitive Landscape
On the supply side, the industry is consolidating around integrated oncology networks with centralized formulary control, compressing procurement diversity into tiered vendor relationships. Three strategic archetypes dominate: multinational pharmaceutical conglomerates with checkpoint inhibitor franchises, regional biotech specialists securing accelerated approval pathways, and radiotherapy equipment manufacturers capturing precision-delivery service contracts. Competitive moves concentrate on strategic partnerships for companion diagnostic co-development and geographic licensing arrangements for emerging market access.
Among multinational developers, Merck & Co., Inc. and Bristol Myers Squibb occupy positions anchoring immunotherapy positioning across major academic medical centers, while BeiGene Ltd. represents the regional specialist archetype securing NMPA approvals for Chinese-speaking market penetration. These three entities exemplify how checkpoint inhibitor developers concentrate procurement influence through formulary committee relationships rather than individual physician discretion.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Bristol Myers Squibb |
| Pfizer Inc. |
| Roche |
| Novartis AG |
| Sanofi |
| Eli Lilly and Company |
| AstraZeneca |
| BeiGene Ltd. |
| Others |
Supply & Pricing Matrix
Chinese and Indian API manufacturers concentrate platinum-based chemotherapy production, anchoring cost structures for cisplatin and carboplatin while immunotherapy biologics capture premium margin pools at academic medical centers. This upstream concentration creates divergent pricing dynamics between commodity chemotherapy agents and patented checkpoint inhibitors.
Pricing Analysis
Volume-discount tiering structures separate branded PD-1 inhibitors from biosimilar-ready chemotherapy agents, with pembrolizumab and nivolumab commanding premium positioning through formulary exclusivity contracts. Price differentiation rests on biomarker validation requirements and infusion infrastructure certification, with Germany's G-BA and NICE imposing outcome-based value thresholds that compress combination regimen margins. Cost compression in platinum-based protocols intensifies as immunotherapy displaces first-line metastatic standards, while insured patient segments at integrated oncology networks show lowest price sensitivity compared to cash-pay populations in Southeast Asian markets.
Supply Chain Analysis
Upstream feedstock dependencies for platinum salts concentrate manufacturing in Jiangsu and Zhejiang provinces, with carboplatin API production drawing from Chinese chemical intermediates and Indian formulation capabilities. Active pharmaceutical ingredients for immunotherapy biologics hinge on mammalian cell culture media sourced from US and European specialty chemical suppliers. Single-source vulnerability permeates platinum supply channels due to export restriction volatility from concentrated Chinese manufacturers. Distribution runs through hospital-based specialty pharmacies and integrated oncology networks with centralized formulary control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Immunotherapy protocol standardization represents an early-cycle expansion story, with PD-1 checkpoint inhibitors redirecting treatment pathways and opening white-space penetration in historically chemotherapy-dependent markets.
For Market Incumbents: Pre-empt formulary displacement by securing companion diagnostic co-development partnerships with reference laboratories ahead of EMA MDR validation deadlines. Anchor proton beam therapy service contracts at academic medical centers before radiotherapy precision investments mature, as cobalt-60 unit retirements accelerate across Singapore and Hong Kong SAR. Vertical integration into real-time EBV DNA monitoring capabilities defends against emerging biotech specialists capturing metastatic patient triage. For New Entrants and Emerging Players: Indonesia and Vietnam present geographic underpenetration where nasopharyngeal carcinoma incidence exceeds 10 per 100,000 yet immunotherapy access remains limited to cash-pay segments. Target specialty clinic partnerships in Guangdong province for radiotherapy capacity expansion, leveraging linear accelerator installation rates that outpace radiation oncology training programs. Pursue licensing arrangements with established distributors for NMPA-approved agents seeking regional market access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed radiotherapy equipment manufacturers holding precision-delivery service contracts at proton centers. Long-term viability frames around immuno-oncology integration timelines and reimbursement pathway maturation across European health technology assessment bodies. Acquisition targets include regional biotech specialists with accelerated approval designations and companion diagnostic platforms. Watch FDA oncology center breakthrough therapy designations as inflection indicators for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Parallel EBV DNA and PD-L1 assay validation satisfies EMA MDR submission requirements. |
| Proton Center Service Contracting | Precision-delivery partnerships at MD Anderson and Singapore National Cancer Centre capture margin pools. |
| NMPA Accelerated Approval Pathway | Breakthrough therapy designation compresses trial-to-market cycles for checkpoint inhibitors. |
| Specialty Clinic Capacity Expansion | Linear accelerator installations in Guangdong province address EBV-endemic patient volume growth. |
| Integrated Formulary Control | Centralized procurement at Guangzhou health systems governs immunotherapy access for insured populations. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads, formulary directors at academic medical centers, and hospital procurement managers anchored the qualitative base. Secondary validation drew from FDA oncology center filings, NMPA breakthrough therapy designations, ClinicalTrials.gov recruitment patterns, and hospital procurement databases. Bottom-up patient flow modeling and top-down health system budget allocation analysis enabled triangulation across data sources.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation dimensions spanning treatment modality, disease stage progression, delivery setting, and regional regulatory cluster. CAGRs derived from epidemiological incidence projections, therapy area penetration curves, and reimbursement pathway maturation timelines. Forecast inputs incorporated EBV DNA monitoring adoption rates and proton beam therapy infrastructure investment cycles.
The forecast holds incumbent behavior within observed patterns; aggressive moves by regional biotech specialists or radiotherapy equipment manufacturers would shift outcomes beyond modeled ranges. Cross-checking against health technology assessment body reimbursement decisions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Tumor Infiltrating Lymphocytes Market
Oncology
Asia Pacific Cancer Immunotherapy Market
Oncology
Ovarian Cancer Market
Oncology
Interventional Oncology Ablation Market
Oncology
BRCA Mutation-Positive Ovarian Cancer Market
Oncology
Australia Cancer Treatment Market
Oncology
Intratumoral Cancer Therapies Market
Oncology
PD1 Resistant Head and Neck Cancer Market
Oncology
Small Cell Lung Cancer (SCLC) Treatment Market
Oncology
Colorectal Cancer Market
Oncology
AI in Oncology Market
Oncology
Testicular Cancer Treatment Market
Oncology
North America Bone Metastasis Market
Oncology
Metastatic Melanoma Market
Oncology
Global Non-Small Cell Lung Cancer (NSCLC) Market
Oncology
Low-Grade Central Osteosarcoma Treatment Market