
 Metastases Spinal Tumor Market | 2026-2036
Metastases Spinal Tumor Market Size, Share, and Industry Trends Forecast 2026-2036
Metastases Spinal Tumor Market Outlook
The metastases spinal tumor treatment landscape is restructuring around a sharp split between premium navigation-guided surgical platforms and commodity radiation delivery systems. Medtronic leverages its integrated surgical ecosystem to anchor high-end spinal oncology procedures across major academic medical centers. Roche differentiates through precision medicine diagnostics that guide patient selection for targeted therapy regimens in metastatic disease.
Metastases spinal tumor refers to secondary malignant growths that originate from primary cancers elsewhere in the body and infiltrate vertebral bone, spinal cord, or surrounding neural structures, typically presenting with epidural compression and requiring multimodal intervention combining decompression, stabilization, and systemic control. The tumor type dimension shows lung cancer and breast cancer origins dominating clinical volume due to their high metastatic propensity to bone, while prostate cancer metastases sustain the fastest protocol development driven by expanding hormonal and radioligand combination therapies. Treatment type segmentation reveals radiation therapy occupying the broadest installed base, though targeted therapy commands the most concentrated investment as pharmaceutical pipelines prioritize spine-specific delivery mechanisms.
The FDA maintains stringent premarket review for spinal tumor ablation devices under its Breakthrough Devices Program, while the EMA's Medical Device Regulation imposes enhanced clinical evidence requirements on implantable spinal stabilization systems used in oncologic reconstruction. Japan's PMDA accelerates priority review for combination products addressing spinal cord compression, reshaping competitive entry timelines for multinational device manufacturers. Stakeholders must monitor evolving reimbursement thresholds for minimally invasive spinal tumor procedures across Medicare, NHS England, and Japan's MHLW fee schedules to anticipate access-driven demand shifts.
Market Dynamics
The metastases spinal tumor market is bifurcating around navigation-guided surgical platforms versus commodity radiation systems, with tertiary hospital consolidation and FDA breakthrough pathway acceleration compressing competitive timelines for novel ablation technologies.
Growth Catalysts
- FDA Breakthrough Device Designation:The pathway accelerates premarket review timelines for spinal tumor ablation systems, enabling faster commercialization of microwave and radiofrequency technologies in vertebral metastasis treatment.
- Aging diagnostic infrastructure:Japan, Germany, and the United States are expanding dedicated spinal oncology protocols in academic medical centers, concentrating patient volume and equipment procurement in tertiary settings.
- Radioligand therapy expansion:Prostate cancer metastases are driving protocol development for lutetium-177 based combination regimens, creating integrated treatment demand spanning systemic therapy and spinal stabilization.
Market Restraints
- Implantable device evidence requirements:The EMA's Medical Device Regulation imposes enhanced clinical trial burdens on spinal stabilization systems used in oncologic reconstruction, extending European market entry timelines.
- Isotope supply concentration:Molybdenum-99 and lutetium-177 production concentrates in a handful of aging reactors, creating radiopharmaceutical availability risk for metastatic bone disease protocols.
- Technical limitation in neural preservation:Thermal ablation technologies face constrained efficacy margins near the spinal cord, limiting applicability in epidural compression cases requiring decompression.
Strategic Opportunities
- Underpenetrated ambulatory surgery centers:United States outpatient facilities are expanding minimally invasive spinal tumor capabilities, creating channel diversification beyond traditional hospital purchasing.
- AI-augmented surgical navigation:Machine vision integration with intraoperative imaging is automating vertebral level identification and tumor margin delineation during metastasis resection procedures.
- Japan's PMDA priority review:Combination products addressing spinal cord compression receive accelerated regulatory timelines, attracting multinational device manufacturers to prioritize Japanese market entry sequencing.
Industry Challenges
- Spine oncology fellowship scarcity:The specialized skill set bridging neurosurgery, orthopedic oncology, and palliative care remains concentrated in a limited number of training programs, constraining procedure volume expansion.
- Legacy EMR integration complexity:Navigation platform data streams require substantial reconfiguration to interface with hospital electronic medical record systems, extending implementation timelines and IT resource demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metastases Spinal Tumor Market |
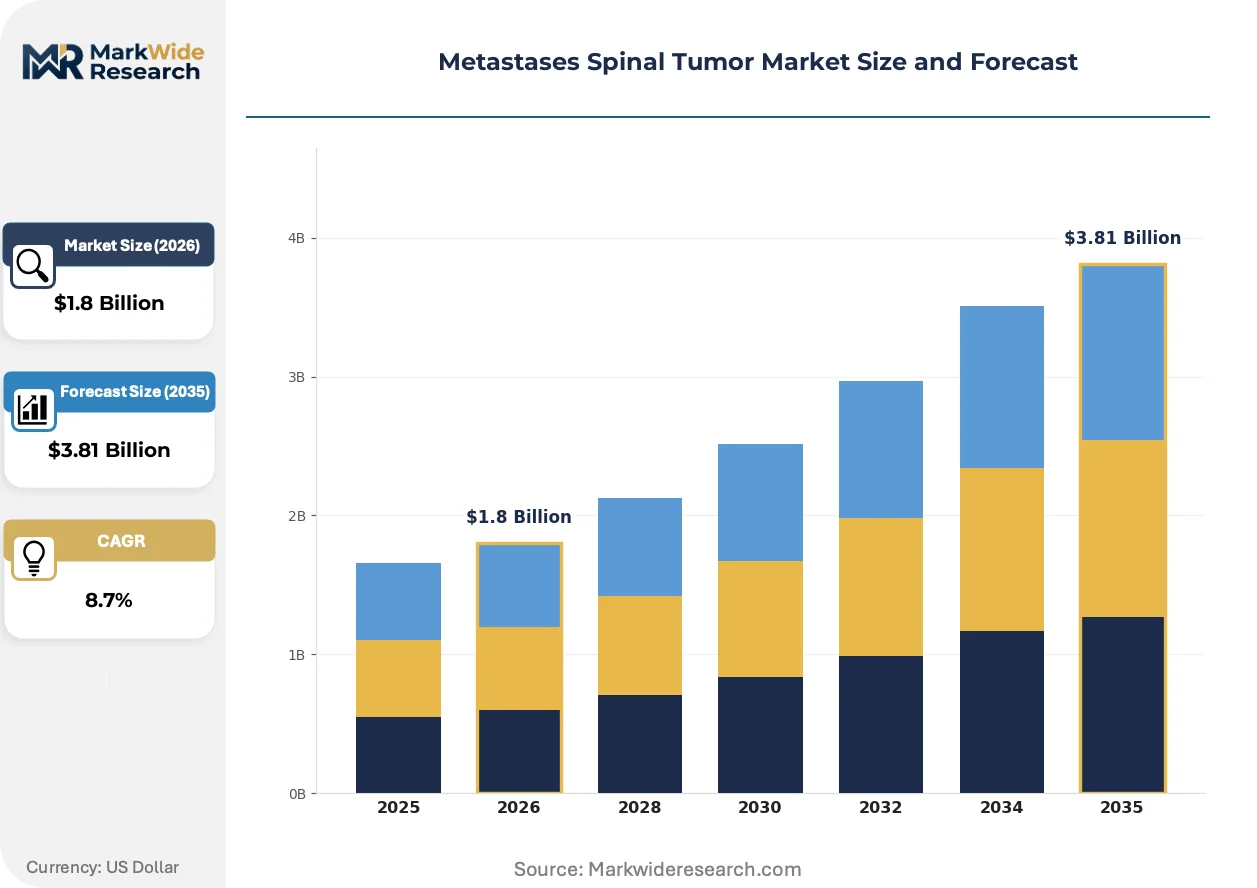
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tumor Type: Osteosarcoma, Lung Cancer, Breast Cancer, Prostate Cancer Diagnosis Method: CT Scan, MRI, Bone Scan, X-Ray Treatment Type: Surgery, Radiation Therapy, Chemotherapy, Targeted Therapy End User: Hospitals, Clinics, Research Institutions, Rehabilitation Centers |
| Companies Covered | Roche, NuVasive, Medtronic, Brainlab, Zimmer Biomet Holdings, Stryker Corporation, Novartis, Amgen, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metastases Spinal Tumor Market Strategic Shifts
Robotic surgical platforms and AI-augmented navigation are compressing the skill gradient required for complex spinal metastasis procedures, while regulatory pathways and procurement models co-evolve around value demonstration requirements.
Intraoperative navigation systems with integrated tumor mapping capabilities are automating real-time instrument guidance during vertebral resection. Academic medical centers in the United States and Germany are deploying these platforms at scale, reducing reliance on intraoperative CT and fluoroscopy. The technology is automating surgical workflow standardization, enabling community hospital systems to offer metastasis procedures previously restricted to major referral centers.
The EMA's Medical Device Regulation now mandates post-market clinical follow-up for implantable spinal oncology devices, shifting evidence generation from pre-market trials to longitudinal surveillance. Manufacturers must establish European patient registries to maintain CE marking for stabilization systems used in pathological fracture reconstruction. High-volume implant suppliers are responding by funding multicenter outcome studies and restructuring European commercial organizations around clinical specialist roles.
Hospital purchasing committees are unbundling device procurement from procedural reimbursement, separating capital equipment acquisition from disposable spine kit contracting. United States health systems are consolidating metastasis procedure purchasing through centralized value analysis committees, displacing individual surgeon preference contracting. This consolidation is most visible in integrated delivery networks across Texas, California, and the Northeast, where standardized protocol pathways override individual physician vendor selection.
Metastases Spinal Tumor Market Segmentation
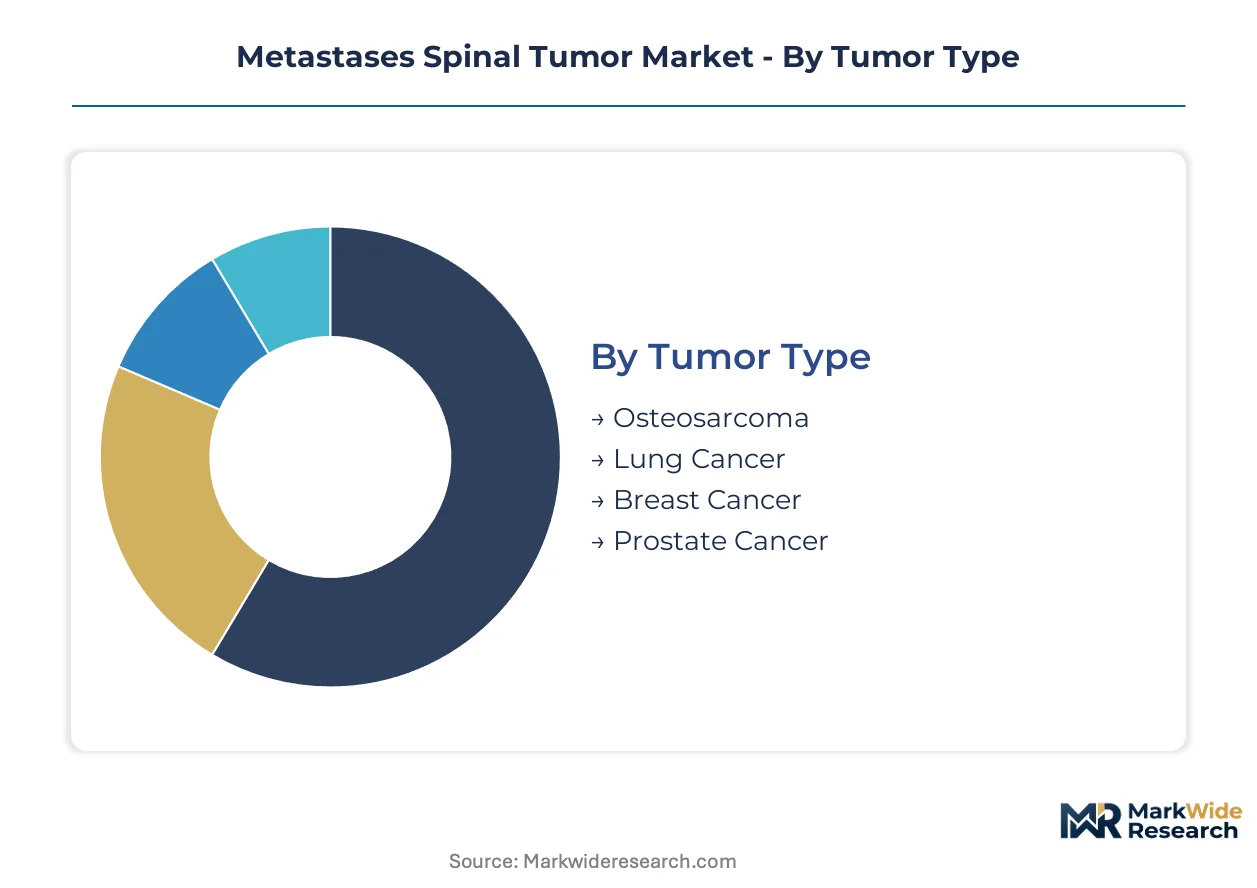
Spinal metastasis treatment protocols demand precise patient stratification across tumor biology, diagnostic pathway, and intervention modality. Segmentation clarity enables equipment manufacturers and pharmaceutical developers to align R&D investment with procedure volume concentration and reimbursement eligibility.
Tumor Type:
FDA Breakthrough Device Designation and EMA MDR compliance requirements vary sharply by primary cancer origin, with prostate and lung metastases commanding distinct evidentiary standards for radioligand and ablation device submissions.
- Lung Cancer:Non-small cell histologies drive the highest absolute volume of spinal epidural compression presentations. Academic medical centers in the United States and Germany concentrate interventional radiology resources for these cases, constrained by limited spine oncology fellowship output.
- Breast Cancer:Hormone receptor status stratifies treatment eligibility for vertebral metastasis protocols. Japan's PMDA has prioritized review timelines for combination products addressing breast cancer spinal cord compression, accelerating device manufacturer entry sequencing.
- Prostate Cancer:Expanding lutetium-177 radioligand therapy integration with spinal stabilization.
- Osteosarcoma:Primary bone malignancy requiring distinct surgical margin protocols from metastatic disease.
Leading the category by volume: Lung Cancer. Growing fastest: Prostate Cancer.
Diagnosis Method:
Capital intensity and consumable economics separate premium imaging modalities from standard-of-care alternatives, with AI-augmented reconstruction software now bundled into MRI and CT procurement contracts.
- MRI:Superior soft tissue contrast enables precise epidural compression grading and spinal cord displacement measurement. Tertiary hospitals in Japan and the United States deploy 3T systems with dedicated spine coils for metastasis staging, driving replacement demand as magnet lifecycles expire.
- CT Scan:Rapid osseous detail acquisition supports emergency decompression triage. Community hospital systems in Germany are expanding CT-guided biopsy capabilities to reduce referral burden to academic centers, shifting point-of-care diagnostic economics.
- Bone Scan:Whole-body skeletal survey for polymetastatic disease detection.
- X-Ray:Initial screening and pathological fracture identification in resource-limited settings.
Commanding premium pricing: MRI. Expanding most quickly into community settings: CT Scan.
Treatment Type:
Reimbursement rate divergence between inpatient surgical episodes and outpatient radiation fractions shapes manufacturer channel strategy and capital equipment placement priorities.
- Radiation Therapy:Stereotactic body radiation delivery occupies the broadest installed base across United States integrated delivery networks. Medicare reimbursement stability for spinal metastasis fractions supports linear accelerator utilization rates, though isotope supply concentration for select modalities creates protocol vulnerability.
- Surgery:Navigation-guided platforms automate vertebral level identification and tumor margin delineation. German academic medical centers are deploying these systems at scale, reducing fluoroscopy dependence and enabling workflow standardization previously restricted to major referral centers.
- Targeted Therapy:Pharmaceutical pipelines prioritize spine-specific delivery mechanisms with concentrated investment.
- Chemotherapy:Systemic backbone for radiosensitive histologies and polymetastatic burden.
Steepest expansion trajectory: Targeted Therapy. Dominating procedure volume: Radiation Therapy.
End User:
Procurement authority centralization distinguishes institutional purchasers with value analysis committees from decentralized clinical decision-makers.
- Hospitals:Tertiary academic centers concentrate spinal metastasis procedure volume and equipment procurement. United States health systems across Texas, California, and the Northeast are consolidating purchasing through centralized committees, displacing individual surgeon preference contracting.
- Clinics:Ambulatory surgery centers in the United States are expanding minimally invasive spinal tumor capabilities. Outpatient facility expansion creates channel diversification beyond traditional hospital purchasing, though Medicare site-of-service payment differentials constrain migration speed.
- Research Institutions:Clinical trial infrastructure for novel ablation and radioligand combinations.
- Rehabilitation Centers:Post-stabilization functional recovery and palliative care coordination.
Concentrating capital expenditure: Hospitals. Gaining share fastest: Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's Kanto medical corridor concentrates Japan's spinal metastasis treatment capacity, with tertiary hospitals deploying navigation-guided surgical platforms at scale. Academic medical centers across Germany's North Rhine-Westphalia and Bavaria regions anchor European procedure volume. The United States maintains diagnostic infrastructure density through integrated delivery networks in Texas, California, and the Northeast corridor.
United States
Medicare reimbursement stability for spinal metastasis fractions sustains linear accelerator utilization across integrated delivery networks. The FDA's Breakthrough Device Designation pathway accelerates premarket review timelines for novel ablation technologies. Texas Medical Center in Houston and MD Anderson anchor concentrated fellowship training output, constraining national procedure expansion capacity.
Germany
Academic medical centers in Munich and Heidelberg deploy navigation-guided platforms to reduce fluoroscopy dependence during vertebral resection. The EMA's Medical Device Regulation imposes enhanced clinical evidence requirements on implantable spinal stabilization systems. The Rhine-Main metropolitan cluster concentrates interventional radiology resources for emergency decompression triage.
Japan
Aging demographics concentrate spinal epidural compression presentations in Tokyo and Osaka metropolitan hospitals. The PMDA accelerates priority review timelines for combination products addressing spinal cord compression. The Kansai medical corridor in Osaka anchors multinational device manufacturer market entry sequencing for Asia-Pacific expansion.
United Kingdom
NHS England fee schedule revisions reshape access-driven demand shifts for minimally invasive spinal tumor procedures. The MHRA maintains stringent post-market surveillance for implantable oncologic reconstruction devices. London's Royal National Orthopaedic Hospital and regional tertiary centers concentrate fellowship-trained spine oncology specialists.
Switzerland
Swissmedic's device approval timelines attract European headquarters placement for spinal navigation platform manufacturers. Basel and Zurich academic hospitals concentrate precision medicine diagnostics integration with surgical oncology protocols. The country's diagnostic infrastructure supports patient selection for targeted therapy regimens in metastatic disease.
Metastases Spinal Tumor Market Competitive Environment
Premium-margin players sit above commodity-margin players across the navigation-surgical platform versus radiation delivery system divide. The vendor base stratifies into three tiers: integrated surgical ecosystem providers, precision medicine diagnostic developers, and standalone radiation equipment manufacturers. Dominant competitive moves include M&A activity consolidating navigation platform capabilities and strategic partnerships bridging pharmaceutical radioligand pipelines with spinal stabilization device portfolios.
Within the integrated surgical ecosystem tier, Medtronic and Stryker Corporation exemplify platform providers anchoring high-end spinal oncology procedures across major academic medical centers. Roche occupies a distinct position representing precision medicine diagnostic developers that guide patient selection for targeted therapy regimens. NuVasive sits within the specialized spinal device archetype, reflecting competitive positioning around minimally invasive vertebral access technologies.
| Leading Market Players |
|---|
| Roche |
| NuVasive |
| Medtronic |
| Brainlab |
| Zimmer Biomet Holdings |
| Stryker Corporation |
| Novartis |
| Amgen |
| Johnson & Johnson |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up surgical device specialists have consolidated navigation platform manufacturers across Germany and the United States, concentrating procurement leverage and enforcing standardized pricing discipline across hospital system contracts. This ownership pattern feeds directly into supply chain behavior, as portfolio companies coordinate component sourcing and cross-subsidize R&D spend to maintain premium positioning against commodity radiation equipment.
Pricing Analysis
Value-based pricing anchored to surgical outcome metrics dominates navigation-guided platform contracts, with tertiary hospitals paying premium rates tied to reduced fluoroscopy exposure and shorter operative times. Three-tier pricing structure across premium navigation systems, standard radiation delivery, and economy stabilization implants reflects FDA breakthrough certification tiers and geographic delivery cost differentials. Pricing pressure stems from Medicare site-of-service payment differentials that constrain outpatient migration speed. Academic medical centers show least price sensitivity due to bundled reimbursement, while ambulatory surgery centers negotiate aggressively on capital equipment leases.
Supply Chain Analysis
FDA Breakthrough Device Designation and EMA MDR compliance requirements create qualification gating that filters component suppliers to a vetted tier of German, Japanese, and United States manufacturers. Navigation platform assembly draws from precision-machined titanium forgings sourced from Osaka and Basel, lutetium-177 radiopharmaceuticals from aging European reactors, and AI-augmented imaging software developed in Boston and Munich. Single-source vulnerability concentrates in isotope production for radioligand therapy. Distribution runs through GPO contracts and direct hospital system agreements, bypassing traditional device distributors for high-value capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metastases spinal tumor market sits in a technology-transition phase, with AI-augmented surgical navigation automating vertebral level identification and displacing legacy fluoroscopy-dependent workflows. This shift rewards stakeholders who anchor positioning around data integration and outcome demonstration.
For Market Incumbents: Hedge against commodity radiation system erosion by deepening software companion development for navigation platforms and securing exclusive GPO contracts with Texas and California integrated delivery networks. Threat substitution from standalone AI imaging vendors demands rapid EMR integration capability buildout. Certification investment in Japan's PMDA priority review pathway offers defensive moat construction. For New Entrants and Emerging Players: Direct-to-clinic digital sales channels enable bypass of consolidated hospital purchasing committees for disposable spine kit components. White-space targets include United States ambulatory surgery centers expanding minimally invasive capabilities and German community hospitals seeking CT-guided biopsy autonomy. Go-to-market angle centers on outcome-guaranteed leasing models that transfer utilization risk from capital-constrained facilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized spinal navigation software developers in the United States Midwest and precision radiopharmaceutical manufacturers facing isotope supply uncertainty. Long-term viability hinges on five-to-ten year regulatory pathway exclusivity and radioligand therapy integration potential. Signal to watch: FDA breakthrough designation grants for microwave ablation systems as inflection indicator for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Exclusive contracts with Texas Medical Center concentrate procedure volume and lock out competitor platform placement. |
| Software Companion Development | AI-augmented navigation modules automate tumor margin delineation and reduce reliance on intraoperative CT. |
| FDA Breakthrough Submission | Accelerated review timelines compress commercialization cycles for microwave ablation technologies in vertebral metastasis. |
| Reimbursement Strategy | Medicare site-of-service payment alignment enables ambulatory surgery center channel expansion beyond traditional hospital purchasing. |
| CE Marking Pathway | EMA MDR compliance for implantable stabilization systems requires European patient registry funding and clinical specialist restructuring. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with spine oncology fellowship directors, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers. FDA 510(k) clearances, EMA MDR submissions, CMS Medicare reimbursement schedules, and hospital procurement databases provided validation points. Bottom-up procedure volume estimates triangulated against top-down equipment installed base data.
Data-stream reconciliation across navigation platform shipment records, linear accelerator utilization reports, and radiopharmaceutical production disclosures enabled forecast construction across the projection horizon. Segmentation dimensions modeled include tumor type, diagnosis method, treatment modality, and end-user facility tier. CAGRs derived from procedure volume growth rates, equipment replacement cycles, and therapy protocol adoption curves. Forecast inputs incorporated PMDA priority review timelines and NHS England fee schedule revision impacts.
The model holds under stable Medicare reimbursement and isotope supply continuity; deviation in FDA breakthrough designation grant velocity or radiopharmaceutical production facility closures would shift equipment procurement timing and therapy mix assumptions. Forecasts reflect documented assumptions regarding fellowship training output and EMR integration implementation timelines. A model refresh is warranted upon material change in Japan's MHLW fee schedule or EMA MDR post-market surveillance enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Osteosarcoma Market
Oncology
South America Bladder Cancer Therapeutics and Diagnostics Market
Oncology
Asia-Pacific Cancer Biomarkers Market
Oncology
Europe Radiotherapy Market
Oncology
Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Cancer Cachexia Market
Oncology
PD1 Non-Small Cell Lung Cancer Treatment Market
Oncology
Breast Cancer Liquid Biopsy Market
Oncology
Tumor Lysis Syndrome Treatment Market
Oncology
BRCA Mutation-Positive Ovarian Cancer Market
Oncology
Outpatient Oncology Infusion Market
Oncology
PD1 Resistant Head and Neck Cancer Market
Oncology
Global Cancer Treatment Market
Oncology
Asia-Pacific Radiation Oncology Market
Oncology
Tumor Ablation Market