
 Global Genomics in Cancer Care Market | 2026-2036
Global Genomics in Cancer Care Market Size, Share, and Industry Trends Forecast 2026-2036
Global Genomics in Cancer Care Market Foresight
Software-defined bioinformatics pipelines is expanding how genomic data gets monetized beyond hardware sales. Illumina leverages its installed base of sequencing instruments to drive recurring consumable revenue. Thermo Fisher Scientific anchors its position through integrated sample-to-answer workflows spanning extraction through analysis. Agilent Technologies specializes in targeted enrichment chemistries that feed into downstream variant calling pipelines.
Genomics in cancer care encompasses the sequencing, analysis, and clinical interpretation of tumor and germline DNA to guide diagnosis, prognosis, and therapeutic decision-making, typically requiring read depths exceeding 100x for somatic variant detection and variant allele frequency thresholds below 5% for minimal residual disease tracking. The field serves oncologists, pathologists, and pharmaceutical developers seeking to match molecular profiles to targeted therapies. Sequencing platforms occupy the largest hardware revenue pool but face margin compression as instrument costs decline. Cloud-based deployment represents the fastest-expanding infrastructure category as laboratories seek elastic compute for sporadic large-cohort analyses. Therapy selection applications command premium pricing due to direct reimbursement linkages to approved companion diagnostics.
FDA regulates laboratory-developed tests and companion diagnostics under distinct premarket pathways that determine market access timelines for genomic profiling products. EMA's In Vitro Diagnostic Regulation and Japan's PMDA oversight of next-generation sequencing-based oncology panels create parallel compliance requirements for multinational product rollouts. China's NMPA accelerated review pathways for innovative diagnostic devices are reshaping launch sequencing for genomics companies. Stakeholders must monitor evolving reimbursement decisions from CMS and analogous national payers, as coverage determinations for broad-panel genomic profiling remain the decisive gate for clinical volume expansion.
Market Dynamics
The convergence of cloud-native bioinformatics and declining sequencing costs is compressing time-to-insight for molecular tumor boards, forcing laboratories to reconfigure capital allocation between on-premise hardware and elastic compute infrastructure.
Growth Catalysts
- CMS reimbursement expansion:Coverage determinations for broad-panel genomic profiling in the United States now extend to minimal residual disease monitoring, unlocking clinical volume for community oncology practices.
- Sample-to-answer automation:Integrated nucleic acid extraction-to-sequencing workflows reduce hands-on time and technician variability in high-throughput diagnostic laboratories.
- China's NMPA accelerated pathways:Innovative oncology companion diagnostics receive priority review, compressing commercialization timelines for multinational genomics firms entering the Chinese market.
Market Restraints
- Reagent supply concentration:Specialty enzymes and modified nucleotides for NGS library preparation originate from a limited supplier base in North America and Europe, creating input vulnerability.
- FDA premarket friction:Laboratory-developed tests face heightened evidentiary requirements under evolving enforcement discretion policies, extending validation timelines for academic medical centers.
- Interoperability gaps:Proprietary file formats from dominant sequencing instrument vendors complicate multi-platform data integration for clinical decision support systems.
Strategic Opportunities
- Germline-somatic integration:Combined tumor-normal sequencing workflows enable hereditary cancer risk stratification alongside therapy selection, opening reimbursement pathways in Germany and the United Kingdom.
- Real-world evidence mandates:FDA's expanded requirements for post-market safety surveillance create demand for prospective genomic registries linked to clinical outcomes.
- Pharmaceutical co-development:Biomarker-driven trial designs position diagnostic firms for companion diagnostic exclusivity agreements with oncology drug developers.
Industry Challenges
- Bioinformatics workforce scarcity:Clinical interpretation of complex structural variants requires specialized training that outpaces current fellowship pipeline output in the United States and Europe.
- Multi-omics integration complexity:Synchronizing genomic, transcriptomic, and proteomic data streams demands substantial informatics infrastructure investment that exceeds capital budgets of mid-sized health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Genomics in Cancer Care Market |
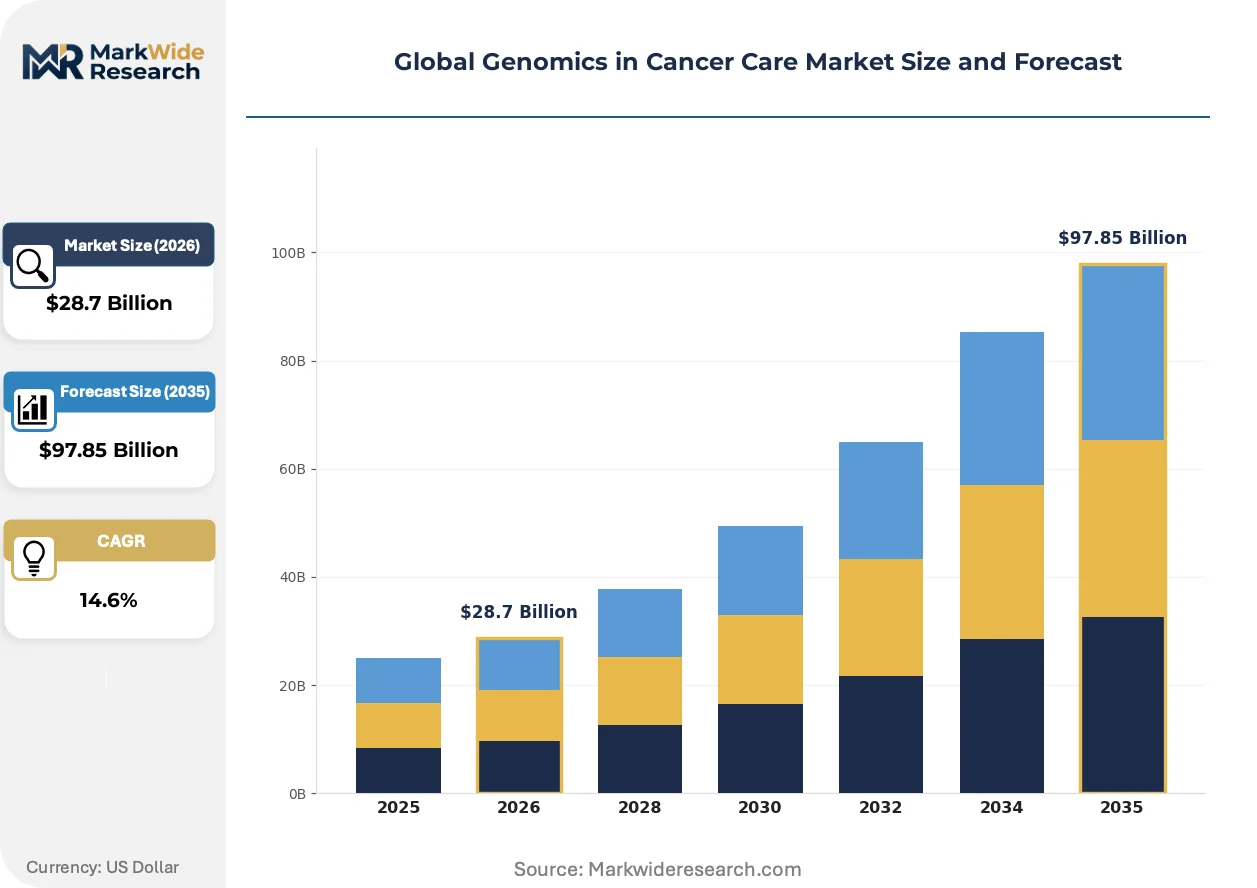
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $97.85 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sequencing Platforms, PCR Kits, Microarrays, Bioinformatics Solutions, CRISPR Tools Application: Mutation Profiling, Risk Assessment, Therapy Selection, Disease Monitoring, Biomarker Discovery End User: Research Institutions, Diagnostic Laboratories, Pharmaceutical Companies, Personalized Medicine Centers Deployment: On-Premise, Cloud-Based, Hybrid Systems, Managed Services |
| Companies Covered | Illumina, Agilent Technologies, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific, Beckman Coulter, Bio-Rad Laboratories, GE Healthcare, Quest Diagnostics, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Genomics in Cancer Care Market Shifts & Advancements
Artificial intelligence is penetrating variant classification pipelines, compressing manual review burden while introducing new validation requirements for algorithmic clinical decision support.
Long-read sequencing platforms from Pacific Biosciences and Oxford Nanopore Technologies are electrifying structural variant detection in hematologic malignancies, where complex rearrangements evade short-read resolution. Major cancer centers in Boston and Heidelberg have adopted these systems for research-grade profiling. The technology is electrifying competitive positioning in minimal residual disease applications, where phased variant detection enables single-molecule sensitivity.
The European Union's In Vitro Diagnostic Regulation (IVDR) reclassifies tumor profiling assays into higher-risk categories, mandating notified body involvement for CE marking. This structural shift favors larger diagnostic manufacturers with established quality management systems over academic laboratory-developed tests. German and French reference laboratories are consolidating validation resources to share conformity assessment costs.
Oncology practices are unbundling genomic interpretation from sequencing execution, contracting specialized molecular pathologists through telemedicine platforms rather than maintaining in-house expertise. This purchasing pattern concentrates interpretive volume at regional hubs in Texas, California, and Bavaria while community hospitals retain specimen logistics. The shift is most pronounced in community oncology networks where case volumes fail to justify dedicated molecular tumor boards.
Global Genomics in Cancer Care Market Segmentation
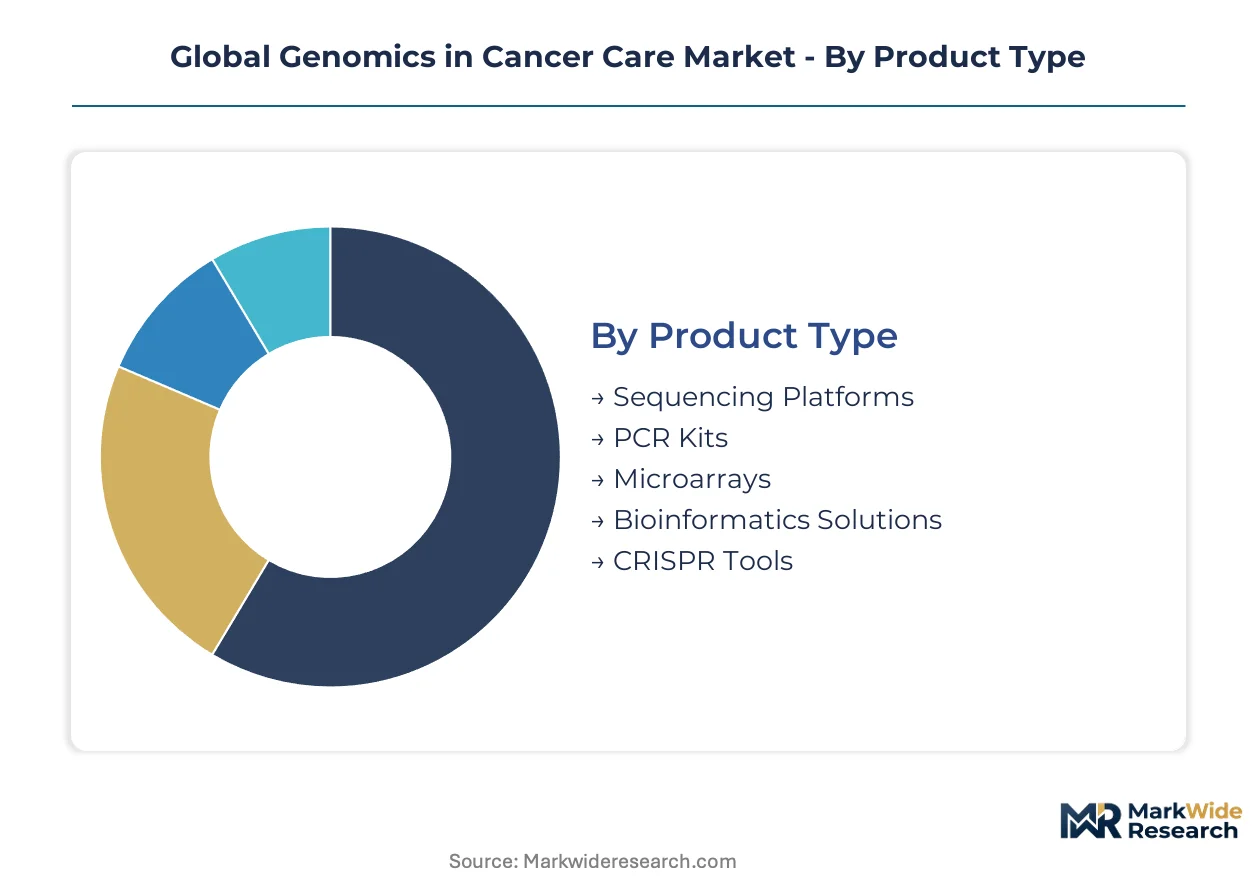
Genomics in cancer care demands precise segmentation because reimbursement pathways, regulatory requirements, and technical specifications diverge sharply across product architectures and clinical use cases. Laboratories configure procurement portfolios around throughput requirements, bioinformatics maturity, and companion diagnostic partnerships rather than selecting homogeneous technology stacks.
Product Type:
Sequencing platforms anchor capital expenditure budgets while consumables and software layers determine lifetime value capture; CRISPR tools occupy emerging standalone positions whereas PCR kits embed into integrated sample-to-answer systems.
- Sequencing Platforms:Short-read instruments from Illumina dominate installed base metrics with read depths exceeding 100x for somatic variant detection. Demand concentrates in United States academic medical centers and Chinese national cancer centers building precision oncology infrastructure, constrained by reagent supply concentration and extended validation timelines for FDA-cleared applications.
- PCR Kits:Digital PCR and quantitative PCR chemistries deliver rapid turnaround for hotspot mutation detection in community oncology settings. German and French diagnostic laboratories favor these for therapy selection workflows where reimbursement requires rapid documented results, though limited multiplexing constrains broad-panel adoption.
- Microarrays:Copy number variation profiling and loss-of-heterozygosity detection for solid tumor classification.
- Bioinformatics Solutions:Cloud-native variant interpretation pipelines with AI-assisted classification for molecular tumor boards.
- CRISPR Tools:Guide RNA libraries for functional genomics screening and synthetic lethal target validation in pharmaceutical research.
Volume placements concentrate in Sequencing Platforms; the faster expansion belongs to Bioinformatics Solutions.
Application:
Clinical utility and reimbursement density vary across the diagnostic continuum, with therapy selection commanding premium pricing through companion diagnostic linkages while disease monitoring builds recurring revenue through longitudinal testing protocols.
- Therapy Selection:Companion diagnostic assays match actionable mutations to FDA-approved targeted therapies, requiring premarket approval and prospective clinical validation. United States community oncology practices drive volume through CMS reimbursement for broad-panel profiling, with China's NMPA accelerated pathways compressing commercialization timelines for multinational assay developers.
- Mutation Profiling:Comprehensive genomic profiling identifies somatic alterations across hundreds of genes to guide clinical trial enrollment and off-label therapy consideration. Academic medical centers in Boston and Heidelberg deploy these for molecular tumor board decision-making, facing bioinformatics workforce scarcity that limits interpretation throughput.
- Risk Assessment:Germline testing for hereditary cancer syndromes in preventive oncology programs.
- Disease Monitoring:Circulating tumor DNA assays for minimal residual disease detection and recurrence surveillance.
- Biomarker Discovery:Research-grade sequencing to identify novel therapeutic targets for pharmaceutical development.
Revenue density peaks in Therapy Selection; Disease Monitoring gains share fastest through longitudinal testing protocols.
End User:
Procurement sophistication and budget scale diverge across institutional types, with pharmaceutical companies funding exploratory biomarker programs while diagnostic laboratories prioritize automation and regulatory compliance.
- Diagnostic Laboratories:High-throughput facilities process thousands of oncology specimens monthly with integrated nucleic acid extraction-to-sequencing workflows. Texas and California regional hubs concentrate interpretive volume through telemedicine-contracted molecular pathologists, reducing hands-on time requirements for community hospital specimen logistics.
- Pharmaceutical Companies:Biomarker-driven trial designs demand prospective genomic registries linked to clinical outcomes for FDA post-market surveillance. Co-development agreements position diagnostic firms for companion diagnostic exclusivity, with Germany and United Kingdom sites leading germline-somatic integration for hereditary risk stratification.
- Research Institutions:Academic medical centers with molecular tumor boards and fellowship training programs.
- Personalized Medicine Centers:Integrated cancer centers combining genomic profiling with clinical trial matching services.
Capital deployment concentrates in Diagnostic Laboratories; Personalized Medicine Centers climb the fastest as community oncology networks consolidate interpretive expertise.
Deployment:
Infrastructure configuration reflects computational demand patterns, with sporadic large-cohort analyses favoring elastic cloud resources while routine clinical testing requires predictable latency and data sovereignty controls.
- Cloud-Based:Elastic compute infrastructure enables sporadic large-cohort analyses without on-premise hardware depreciation. Bavarian and Heidelberg cancer centers adopt these for multi-omics integration projects, though proprietary file formats from dominant sequencing vendors complicate multi-platform data integration for clinical decision support systems.
- Hybrid Systems:Local preprocessing with cloud-based variant interpretation balances latency requirements against scalable analytics. United States mid-sized health systems favor this architecture to contain capital budgets while accessing AI-assisted classification pipelines that exceed on-premise computational capacity.
- On-Premise:Dedicated servers and storage for institutions with strict data residency requirements.
- Managed Services:Outsourced bioinformatics operations with service-level agreements for turnaround time.
Existing infrastructure concentrates in On-Premise installations; Hybrid Systems gain traction fastest among capital-constrained health systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sequencing instrument production concentrates in the United States and China, while clinical consumption spreads across Germany, Japan, and the United Kingdom as precision oncology infrastructure matures. Reimbursement policy divergence between CMS and national health technology assessment bodies creates asynchronous adoption curves across major markets.
United States
Academic medical centers in Boston and Houston drive demand for high-throughput tumor profiling platforms. FDA premarket approval pathways for companion diagnostics shape commercialization timelines for assay developers. Texas regional hubs concentrate interpretive expertise through telemedicine-contracted molecular pathologists serving community oncology networks.
Germany
Reference laboratories in Heidelberg and Munich consolidate validation resources to share EU IVDR conformity assessment costs. EMA oversight of next-generation sequencing-based oncology panels mandates notified body involvement for CE marking. Bavarian cancer centers adopt hybrid cloud infrastructure for multi-omics integration projects.
China
National cancer centers in Beijing and Shanghai build precision oncology infrastructure with accelerated NMPA review pathways for innovative companion diagnostics. Domestic sequencing platform manufacturers compete with multinational installed bases. Reagent supply localization programs reduce import dependency for modified nucleotides.
Japan
PMDA oversight of genomic profiling panels creates parallel compliance requirements for multinational product rollouts. Tokyo and Osaka metropolitan areas concentrate molecular tumor board expertise. Pharmaceutical co-development agreements position diagnostic firms for companion diagnostic exclusivity in oncology drug trials.
United Kingdom
NHS England coverage determinations for broad-panel genomic profiling gate clinical volume expansion in community oncology practices. London and Cambridge clusters anchor biomarker discovery programs linked to pharmaceutical development pipelines. Germline-somatic integration workflows open reimbursement pathways for hereditary cancer risk stratification.
Global Genomics in Cancer Care Market Competitive Landscape
Capital-heavy sequencing platform producers compete with asset-light bioinformatics developers for margin capture in the cancer genomics value chain. The vendor base stratifies across integrated sample-to-answer providers, specialized enrichment chemistry suppliers, and cloud-native analytics vendors. Three archetypes dominate: instrument manufacturers monetizing recurring consumable revenue, diagnostic laboratories unbundling interpretation from sequencing execution, and software vendors extracting value from variant classification automation. Competitive moves concentrate on strategic partnerships between platform vendors and pharmaceutical developers, plus geographic expansion through distributor networks in Asia-Pacific markets.
Among North American platform manufacturers, Illumina anchors the short-read instrument segment with installed base metrics exceeding competing technologies. Thermo Fisher Scientific occupies a position spanning extraction chemistries through analysis software. Agilent Technologies exemplifies the specialized reagent archetype with targeted enrichment portfolios feeding downstream variant pipelines. These three represent contrasting strategic postures: platform lock-in through consumable economics, vertical integration across workflow stages, and niche chemistry dominance.
| Leading Market Players |
|---|
| Illumina |
| Agilent Technologies |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific |
| Beckman Coulter |
| Bio-Rad Laboratories |
| GE Healthcare |
| Quest Diagnostics |
| PerkinElmer |
| Others |
Supply & Pricing Matrix
Modified nucleotide spot prices and specialty enzyme contract indices cascade through NGS library preparation tiers, compressing margins for mid-scale diagnostic laboratories while concentrating pricing power with integrated platform vendors that captive-produce critical reagents.
Pricing Analysis
Margin tightening in consumables reflects Illumina's consumable economics and Thermo Fisher's vertical integration of extraction chemistries. Pricing stratifies across FDA-cleared companion diagnostic tiers, CE-IVD marked panels, and research-use-only assays, with certification grade and volume scale as primary differentiation drivers. Cost-down pressure on bioinformatics software accelerates as cloud-native vendors displace on-premise perpetual licenses. Community oncology practices exhibit highest price sensitivity; pharmaceutical co-development partners demonstrate lowest.
Supply Chain Analysis
Instrument refurbishment flows and certified pre-owned sequencing platforms from United States academic medical centers feed secondary markets in India and Brazil, extending asset lifecycles. Reagent manufacturing concentrates in United States, Germany, and China, with modified nucleotides and heat-stable polymerases as critical inputs. Single-source vulnerability pervades specialty enzyme supply. Distribution runs through direct sales forces for capital equipment and distributor networks for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Short-read sequencing platforms face displacement pressure from long-read systems in structural variant applications, compressing incumbent hardware margins while expanding bioinformatics service addressable markets.
For Market Incumbents: Extend platform lock-in through consumable subscription models that embed bioinformatics interpretation, countering Pacific Biosciences' and Oxford Nanopore's research-grade positioning. Deepen backward integration into modified nucleotide production to neutralize reagent supply concentration risks. Prioritize FDA premarket approval investments for companion diagnostic exclusivity.
For New Entrants and Emerging Players: Community oncology practices in Texas and California represent underserved interpretive demand, as telemedicine-contracted molecular pathologists concentrate at regional hubs. White-space targets include AI-assisted variant classification for mid-sized health systems and germline-somatic integration workflows for German reference laboratories. Go-to-market through GPO contracts with hospital procurement committees.
For Investors and Strategic Acquirers: Distressed-cycle entries favor cloud-native bioinformatics developers with ISO 13485 quality systems in Bavaria and Heidelberg clusters, where EU IVDR compliance costs strain academic laboratory-developed tests. Long-term viability hinges on pharmaceutical co-development agreement pipelines. Monitor NMPA accelerated approval volumes as China demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Companion diagnostic exclusivity locks in therapy selection revenue with oncology drug developers. |
| CE Marking Pathway | EU IVDR notified body involvement gates market access for tumor profiling assays in Germany and France. |
| Hospital System Partnership | Texas regional hubs consolidate interpretive volume through telemedicine-contracted molecular pathologists. |
| Software Companion Development | AI-assisted variant classification pipelines differentiate cloud-native bioinformatics offerings for molecular tumor boards. |
| Reimbursement Strategy | CMS coverage determinations for broad-panel profiling and minimal residual disease monitoring unlock clinical volume. |
Research Methodology
Document review covered FDA 510(k) and PMA filings, EMA scientific advice letters, NMPA registration databases, and CMS national coverage determinations, complemented by interviews with molecular pathologists, diagnostic laboratory operations directors, pharmaceutical biomarker strategy leads, and hospital GPO contracts managers. Secondary sources included ClinicalTrials.gov genomic biomarker protocols, SEC 10-K instrument revenue disclosures, and EU IVDR notified body guidance documents. Bottom-up sequencing platform placement data triangulated against top-down precision oncology infrastructure investment flows.
Historical instrument shipment patterns cross-referenced against panel input from reimbursement policy specialists and regulatory affairs consultants. Segmentation dimensions modeled encompassed product architecture, clinical application, end-user procurement sophistication, and deployment infrastructure configuration across the projection horizon. CAGRs derived from elasticity-adjusted adoption curves and price trajectory assumptions for consumables and software layers. Forecast inputs incorporated NMPA review timeline compression effects and EU IVDR implementation cost pass-through rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CMS coverage expansion decisions, FDA enforcement discretion policy shifts, and CRISPR diagnostic platform technical maturation. Practitioners should monitor NMPA accelerated approval volumes, EU IVDR notified body capacity constraints, and long-read sequencing clinical validation milestones for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Peritoneal Cancer Treatment Market
Oncology
PD1 Non-Small Cell Lung Cancer Treatment Market
Oncology
Europe Proton Therapy Market
Oncology
Vulvar Cancer Market
Oncology
Angiosarcomas Treatment Market
Oncology
Solid Tumor Market
Oncology
America Cancer Immunotherapy Market
Oncology
North America Bone Metastasis Market
Oncology
Colorectal Cancer Treatment Market
Oncology
Esophageal Cancer Drugs Market
Oncology
Global Skin Cancer Diagnostics and Therapeutics Market
Oncology
Glottic Cancer Treatment Market
Oncology
Europe Tumor Ablation Market
Oncology
Epithelial Ovarian Cancer Market
Oncology
Tumor Embolization Market
Oncology
Liposarcoma Treatment Market