
 Non-Small Cell Lung Carcinoma (NSCLC) Market | 2026-2036
Non-Small Cell Lung Carcinoma (NSCLC) Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Small Cell Lung Carcinoma (NSCLC) Market Analytics
Modular combination regimens is rebalancing how oncologists sequence first-line and second-line interventions across academic medical centers. F. Hoffmann-La Roche Ltd. anchors its position through companion diagnostic bundling with programmed death-ligand 1 assays. Merck & Co., Inc. dominates the checkpoint inhibitor segment with broad non-small cell lung carcinoma labeling across histologies and lines of therapy. Bristol Myers Squibb leverages dual immunotherapy combinations to differentiate its portfolio in competitive treatment settings.
Non-small cell lung carcinoma comprises adenocarcinoma, squamous cell carcinoma, and large cell carcinoma subtypes distinguished by histopathological morphology and molecular driver profiles. The disease arises from epithelial cell mutations in lung tissue, with treatment selection governed by programmed death-ligand 1 expression levels, epidermal growth factor receptor alterations, anaplastic lymphoma kinase rearrangements, and other actionable biomarkers. Immunotherapy commands the largest revenue pool among therapy areas as checkpoint inhibitors displace chemotherapy in front-line settings across major markets. Targeted therapy segments for epidermal growth factor receptor and anaplastic lymphoma kinase alterations sustain premium pricing through oral delivery modes that shift administration from infusion centers to outpatient settings.
FDA accelerated approval pathways and EMA conditional marketing authorization frameworks compress development timelines for breakthrough oncology therapies while demanding confirmatory evidence from post-marketing studies. The European Medicines Agency's Committee for Medicinal Products for Human Use and the FDA's Oncology Center of Excellence increasingly harmonize biomarker qualification standards to streamline multinational clinical trial design. Stakeholders must monitor evolving reimbursement criteria for combination regimens as health technology assessment bodies in Germany, France, and England tighten cost-effectiveness thresholds for incremental survival gains.
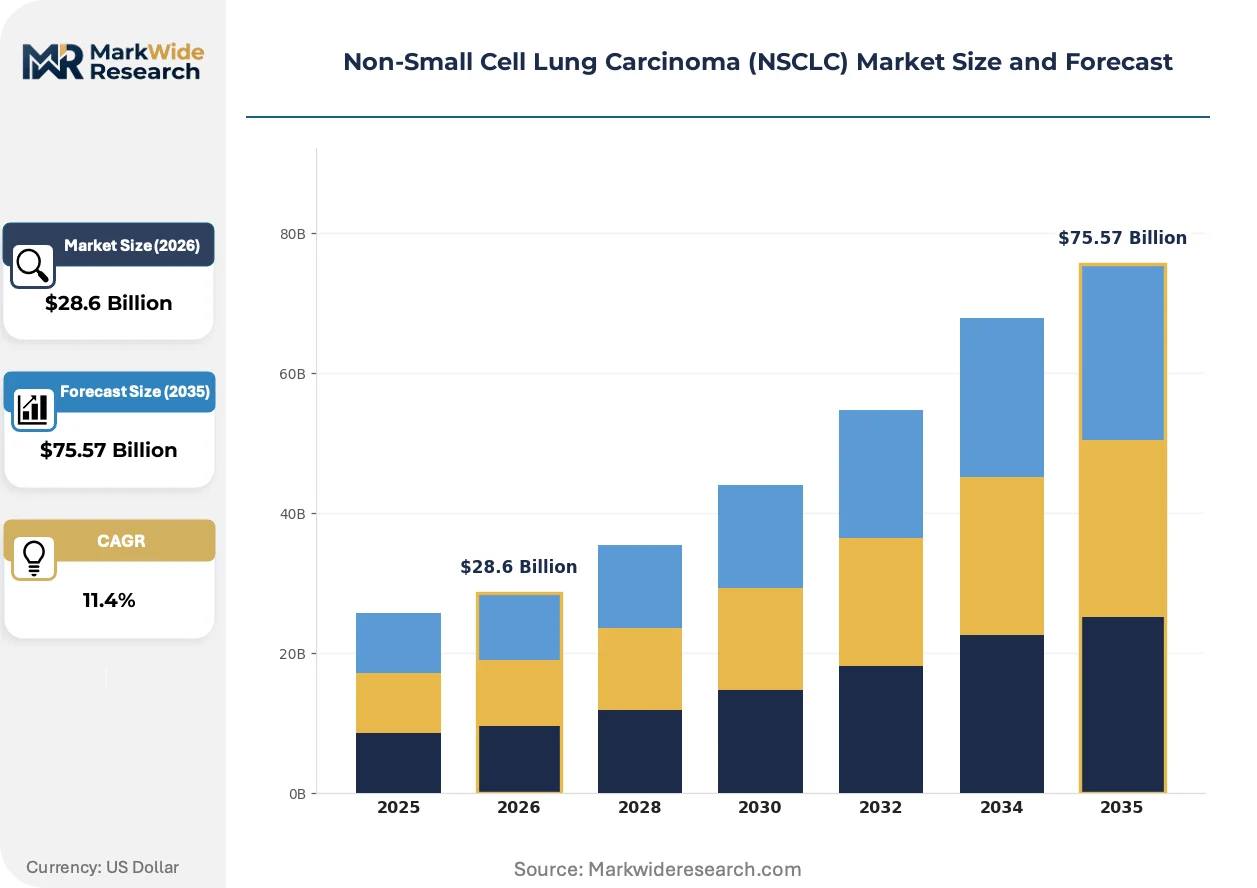
Market Dynamics
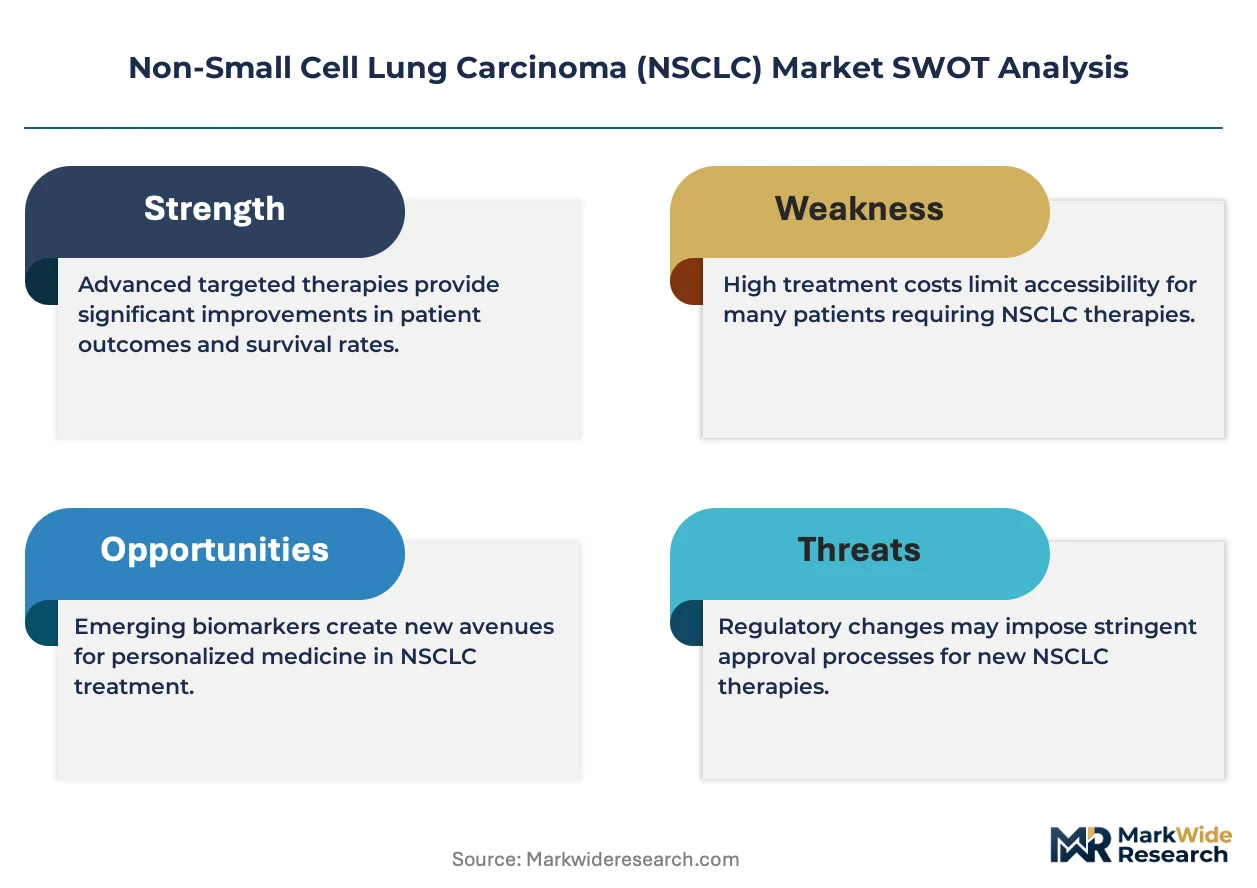
FDA and EMA accelerated approval pathways compress development timelines for checkpoint inhibitors, forcing sponsors to generate confirmatory evidence faster while expanding biomarker-qualified patient populations. This regulatory velocity is redrawing competitive moats around companion diagnostic capabilities and real-world evidence generation infrastructure.
Growth Catalysts
- Biomarker-guided protocols:PD-L1 expression testing and next-generation sequencing now standardize first-line treatment selection across academic medical centers in the United States and Western Europe.
- IRA Medicare price negotiation:The Inflation Reduction Act's oncology provisions are accelerating patient access timelines for approved immunotherapies in Medicare populations.
- Oral targeted therapy expansion:EGFR and ALK inhibitors shift administration from infusion centers to outpatient settings, expanding addressable patient pools beyond hospital catchment areas.
Market Restraints
- Checkpoint inhibitor manufacturing concentration:Bioreactor capacity for monoclonal antibody production concentrates among contract manufacturers in Switzerland and Ireland, creating supply vulnerability.
- Health technology assessment tightening:Germany's IQWiG and England's NICE are rejecting combination regimens failing to demonstrate incremental survival gains against cost-effectiveness thresholds.
- Tissue biopsy dependency:Insufficient tumor sample volume limits comprehensive biomarker profiling in 30-40% of advanced-stage presentations, restricting precision therapy eligibility.
Strategic Opportunities
- Plasma-based liquid biopsy:Circulating tumor DNA testing enables real-time resistance monitoring without repeat tissue sampling, opening longitudinal therapy optimization revenue streams.
- Neoadjuvant immunotherapy:Pre-surgical checkpoint blockade in resectable disease creates new addressable populations previously managed with chemotherapy alone.
- China's precision oncology infrastructure:National reimbursement expansion for molecular diagnostics is scaling biomarker testing penetration in tier-one hospital networks.
Industry Challenges
- Biomarker assay harmonization:Discordant PD-L1 scoring between 22C3, 28-8, SP142, and SP263 antibodies complicates clinical trial enrollment and therapy selection across sites.
- Real-world evidence generation:Post-marketing confirmatory study requirements demand electronic health record integration and long-term follow-up infrastructure that stretches sponsor data science capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Small Cell Lung Carcinoma (NSCLC) Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Immunotherapy, Targeted Therapy, Chemotherapy, Radiation Therapy Application: Diagnosis, Treatment, Monitoring, Patient Support Delivery Mode: Oral, Injectable, Intravenous, Combination Therapy End User: Hospitals, Research Laboratories, Specialty Clinics, Homecare Providers |
| Companies Covered | F. Hoffmann-La Roche Ltd., Merck & Co., Inc., Bristol Myers Squibb, AstraZeneca, Novartis AG, Pfizer Inc., Eli Lilly and Company, Sanofi, Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Small Cell Lung Carcinoma (NSCLC) Market Evolving Landscape
Checkpoint inhibitor development is converging with artificial intelligence-enabled patient selection, compressing trial enrollment timelines while raising the bar for mechanistic differentiation. Three forces are actively restructuring how value is captured across the therapy lifecycle.
Artificial intelligence platforms analyze radiomic features and electronic health record data to predict immunotherapy response before treatment initiation. Memorial Sloan Kettering and MD Anderson are deploying these tools to stratify trial populations and reduce screening failure rates. This capability is converging with decentralized clinical trial models to expand geographic reach beyond traditional academic centers.
The FDA's Project Optimus is mandating dose-optimization studies for oncology drugs, moving away from maximum tolerated dose paradigms toward exposure-response relationships. Sponsors must now conduct randomized dose-ranging trials that extend development timelines but potentially expand labeled populations. Small-molecule targeted therapy developers are most affected, reformulating clinical pharmacology strategies to satisfy this evidentiary standard.
Hospital systems are consolidating oncology service line purchasing through specialty pharmacy carve-outs and 340B program optimization. Community oncology practices in the United States are affiliating with hospital networks to access discounted drug acquisition costs, shifting site-of-care economics toward infusion center consolidation. This reconfiguration is most visible in Texas and Florida, where private equity-backed practice aggregation has concentrated regional market influence.
Non-Small Cell Lung Carcinoma (NSCLC) Market Segmentation
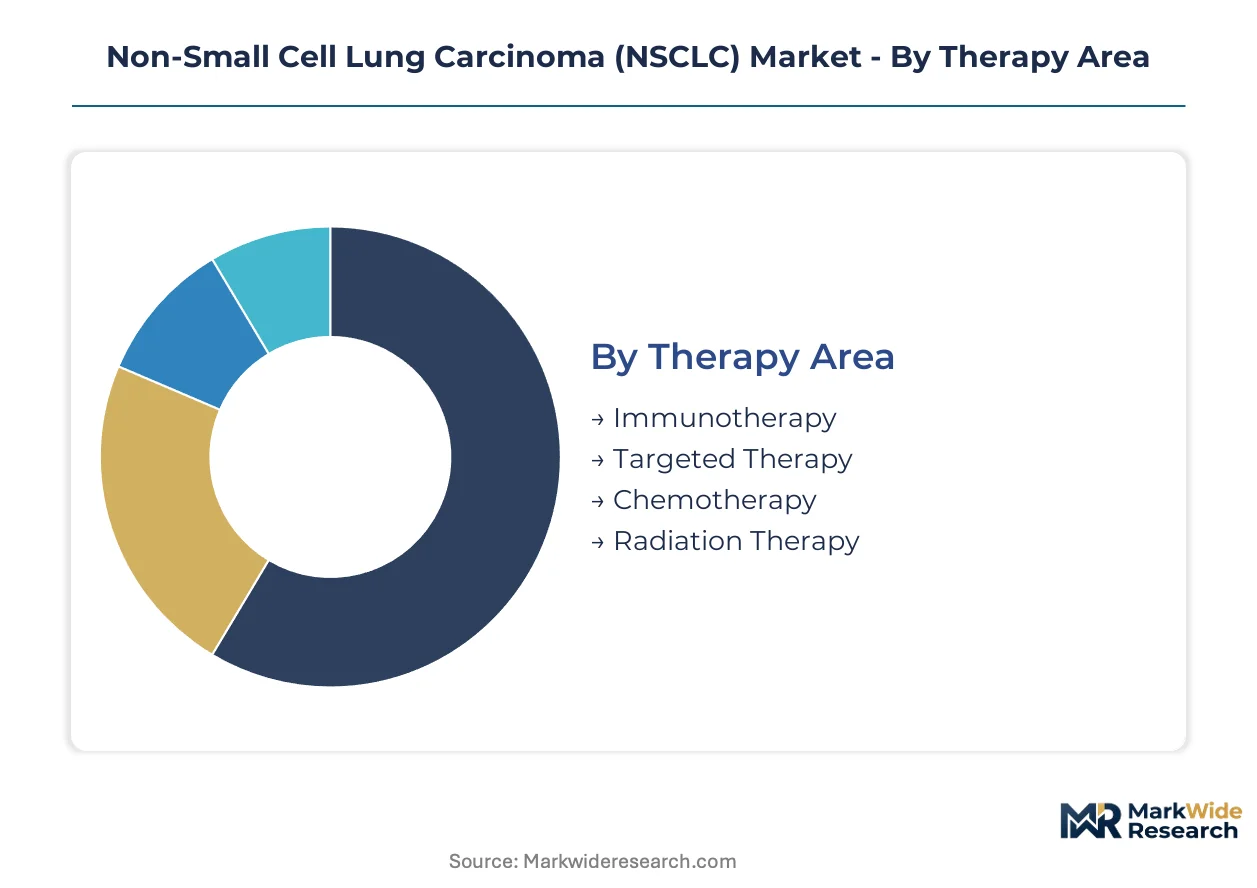
NSCLC market segmentation reflects divergent capital requirements across therapy modalities and care delivery settings. Biologics manufacturing demands billion-dollar bioreactor investments while oral targeted therapies shift value toward companion diagnostics and distribution infrastructure.
Therapy Area:
Capital intensity peaks with immunotherapy manufacturing, where monoclonal antibody production requires dedicated bioreactor networks and cold-chain logistics at scale.
- Immunotherapy:Checkpoint inhibitors targeting PD-1/PD-L1 pathways command premium pricing through infusion-based delivery. Demand concentrates in United States academic medical centers where biomarker testing infrastructure supports patient selection protocols.
- Targeted Therapy:Small-molecule inhibitors against EGFR, ALK, and emerging driver mutations enable oral administration. Germany and Japan are scaling reimbursement for next-generation sequencing that identifies actionable alterations.
- Chemotherapy:Platinum-based regimens retain utility in biomarker-negative populations and resource-constrained settings. Generic competition has compressed margins, redirecting investment toward supportive care agents.
- Radiation Therapy:External beam and stereotactic ablative modalities integrate with systemic therapy in locally advanced disease. Proton center construction in Texas and Florida reflects site-of-care consolidation trends.
Immunotherapy absorbs the bulk of installed capacity; targeted therapy is expanding most quickly.
Application:
Revenue distribution follows the patient journey from molecular profiling through longitudinal disease management.
- Treatment:Systemic therapy administration generates recurring revenue through dosing cycles. Hospital outpatient departments in China and Japan are expanding infusion capacity to accommodate immunotherapy volume.
- Diagnosis:Tissue-based and liquid biopsy platforms determine therapy eligibility. The FDA and EMA harmonization of PD-L1 assay standards is streamlining companion diagnostic development.
- Monitoring:Circulating tumor DNA surveillance tracks treatment response and resistance emergence. United States payers are piloting coverage for serial testing in metastatic settings.
- Patient Support:Adherence programs and toxicity management services differentiate branded offerings. Specialty pharmacy networks in England are integrating nurse navigator functions.
Treatment captures dominant revenue share; diagnosis is climbing the fastest as testing penetration deepens.
Delivery Mode:
Administration economics reshape competitive positioning between hospital-based infusion and ambulatory oral therapy.
- Intravenous:Infusion center capacity constraints in United States urban markets are extending appointment lead times. Academic medical centers are expanding satellite facilities to decompress main campus volumes.
- Oral:Pharmacy benefit management integration enables home-based administration with remote monitoring. Japan's reimbursement expansion for EGFR inhibitors is accelerating outpatient conversion.
- Injectable:Subcutaneous checkpoint inhibitor formulations reduce administration time and facility burden. The FDA's approval of subcutaneous pembrolizumab is pressuring infusion center economics.
- Combination Therapy:Sequenced or concurrent multimodal protocols require care coordination infrastructure. Germany's oncology networks are standardizing multidisciplinary tumor board protocols.
Intravenous retains the largest installed base; oral is gaining share fastest through patient convenience and site-of-care shift.
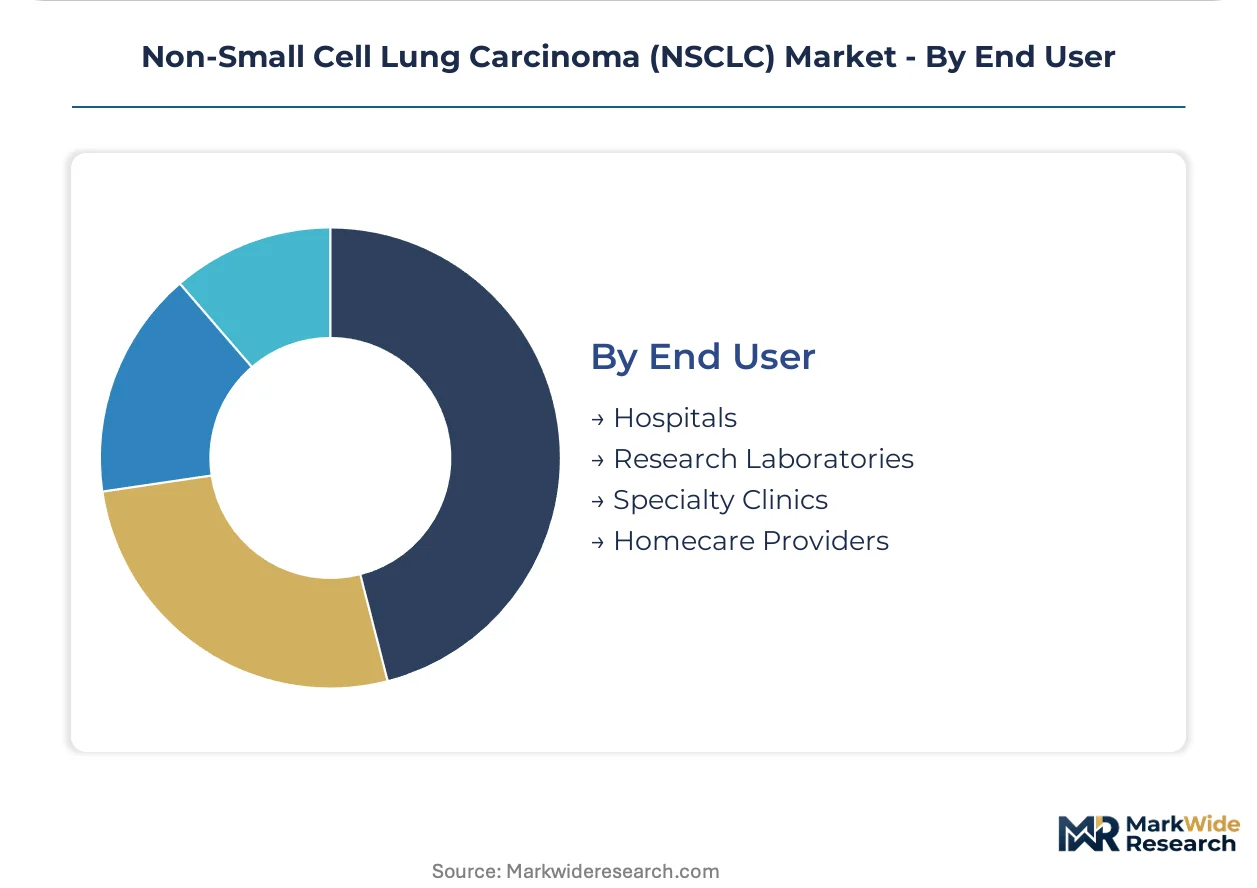
End User:
Customer concentration varies by therapy complexity and reimbursement pathway.
- Hospitals:Integrated delivery networks capture 340B pricing advantages and specialty pharmacy carve-outs. Texas and Florida health systems are aggregating community oncology practices to consolidate purchasing.
- Specialty Clinics:Community oncology practices affiliate with hospital networks to access discounted acquisition costs. United States private equity-backed consolidation is concentrating regional market influence.
- Research Laboratories:Centralized reference labs process next-generation sequencing for community settings. China's tier-one hospital networks are building in-house molecular pathology capabilities.
- Homecare Providers:Oral therapy expansion enables remote administration with telehealth monitoring. England's NHS is piloting home delivery for stable patients on targeted agents.
Hospitals command the dominant share of infused therapy volume; specialty clinics are restructuring fastest through network affiliation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics manufacturing concentrates in Switzerland and Ireland while demand concentrates in the United States, China, and Japan. This production-consumption divide shapes supply chain risk and pricing power across major markets.
United States
Oncology centers in Texas and Florida are consolidating community practices through private equity-backed aggregation. The FDA's Oncology Center of Excellence accelerates checkpoint inhibitor approvals through breakthrough therapy designation. Memorial Sloan Kettering and MD Anderson anchor biomarker-guided protocol development in New York and Houston.
China
Tier-one hospital networks in Beijing and Shanghai are scaling precision oncology infrastructure with national reimbursement expansion for molecular diagnostics. The NMPA aligns with FDA biomarker qualification standards to streamline multinational trial enrollment. Yangtze River Delta medical centers are building in-house next-generation sequencing capabilities.
Germany
IQWiG cost-effectiveness thresholds are tightening reimbursement for combination regimens lacking incremental survival gains. The EMA's Committee for Medicinal Products for Human Use harmonizes PD-L1 assay standards with FDA frameworks. Bavaria's oncology networks standardize multidisciplinary tumor board protocols across Munich and Nuremberg clusters.
Japan
Reimbursement expansion for EGFR inhibitors is accelerating outpatient conversion from infusion centers. The PMDA participates in FDA-EMA harmonization initiatives for companion diagnostic qualification. Kanto region hospitals in Tokyo are expanding satellite infusion capacity to decompress main campus volumes.
Switzerland
Contract manufacturing bioreactor capacity for monoclonal antibodies concentrates among Basel-area facilities. Swissmedic maintains alignment with EMA accelerated approval pathways for breakthrough oncology therapies. The country's precision medicine ecosystem supports companion diagnostic bundling with immunotherapy development.
Non-Small Cell Lung Carcinoma (NSCLC) Market Competitive Landscape
The competitive structure tilts toward integrated biopharmaceutical conglomerates with companion diagnostic capabilities. Checkpoint inhibitor development demands billion-dollar bioreactor networks and cold-chain logistics that exclude smaller entrants. Two strategic archetypes dominate: diversified conglomerates bundling diagnostics with therapeutics, and oncology-focused specialists leveraging dual immunotherapy combinations. Consolidation moves center on specialty pharmacy carve-outs and 340B program optimization in United States hospital systems.
Among Swiss and German pharmaceutical conglomerates, F. Hoffmann-La Roche Ltd. and Novartis AG occupy positions emphasizing diagnostic-therapeutic integration. United States-based oncology specialists Merck & Co., Inc. and Bristol Myers Squibb exemplify checkpoint inhibitor portfolio scale across histologies and lines of therapy. These three anchors represent divergent competitive vectors: diagnostic bundling, broad labeling dominance, and dual immunotherapy differentiation.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Merck & Co., Inc. |
| Bristol Myers Squibb |
| AstraZeneca |
| Novartis AG |
| Pfizer Inc. |
| Eli Lilly and Company |
| Sanofi |
| Amgen Inc. |
| Others |
Value Network & Pricing Analysis
Captive bioreactor networks in Switzerland and Ireland anchor monoclonal antibody supply positions while concentrating pricing power among contract manufacturers serving checkpoint inhibitor developers. This integration pattern locks in premium manufacturing margins and creates tiered access economics between biologics innovators and oral targeted therapy competitors.
Pricing Analysis
Margin tightening in immunotherapy reflects health technology assessment tightening across Germany, France, and England as IQWiG and NICE reject combination regimens lacking incremental survival gains. Three-tier pricing structure across premium checkpoint inhibitors, standard targeted therapies, and economy chemotherapy generics separates infusion-based biologics from oral small molecules. Cost-down pressure on platinum-based regimens accelerates because generic competition has compressed margins to commodity levels. Community oncology practices in Texas and Florida exhibit highest price sensitivity due to 340B program dependency, while academic medical centers in New York and Houston demonstrate lowest sensitivity through bundled diagnostic-therapeutic contracts.
Supply Chain Analysis
Regional distribution centers in Switzerland, Ireland, and the United States maintain hub-and-spoke cold-chain patterns for monoclonal antibody finished goods. Bioreactor capacity concentrates among Basel-area facilities and Irish contract manufacturing organizations while active pharmaceutical ingredients for small-molecule inhibitors source from India and China. Single-source vulnerability in monoclonal antibody production creates supply risk given limited qualified alternative sites. Distribution runs through hospital-based infusion centers in the United States and specialty pharmacy networks in England, with oral therapies shifting toward homecare delivery models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Checkpoint inhibitor development operates as a cost-of-compliance story where FDA's Project Optimus dose-optimization mandates and EMA confirmatory evidence requirements erect billion-dollar barrier-to-entry moats that protect compliant incumbents.
For Market Incumbents: Hedge against biosimilar entry by deepening companion diagnostic bundling with PD-L1 assays and circulating tumor DNA platforms. Secure bioreactor capacity additions in Switzerland and Ireland through long-term manufacturing agreements before contract manufacturing organization constraints tighten. Counter margin pressure from health technology assessment tightening by generating real-world evidence through electronic health record integration at Memorial Sloan Kettering and MD Anderson.
For New Entrants and Emerging Players: The mid-tier pricing gap between premium checkpoint inhibitors and economy chemotherapy creates white-space opportunity for subcutaneous formulations and neoadjuvant immunotherapy protocols. Plasma-based liquid biopsy monitoring represents the most penetrable segment given insufficient tumor sample volume restricts precision therapy eligibility in 30-40% of advanced-stage presentations. Pursue go-to-market angles through China's tier-one hospital networks where national reimbursement expansion for molecular diagnostics is scaling biomarker testing penetration.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty pharmacy carve-outs and 340B program optimization plays across Texas and Florida health systems. Long-term viability favors integrated biopharmaceutical conglomerates with captive diagnostic capabilities over pure-play oncology specialists lacking companion diagnostic infrastructure. Watch FDA-EMA harmonization progress on biomarker qualification standards as the inflection indicator for multinational clinical trial economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Bundling | Roche's PD-L1 assay integration locks in therapy selection protocols across academic medical centers. |
| Subcutaneous Formulation Development | Merck's pembrolizumab subcutaneous approval pressures infusion center economics and extends site-of-care reach. |
| Liquid Biopsy Platform Expansion | Circulating tumor DNA surveillance enables longitudinal revenue streams beyond initial therapy selection. |
| Neoadjuvant Protocol Establishment | Pre-surgical checkpoint blockade creates addressable populations previously managed with chemotherapy alone. |
| China Precision Oncology Infrastructure | NMPA alignment with FDA standards streamlines multinational trial enrollment in tier-one hospital networks. |
Research Methodology
Document review covered FDA accelerated approval filings, EMA conditional marketing authorization decisions, ClinicalTrials.gov protocol registrations, and formulary database entries, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from SEC 10-K oncology segment disclosures, CMS Medicare reimbursement data, and health technology assessment publications. Bottom-up patient-flow modeling and top-down revenue triangulation cross-referenced manufacturer reported sales with payer claims data.
Cross-referencing historical approval timelines against expert panel input on development cycle compression shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include therapy modality, treatment line, administration route, biomarker qualification status, and regional regulatory cluster. CAGRs were derived from patient incidence projections, therapy penetration curves, and pricing trajectory assumptions. Forecast inputs incorporated biomarker testing penetration rates in China and Japan, and health technology assessment rejection probabilities in Germany and England.
Inputs from FDA and EMA regulatory databases were available through the study window; gaps in post-marketing confirmatory study completion rates introduce uncertainty bands around long-term checkpoint inhibitor revenue sustainability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Musculoskeletal Oncology Therapeutics Market
Oncology
Lung Cancer Treatment Market
Oncology
Ovarian Cancer Market
Oncology
Liposarcoma Treatment Market
Oncology
Europe Radiotherapy Patient Positioning Market
Oncology
Bone Cancer Treatment Market
Oncology
Europe Tumor Ablation Market
Oncology
Low-Grade Central Osteosarcoma Treatment Market
Oncology
Internal Radiation Therapy Market
Oncology
Bone Cancer Market
Oncology
Sterile Oncology Injectable Market
Oncology
Immuno-Oncology Market
Oncology
Europe Proton Therapy Market
Oncology
Asia-Pacific Proton Therapy Market
Oncology
Australia Cancer Treatment Market
Oncology
Metastatic Cancer Drug Market