
 Asia-Pacific Proton Therapy Market | 2026-2036
Asia-Pacific Proton Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Proton Therapy Market Insights
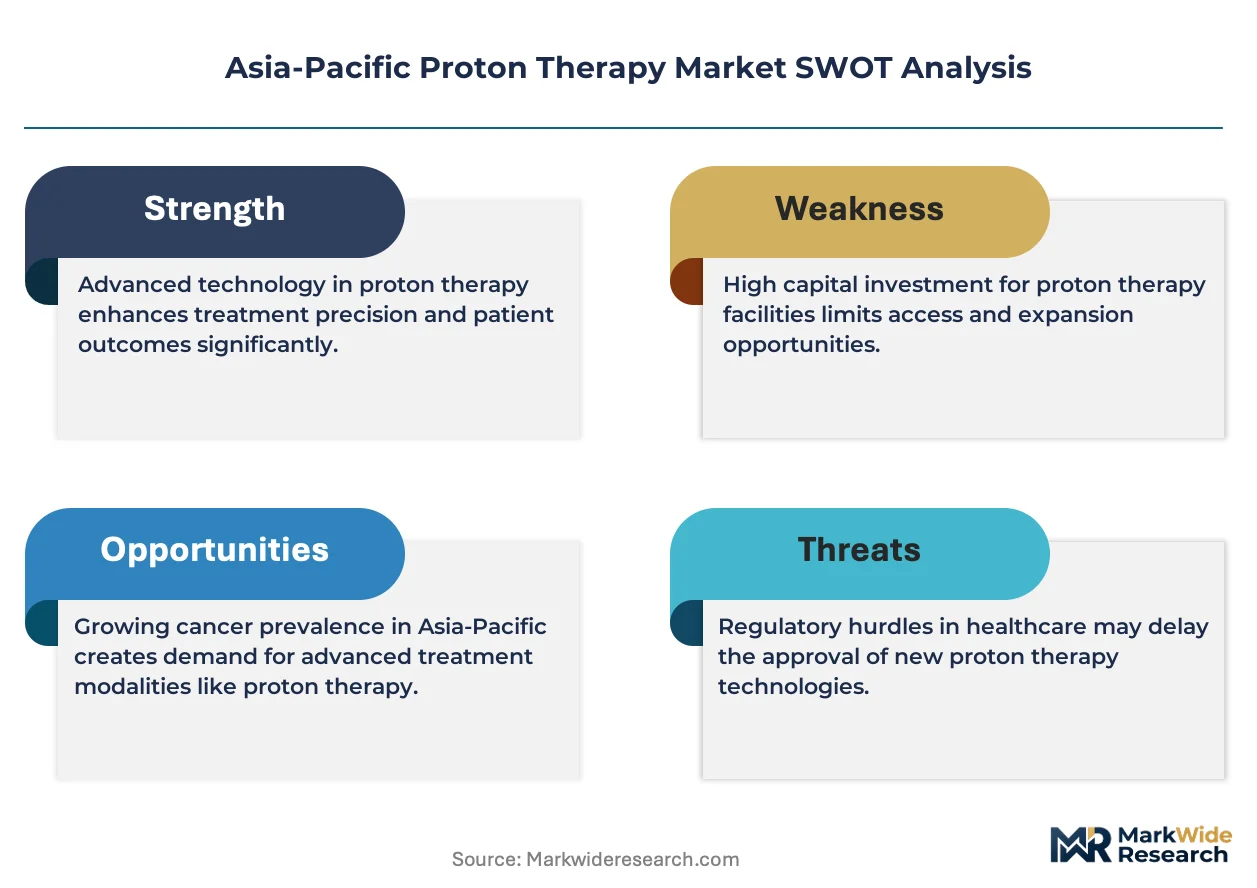
China's hospital infrastructure build-out is reconfiguring proton therapy access across the Asia-Pacific region. Hitachi, Ltd. leverages its superconducting synchrotron technology to anchor high-throughput installations in Japanese university hospitals. Sumitomo Heavy Industries, Ltd. competes through compact single-room systems designed for space-constrained urban oncology centers. Siemens Healthineers AG differentiates via integrated imaging-proton workflow platforms that streamline treatment planning.
Proton therapy delivers precisely targeted radiation using accelerated proton beams that release peak energy at a calculated depth within tissue, sparing surrounding healthy structures through the Bragg peak effect. Compact Systems dominate current procurement budgets as hospitals prioritize lower capital footprints and faster installation timelines. Pencil Beam Scanning represents the fastest-growing technology segment, displacing Passive Scattering in new installations due to superior dose conformity for complex tumor geometries. Brain Tumors and Pediatric Cancer applications command premium system configurations because these cases demand the highest precision to protect developing or critical tissues.
Japan's Ministry of Health, Labour and Welfare reimbursement policies and South Korea's MFDS medical device licensing frameworks shape product standards and market access timelines for proton system vendors. China's NMPA approval pathways for imported radiotherapy equipment create additional regulatory filtration that favors established multinationals with localized clinical evidence portfolios. Stakeholders must monitor reimbursement expansion decisions in Southeast Asian national health insurance schemes, as these determinations will dictate whether proton therapy remains concentrated in Northeast Asian tier-one cities or disperses across broader Asia-Pacific patient populations.
Market Dynamics
Pencil Beam Scanning technology is compressing treatment timelines while Japan's Ministry of Health, Labour and Welfare reimbursement expansion is pulling capital into metropolitan hospital clusters across Tokyo, Seoul, and Shanghai.
Growth Catalysts
- Reimbursement Policy Expansion:Japan's Ministry of Health, Labour and Welfare proton therapy approvals are accelerating facility investments in university hospitals. Pediatric oncology demand is concentrating procurement decisions.
- Technology Convergence:Integrated imaging-proton workflow platforms are streamlining treatment planning for brain tumor applications. Multi-room system deployments are rising in metropolitan clusters.
- Compact System Design:Space-constrained urban oncology centers across Seoul and Shanghai are prioritizing single-room configurations. Faster installation timelines are unlocking previously inaccessible hospital real estate.
Market Restraints
- Capital Intensity Barriers:Superconducting synchrotron equipment requires substantial upfront investment. Smaller municipal hospitals face exclusion from proton therapy networks.
- Regulatory Filtration:China's NMPA approval pathways for imported radiotherapy equipment create extended market access timelines. Localized clinical evidence requirements favor established portfolios.
- Input Concentration Risk:Heavy reliance on specialized superconducting magnet suppliers concentrates supply vulnerability. Disruptions affect installation schedules across Northeast Asia.
Strategic Opportunities
- Southeast Asian Penetration:National health insurance schemes in Thailand, Malaysia, and Vietnam remain undetermined on proton therapy coverage. Early regulatory engagement positions vendors for first-mover advantage.
- Pediatric Application Deepening:Developing tissue protection requirements in pediatric cancer cases are creating demand for premium precision configurations. Dedicated pediatric proton centers represent whitespace.
- Technology Hybridization:Artificial intelligence integration with treatment planning software is opening workflow efficiency gains. Machine learning dose optimization is attracting radiotherapy department investment.
Industry Challenges
- Specialized Workforce Scarcity:Certified medical physicists with proton therapy specialization are concentrated in Japan and South Korea. Training pipeline gaps constrain facility expansion timelines.
- Legacy System Integration:Hospital IT infrastructure heterogeneity complicates imaging-proton workflow platform deployment. Custom interface development extends commissioning phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Proton Therapy Market |
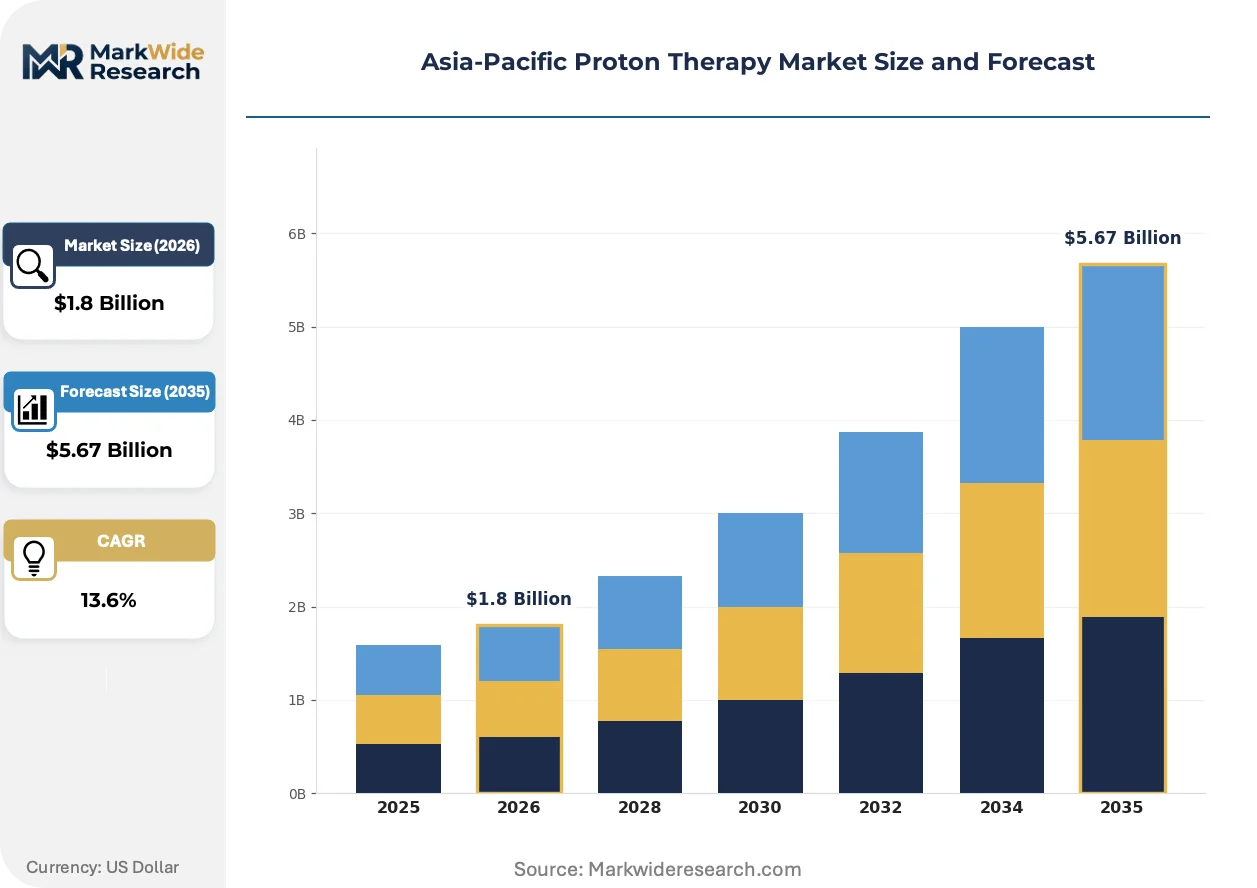
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.67 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Systems, Cyclotrons, Treatment Rooms, Control Systems End User: Hospitals, Research Institutes, Oncology Centers, Specialty Clinics Technology: Intensity-Modulated Proton Therapy, Pencil Beam Scanning, Passive Scattering, Spot Scanning Application: Brain Tumors, Pediatric Cancer, Breast Cancer, Head and Neck Cancer |
| Companies Covered | Hitachi, Ltd., Ion Beam Applications SA, Sumitomo Heavy Industries, Ltd., Mevion Medical Systems, Inc., Siemens Healthineers AG, Toshiba Corporation, Mitsubishi Electric Corporation, Provision Healthcare, Optivus Proton Therapy, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Proton Therapy Market Trends and Innovations
Proton therapy technology is converging with artificial intelligence and compact engineering, while reimbursement policy and procurement models are reconfiguring how capital flows into radiotherapy infrastructure across the region.
Intensity-modulated proton therapy is hybridizing with real-time imaging feedback to enable adaptive treatment delivery. Major oncology centers in Tokyo and Seoul are adopting these systems for complex cranial and spinal cases. The technology is compressing the gap between diagnostic imaging and therapeutic intervention, enabling same-day plan adjustments based on anatomical changes.
South Korea's MFDS medical device licensing frameworks are tightening clinical evidence requirements for imported proton systems. Domestic manufacturers are accelerating indigenous superconducting cyclotron development to bypass import dependency. Japanese university hospitals are responding by deepening collaboration with domestic vendors on next-generation beam delivery systems.
Hospital procurement committees are unbundling equipment purchase from long-term service contracts, forcing vendors to compete on discrete performance metrics. Metropolitan cancer centers in Shanghai are leading this shift, separating hardware acquisition from physics support and maintenance obligations. This fragmentation is pressuring traditional bundled pricing models and creating openings for specialized service providers.
Asia-Pacific Proton Therapy Market Segmentation
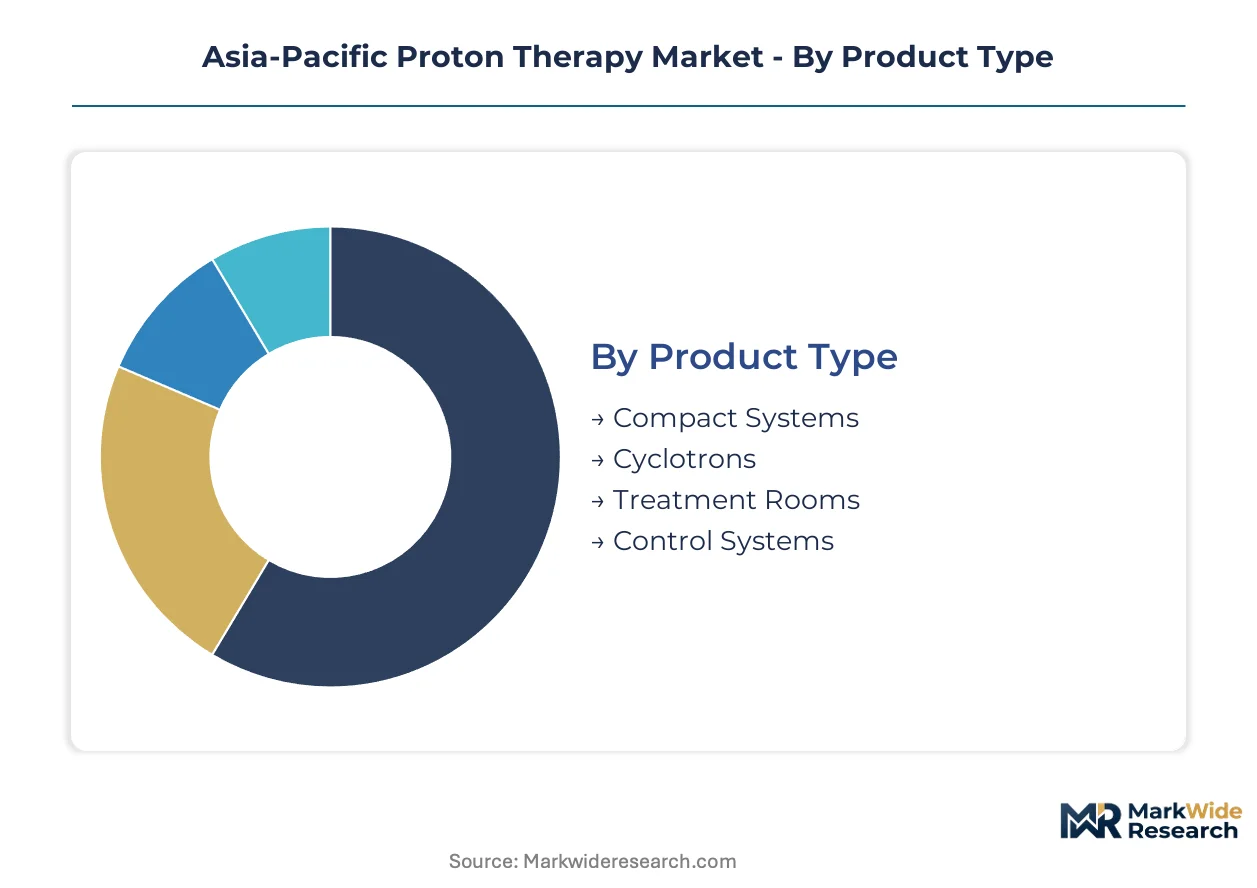
Proton therapy segmentation reveals distinct procurement rhythms across hardware, software, and service layers. Equipment categories cycle through capital planning horizons measured in years, while technology segments turn over as treatment protocols evolve and reimbursement policies mature.
Product Type:
Cyclotrons and treatment rooms carry extended procurement cycles spanning multiple fiscal years, while compact systems and control systems refresh on compressed timelines driven by software upgrade schedules and space-constrained installation demands.
- Compact Systems:Single-room configurations integrate superconducting synchrotron technology into reduced footprints. Seoul and Shanghai metropolitan hospitals prioritize these systems for space-constrained urban oncology centers where real estate premiums dominate capital planning.
- Treatment Rooms:Multi-room installations anchor high-throughput university hospital deployments in Tokyo and Osaka. Japan's Ministry of Health, Labour and Welfare reimbursement expansion is accelerating dedicated room construction for pediatric cancer protocols.
- Cyclotrons:Particle acceleration infrastructure requiring substantial shielding and civil works.
- Control Systems:Software-hardware interfaces governing beam delivery and patient positioning.
Compact Systems anchors the volume base while Treatment Rooms gains share at the steepest rate.
End User:
Procurement authority concentrates differently across institutional types, with university hospitals commanding multi-room system budgets while specialty clinics drive compact single-room demand.
- Oncology Centers:Dedicated cancer facilities in Tokyo, Seoul, and Shanghai metropolitan clusters deploy multi-room configurations for high patient throughput. Japan's Ministry of Health, Labour and Welfare reimbursement approvals are concentrating capital deployment in these specialized institutions.
- Hospitals:General acute-care institutions with embedded radiotherapy departments represent the broadest installed base across the Asia-Pacific region. China's NMPA approval pathways for imported radiotherapy equipment shape procurement timelines for hospital-based systems.
- Research Institutes:Academic medical centers advancing beam delivery protocols and clinical trial infrastructure.
- Specialty Clinics:Focused outpatient facilities prioritizing single-room compact configurations for specific tumor types.
Hospitals anchors the volume base while Oncology Centers expands most quickly.
Technology:
Beam delivery methods stratify sharply by dose conformity requirements, with advanced scanning technologies displacing legacy scattering approaches in new installations.
- Pencil Beam Scanning:Magnetically steered proton beams deposit dose in discrete spots with superior conformity for complex tumor geometries. Brain tumor and pediatric cancer applications in Japanese university hospitals are driving displacement of Passive Scattering installations.
- Intensity-Modulated Proton Therapy:Layered spot delivery enables dose painting across irregular tumor volumes. South Korea's MFDS medical device licensing frameworks are tightening clinical evidence requirements for these advanced systems.
- Passive Scattering:Physical beam modulation using scatterers and compensators in legacy installations.
- Spot Scanning:Discrete spot-based delivery with reduced neutron contamination relative to scattering methods.
Passive Scattering anchors the volume base while Pencil Beam Scanning climbs the fastest.
Application:
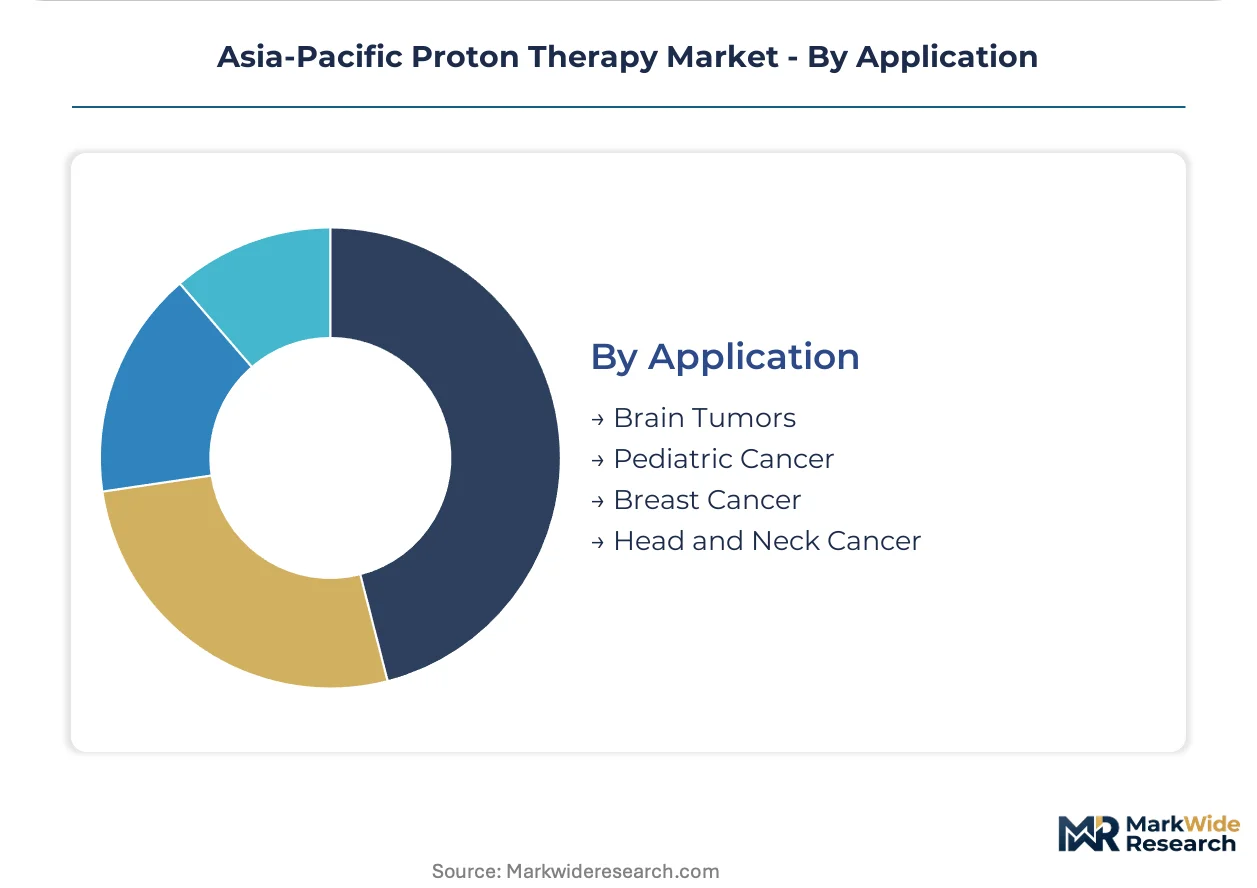
Tumor site selection dictates system configuration premiums, with developing tissue and critical organ proximity driving precision requirements.
- Pediatric Cancer:Developing tissue protection requirements mandate the highest precision configurations to spare growing organs. Dedicated pediatric proton centers in Tokyo and Seoul represent whitespace expansion opportunities with premium equipment specifications.
- Brain Tumors:Cranial and spinal cases demand millimeter-scale accuracy to preserve neurological function. Intensity-modulated proton therapy hybridized with real-time imaging feedback is compressing treatment timelines for these applications in major oncology centers.
- Breast Cancer:Cardiac-sparing potential drives proton adoption versus conventional radiotherapy.
- Head and Neck Cancer:Complex anatomical proximity to critical structures benefits from Bragg peak dose deposition.
Breast Cancer anchors the volume base while Pediatric Cancer gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Superconducting synchrotron manufacturing concentrates in Japan and South Korea, with metropolitan hospital clusters in Tokyo, Seoul, and Shanghai absorbing the majority of system deployments. Japan's Ministry of Health, Labour and Welfare reimbursement policies and South Korea's MFDS frameworks are accelerating facility investments across Northeast Asia.
Japan
University hospitals in Tokyo and Osaka are expanding multi-room installations for pediatric cancer protocols. The Ministry of Health, Labour and Welfare has broadened proton therapy reimbursement categories, pulling capital into metropolitan oncology centers. Kanto and Kansai regions host the densest concentration of operational facilities, with dedicated pediatric proton centers representing whitespace opportunities.
South Korea
Seoul metropolitan hospitals prioritize compact single-room systems for space-constrained urban oncology centers. MFDS medical device licensing frameworks are tightening clinical evidence requirements for imported proton systems, accelerating indigenous superconducting cyclotron development. The Seoul Capital Area commands premium system configurations for brain tumor and pediatric applications.
China
Shanghai and Beijing-Tianjin-Hebei clusters are driving multi-room system procurement for high-throughput cancer centers. NMPA approval pathways for imported radiotherapy equipment create extended market access timelines favoring established multinationals with localized clinical evidence. Yangtze River Delta metropolitan hospitals are unbundling equipment purchase from long-term service contracts.
Australia
Sydney and Melbourne oncology centers are evaluating proton therapy feasibility for pediatric and central nervous system applications. The Therapeutic Goods Administration (TGA) regulates radiotherapy equipment imports, with clinical evidence requirements shaping vendor selection timelines. New South Wales and Victoria are assessing dedicated proton facility business cases against conventional radiotherapy expansion.
Singapore
National University Hospital and private oncology groups are exploring compact system deployments for high-value cancer cases. The Health Sciences Authority (HSA) medical device registration framework governs proton system market entry. The city-state's concentrated patient pool and premium healthcare positioning favor single-room configurations with fast installation timelines.
Asia-Pacific Proton Therapy Market Competitive Landscape
Integrated-system providers and compact-technology specialists split the market along capital-intensity and footprint-optimization vectors. Vendor concentration is moderate, with established multinationals holding advantages in regulatory navigation and clinical evidence portfolios. Two strategic archetypes dominate: superconducting synchrotron developers serving high-throughput university hospitals, and single-room system designers targeting space-constrained urban centers. Competitive positioning hinges on M&A activity to secure specialized superconducting magnet supply chains, and strategic partnerships with metropolitan hospital clusters for long-term service contracts.
Within the integrated-system tier, Hitachi, Ltd. and Siemens Healthineers AG exemplify divergent approaches to imaging-proton workflow convergence. Among compact-technology specialists, Sumitomo Heavy Industries, Ltd. occupies a position emphasizing reduced civil works and faster commissioning timelines. These three companies represent distinct archetypes—Japanese conglomerate-backed precision engineering, German healthcare technology integration, and industrial machinery diversification into medical applications—each anchoring different procurement committee priorities across the region's metropolitan hospital clusters.
| Leading Market Players |
|---|
| Hitachi, Ltd. |
| Ion Beam Applications SA |
| Sumitomo Heavy Industries, Ltd. |
| Mevion Medical Systems, Inc. |
| Siemens Healthineers AG |
| Toshiba Corporation |
| Mitsubishi Electric Corporation |
| Provision Healthcare |
| Optivus Proton Therapy, Inc. |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Japanese superconducting magnet manufacturers determines both pricing tier spreads and supply chain shape across the Asia-Pacific proton therapy market. Japan's Ministry of Health, Labour and Welfare reimbursement policies compress procurement timelines while concentrated input sourcing forces buyers into premium configurations or extended delivery schedules.
Pricing Analysis
Japan's Ministry of Health, Labour and Welfare reimbursement approvals dictate the pricing tier structure across metropolitan hospital clusters. Three-tier pricing structure across premium multi-room, standard compact, and economy refurbished installations separates university hospitals from urban oncology centers and municipal facilities. Price differentiation rests on beam delivery technology certification and after-sales physics support bundling. Cost compression in standard compact configurations is intensifying because Seoul and Shanghai procurement committees are unbundling hardware from service contracts. Municipal hospitals exhibit highest price sensitivity while pediatric-dedicated centers demonstrate lowest sensitivity due to tissue protection mandates.
Supply Chain Analysis
Export controls on superconducting synchrotron technology limit flows from Japan and South Korea to Chinese installations under NMPA review. Manufacturing concentrates in Japan, South Korea, and Germany for precision magnet assemblies, vacuum systems, and beamline components. Raw material dependencies include niobium-titanium superconducting wire, high-purity copper for RF cavities, and specialized steel alloys for shielding. Single-source vulnerability concentrates around cryogenic cooling system suppliers based in Osaka and Seoul. Distribution runs through direct vendor-hospital negotiations with multi-year commissioning phases rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific proton therapy market is recovering from reimbursement policy cyclicality. Japan's Ministry of Health, Labour and Welfare expansion of approved indications provides the cyclical anchor.
For Market Incumbents: Entrench superconducting synchrotron supply relationships through captive magnet production partnerships in Kanto region. Deepen pediatric protocol software development to defend against compact-system displacement. Lock long-term service contracts before Shanghai procurement committees complete unbundling transitions.
For New Entrants and Emerging Players: Dedicated pediatric proton centers in Southeast Asian capitals represent the most penetrable entry point where national health insurance schemes remain undetermined on coverage. Compact single-room configurations for brain tumor specialty clinics in Bangkok and Kuala Lumpur offer second white-space target. Pursue early regulatory engagement with Thailand's national health insurance administrators as go-to-market angle.
For Investors and Strategic Acquirers: Indigenous superconducting cyclotron developers in South Korea present acquisition targets with technology autonomy potential. Long-term viability frames around MFDS localization requirements and China's NMPA import substitution timeline. Monitor Southeast Asian national health insurance proton therapy coverage determinations as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Japan's Ministry of Health, Labour and Welfare pediatric protocol approvals accelerate facility commissioning timelines. |
| Hospital System Partnership | Metropolitan cancer centers in Shanghai unbundle procurement to separate hardware from physics support obligations. |
| Software Companion Development | Artificial intelligence treatment planning integration attracts radiotherapy department investment in Tokyo and Seoul. |
| CE Marking Pathway | European clinical evidence portfolios ease NMPA approval navigation for China market entry. |
| Backward Integration | Captive superconducting magnet production secures supply schedules against installation delays. |
Research Methodology
Cross-validation between primary interviews with proton therapy center directors and secondary validation through hospital procurement databases anchors the qualitative findings. Stakeholder roles included medical physicists, radiotherapy department heads, biomedical engineers, GPO contracts managers, and equipment procurement officers. Secondary sources comprised MFDS medical device licensing records, NMPA import approval filings, Japan's Ministry of Health, Labour and Welfare reimbursement bulletins, and CMS-equivalent hospital expenditure data. Bottom-up facility installation tracking and top-down healthcare infrastructure spending analysis provided triangulation.
Calibration against historical reimbursement policy cycles and capital deployment patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user institution, beam delivery technology, and tumor application. CAGRs derived from facility capacity expansion timelines weighted by reimbursement policy probability. Industry-specific inputs incorporated superconducting equipment lead times and pediatric protocol adoption curves.
Practitioners should monitor Southeast Asian national health insurance coverage determinations and MFDS localization requirements for early signals. Forecasts reflect assumptions around reimbursement policy continuity and superconducting magnet supply stability. Material shifts in Japan's Ministry of Health, Labour and Welfare pediatric indication approvals or export control tightening on synchrotron technology would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Global Interventional Oncology Market
Oncology
Global Non-Small Cell Lung Cancer (NSCLC) Market
Oncology
Europe Radiotherapy Patient Positioning Market
Oncology
Metastases Spinal Tumor Market
Oncology
Global HER-2 Negative Breast Cancer Market
Oncology
Europe Proton Therapy Market
Oncology
Musculoskeletal Oncology Therapeutics Market
Oncology
Global Veterinary Oncology Market
Oncology
Unresectable Hepatocellular Carcinoma Market
Oncology
Asia-Pacific Cancer Therapy Market
Oncology
Esophageal Cancer Drugs Market
Oncology
Vulvar Cancer Market
Oncology
Pancreatic Cancer Market
Oncology
Global Cancer Supportive Care Drugs Market
Oncology
US Radiation Oncology Market
Oncology
Head and Neck Cancer Drugs Market