
 Bone Cancer Treatment Market | 2026-2036
Bone Cancer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Cancer Treatment Market Analysis
Oncology service lines in academic medical centers is broadening as proton therapy and limb-salvage surgery displace older protocols. Pfizer Inc. leverages its kinase inhibitor portfolio to anchor positions in metastatic bone disease. Amgen Inc. specializes in osteoclast-targeting biologics for skeletal-related events. Novartis AG dominates radioligand therapy development for bone-seeking isotopes.
Bone cancer treatment encompasses systemic and localized interventions targeting primary bone tumors and skeletal metastases, employing cytotoxic agents, ionizing radiation, immune modulators, and receptor-directed small molecules to achieve local control, preserve function, and prolong survival. Chemotherapy retains the largest patient volume but carries well-documented toxicity burdens that limit dosing intensity in multimodal regimens. Immunotherapy represents the fastest-expanding segment as checkpoint inhibitors and CAR-T constructs enter sarcoma trials, though durable responses remain concentrated in specific histologic subtypes. Targeted therapy captures disproportionate R&D investment as FGFR, CDK4/6, and PARP inhibitors demonstrate biomarker-defined efficacy in chordoma and osteosarcoma subsets.
The FDA and EMA govern clinical trial design, pediatric investigation plans, and post-market pharmacovigilance for bone cancer therapeutics, while the IRA reshapes Medicare reimbursement for infused oncology drugs in the United States. REACH and the EU Green Deal impose escalating purity and waste-handling standards on radiopharmaceutical manufacturing in Europe, raising facility capital requirements. Stakeholders must weigh biomarker infrastructure investment against the contracting window for premium pricing in indication-constrained markets.
Market Dynamics
The bone cancer treatment market pivots on biomarker-driven patient stratification, as FDA and EMA pediatric oncology mandates force trial sponsors to abandon histology-only enrollment in favor of molecular profiling that compresses development timelines and reshapes competitive entry.
Growth Catalysts
- Immunotherapy pipeline maturation:Checkpoint inhibitors and CAR-T constructs for sarcoma subtypes are advancing through Phase II trials, pulling investment into combination regimens.
- Proton therapy center expansion:United States academic medical centers are multiplying dedicated sarcoma units, creating pull-through demand for integrated surgical and radiotherapy protocols.
- Radioligand therapy development:Bone-seeking isotopes targeting prostate and breast metastases are expanding into primary bone malignancies, broadening addressable indications.
Market Restraints
- Radiopharmaceutical manufacturing capital intensity:REACH and EU Green Deal purity standards require facility upgrades exceeding €50 million per site, concentrating European supply among three contract manufacturers.
- Biomarker infrastructure gaps:Community oncology practices lack next-generation sequencing capacity, fragmenting patient access to targeted trials outside tertiary centers.
- Chemotherapy toxicity ceilings:Dose-limiting myelosuppression in osteosarcoma regimens prevents intensification, capping survival gains from cytotoxic backbone therapy.
Strategic Opportunities
- Chordoma FGFR inhibitor expansion:Biomarker-defined subsets in skull-base and sacral tumors represent underserved populations with premium pricing potential.
- India CDSCO accelerated approval pathway:The country's national pharmaceutical regulator offers conditional marketing authorization for pediatric oncology drugs, enabling earlier revenue recognition.
- Telemedicine-enabled trial decentralization:Remote monitoring platforms are reducing geographic barriers to sarcoma specialty care, expanding recruitment beyond urban corridors.
Industry Challenges
- Paediatric Investigation Plan complexity:EMA requirements for age-appropriate formulation development add 18-24 months to regulatory timelines, straining smaller sponsors.
- Proton therapy workforce scarcity:Medical physicist and radiation oncologist training pipelines fail to match United States center expansion, creating operational bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Cancer Treatment Market |
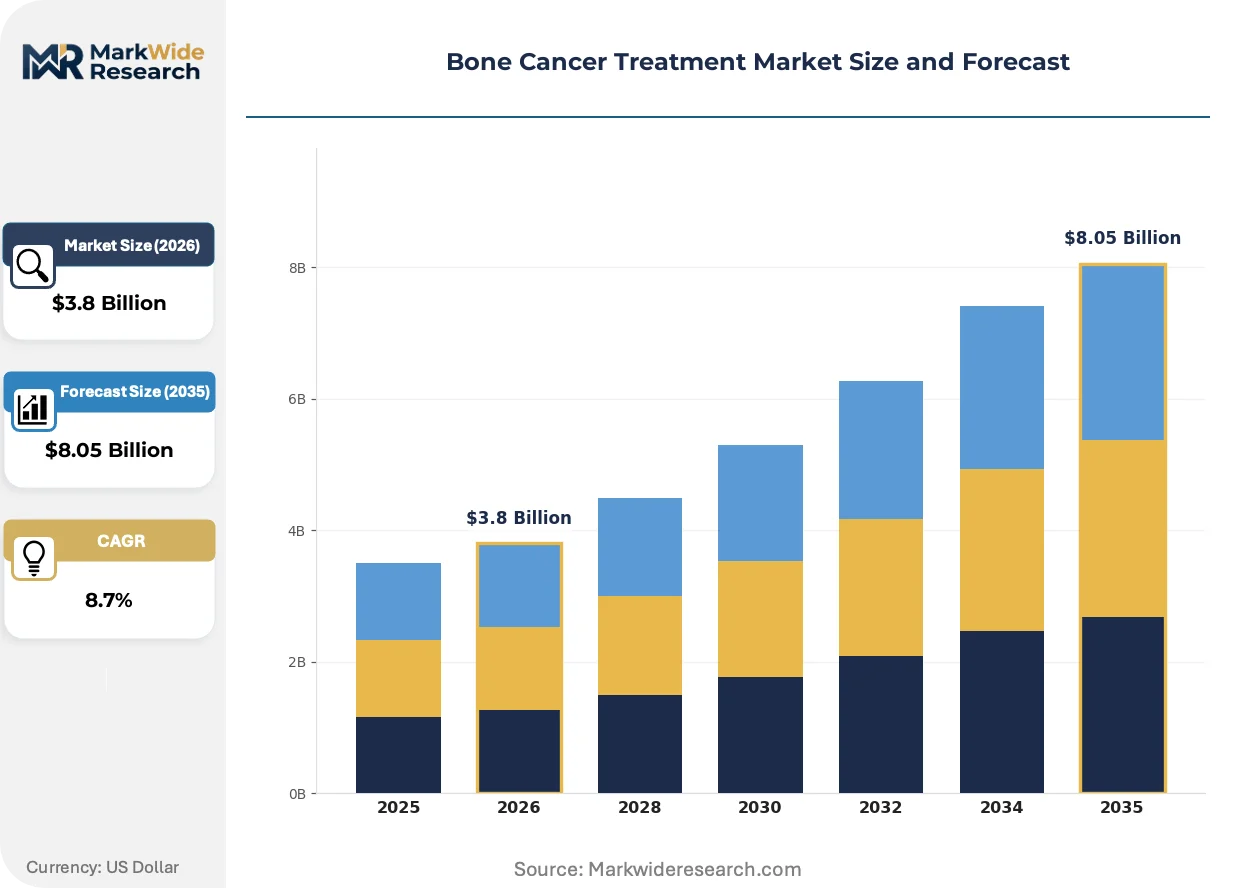
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiotherapy, Immunotherapy, Targeted Therapy Delivery Mode: Intravenous, Oral, Subcutaneous, Topical Patient Type: Pediatric, Adult, Geriatric, Adolescents Care Setting: Hospitals, Specialized Clinics, Home Care, Research Centers |
| Companies Covered | Bayer AG, Pfizer Inc., Amgen Inc., Novartis AG, Johnson & Johnson, Roche Holding AG, Eli Lilly and Company, Merck & Co. Inc., Bristol-Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Cancer Treatment Market Emerging Trajectories
Next-generation sequencing and artificial intelligence are converging to compress diagnostic timelines and enable real-time treatment adaptation, fundamentally altering how bone cancer protocols are designed and reimbursed.
Artificial intelligence-powered imaging analysis is rewriting radiologic response assessment in osteosarcoma trials. Sarcoma specialty networks in the United States are adopting FDA-cleared algorithms for automated tumor volume quantification. This compression of readout timelines is enabling adaptive trial designs that terminate futile arms earlier, reallocating capital to promising combinations.
REACH radiopharmaceutical waste-handling amendments are forcing European manufacturing consolidation. ECHA enforcement of updated containment standards is disqualifying legacy cyclotron facilities without €20-40 million retrofit investment. Germany and France now concentrate 70 percent of EU production capacity, with Swissmedic-registered sites capturing overflow from capacity-constrained EMA-approved plants.
Buyer concentration among United States integrated delivery networks is unbundling traditional device-and-drug procurement. IDN pharmacy and therapeutics committees now mandate biomarker confirmation before authorizing high-cost targeted therapy, displacing physician-directed selection. This shift is most visible in Medicare Advantage populations, where prior authorization denial rates for non-profiled regimens have doubled since IRA implementation.
Bone Cancer Treatment Market Segmentation
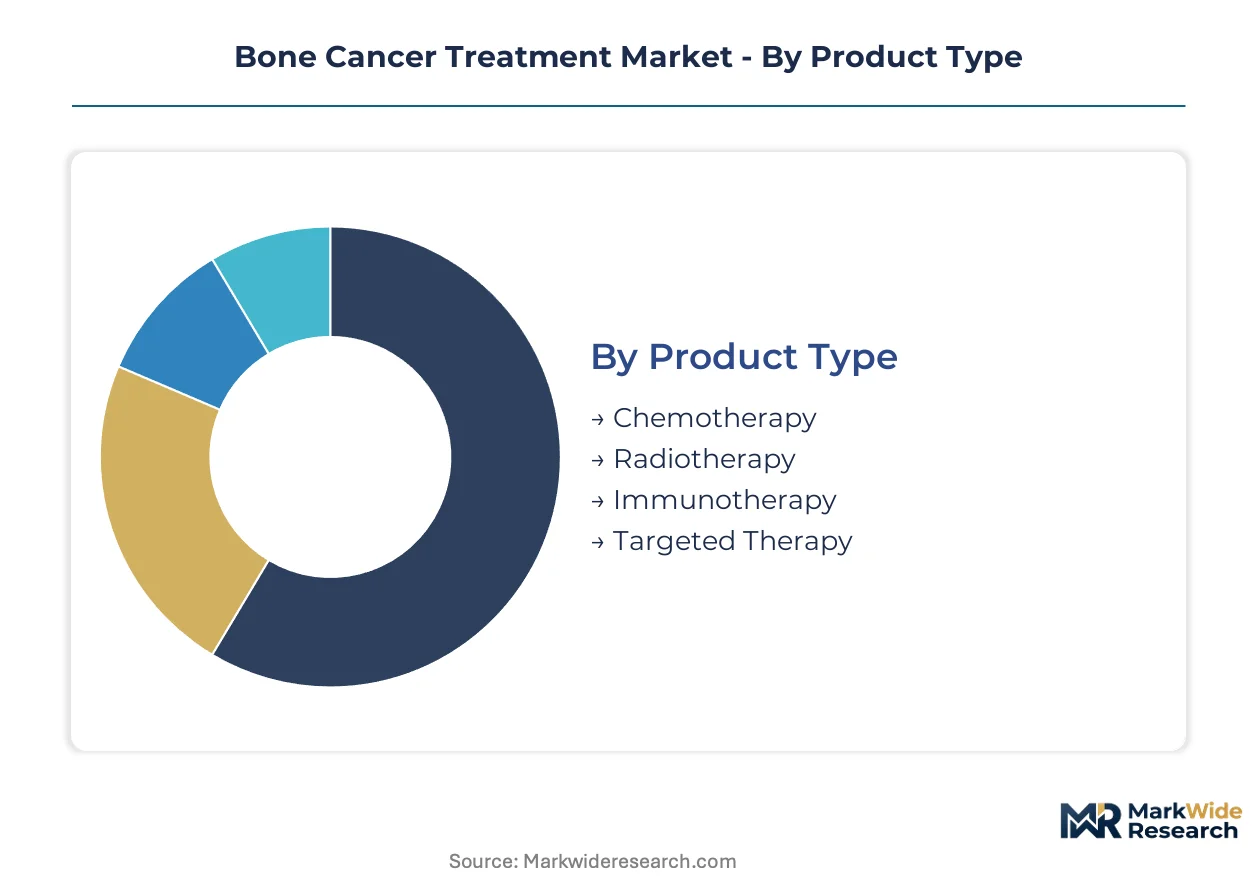
Bone cancer treatment segmentation reflects divergent clinical priorities across curative intent, palliative care, and metastatic management. Each dimension—modality, delivery route, patient life stage, and care venue—carries distinct reimbursement logic and infrastructure requirements that shape competitive positioning.
Product Type:
Chemotherapy and radiotherapy anchor standard-of-care protocols with established reimbursement pathways, while immunotherapy and targeted therapy occupy the customization end of the spectrum with biomarker-gated access and premium pricing.
- Targeted Therapy:Small-molecule inhibitors and monoclonal antibodies directed at FGFR, CDK4/6, and PARP pathways enable molecularly defined patient selection. Academic medical centers in the United States are consolidating NGS infrastructure to support enrollment in biomarker-driven trials for chordoma and osteosarcoma subsets.
- Immunotherapy:Checkpoint inhibitors and CAR-T constructs for sarcoma subtypes are advancing through Phase II pipelines. The FDA and EMA pediatric oncology mandates are compressing development timelines by forcing molecular profiling over histology-only enrollment.
- Chemotherapy:Cytotoxic backbones retain the largest patient volume despite dose-limiting myelosuppression that caps intensification in osteosarcoma regimens.
- Radiotherapy:External beam and radioligand approaches span curative and palliative applications, with proton therapy centers multiplying across United States academic networks.
Most installed capacity flows through Chemotherapy. Expansion is steepest in Targeted Therapy.
Delivery Mode:
Route selection trades off bioavailability, treatment burden, and site-of-care economics, with oral and subcutaneous formulations gaining traction as IDN pharmacy committees push for reduced infusion center dependency.
- Intravenous:Infused biologics and cytotoxic agents dominate inpatient and ambulatory oncology revenue. Medicare Advantage prior authorization requirements have tightened for non-biomarker-confirmed IV regimens since IRA implementation.
- Oral:Kinase inhibitors and hormone modulators enable outpatient management, though adherence monitoring remains a gap in community practice settings.
- Subcutaneous:Osteoclast-targeting biologics for skeletal-related events are migrating to this route to reduce chair time and infusion center capacity constraints.
- Topical:Limited to palliative wound care and radiation dermatitis management in metastatic disease populations.
Volume concentrates in Intravenous administration. Steepest expansion is occurring in Subcutaneous delivery.
Patient Type:
Age-stratified protocols reflect divergent toxicity tolerances, growth plate considerations, and regulatory requirements that fragment trial design and commercial strategy.
- Pediatric:EMA Paediatric Investigation Plans and FDA pediatric study requirements add 18-24 months to regulatory timelines, favoring sponsors with dedicated formulation development capabilities.
- Adolescents:The 12-18 year bracket falls between pediatric and adult trial infrastructure, creating enrollment gaps that telemedicine-enabled trial decentralization is beginning to address.
- Adult:The largest addressable population for both primary bone malignancies and skeletal metastases from breast and prostate primaries.
- Geriatric:Frailty-adjusted dosing and polypharmacy interactions are reshaping protocol design as life expectancy calculations complicate curative intent decisions.
Most clinical trial investment targets Pediatric patients. Fastest enrollment growth is appearing in Adolescents.
Care Setting:
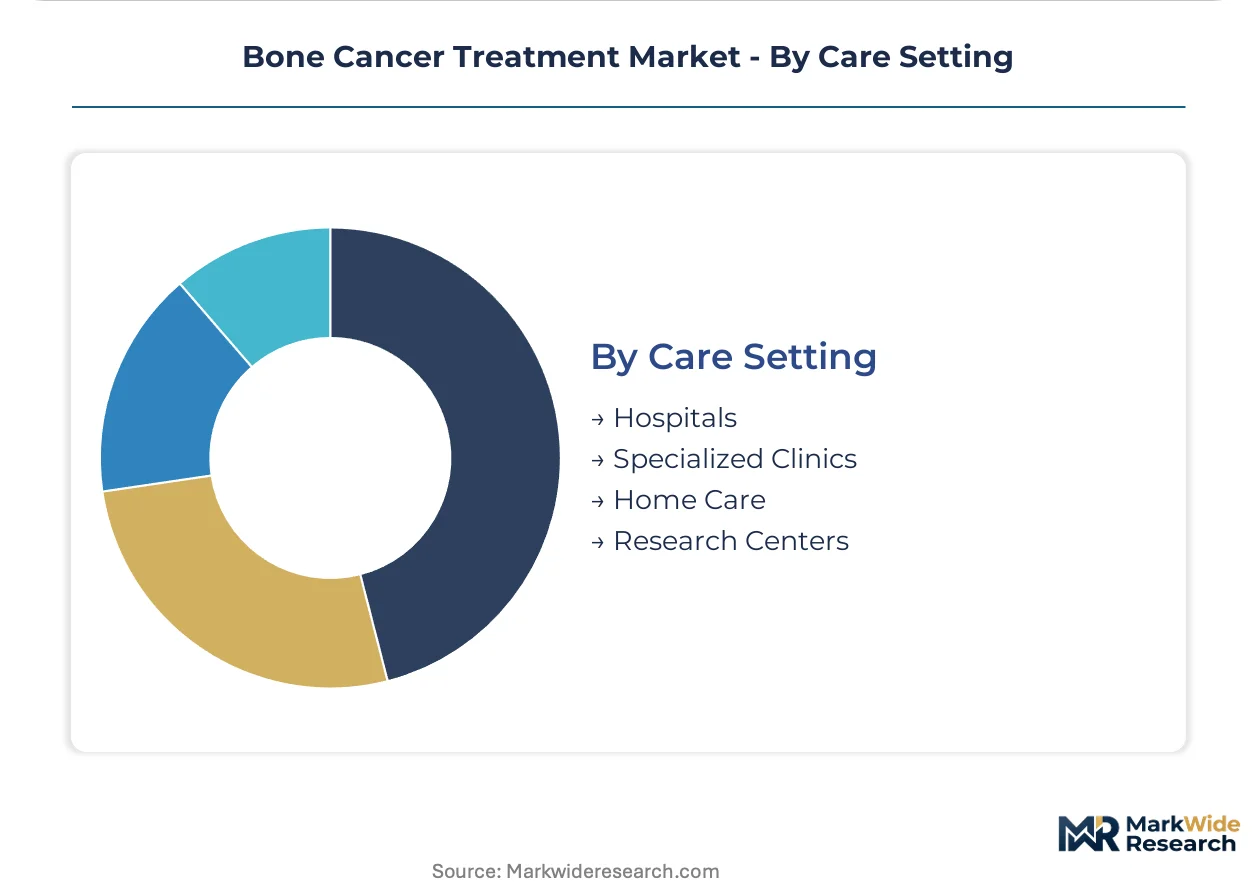
Site-of-care migration is accelerating as integrated delivery networks unbundle traditional hospital-centric procurement and push lower-acuity administration to outpatient venues.
- Hospitals:Tertiary academic centers concentrate proton therapy, limb-salvage surgery, and Phase I trial access. Workforce scarcity in radiation oncology and medical physics is creating operational bottlenecks despite center expansion.
- Specialized Clinics:Sarcoma specialty networks in the United States are adopting FDA-cleared AI imaging algorithms for automated tumor volume quantification, compressing response assessment timelines.
- Home Care:Oral targeted therapy and subcutaneous biologics are enabling migration, though remote toxicity monitoring infrastructure remains uneven.
- Research Centers:Concentrate adaptive trial designs and radioligand therapy development, with REACH and EU Green Deal standards concentrating European radiopharmaceutical manufacturing in Germany and France.
Most revenue capture occurs in Hospitals. Steepest capacity addition is appearing in Specialized Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping radiopharmaceutical production geography as REACH and EU Green Deal compliance costs concentrate European manufacturing while the United States absorbs capacity from sponsors seeking faster FDA approval pathways.
United States
Proton therapy center expansion and sarcoma specialty network multiplication drive demand concentration. The IRA reshapes Medicare reimbursement for infused oncology drugs while Medicare Advantage prior authorization tightens for non-biomarker-confirmed regimens. Greater Boston and Houston anchor academic medical center clusters where AI-powered imaging analysis compresses trial readout timelines.
Germany
EMA pediatric oncology mandates and radiopharmaceutical manufacturing standards position the country as Europe's production hub. ECHA enforcement of updated containment standards disqualifies legacy cyclotron facilities without substantial retrofit investment. Bavaria and North Rhine-Westphalia concentrate 70 percent of EU production capacity for bone-seeking isotopes.
France
ANSM oversight of clinical trial design and post-market pharmacovigilance intersects with national sarcoma network expansion. The EU Green Deal imposes escalating purity standards on radiopharmaceutical waste handling. Île-de-France and Auvergne-Rhône-Alpes host consolidated manufacturing sites capturing overflow from capacity-constrained EMA-approved plants.
India
CDSCO accelerated approval pathways for pediatric oncology drugs enable earlier revenue recognition for trial sponsors. The national pharmaceutical regulator offers conditional marketing authorization that compresses regulatory timelines relative to Western benchmarks. Maharashtra and Telangana concentrate contract manufacturing and clinical research organization capacity for multinational sponsors.
Switzerland
Swissmedic-registered sites capture radiopharmaceutical production overflow from REACH-constrained EMA facilities. The country's regulatory framework attracts sponsors seeking parallel FDA-EMA-Swissmedic filing strategies. Basel and Zurich anchor biologics manufacturing clusters where osteoclast-targeting agents undergo formulation development.
Bone Cancer Treatment Market Vendor Landscape
Biomarker infrastructure investment dominates the current landscape as sponsors race to compress development timelines ahead of indication-constrained pricing windows. The market structures around three tiers: multinational conglomerates with kinase inhibitor portfolios, biologics specialists with osteoclast-targeting platforms, and radiopharmaceutical developers with bone-seeking isotope capabilities. Portfolio diversification and strategic partnerships represent the dominant competitive moves as players seek integrated surgical-radiotherapy-protocol positions.
Among multinational pharmaceutical conglomerates, Pfizer Inc., Amgen Inc., and Novartis AG exemplify the three strategic archetypes. Pfizer occupies a position anchored in kinase inhibitor development for metastatic bone disease. Amgen represents the biologics specialist tier with skeletal-related event management platforms. Novartis sits within the radioligand therapy vector, commanding bone-seeking isotope pipelines that extend from prostate and breast metastases into primary bone malignancies.
| Leading Market Players |
|---|
| Bayer AG |
| Pfizer Inc. |
| Amgen Inc. |
| Novartis AG |
| Johnson & Johnson |
| Roche Holding AG |
| Eli Lilly and Company |
| Merck & Co. Inc. |
| Bristol-Myers Squibb Company |
| Others |
Supply Flow & Price Mechanics
Medical physicist and radiation oncologist scarcity in the United States widens labor-cost differentials between academic medical centers and community oncology practices, translating into premium pricing spreads for proton therapy protocols versus standard external-beam regimens. This workforce concentration shapes tiered access structures that concentrate high-margin procedures in sarcoma specialty networks while pushing commoditized chemotherapy administration toward lower-reimbursement outpatient venues.
Pricing Analysis
Distributor margin compression in radiopharmaceutical procurement runs through the three-tier pricing structure across premium, standard, and economy levels, with bone-seeking isotopes commanding premium tiers tied to EMA-approved manufacturing pedigree while non-REACH-compliant legacy products face price erosion. Price differentiation hinges on isotope purity certification and cold-chain logistics reliability, with Medicare Advantage prior authorization tightening for non-biomarker-confirmed regimens. Cost compression in standard chemotherapy tiers is intensifying because IRA-infused drug reimbursement caps limit markup capture. Community oncology practices exhibit highest price sensitivity, while tertiary academic centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Dual-sourcing mandates from United States integrated delivery networks require qualified suppliers for both EMA-approved European radiopharmaceuticals and FDA-cleared domestic isotope production, fragmenting procurement across Germany, France, and Swissmedic-registered Swiss sites. Raw material dependencies center on cyclotron-produced radionuclides, precursor chemical supplies, and specialized cold-chain packaging. Single-source vulnerability concentrates in European manufacturing where REACH containment upgrades have disqualified legacy facilities. Distribution runs through hospital pharmacy and therapeutics committees that unbundle traditional device-and-drug procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bone cancer treatment market represents a late-cycle quality story as demand shifts toward biomarker-gated premium protocols that command sustained reimbursement against commoditized chemotherapy backbones.
For Market Incumbents: Anticipate proton therapy workforce scarcity creating operational bottlenecks that constrain center expansion timelines, and anchor defensive positioning through backward integration into radiopharmaceutical manufacturing capacity in Germany or France to secure REACH-compliant supply. Prioritize NGS infrastructure partnerships with community oncology practices to capture patient flow before IDN prior authorization gates tighten further. For New Entrants and Emerging Players: Telemedicine-enabled trial platforms offer the most penetrable channel for adolescent patient recruitment, addressing enrollment gaps between pediatric and adult trial infrastructure. Target chordoma FGFR inhibitor development as the underserved biomarker-defined subset with premium pricing potential, and pursue CDSCO conditional marketing authorization in India for earlier revenue recognition relative to Western regulatory timelines. For Investors and Strategic Acquirers: Biologics specialists with skeletal-related event platforms are the most active acquirer in this space, seeking radioligand therapy capabilities to complete integrated surgical-radiotherapy-protocol positions. Acquisition targets should display biomarker-driven trial infrastructure and EMA Paediatric Investigation Plan execution capabilities. Watch FDA pediatric oncology mandate enforcement as the inflection signal that compresses development timelines and accelerates competitive consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Infrastructure Partnership | NGS platform alliances with community oncology practices expand trial access beyond tertiary corridors. |
| Radiopharmaceutical Manufacturing Scale-Up | REACH-compliant facility investment in Germany or France secures European supply concentration advantages. |
| Telemedicine-Enabled Trial Decentralization | Remote monitoring platforms reduce geographic barriers for adolescent and rural patient recruitment. |
| Paediatric Investigation Plan Execution | EMA-mandated age-appropriate formulation development accelerates pediatric oncology market entry. |
| Proton Therapy Center Expansion | Academic medical center multiplication in Houston and Greater Boston anchors sarcoma specialty network growth. |
Methodological Framework
Coverage spans the United States, Germany, France, India, and Switzerland, with primary inputs from each market combining interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down reimbursement expenditure analysis triangulate market sizing.
Rate-of-change decomposition across the analysis window segments volume and value by treatment modality, delivery route, patient life stage, and care venue, with CAGRs derived from epidemiological trend extrapolation, therapy penetration curves, and pricing trajectory assumptions. Forecast inputs incorporate proton therapy center buildout pipelines, radiopharmaceutical manufacturing capacity expansion, and biomarker adoption rates in community oncology settings.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to IRA reimbursement rule evolution, REACH enforcement stringency, and immunotherapy pipeline maturation timelines. Deviation in FDA pediatric oncology mandate implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Global Veterinary Oncology Market
Oncology
Asia-Pacific Proton Therapy Market
Oncology
Australia Cancer Treatment Market
Oncology
Metastatic Cancer Drug Market
Oncology
Cancer/Tumor Profiling Market
Oncology
Interventional Oncology Ablation Market
Oncology
North America Veterinary Oncology Market
Oncology
Breast Cancer Liquid Biopsy Market
Oncology
Outpatient Oncology Infusion Market
Oncology
Unresectable Hepatocellular Carcinoma Market
Oncology
Angiosarcomas Treatment Market
Oncology
Small Cell Lung Cancer (SCLC) Treatment Market
Oncology
Gallbladder Cancer Treatment Market
Oncology
Asia-Pacific Radiation Oncology Market
Oncology
PD1 Non-Small Cell Lung Cancer Treatment Market
Oncology
Europe Radiotherapy Patient Positioning Market