
 Bone Metastasis Market | 2026-2036
Bone Metastasis Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Metastasis Market Analysis
Specialized radiopharmaceutical manufacturing capacity in North America is realigning around alpha-emitting isotopes for bone-seeking indications. Novartis leverages its established radioligand therapy infrastructure to sustain leadership in targeted skeletal treatments. Bayer anchors European supply chains through its differentiated alpha-particle platform for metastatic castration-resistant prostate cancer with bone involvement.
Bone metastasis denotes the dissemination of malignant cells from primary tumor sites to osseous tissue, where cancer cells disrupt normal bone remodeling through osteoclast-mediated resorption and osteoblastic proliferation, producing lytic or blastic lesions detectable via bone scintigraphy, PET-CT, or MRI. The condition serves as a major source of morbidity in advanced cancer, necessitating systemic therapy, localized radiation, surgical stabilization, and supportive care to manage pain, prevent pathologic fracture, and preserve functional status. Targeted therapy segments are attracting disproportionate R&D investment as antibody-drug conjugates and radiopharmaceuticals demonstrate superior overall survival in pivotal trials. Intravenous delivery modes retain structural dominance due to the complexity of biologic and radiolabeled agents, though oral bisphosphonate formulations maintain volume leadership in the maintenance setting across hospital and oncology clinic channels.
The FDA breakthrough therapy and orphan drug programs shape clinical development priorities and expedite review timelines for bone-targeted agents, while EMA's centralized marketing authorization process governs commercial access across EU member states. WHO essential medicines criteria for cancer therapeutics indirectly influence national reimbursement decisions and procurement patterns in lower-income markets. Stakeholders must monitor evolving radiopharmaceutical reimbursement methodologies and site-of-care certification requirements as these determine prescriber adoption and manufacturer channel strategy.
Market Dynamics
Alpha-emitting radiopharmaceuticals are compressing clinical trial timelines and redrawing competitive boundaries in skeletal metastasis treatment, as manufacturers race to secure manufacturing capacity and site-of-care certifications ahead of reimbursement determinations.
Growth Catalysts
- FDA Breakthrough Therapy Pathway:The streamlined designation accelerates enrollment timelines for novel bone-seeking agents and compresses commercial access windows by 12-18 months compared to standard review.
- Medicare Reimbursement Reform:Updated payment methodologies for radiopharmaceuticals in the United States are shifting prescriber behavior toward hospital outpatient departments and freestanding oncology clinics.
- Targeted Alpha Therapy:The transition from beta-emitting to alpha-emitting isotopes delivers higher linear energy transfer to bone lesions with reduced marrow toxicity, expanding treatable patient populations.
Market Restraints
- Isotope Supply Concentration:Production of actinium-225 and radium-223 concentrates at fewer than five government-backed reactors worldwide, creating single-source vulnerability for alpha-therapy developers.
- Cold Chain Complexity:Radiopharmaceutical half-lives measured in hours necessitate just-in-time manufacturing within 300 kilometers of infusion sites, limiting geographic expansion.
- Specialized Workforce Scarcity:Nuclear pharmacists and radiation safety officers require board certification cycles exceeding 24 months, constraining site activation velocity.
Strategic Opportunities
- Community Oncology Penetration:Untapped demand exists in United States suburban markets where 60% of metastatic prostate cancer patients receive care outside academic medical centers.
- Combination Regimen Development:Pairing radiopharmaceuticals with immune checkpoint inhibitors in melanoma and lung cancer bone metastases represents a white-space indication with no approved agents.
- EMA Centralized Authorization:The streamlined marketing authorization process enables simultaneous commercial access across Germany, France, Italy, and Spain through a single regulatory filing.
Industry Challenges
- Good Manufacturing Practice Certification:Radiopharmaceutical facilities require both FDA drug GMP and nuclear regulatory commission licensing, with facility buildouts extending 36-48 months.
- Reimbursement Uncertainty:Hospital outpatient prospective payment system rates for novel radiopharmaceuticals remain unsettled, forcing manufacturers to absorb 90-120 day payment delays during coverage determinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Metastasis Market |
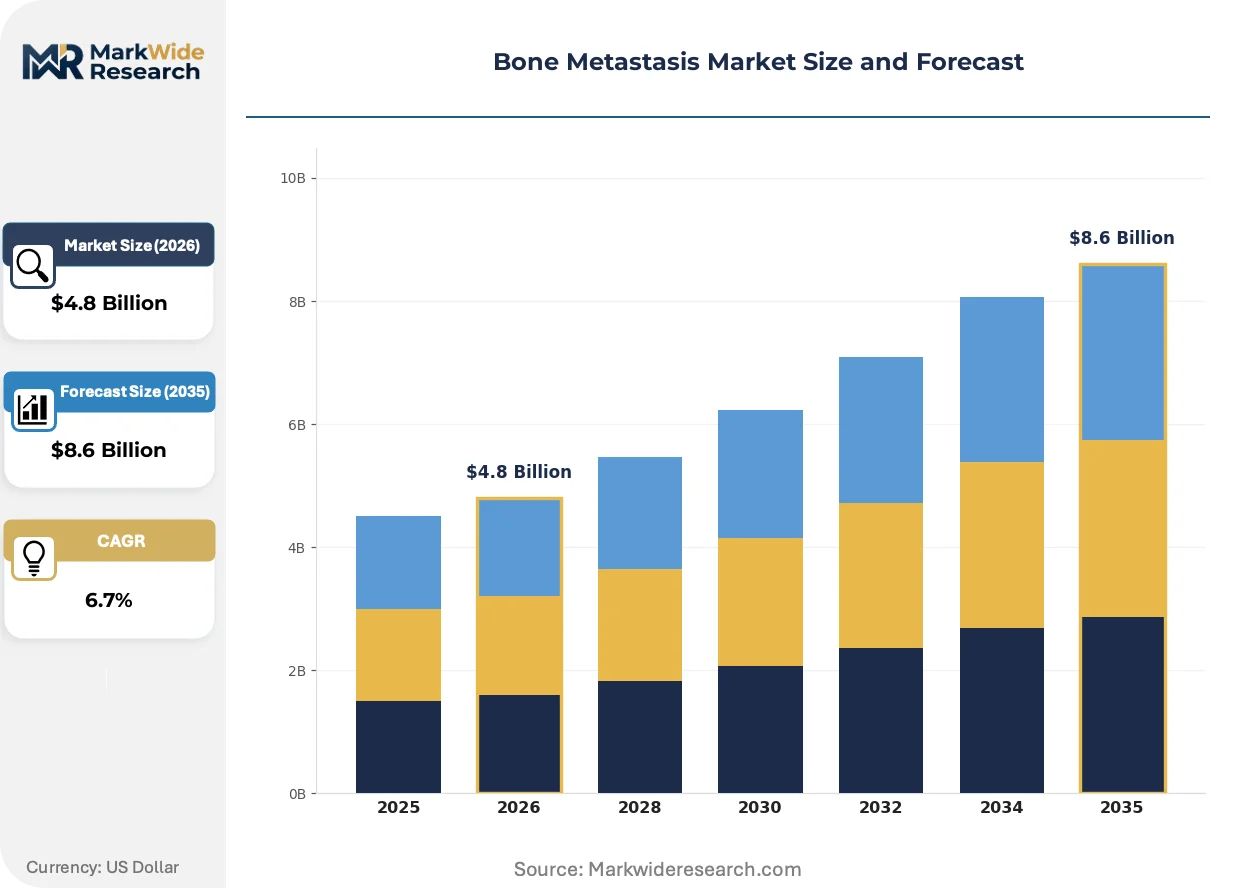
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiation Therapy, Bisphosphonates, Chemotherapy, Targeted Therapy End User: Oncology Clinics, Hospitals, Research Laboratories, Home Care Settings Application: Pain Management, Diagnostic Imaging, Patient Monitoring, Surgical Intervention Delivery Mode: Intravenous, Oral, Subcutaneous, Injectable |
| Companies Covered | Novartis AG, Bayer AG, Amgen Inc., Pfizer Inc., Merck & Co., Inc., Johnson & Johnson, Roche Holding AG, Eli Lilly and Company, AstraZeneca PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Metastasis Market Emerging Trajectories
Automation and real-time logistics coordination are displacing manual compounding and static inventory models across the radiopharmaceutical value chain, while regulatory frameworks race to accommodate shorter product lifecycles.
Artificial intelligence-enabled dosimetry platforms are automating personalized radiation dose calculations based on patient-specific pharmacokinetic modeling. Oncology clinics in the United States and Germany are piloting these systems to reduce inter-operator variability in treatment planning. The technology is automating what previously required nuclear medicine physicians to perform manual calculations, compressing pretreatment preparation from hours to minutes.
REACH authorization requirements for novel chelating agents used in radiopharmaceutical formulation are tightening purity specifications for European manufacturers. The industrial consequence is a 15-20% increase in raw material qualification costs and extended supplier audit timelines. Small-molecule developers targeting the European market are responding by pre-qualifying dual-source supply chains before clinical trial initiation.
Integrated delivery networks are consolidating radiopharmaceutical procurement under centralized pharmacy committees rather than individual physician preference. Hospital systems in the United States are displacing fragmented purchasing with enterprise-wide contracts that bundle bone-seeking agents with imaging isotopes and supportive care medications. This concentration is most visible in the southeastern United States, where three health systems control 40% of metastatic prostate cancer infusion volume.
Bone Metastasis Market Segmentation
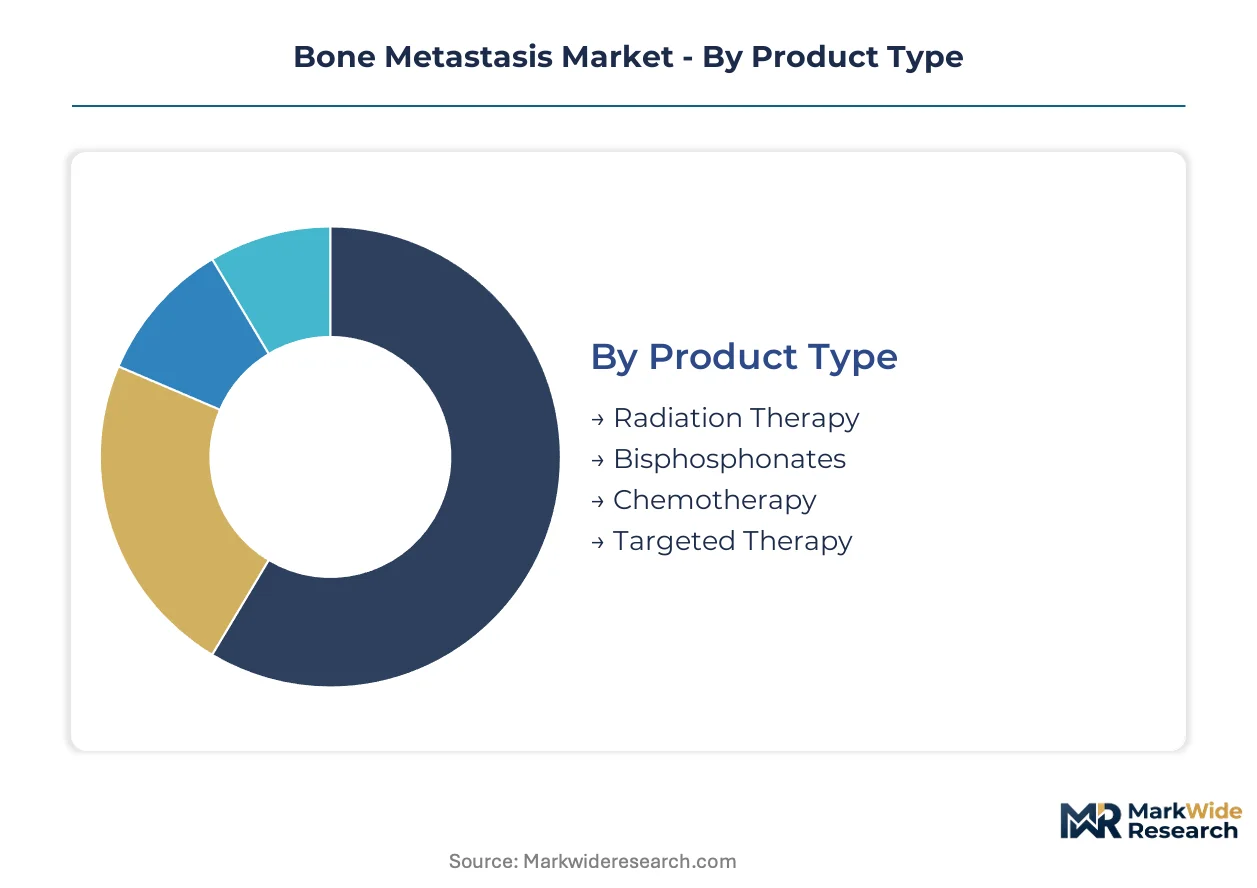
Segmentation in bone metastasis treatment reveals divergent investment priorities across therapeutic modalities and care settings. Product type splits reflect the tension between established bisphosphonate maintenance and emerging radiopharmaceutical innovation. End-user concentration exposes infrastructure gaps between academic centers and community oncology.
Product Type:
Volume leadership belongs to oral bisphosphonates, while premium value concentrates in alpha-emitting radiopharmaceuticals with superior survival data.
- Targeted Therapy:Antibody-drug conjugates and radioligand therapies bind bone-seeking ligands to cytotoxic payloads or alpha-emitting isotopes. Demand clusters in United States oncology clinics where Medicare reimbursement reforms favor hospital outpatient administration of high-cost agents.
- Radiation Therapy:External beam and systemic radiopharmaceuticals deliver ionizing radiation to skeletal lesions. United States freestanding oncology clinics are expanding capacity for radium-223 and actinium-225 based therapies as site-of-care certifications proliferate.
- Bisphosphonates:Established oral and intravenous formulations inhibit osteoclast-mediated bone resorption.
- Chemotherapy:Cytotoxic agents with bone marrow suppression profiles used in combination regimens.
Mature deployment sits with Bisphosphonates. Newer deployment is concentrated in Targeted Therapy.
End User:
Academic medical centers anchor complex radiopharmaceutical administration, while community oncology clinics represent the largest untreated addressable population.
- Oncology Clinics:Freestanding infusion centers and hospital outpatient departments administer systemic therapies and radiopharmaceuticals. United States suburban markets drive expansion as 60% of metastatic prostate cancer patients receive care outside academic settings.
- Hospitals:Inpatient and outpatient facilities manage pathologic fractures, spinal cord compression, and surgical stabilization. Germany, France, and United Kingdom hospital systems are consolidating radiopharmaceutical procurement under centralized pharmacy committees.
- Research Laboratories:Clinical trial sites and translational research facilities.
- Home Care Settings:Oral bisphosphonate administration and supportive care delivery.
Revenue concentration favors Oncology Clinics. Patient volume leadership remains with Hospitals.
Application:
Chronic pain management commands recurring utilization, while diagnostic imaging enables patient selection for premium therapies.
- Pain Management:Systemic therapies, external beam radiation, and supportive care address cancer-related bone pain. United States Medicare reimbursement reforms are shifting site-of-care decisions toward hospital outpatient departments for radiopharmaceutical-based palliation.
- Diagnostic Imaging:Bone scintigraphy, PET-CT, and MRI detect osteoblastic and osteolytic lesions. German oncology clinics are piloting artificial intelligence-enabled dosimetry platforms to automate personalized radiation dose calculations.
- Patient Monitoring:Biomarker tracking and imaging surveillance for disease progression.
- Surgical Intervention:Stabilization of impending or completed pathologic fractures.
Established utilization centers on Pain Management. Emerging utilization is expanding fastest in Diagnostic Imaging.
Delivery Mode:
Intravenous administration captures biologic and radiolabeled agent complexity, while oral formulations sustain maintenance therapy scale.
- Intravenous:Bisphosphonates, radiopharmaceuticals, and antibody-drug conjugates require infusion infrastructure. Cold chain constraints limit geographic expansion as radiopharmaceutical half-lives measured in hours necessitate just-in-time manufacturing within 300 kilometers of infusion sites.
- Oral:Bisphosphonate tablets and supportive care medications enable outpatient maintenance. United States integrated delivery networks are bundling oral bone health agents with imaging isotopes under enterprise-wide pharmacy contracts.
- Subcutaneous:Monoclonal antibodies and supportive therapies.
- Injectable:Depot formulations and localized delivery systems.
Structural dominance rests with Intravenous. Volume accessibility belongs to Oral.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Actinium-225 production concentrates at Oak Ridge National Laboratory in Tennessee, anchoring United States supply chains for alpha-emitting radiopharmaceuticals while European and Asian markets develop alternative sourcing strategies.
United States
Medicare reimbursement reforms for radiopharmaceuticals are shifting site-of-care decisions toward hospital outpatient departments and freestanding oncology clinics. The FDA breakthrough therapy designation pathway compresses commercial access timelines by 12-18 months for novel bone-seeking agents. The southeastern United States shows concentrated procurement consolidation, with three health systems controlling 40% of metastatic prostate cancer infusion volume.
Germany
Oncology clinics across Bavaria and North Rhine-Westphalia are expanding adoption of targeted radionuclide therapies for skeletal metastases. EMA centralized marketing authorization enables simultaneous commercial access across EU member states through single regulatory filings. The Munich-Düsseldorf corridor anchors radiopharmaceutical manufacturing infrastructure serving central European distribution networks.
France
ANSM oversight of radiopharmaceutical manufacturing aligns with EMA frameworks while maintaining national specificity for nuclear pharmacy licensing. Paris and Lyon clusters concentrate clinical trial enrollment for alpha-emitting therapies in metastatic castration-resistant prostate cancer. Hospital systems in Île-de-France are consolidating procurement under centralized pharmacy committees.
United Kingdom
NHS England specialized commissioning frameworks determine access to high-cost radiopharmaceuticals through technology appraisal processes. The Greater London and Manchester oncology networks pilot artificial intelligence-enabled dosimetry platforms for personalized radiation dose calculations. MHRA post-Brexit regulatory autonomy maintains alignment with EMA standards while enabling accelerated access pathways.
Japan
PMDA sakigake designation system accelerates review timelines for innovative radiopharmaceuticals addressing unmet needs in skeletal metastasis. The Kanto region surrounding Tokyo concentrates nuclear medicine infrastructure and radiopharmaceutical manufacturing capacity. METI industrial policy supports domestic isotope production to reduce import dependency for medical radioisotopes.
Bone Metastasis Market Vendor Landscape
Global majors compete with regional champions across manufacturing infrastructure and site-of-care certification capabilities in bone metastasis treatment. The market structure concentrates around vertically integrated radiopharmaceutical manufacturers with captive isotope supply and specialized oncology service networks. Three archetypes dominate: diversified pharmaceutical conglomerates with radioligand therapy platforms, mid-cap radiopharmaceutical specialists with regional manufacturing footprints, and emerging biotech developers targeting alpha-emitting modalities. Competitive dynamics center on manufacturing capacity expansion and strategic partnerships securing isotope supply chains.
Among Swiss-based pharmaceutical conglomerates, Novartis AG occupies a position exemplifying integrated radioligand therapy infrastructure. German chemical-pharmaceutical conglomerate Bayer AG represents the European anchor for alpha-particle platform development. United States biotechnology leader Amgen Inc. sits within the biologics-focused tier addressing skeletal-related events through monoclonal antibody pathways.
| Leading Market Players |
|---|
| Novartis AG |
| Bayer AG |
| Amgen Inc. |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Johnson & Johnson |
| Roche Holding AG |
| Eli Lilly and Company |
| AstraZeneca PLC |
| Others |
Supply Flow & Price Mechanics
Actinium-225 spot pricing volatility cascades through alpha-emitting radiopharmaceutical tiers, compressing margins for developers without captive isotope supply while concentrating pricing power among manufacturers with Oak Ridge National Laboratory offtake agreements and integrated cold-chain logistics.
Pricing Analysis
Service bundling separates site-of-care certification packages from standalone drug pricing, with manufacturers absorbing 90-120 day reimbursement delays during Medicare coverage determinations. Three-tier pricing structure across premium, standard, and economy levels reflects alpha-emitter purity grades, GMP certification tiers, and bundled radiation safety officer training. Cost compression in the standard tier is intensifying because hospital outpatient prospective payment system rates remain unsettled for novel agents. Community oncology clinics exhibit highest price sensitivity due to capital constraints for nuclear pharmacy infrastructure, while academic medical centers prioritize clinical outcomes over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from United States integrated delivery networks require qualification of both Oak Ridge National Laboratory and alternative European reactor capacity for actinium-225 procurement. Manufacturing concentrates in the United States, Germany, and Belgium, with raw material dependencies spanning high-purity chelating agents, medical-grade isotope carriers, and specialized cold-chain packaging. Single-source vulnerability concentrates at fewer than five government-backed reactors worldwide. Distribution runs through radiopharmaceutical compounding facilities positioned within 300 kilometers of infusion sites, with just-in-time manufacturing displacing static inventory models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bone metastasis treatment is consolidating around manufacturers with captive isotope supply and radioligand therapy infrastructure, as reimbursement complexity and cold-chain capital requirements force sub-scale developers toward partnership or exit.
For Market Incumbents: Deploy backward integration into actinium-225 production capacity to secure supply autonomy against Oak Ridge allocation constraints. Expand site-of-care certification partnerships in United States suburban oncology clinics where 60% of metastatic prostate cancer patients receive care outside academic settings. Deepen EMA centralized filing capabilities to compress multi-country commercial access timelines. For New Entrants and Emerging Players: Enter via combination regimen development pairing radiopharmaceuticals with immune checkpoint inhibitors in melanoma and lung cancer bone metastases, a white-space indication with no approved agents. Target United States southeastern suburban markets where three health systems control 40% of infusion volume and procurement consolidation creates enterprise contract entry points. Pursue licensing arrangements with established manufacturers for isotope supply rather than greenfield production investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap radiopharmaceutical specialists with regional manufacturing footprints and existing site-of-care certifications in Germany or the United States. Long-term viability hinges on securing alternative actinium-225 sourcing beyond Oak Ridge as European reactor capacity matures. Watch for Medicare reimbursement determination finalization as the inflection signal for prescriber adoption velocity and manufacturer margin stabilization.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive actinium-225 production capacity insulates against Oak Ridge allocation limits and secures supply continuity for alpha-therapy pipelines. |
| Site-of-Care Certification Expansion | FDA and nuclear regulatory commission licensing for community oncology clinics extends addressable patient population beyond academic medical centers. |
| EMA Centralized Authorization | Single regulatory filing enables simultaneous commercial access across Germany, France, Italy, and Spain, compressing multi-country launch timelines. |
| Combination Regimen Development | Pairing radiopharmaceuticals with immune checkpoint inhibitors opens white-space indications in melanoma and lung cancer bone metastases. |
| Reimbursement Strategy | Hospital outpatient prospective payment system rate negotiation determines prescriber adoption and site-of-care migration for novel bone-seeking agents. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving nuclear medicine physicians, hospital pharmacy directors, radiopharmaceutical manufacturing executives, and Medicare reimbursement specialists. FDA breakthrough therapy designation databases, EMA centralized marketing authorization records, and hospital procurement databases supplied quantitative validation. Bottom-up patient-flow modeling and top-down epidemiological projections were triangulated against manufacturer-reported capacity expansion timelines.
Segmentation granularity extended to treatment modality, delivery mode, end-user facility type, and regional regulatory cluster across the analysis window. CAGRs were derived from fitted growth curves applied to patient population projections, therapy penetration assumptions, and pricing trajectory scenarios. Forecast inputs incorporated actinium-225 production capacity expansion schedules, Medicare reimbursement reform implementation pace, and site-of-care certification velocity in United States suburban markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under isotope supply disruption or reimbursement determination delays. Deviation in actinium-225 production allocation from Oak Ridge National Laboratory would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Global Nasopharyngeal Cancer Market
Oncology
Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Ustekinumab Market
Oncology
Small Cell Lung Cancer (SCLC) Therapeutics Market
Oncology
Global Oncology Clinical Trials Market
Oncology
Australia Cancer Treatment Market
Oncology
Glioblastoma Market
Oncology
Metastases Spinal Tumor Market
Oncology
Radiation Therapy Software Market
Oncology
North America Proton Therapy Market
Oncology
Unresectable Hepatocellular Carcinoma Market
Oncology
Europe Radiotherapy Market
Oncology
Colorectal Cancer Market
Oncology
Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Intratumoral Cancer Therapies Market
Oncology
Breast Cancer Liquid Biopsy Market